
 Astragalus Propinquus Market | 2026-2036
Astragalus Propinquus Market Size, Share, and Industry Trends Forecast 2026-2036
Astragalus Propinquus Market Analytics
Skilled botanical extract chemists is bifurcating competitive capability across the Astragalus Propinquus supply base. Novoherb Technologies leverages in-house phytochemical laboratories to sustain premium positioning in polysaccharide-standardized extracts. Kan Phytochemicals Private Limited anchors South Asian supply through backward integration into contract farming networks across Madhya Pradesh and Rajasthan. Oregon's Wild Harvest differentiates via certified organic wildcrafting protocols that command shelf-space premiums in North American natural retail channels.
Astragalus propinquus designates a perennial leguminous species whose dried root yields cycloastragenol, calycosin, and astragaloside IV—bioactive markers standardized via HPLC quantification for therapeutic-grade applications. The root serves primary commercial purpose as an adaptogenic raw material in immune-modulation and anti-fatigue formulations across pharmaceutical and nutraceutical production lines. Extracts dominate value capture due to concentration-dependent bioactive potency and dosage-form flexibility, while capsules lead volume throughput in direct-to-consumer channels where unit-dose convenience shapes repeat purchase behavior. Nutraceuticals represent the fastest-expanding end-use industry as functional-positioned beverages and condition-specific supplements absorb premium botanical inputs.
FDA Dietary Supplement Current Good Manufacturing Practices enforce identity-testing burdens that filter smaller traders from US market access. EFSA Novel Food cataloguing requirements constrain unapproved astragalus-derived ingredients within European Union member states. China's NMPA traditional Chinese medicine substance standards provide regulatory clarity that accelerates domestic extraction capacity expansion. Stakeholders must monitor evolving pharmacovigilance data on astragaloside IV bioavailability claims as regulatory scrutiny intensifies across major import jurisdictions.
Market Dynamics
Pharmaceutical formulators in Germany and the United States are expanding procurement of standardized root extracts, reshaping competitive capability requirements across the Astragalus Propinquus supply base. This demand compression is forcing extraction houses to invest in in-house phytochemical laboratories or risk displacement from premium supply tiers.
Growth Catalysts
- NMPA herbal medicine registration reforms:China's streamlined approval pathways for traditional botanical ingredients accelerate domestic extraction capacity expansion and reduce time-to-market for TCM-integrated formulations.
- Functional beverage absorption:Condition-specific supplements and adaptogenic drinks in East Asian markets absorb premium botanical inputs, creating sustained volume pull for polysaccharide-standardized extracts.
- HPLC quantification adoption:Therapeutic-grade applications now require bioactive marker standardization, filtering smaller traders and concentrating value capture among certified extraction facilities.
Market Restraints
- Wildcrafting supply volatility:Certified organic wildcrafting protocols in Oregon and comparable jurisdictions face harvest seasonality and climate-driven yield compression, constraining premium raw material flows.
- EFSA Novel Food cataloguing:Unapproved astragalus-derived ingredients face market access barriers across European Union member states, fragmenting addressable demand for European formulators.
- Substitution by synthetic adaptogens:Laboratory-synthesized immune-modulation compounds compete on cost and batch consistency, pressuring botanical extract pricing in pharmaceutical procurement.
Strategic Opportunities
- Contract farming network expansion:Backward integration into cultivation across Madhya Pradesh and Rajasthan reduces wild-harvest dependency while securing traceable supply for South Asian extraction houses.
- FDA cGMP compliance specialization:Identity-testing infrastructure investments filter non-compliant traders from US market access, creating defensive moats for qualified suppliers.
- Direct-to-consumer capsule formats:Unit-dose convenience shapes repeat purchase behavior in North American natural retail channels, opening margin expansion through branded finished goods.
Industry Challenges
- Phytochemical laboratory talent scarcity:Skilled botanical extract chemists command premium compensation, bifurcating competitive capability between capitalized laboratories and commodity traders.
- Pharmacovigilance data monitoring:Evolving bioavailability claims for astragaloside IV intensify regulatory scrutiny across major import jurisdictions, requiring dedicated compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Astragalus Propinquus Market |
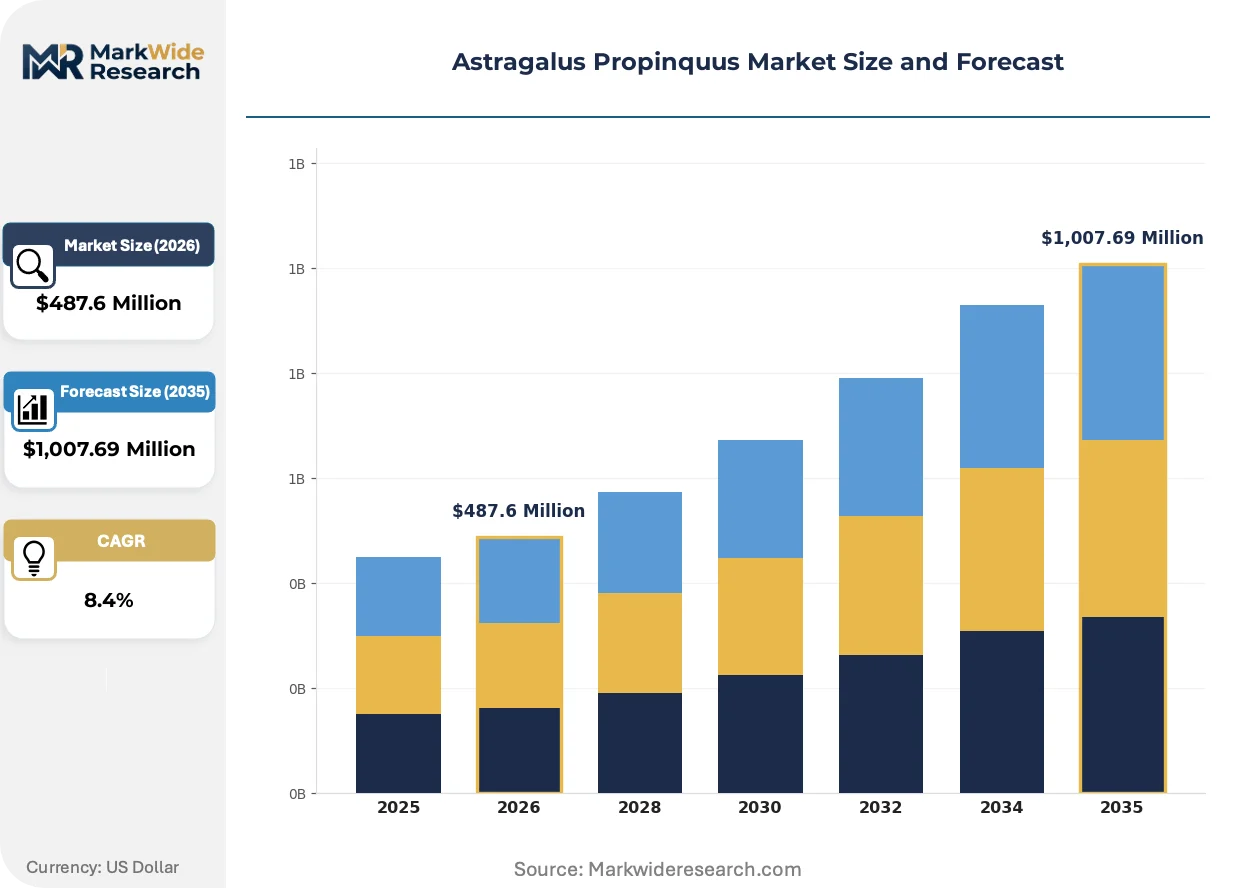
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracts, Capsules, Powders, Teas End Use Industry: Pharmaceuticals, Nutraceuticals, Cosmetics, Food & Beverage Form: Solid, Liquid, Semi-solid, Gels Packaging Type: Bottles, Jars, Pouches, Blister Packs |
| Companies Covered | Novoherb Technologies, Nutragreenlife Biotechnology Co., Ltd, Starwest Botanicals Inc., Indigo Herbs Ltd, Kan Phytochemicals Private Limited, Oregon's Wild Harvest, HealthAid Limited, PhytoHealth Corporation, Naturex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Astragalus Propinquus Market Evolving Landscape
Extraction technology and regulatory classification systems are actively compressing traditional supply hierarchies in the Astragalus Propinquus market. These forces are reconfiguring which capabilities command premium positioning versus commodity margin erosion.
Supercritical CO2 extraction is supplanting conventional solvent-based methods in high-value polysaccharide recovery. Pharmaceutical formulators in Germany now specify supercritical-derived extracts for immune-support applications, compressing demand for ethanol-extracted alternatives and forcing mid-tier suppliers to retool or exit premium tiers.
China's NMPA traditional Chinese medicine substance standards provide regulatory clarity that accelerates domestic capacity expansion. This framework compresses approval timelines for standardized root extracts, concentrating investment in Shaanxi and Gansu processing clusters while foreign competitors face extended equivalence negotiations.
Condition-specific supplement buyers now demand certificate-of-analysis transparency prior to contract execution. North American natural retail channels are displacing opaque bulk sourcing with verified chain-of-custody documentation, privileging suppliers with integrated cultivation-to-extraction operations over trader intermediaries.
Astragalus Propinquus Market Segmentation
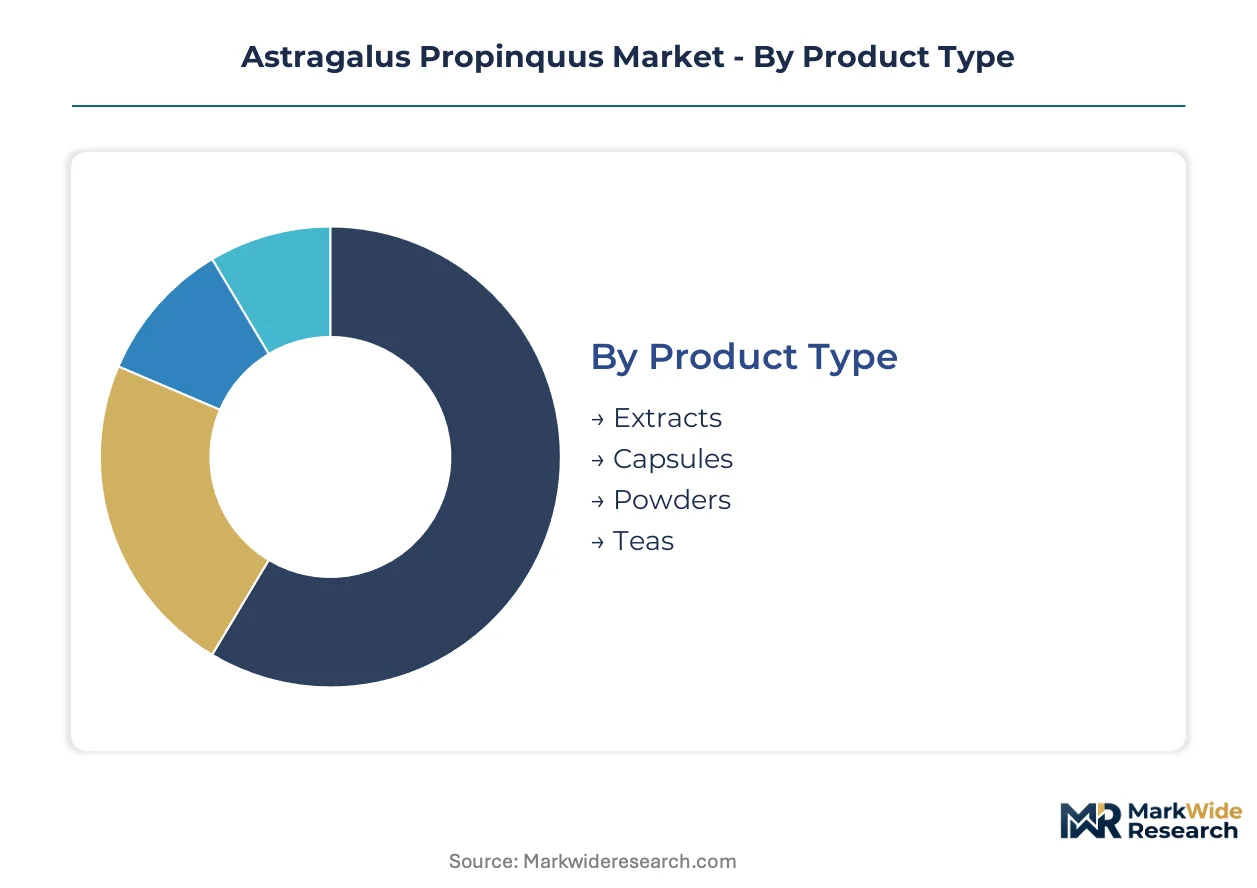
Segmentation in the Astragalus Propinquus market reveals how bioactive potency requirements and dosage-form preferences split procurement patterns across pharmaceutical and consumer channels. Each dimension carries distinct regulatory burdens and margin structures that determine supplier viability.
Product Type:
Extracts face the most acute substitution pressure from synthetic adaptogens, forcing suppliers to differentiate through marker-standardized potency that laboratory compounds cannot replicate.
- Extracts:Concentrated preparations standardized via HPLC quantification for astragaloside IV and cycloastragenol content. Pharmaceutical formulators in Germany specify these for immune-modulation applications, though supercritical CO2 extraction investments now filter mid-tier suppliers from premium procurement.
- Capsules:Unit-dose gelatin or vegetable-shell delivery systems dominating North American natural retail channels. Repeat purchase behavior in direct-to-consumer markets rewards brands with verified chain-of-custody documentation over opaque bulk sourcing.
- Powders:Bulk raw material for functional beverage manufacturing and compounding pharmacies.
- Teas:Traditional infusion formats retaining adherence in East Asian TCM-integrated wellness protocols.
Extracts retain volume leadership; Capsules hold the steepest expansion curve.
End Use Industry:
Margin stratification runs deepest in this dimension, with pharmaceutical-grade specifications commanding multiple price multiples over commodity nutraceutical inputs.
- Pharmaceuticals:Therapeutic-grade applications requiring GMP-certified extraction and pharmacovigilance data infrastructure. FDA cGMP identity-testing burdens filter smaller traders from US market access, concentrating supply among capitalized laboratories.
- Nutraceuticals:Functional-positioned supplements and adaptogenic formulations absorbing premium botanical inputs. Condition-specific supplement buyers now demand certificate-of-analysis transparency prior to contract execution.
- Cosmetics:Topical applications leveraging astragalus polysaccharides for barrier-function positioning.
- Food & Beverage:Adaptogenic beverage formulations in East Asian markets driving volume absorption of polysaccharide-standardized inputs.
Pharmaceuticals capture the highest per-kilogram value; Nutraceuticals are expanding most quickly.
Form:
Supply chain configuration determines which forms achieve viable scale, with liquid processing requiring specialized stabilization infrastructure that constrains producer entry.
- Solid:Dried root slices, granules, and compressed tablets dominating TCM pharmacy dispensing. China's NMPA traditional Chinese medicine substance standards provide regulatory clarity accelerating domestic capacity expansion for these formats.
- Liquid:Tinctures and fluid extracts requiring ethanol stabilization protocols. EFSA Novel Food cataloguing requirements constrain unapproved astragalus-derived ingredients across European Union member states, fragmenting addressable demand for liquid formulators.
- Semi-solid:Cream bases and ointment vehicles for topical delivery systems.
- Gels:Hydrogel suspensions for cosmetic and transdermal applications.
Solid forms retain volume leadership; Liquid preparations face the steepest regulatory headwinds.
Packaging Type:
Channel differentiation drives packaging selection, with natural retail premiums attaching to sustainability credentials and tamper-evident features.
- Bottles:Amber glass or PET containers for liquid extracts and capsules. Oregon's Wild Harvest leverages certified organic wildcrafting protocols to command shelf-space premiums in North American natural retail channels for bottle-packaged finished goods.
- Jars:Wide-mouth containers for powder formats and bulk tea packaging. Madhya Pradesh and Rajasthan contract farming networks supply traceable raw material for jar-packaged South Asian exports.
- Pouches:Flexible film sachets for single-serve functional beverage powders.
- Blister Packs:Thermoformed unit-dose cards for pharmaceutical compliance markets.
Bottles retain volume leadership; Pouches gain share fastest in functional beverage absorption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian markets absorb Astragalus Propinquus primarily through traditional medicine protocols, while Western formulators emphasize standardized extracts for immune-support applications. This consumption-mix differential shapes procurement specifications, regulatory pathways, and supplier capability requirements across major demand centers.
China
TCM-integrated wellness protocols sustain acute demand for dried root slices and standardized extracts. NMPA traditional Chinese medicine substance standards compress approval timelines and accelerate domestic extraction capacity expansion in Shaanxi and Gansu processing clusters. Shaanxi province concentrates pharmaceutical-grade extraction facilities serving both domestic TCM pharmacies and export markets.
Germany
Pharmaceutical formulators specify supercritical CO2-derived extracts for immune-modulation applications, compressing demand for conventional ethanol-extracted alternatives. EFSA Novel Food cataloguing requirements constrain unapproved astragalus-derived ingredients, fragmenting addressable demand for European formulators. Baden-Württemberg hosts GMP-certified extraction houses supplying therapeutic-grade inputs to regional pharmaceutical manufacturers.
United States
Natural retail channels privilege verified chain-of-custody documentation and certified organic wildcrafting protocols. FDA Dietary Supplement cGMP identity-testing burdens filter smaller traders from market access, concentrating supply among capitalized laboratories. Oregon's wildcrafting operations command shelf-space premiums in North American natural product distribution.
India
South Asian extraction houses secure traceable supply through backward integration into contract farming networks. CDSCO herbal medicine regulations govern import and domestic distribution of botanical raw materials for pharmaceutical applications. Madhya Pradesh and Rajasthan cultivation belts supply standardized root material to regional processing facilities.
Japan
Functional beverage manufacturers absorb polysaccharide-standardized extracts for adaptogenic positioning in condition-specific supplements. PMDA oversight of health food claims with functional properties shapes formulation and marketing strategies for finished goods. Kanto region distributors channel premium botanical inputs to domestic nutraceutical formulators and export markets.
Astragalus Propinquus Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with extraction technology and regulatory compliance capability determining tier placement. The upper tier commands premium positioning through in-house phytochemical laboratories and certified organic supply chains. Mid-tier suppliers face displacement pressure as pharmaceutical procurement specifications tighten around HPLC-quantified bioactive markers. Dominant competitive moves include backward integration into contract farming networks and supercritical CO2 extraction infrastructure investments.
Among extraction specialists, Novoherb Technologies and Kan Phytochemicals Private Limited occupy positions reflecting distinct geographic supply strategies. Oregon's Wild Harvest exemplifies the certified organic wildcrafting archetype commanding retail premiums in North American natural channels. These three entities represent the capability bifurcation between capitalized laboratory operations and commodity-trader intermediaries.
| Leading Market Players |
|---|
| Novoherb Technologies |
| Nutragreenlife Biotechnology Co., Ltd |
| Starwest Botanicals Inc. |
| Indigo Herbs Ltd |
| Kan Phytochemicals Private Limited |
| Oregon's Wild Harvest |
| HealthAid Limited |
| PhytoHealth Corporation |
| Naturex |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between pharmaceutical formulators and extraction houses lock in both supply access and price visibility, insulating premium-tier suppliers from spot-market volatility while compressing margins for traders lacking backward integration into Shaanxi and Gansu cultivation networks.
Pricing Analysis
Contract-based long-term offtake dominates procurement between German pharmaceutical formulators and certified extraction facilities, with price differentiation resting on HPLC-quantified bioactive markers and organic certification tier. Cost compression in ethanol-extracted alternatives is intensifying because supercritical CO2 extraction investments filter mid-tier suppliers, while commodity traders face the steepest price sensitivity due to identity-testing burdens under FDA cGMP.
Supply Chain Analysis
Inventory cycles stretching across harvest seasonality in Oregon wildcrafting operations and Madhya Pradesh contract farming networks create lead-time volatility that pharmaceutical buyers mitigate through dual-sourcing strategies. Supply draws from China, India, and the United States as primary concentration points, with dependencies on cycloastragenol-rich root stock, supercritical CO2 processing equipment, and gelatin capsule shell inputs. Single-source vulnerability runs through Shaanxi extraction clusters serving TCM-integrated wellness protocols. Distribution feeds from integrated cultivation-to-extraction operations toward North American natural retail channels and European pharmaceutical formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Astragalus Propinquus market is experiencing high-growth disruption as NMPA registration reforms compress approval timelines and supercritical CO2 extraction technology reshapes competitive capability requirements.
For Market Incumbents: Compound defensive positioning through in-house phytochemical laboratory investments that sustain HPLC quantification capabilities against synthetic adaptogen substitution threats. Expand backward integration into Rajasthan and Madhya Pradesh contract farming networks to secure traceable supply and filter commodity traders from premium procurement tiers.
For New Entrants and Emerging Players: Lead with white-space penetration in condition-specific functional beverages and direct-to-consumer capsule formats where unit-dose convenience shapes repeat purchase behavior. Target North American natural retail channels with verified chain-of-custody documentation as the most penetrable entry point, deploying certified organic wildcrafting protocols as differentiation leverage.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated extraction specialists possessing captive cultivation networks and GMP-certified processing infrastructure over trader intermediaries facing margin compression. Long-term viability over the next decade hinges on regulatory compliance scalability across FDA, EFSA, and NMPA jurisdictions. Monitor pharmacovigilance data developments on astragaloside IV bioavailability claims as the critical inflection signal for valuation recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Extraction Infrastructure | Pharmaceutical formulators in Germany now specify supercritical-derived extracts, displacing ethanol-based alternatives from premium tiers. |
| Backward Integration into Contract Farming | Kan Phytochemicals anchors South Asian supply through captive cultivation networks across Madhya Pradesh and Rajasthan. |
| FDA cGMP Compliance Specialization | Identity-testing infrastructure investments filter non-compliant traders from US market access, creating defensive moats. |
| Direct-to-Consumer Capsule Launch | Oregon's Wild Harvest commands shelf-space premiums in North American natural retail through branded finished goods. |
| NMPA Registration Pathway Optimization | Streamlined approval timelines for standardized root extracts accelerate domestic capacity expansion in Shaanxi processing clusters. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extraction facility managers, pharmaceutical procurement leads, TCM pharmacy dispensers, and regulatory affairs specialists; and secondary validation through NMPA substance standards documentation, FDA cGMP guidance filings, EFSA Novel Food catalogues, and customs trade records. Bottom-up volume modeling triangulated against top-down value estimates derived from procurement contract analysis.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, end-use industry, form, and packaging format alongside regional regulatory cluster variations. CAGRs were derived from trend extrapolation of historical procurement patterns and capacity expansion announcements, with inputs including supercritical CO2 adoption rates and NMPA approval velocity metrics.
The analysis sits within stated boundaries; outcomes outside sustained NMPA reform momentum or stable pharmacovigilance data on astragaloside IV would require recalibration. Forecasts reflect documented assumptions on regulatory clarity and extraction technology diffusion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Folic Acid Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Bovine Collagen Peptide Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
Natural Colostrum Supplements Market
Nutritional Supplements
Heart Health Supplement Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Pulse Protein Market
Nutritional Supplements
Europe Nutraceutical Excipients Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
Japan Protein Market