
 Olive Supplements Market | 2026-2036
Olive Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Olive Supplements Market Analytics
Clean-label extraction technology is reshaping how olive polyphenols are concentrated and standardized for supplement applications. NOW Health Group Inc. leverages vertical integration from raw material sourcing to finished softgel production. Gaia Herbs Inc. differentiates through certified organic traceability programs that anchor consumer trust in premium channels. Comvita Ltd. specializes in polyphenol stabilization methods that extend shelf life without synthetic preservatives.
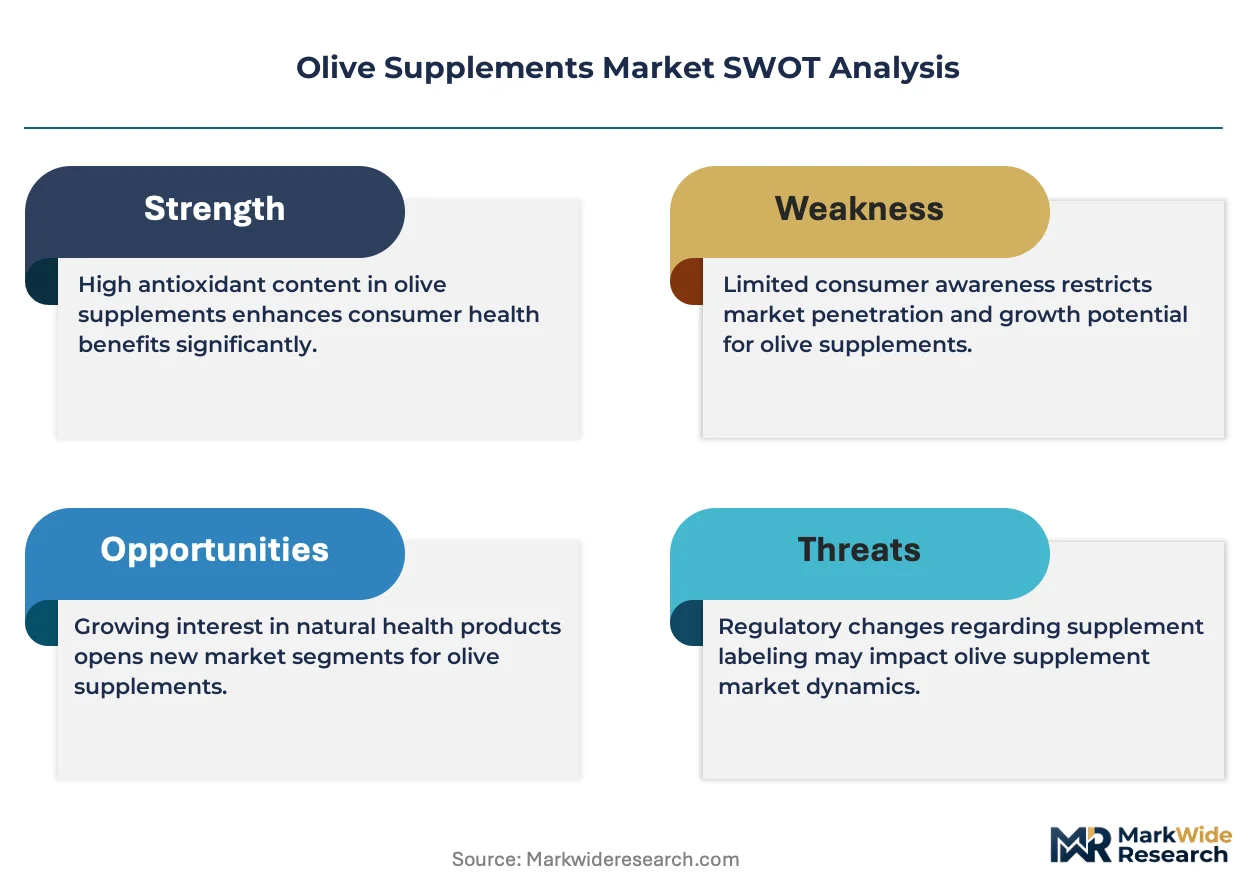
Olive supplements contain standardized hydroxytyrosol, oleuropein, and other polyphenolic compounds extracted from Olea europaea leaf or fruit, typically formulated at concentrations ranging from 10% to 40% active polyphenols for antioxidant and cardiovascular support applications. Oil-based delivery formats dominate current revenue pools due to superior bioavailability of lipophilic actives, while capsule and tablet forms are gaining traction among fitness enthusiasts seeking precise dosing portability. Powder formulations remain nascent but attract functional food manufacturers pursuing clean-label ingredient integration.
EFSA health claim substantiation requirements under EU Regulation 1924/2006 constrain marketing language for cardiovascular benefit claims, compelling reformulation toward compliant polyphenol thresholds. FDA enforcement of Current Good Manufacturing Practice regulations for dietary supplements shapes quality control investments by US-market suppliers. Stakeholders must monitor evolving polyphenol measurement methodologies and jurisdiction-specific health claim frameworks to maintain competitive positioning without regulatory exposure.
Market Dynamics
Clean-label extraction technology is compressing production timelines for standardized olive polyphenols while EFSA's tightening health claim substantiation requirements force reformulation investments. This dual pressure reshapes competitive positioning between Mediterranean raw material controllers and technology-forward processors.
Growth Catalysts
- EU Novel Food Regulation:Standardized approval pathways for hydroxytyrosol concentrates accelerate new product introductions across member states. Polyphenol-based cardiovascular claims gain clearer substantiation frameworks.
- Functional food manufacturers:Beverage and fortified food producers integrate olive-derived ingredients into clean-label antioxidant formulations. Cross-category demand expands beyond traditional supplement channels.
- Spain-Italy cultivation clusters:Established Olea europaea processing infrastructure secures raw material throughput for high-volume extraction operations. Geographic concentration lowers procurement volatility for standardized actives.
Market Restraints
- Input cost volatility:Olive leaf and fruit biomass prices fluctuate with agricultural yield cycles and climate stress on Mediterranean orchards. Raw material insecurity constrains margin predictability.
- EFSA health claim friction:Article 13.1 cardiovascular benefit claims require polyphenol thresholds that many existing formulations fail to meet. Compliance-driven reformulation absorbs R&D capital without immediate revenue return.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and tertiary butylhydroquinone retain cost advantages in mass-market food preservation. Price-sensitive applications delay natural polyphenol adoption.
Strategic Opportunities
- Sports nutrition channel expansion:Fitness enthusiasts seeking portable precise-dosing formats drive capsule and tablet format development. Oil-based bioavailability advantages meet convenience requirements through microencapsulation.
- India PLI scheme alignment:Domestic herbal extract manufacturing incentives attract investment in localized olive leaf processing infrastructure. Import substitution policies favor regional supply chain development.
- Polyphenol stabilization convergence:Advanced encapsulation technologies extend shelf life without synthetic preservatives. Clean-label preservation meets extended distribution requirements for e-commerce channels.
Industry Challenges
- Analytical methodology standardization:Inconsistent hydroxytyrosol and oleuropein measurement protocols across laboratories create formulation uncertainty. Harmonized reference methods remain under development at ISO and AOAC levels.
- CGMP compliance capital intensity:FDA dietary supplement manufacturing regulations require facility upgrades for US market access. Quality control infrastructure investments strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olive Supplements Market |
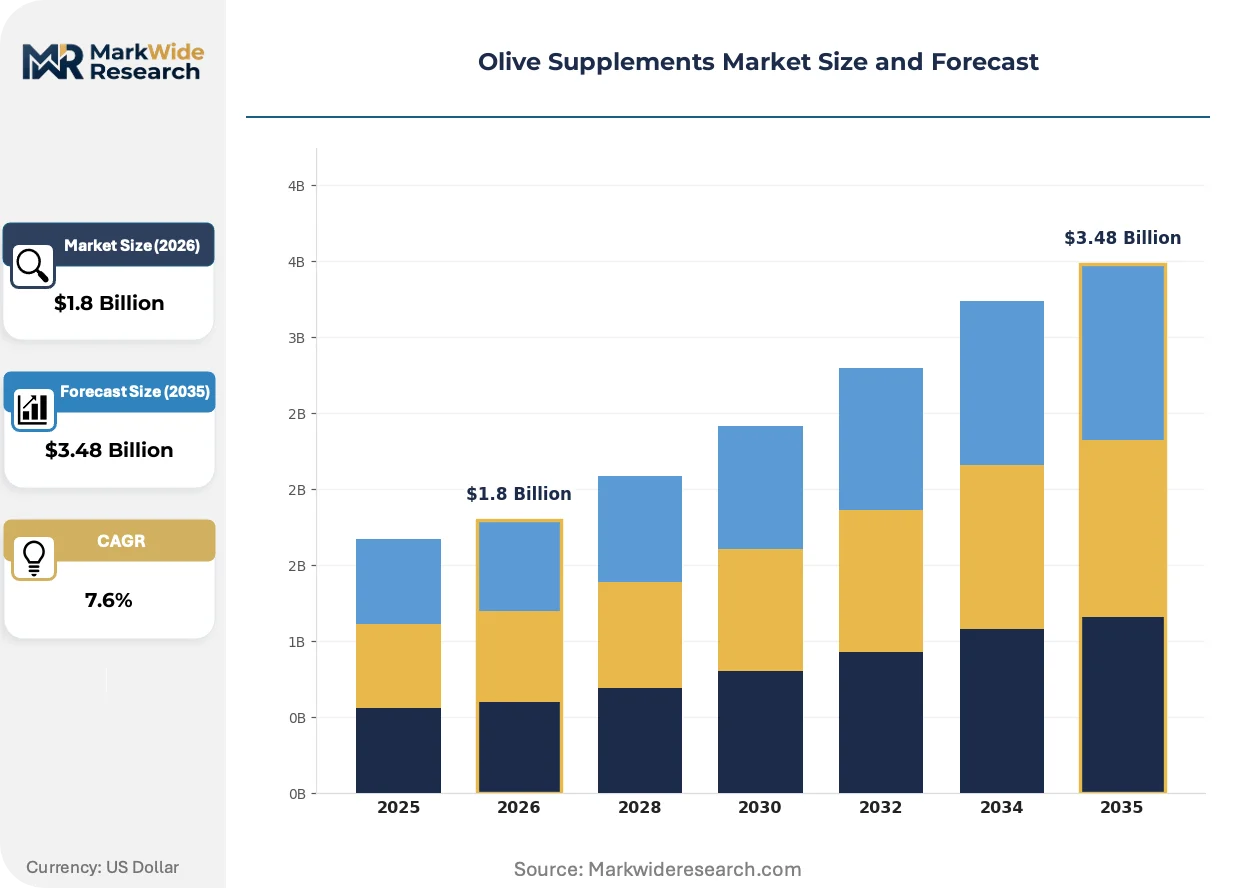
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil, Extract, Capsule, Tablet Form: Liquid, Powder, Softgel, Cream End User: Adults, Seniors, Athletes, Fitness Enthusiasts Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Barleans Organic Oils LLC, Comvita Ltd., Dohler GmbH, Gaia Herbs Inc., Evergreen Life Products Srl, Olivus Inc., Nature's Way, NOW Health Group Inc., Dr. Willmar Schwabe GmbH and Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olive Supplements Market Evolving Landscape
Supercritical CO2 extraction is displacing solvent-based methods across premium olive polyphenol production. This technology shift compresses environmental compliance costs while enabling higher concentration ratios for functional food integration.
Membrane filtration technology is virtualizing traditional chromatographic separation steps in hydroxytyrosol concentration workflows. Spanish and Italian extractors adopt ceramic and polymeric membrane systems to reduce organic solvent consumption. This displacement lowers operational expenditure while enabling food-grade certification for broader ingredient applications.
EFSA's updated guidance on polyphenol characterization requires quantitative metabolite profiling for novel food approvals. Extractors must invest in LC-MS analytical infrastructure to document oleuropein derivative pathways. Mediterranean suppliers with in-house phytochemistry capabilities gain first-mover advantage in compliant concentrate commercialization.
Direct-to-consumer subscription models are fragmenting traditional supplement retail channels. Olive oil and softgel formats bypass pharmacy and mass-market intermediaries through specialized wellness platforms. German and French consumers demonstrate highest conversion rates for polyphenol-focused monthly delivery programs.
Olive Supplements Market Segmentation
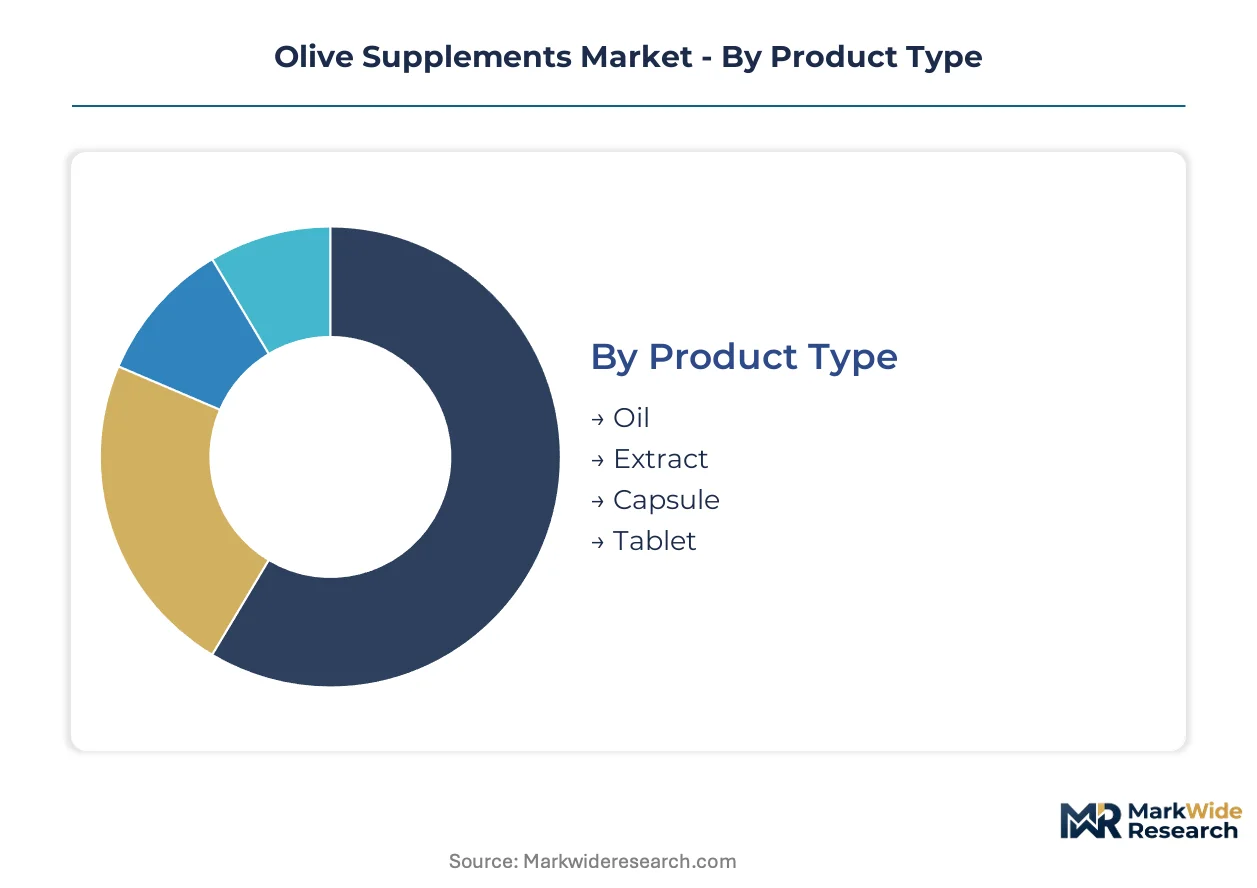
Olive supplement segmentation reveals divergent production cycles across delivery formats, with oil-based formulations requiring extended stabilization timelines while powder formats compress manufacturing-to-shelf intervals. Understanding these velocity differentials shapes inventory strategy and working capital allocation for extractors and finished goods manufacturers.
Product Type:
Cycle times vary dramatically across extraction and formulation approaches, with cold-pressed oils demanding months of settling and filtration while encapsulated extracts move through accelerated release testing protocols.
- Oil:Cold-pressed or refined Olea europaea fruit oil retains native polyphenol matrices at 10-20% hydroxytyrosol equivalents. Mediterranean bottling facilities in Spain and Italy dominate supply, though California orchards are expanding cold-press capacity for North American demand.
- Extract:Standardized oleuropein and hydroxytyrosol concentrates at 20-40% polyphenol content enable precise dosing in functional food integration. Spanish extractors in Andalusia leverage supercritical CO2 infrastructure to compress lead times for beverage manufacturer procurement.
- Capsule:Hard-shell gelatin and vegetable cellulose formats encapsulate powdered olive leaf extract for portability-focused consumers.
- Tablet:Compressed formulations with binding agents suit mass-market retail positioning and automated packaging lines.
Oil anchors the volume base while extract gains share at the steepest rate.
Form:
Cost tier differentiation separates premium-positioned delivery systems from commodity formats, with softgel encapsulation commanding manufacturing premiums over bulk powder.
- Liquid:Unemulsified oil and glycerite suspensions serve traditional Mediterranean consumption patterns and culinary crossover applications.
- Powder:Spray-dried and freeze-dried extracts enable functional food manufacturer integration into protein blends and beverage premixes.
- Softgel:Oil-filled gelatin capsules protect lipophilic actives from oxidation while masking taste profiles. NOW Health Group and comparable integrators operate captive softgel lines to capture margin between extract and finished goods.
- Cream:Topical formulations with olive-derived squalene and polyphenols target dermal antioxidant positioning in cosmeceutical channels.
Softgel commands the premium tier while powder expands most quickly into cross-category applications.
End User:
Application intensity varies across demographic segments, with athletes demanding rapid recovery positioning while seniors prioritize cardiovascular maintenance claims.
- Adults:General wellness consumers seeking preventive antioxidant supplementation represent the broadest addressable population.
- Seniors:Cardiovascular and cognitive health positioning targets consumers over 55 with EFSA-compliant polyphenol thresholds for approved claims.
- Athletes:Exercise-induced oxidative stress mitigation drives demand for high-dose hydroxytyrosol formats with rapid absorption kinetics.
- Fitness Enthusiasts:Lifestyle-oriented consumers without competitive athletic demands favor portable capsule and tablet formats for gym bag convenience.
Adults provide the volume foundation while fitness enthusiasts climb the fastest as gym culture normalizes supplement routines.
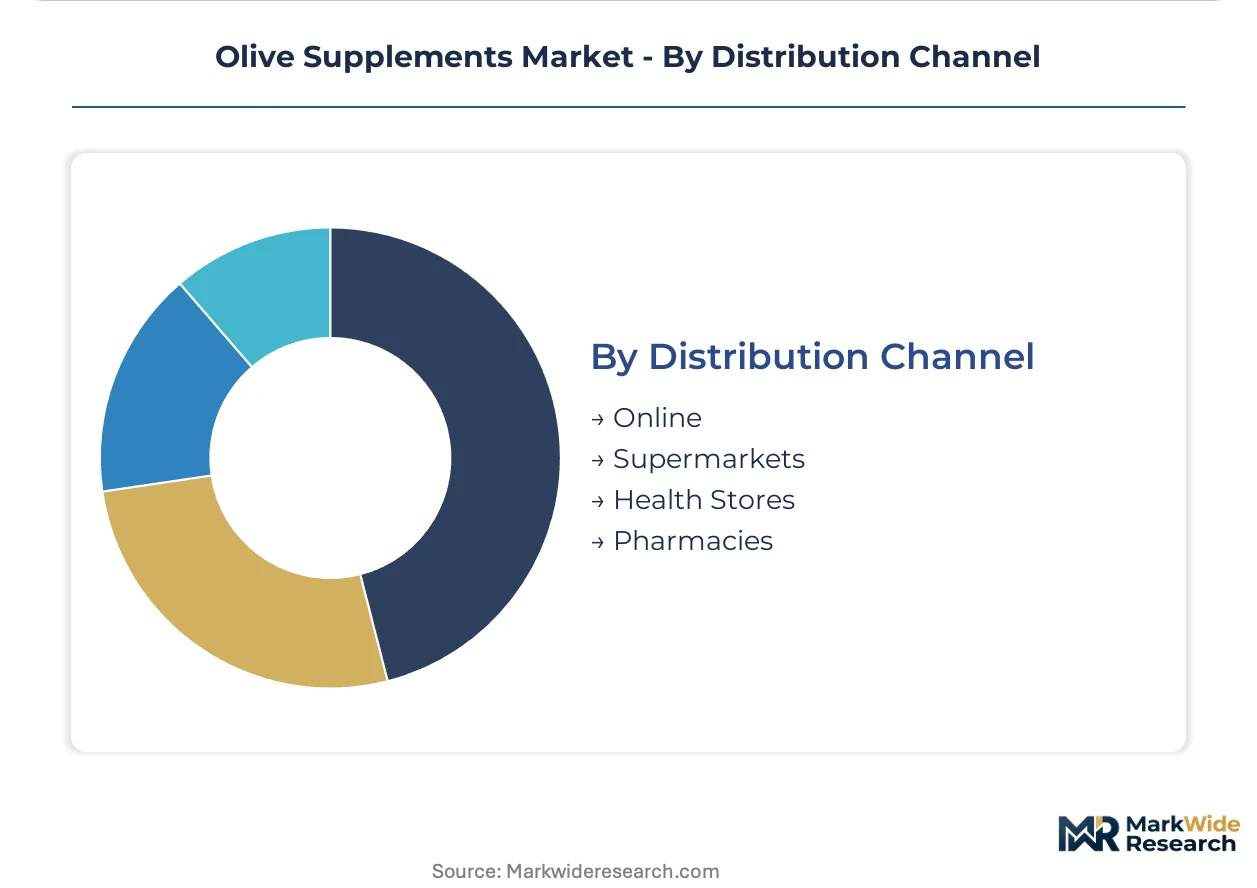
Distribution Channel:
Customer type stratification separates subscription-committed direct buyers from transaction-oriented retail shoppers, with channel selection determining margin structure and brand control.
- Online:Direct-to-consumer platforms and specialized wellness marketplaces enable subscription retention models. German and French consumers demonstrate highest conversion rates for polyphenol-focused monthly delivery programs.
- Supermarkets:Mass-market retail placement requires price-competitive positioning against synthetic antioxidant alternatives.
- Health Stores:Independent and chain natural products retailers emphasize certified organic traceability and staff education on polyphenol sourcing.
- Pharmacies:Professional recommendation channels favor clinically positioned extracts with documented bioavailability data.
Online channels expand most quickly while health stores retain the highest margin positioning for premium traceability formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preventive wellness buyers concentrate in Mediterranean economies with established olive consumption traditions, while functional food manufacturers in North America and Asia-Pacific drive cross-category ingredient demand.
Spain
Andalusian extraction facilities process the majority of European olive leaf biomass for standardized hydroxytyrosol concentrates. EFSA's Novel Food Regulation streamlines approval pathways for polyphenol-based cardiovascular claims. Jaén and Córdoba provinces host supercritical CO2 infrastructure that supplies beverage manufacturers with food-grade certified extracts.
Italy
Pharmacy-channel consumers in northern regions favor clinically positioned softgel formats with documented bioavailability data. REACH compliance requirements shape solvent selection in extraction workflows. Tuscany and Umbria cultivation clusters secure raw material throughput for premium organic traceability programs.
United States
Fitness enthusiasts in California and the Northeast drive demand for portable capsule formats with precise dosing. FDA Current Good Manufacturing Practice regulations mandate facility upgrades for domestic supplement manufacturing. Central Valley orchards are expanding cold-press capacity to reduce import dependency for North American demand.
Germany
Direct-to-consumer subscription platforms achieve highest conversion rates for polyphenol-focused monthly delivery programs. CSRD reporting requirements pressure mid-scale processors to document sustainable sourcing practices. Bavarian and Baden-Württemberg distribution hubs coordinate cross-border fulfillment for French and Benelux markets.
India
Domestic herbal extract manufacturers leverage PLI scheme incentives to build localized olive leaf processing infrastructure. FSSAI labeling standards constrain marketing language for antioxidant positioning. Maharashtra and Gujarat processing zones target import substitution for regional supply chain development.
Olive Supplements Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mediterranean raw material controllers anchor supply security while technology-forward processors capture premium extraction margins. Three archetypes dominate: vertically integrated softgel manufacturers, certified organic traceability specialists, and polyphenol stabilization technology developers. Capacity expansion in supercritical CO2 infrastructure and backward integration into orchard assets represent the dominant competitive moves reshaping positioning.
Among North American integrators, NOW Health Group Inc. occupies a position exemplifying captive manufacturing architecture, while Gaia Herbs Inc. represents the certified organic traceability archetype. Comvita Ltd. anchors the polyphenol stabilization specialist tier. These three companies illustrate how geographic origin and structural configuration map to distinct competitive vectors without requiring identical strategic postures.
| Leading Market Players |
|---|
| Barleans Organic Oils LLC |
| Comvita Ltd. |
| Dohler GmbH |
| Gaia Herbs Inc. |
| Evergreen Life Products Srl |
| Olivus Inc. |
| Nature's Way |
| NOW Health Group Inc. |
| Dr. Willmar Schwabe GmbH and Co. KG |
| Others |
Value Network & Pricing Analysis
Barcelona-Valencia freight corridors transmit Mediterranean olive biomass to extraction facilities, with container rates compressing procurement costs for Andalusian processors while amplifying price spreads between premium organic traceability tiers and commodity-standard concentrates.
Pricing Analysis
Cost-plus contracts indexed to olive fruit and leaf biomass spot markets dominate procurement between cultivators and extractors. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-compliant polyphenol concentrates from food-grade extracts and bulk oil commodities. Pricing pressure stems from synthetic antioxidant substitution in mass-market food preservation, with cost-sensitive beverage manufacturers delaying natural polyphenol adoption. Fitness enthusiasts seeking portable capsule formats demonstrate lowest price sensitivity, while functional food manufacturers purchasing bulk powder exhibit highest elasticity.
Supply Chain Analysis
Supply-chain finance facilities extended by Spanish and Italian extraction houses to Andalusian and Tuscan cultivators stabilize raw material throughput against agricultural yield volatility. Geographic concentration centers on Spain, Italy, and emerging California processing zones. Raw material dependencies rest on Olea europaea leaf biomass, cold-pressed fruit oil, and standardized hydroxytyrosol concentrates. Single-source vulnerability runs through Mediterranean climate exposure affecting orchard productivity. Distribution runs through direct-to-consumer subscription platforms, pharmacy channels, and health store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as functional food manufacturers accelerate cross-category polyphenol integration beyond traditional supplement channels.
For Market Incumbents: Entrench supply security through backward integration into orchard assets in Jaén and Córdoba provinces, while deploying supercritical CO2 capacity additions to defend extraction margins against technology-forward processors. EFSA's tightening Novel Food substantiation requirements threaten formulation-dependent competitors; incumbents should anchor R&D in LC-MS analytical infrastructure to lock in compliant concentrate commercialization. For New Entrants and Emerging Players: Build out sports nutrition channel presence with microencapsulated oil formats that merge bioavailability advantages with gym-bag portability, targeting fitness enthusiasts in California and the Northeast. White-space concentrates in India's PLI-backed herbal extract manufacturing, where localized olive leaf processing infrastructure remains underdeveloped. Go-to-market should leverage direct-to-consumer subscription models proven in German and French markets. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified botanical extract houses with undermonetized olive polyphenol divisions and captive softgel manufacturing lines. Long-term viability hinges on regulatory compliance infrastructure and clean-label extraction technology ownership. Watch for inflection in FSSAI enforcement patterns affecting antioxidant claim permissibility in India.| Strategic Initiative | Industry Significance |
|---|---|
| Supercritical CO2 Capacity Expansion | Spanish extractors in Andalusia compress lead times for beverage manufacturer procurement while securing food-grade certification. |
| Backward Integration into Orchard Assets | Jaén and Córdoba province cultivation clusters lock in raw material throughput against climate-driven yield volatility. |
| Direct-to-Consumer Subscription Launch | German and French wellness platforms demonstrate highest conversion rates for polyphenol-focused monthly delivery programs. |
| LC-MS Analytical Infrastructure Investment | Mediterranean suppliers with in-house phytochemistry capabilities gain first-mover advantage in EFSA-compliant concentrate commercialization. |
| Sports Nutrition Channel Expansion | Microencapsulation technology merges oil-based bioavailability with capsule portability for fitness enthusiast penetration. |
Research Methodology
Desk research of customs trade records, EFSA Novel Food approval databases, and FSSAI labeling guidelines preceded structured interviews with extraction facility operations directors, functional food manufacturer procurement leads, pharmacy channel category managers, and dietary supplement brand managers. Primary fieldwork validated secondary data from SEC filings, EU agricultural subsidy disclosures, and olive oil industry association reports. Bottom-up volume modeling triangulated against top-down market sizing across product type, delivery format, and distribution channel dimensions.
The forecast framework holds EFSA enforcement intensity and FDA CGMP compliance thresholds constant while varying functional food manufacturer adoption rates and climate stress scenarios across the projection horizon. Segmentation modeling incorporated product type, form, end user demographic, and distribution channel dimensions. CAGRs derived from weighted average of historical trajectory and penetration-adjusted growth curves, with inputs including supercritical CO2 capacity buildout schedules and PLI scheme disbursement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by technology-forward processors or accelerated synthetic antioxidant substitution would shift outcomes. Macroeconomic deviation, regulatory enforcement intensity changes, or breakthrough encapsulation technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Chaga Mushroom Extract Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Dietary Fiber Gummies Market
Nutritional Supplements
Soy Isoflavones Market
Nutritional Supplements
Red Yeast Rice Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Asia Pacific Collagen Supplements Market
Nutritional Supplements
Mexico Collagen Peptides Market
Nutritional Supplements
Europe Moringa Supplement Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Wellness Supplements Market
Nutritional Supplements
Africa Beta Glucan Market
Nutritional Supplements
Micellar Casein Market
Nutritional Supplements
Vegan Collagen Powder Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
EPA and DHA Market