
 Older Adults Health Supplements Market | 2026-2036
Older Adults Health Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Older Adults Health Supplements Market Analytics
China is tilting its manufacturing capacity toward geriatric nutrition complexes with new facility investments in Jiangsu and Zhejiang provinces. Abbott Laboratories leverages its clinical nutrition heritage to dominate hospital discharge channels for older adults. Glanbia plc anchors its position through backward integration into whey protein isolate supply for senior-focused formulations. Haleon PLC differentiates via pharmacist-driven recommendation networks across European retail.
Older adults health supplements comprise orally administered nutritional preparations formulated with bioactive compounds, including standardized vitamin D3, calcium citrate, and EPA/DHA concentrates, manufactured through microencapsulation and cold-press extraction to preserve thermolabile actives for physiological support in aging populations. Vitamins and minerals sustain the largest revenue pool due to established prescriber familiarity and insurance adjacency, while probiotics represent the fastest-expanding category as gut-brain axis research validates cognitive claims in geriatric cohorts. Delivery mode preferences fragment sharply by care setting: gummies gain traction in home care for palatability, whereas liquid formats dominate nursing homes where dysphagia prevalence drives formulation requirements.
FDA cGMP inspections and USP verification programs enforce identity, purity, and potency standards that determine retail pharmacy stocking decisions for senior-targeted products. EFSA health claim authorization under Regulation 1924/2006 constrains marketing language for European brands, while Japan's FOSHU system creates a premium regulatory tier for functionally substantiated elder supplements. Stakeholders must monitor evolving substantiation requirements for novel ingredients as regulatory divergence between major markets intensifies compliance architecture decisions.
Market Dynamics
FDA cGMP enforcement and EFSA health claim substantiation requirements are compressing formulation timelines while elevating quality assurance costs for senior-targeted supplement portfolios. Nursing home procurement consolidation is simultaneously shifting volume toward condition-specific program contracts.
Growth Catalysts
- FOSHU Premium Tier:Japan's Foods for Specified Health Uses system creates reimbursement-adjacent positioning for clinically validated elder formulations, pulling R&D investment toward substantiated cognitive and mobility claims.
- Hospital Discharge Protocols:Post-acute care facilities in the United States are integrating nutrition screening into discharge planning, opening institutional channels for medical-grade supplement dispensing.
- Gut-Brain Axis Research:Probiotic strains with documented neurocognitive endpoints in geriatric cohorts are expanding addressable demand beyond digestive health into mood and memory positioning.
Market Restraints
- Wild-Caught Fish Oil Volatility:Peruvian anchovy quota fluctuations and El Niño disruptions are compressing EPA/DHA concentrate margins for cardiovascular-positioned senior products.
- Cholecalciferol Feedstock Concentration:Seven Chinese manufacturers control over 80% of global vitamin D3 raw material supply, creating single-source vulnerability for osteoporosis-focused formulations.
- EFSA Article 13.5 Rejection Rate:The European Food Safety Authority's stringent substantiation standards for novel senior health claims are blocking market access for botanical and probiotic innovators.
Strategic Opportunities
- German Pharmacy Networks:Apotheken channel consolidation creates scale-efficient entry points for pharmacist-recommended senior nutrition programs with insurance reimbursement pathways.
- Liquid Format Dysphagia Positioning:Texture-modified delivery systems for nursing home residents with swallowing disorders command 40-60% price premiums over standard tablets with limited formulation competition.
- IRA Preventive Coverage Expansion:United States Inflation Reduction Act provisions expanding Medicare preventive benefits may extend to medical nutrition counseling and prescribed supplement protocols.
Industry Challenges
- Clinical Trial Recruitment:Geriatric cohort retention in 12-month probiotic cognition studies suffers 35-50% dropout rates, delaying substantiation timelines and regulatory submissions.
- Multi-Country cGMP Harmonization:Simultaneous compliance with FDA 21 CFR Part 111, EFSA GMP, and Japan MHLW standards requires redundant quality systems that inflate fixed costs for mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Older Adults Health Supplements Market |
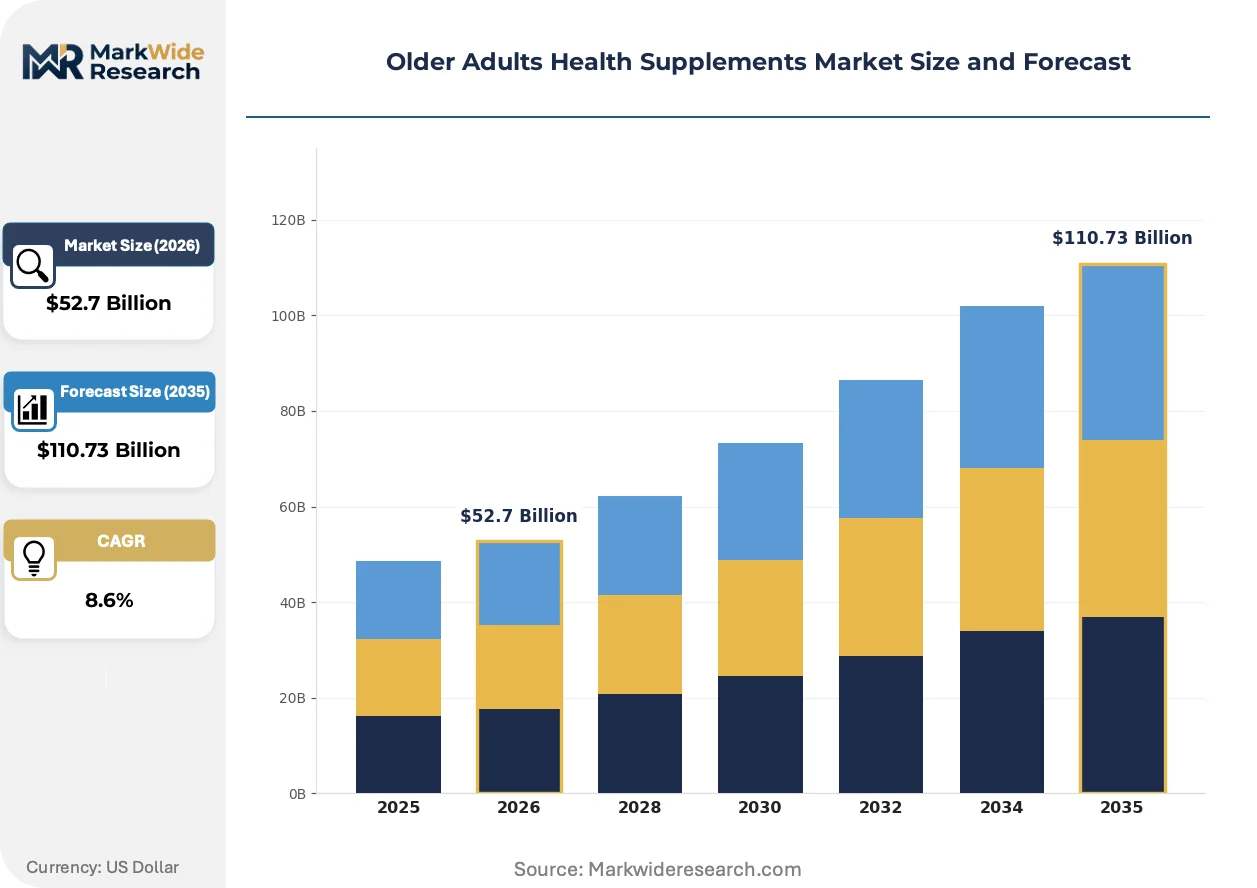
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Omega-3 Fatty Acids Delivery Mode: Pills, Powders, Gummies, Liquid Ingredient Source: Natural, Synthetic, Herbal, Fortified End User: Home Care, Assisted Living, Nursing Homes, Outpatient Clinics |
| Companies Covered | Nestlé S.A., Abbott Laboratories, Haleon PLC, Bayer AG, Amway Corporation, Glanbia plc, Otsuka Pharmaceutical, Nature's Bounty Co., Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Older Adults Health Supplements Market Evolving Landscape
Liposomal encapsulation and precision fermentation are converging to reshape bioavailability standards for senior-targeted actives. These platform technologies are compressing the gap between pharmaceutical and nutritional efficacy claims while fragmenting manufacturing footprints across biotech and traditional supplement facilities.
Liposomal vitamin D3 and curcumin formulations are rendering obsolete standard oil-based softgels for populations with malabsorption conditions. Nursing home formulary committees in Germany and Japan are adopting these formats for residents with Crohn's disease, celiac, or post-bariatric surgery status. The technology is compressing competitive differentiation around particle size distribution and phospholipid sourcing rather than raw ingredient purity alone.
EFSA's 2023 updated guidance on health claim substantiation for the elderly is tightening clinical endpoint requirements for joint and cognitive positioning. European brands must now demonstrate statistically significant outcomes in populations over 65 rather than extrapolating from younger adult studies. Probiotic and collagen peptide segments are responding by commissioning dedicated geriatric trials with mobility and memory primary endpoints.
Direct-to-patient subscription models are displacing retail pharmacy replenishment for chronic condition management. United States Medicare Advantage plans with supplemental benefit allowances are piloting home delivery programs for osteoporosis and cardiovascular prevention bundles. This channel shift is most visible in Florida and Arizona retirement corridors where plan density and digital literacy among aging subscribers overlap.
Older Adults Health Supplements Market Segmentation
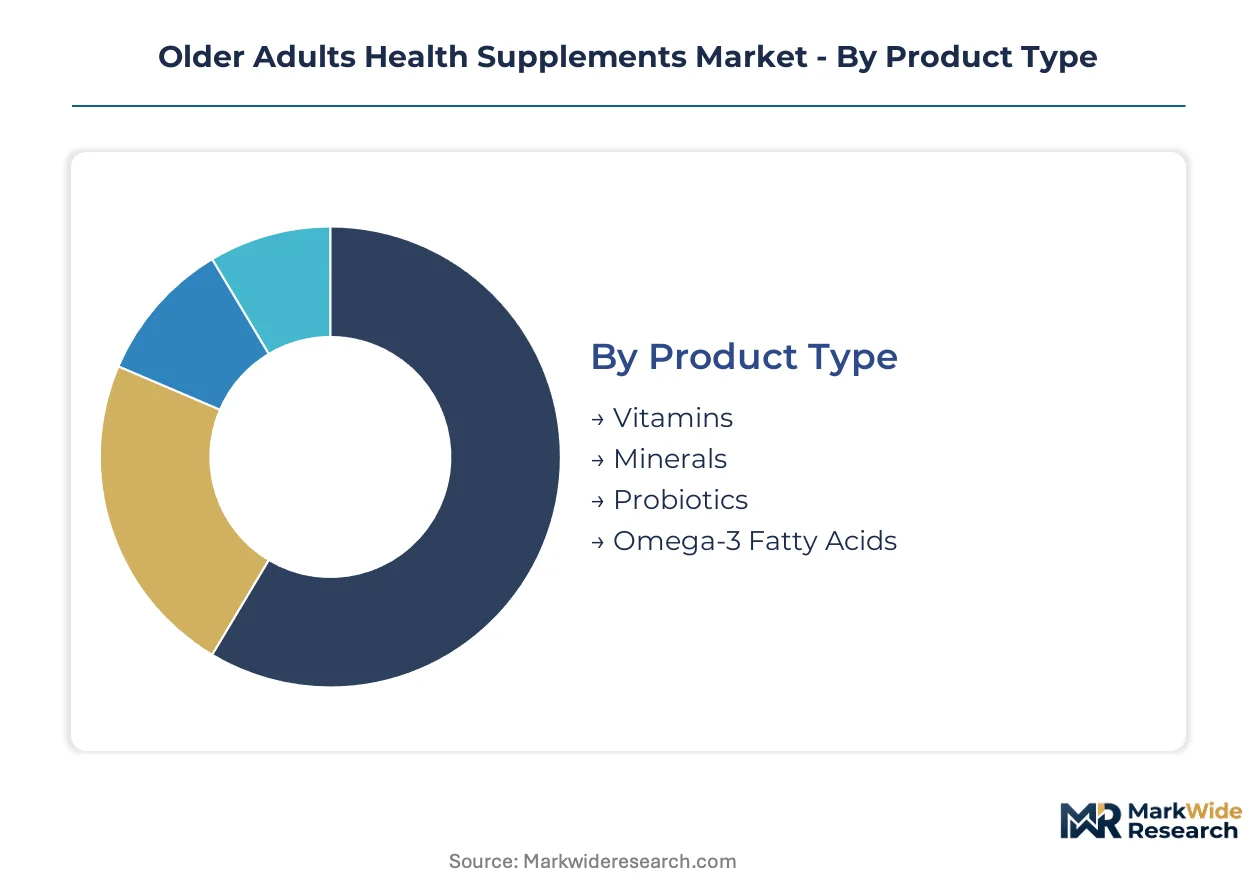
Older adults health supplements fragment across formulation chemistry, administration practicality, and care setting infrastructure. Each segmentation axis carries distinct margin profiles and regulatory burdens that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with probiotics demanding cold-chain logistics support and clinician education that vitamins rarely require.
- Vitamins:Standardized vitamin D3, B12 methylcobalamin, and K2 menaquinone formulations dominate prescriber familiarity and insurance adjacency. Demand concentrates in United States Medicare Advantage supplemental benefit programs where pharmacy networks handle reimbursement complexity.
- Minerals:Calcium citrate, magnesium glycinate, and zinc picolinate address osteoporosis and wound healing protocols. German Apotheken channels capture the highest margin concentration due to pharmacist consultation requirements and statutory health insurance partial coverage.
- Probiotics:Multi-strain formulations with documented CFU counts at expiration require refrigerated distribution and patient adherence coaching.
- Omega-3 Fatty Acids:EPA/DHA concentrates from marine or algal sources face raw material volatility and oxidation stability challenges.
Vitamins and minerals hold the largest share; momentum sits with probiotics as gut-brain axis research validates cognitive claims.
Delivery Mode:
Cost tier stratification separates premium liquid formats from economy tablet production, with texture-modified systems commanding specialized manufacturing investment.
- Pills:Standard tablets and capsules retain volume leadership through manufacturing scale and packaging stability. United States retail pharmacy chains prioritize USP-verified tablet SKUs for their senior-targeted planogram slots.
- Liquid:Texture-modified and flavor-masked solutions address dysphagia prevalence in institutional settings. Japanese nursing homes and assisted living facilities specify liquid formats in procurement tenders, accepting 40-60% price premiums over standard tablets.
- Powders:Single-serve sachets and bulk canisters appeal to home care mixing flexibility.
- Gummies:Palatability-driven formats gain traction in home care where patient compliance overrides cost considerations.
Pills hold the largest share; gummies are expanding most quickly as palatability-driven positioning penetrates home care channels.
Ingredient Source:
Application requirements from institutional procurement committees favor synthetic consistency, while retail differentiation pushes natural and herbal positioning.
- Synthetic:Bio-identical molecules manufactured through chemical synthesis deliver batch-to-batch consistency critical for nursing home formulary approval. United States FDA cGMP enforcement prioritizes synthetic supply chains for their documentation traceability.
- Natural:Fermentation-derived and plant-extracted actives command premium positioning in European markets where EFSA health claim substantiation favors naturally sourced bioactives.
- Herbal:Standardized botanical extracts face regulatory scrutiny for adulteration and standardization.
- Fortified:Food-matrix delivery systems integrate supplements into conventional nutrition products.
Synthetic sources hold the largest share; natural sourcing is climbing the fastest as European and Japanese consumers prioritize clean-label positioning.
End User:
Customer type determines purchasing authority, with institutional procurement committees operating on 12-24 month contract cycles distinct from retail replenishment patterns.
- Home Care:Individual consumers and family caregivers drive replenishment through retail pharmacy, e-commerce subscription, and direct-to-patient delivery. United States Medicare Advantage supplemental benefit pilots in Florida and Arizona retirement corridors are reshaping channel economics.
- Nursing Homes:Centralized procurement departments negotiate condition-specific program contracts with annual volume commitments. German and Japanese facility networks specify liquid formats and therapeutic nutrition bundles in tenders.
- Assisted Living:Semi-institutional settings balance resident preference with staff administration practicality.
- Outpatient Clinics:Hospital discharge protocols and medical nutrition counseling create prescription-adjacent dispensing opportunities.
Home care holds the largest share; nursing homes are gaining share fastest as procurement consolidation shifts volume toward condition-specific program contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States buyers favor insurance-adjacent vitamin bundles through Medicare Advantage channels, while Japanese consumers prioritize FOSHU-certified functional claims, and German procurement committees specify liquid dysphagia formats for institutional contracts.
United States
Medicare Advantage supplemental benefit pilots in Florida and Arizona retirement corridors are reshaping channel economics toward direct-to-patient subscription models. FDA 21 CFR Part 111 cGMP enforcement determines retail pharmacy stocking decisions for senior-targeted products. Hospital discharge protocols in Texas and California are integrating nutrition screening into post-acute care planning.
Germany
Apotheken channel consolidation creates scale-efficient entry points for pharmacist-recommended senior nutrition programs with statutory health insurance partial coverage. EFSA health claim authorization under Regulation 1924/2006 constrains marketing language for European brands. Manufacturing clusters in Bavaria and North Rhine-Westphalia specialize in precision fermentation for liposomal encapsulation formats.
Japan
FOSHU premium tier positioning pulls R&D investment toward substantiated cognitive and mobility claims with reimbursement-adjacent access. Japan MHLW standards enforce quality benchmarks that exceed baseline international requirements. Production facilities in Kanto and Kansai regions concentrate on texture-modified liquid formulations for nursing home procurement tenders.
China
Seven domestic manufacturers control over 80% of global vitamin D3 raw material supply, creating single-source vulnerability for osteoporosis-focused formulations. SAMR oversight of dietary supplement manufacturing is tightening facility inspection protocols. New facility investments in Jiangsu and Zhejiang provinces target geriatric nutrition complex capacity expansion.
United Kingdom
Pharmacist-driven recommendation networks across retail channels favor clinically validated elder formulations with documented bioavailability endpoints. MHRA alignment with EFSA substantiation standards blocks market access for botanical innovators lacking dedicated geriatric trials. London and Southeast England clusters focus on subscription platform development for chronic condition management bundles.
Older Adults Health Supplements Market Competitive Landscape
Capability concentration sits with clinical nutrition heritage players; scale advantage sits with diversified consumer health conglomerates. The market structures around three tiers: pharmaceutical-grade manufacturers with hospital discharge channel access, retail pharmacy network anchors with USP verification, and direct-to-consumer specialists with subscription infrastructure. Dominant competitive moves include backward integration into whey protein isolate supply and pharmacist network consolidation across European retail.
Among diversified nutrition conglomerates, Nestlé S.A. and Danone occupy positions bridging medical and consumer channels through clinical heritage assets. Abbott Laboratories exemplifies the pharmaceutical-grade tier with hospital discharge protocol integration. Haleon PLC and Bayer AG represent European retail pharmacy network anchors leveraging pharmacist recommendation systems. Amway Corporation sits within the direct-to-consumer specialist archetype with subscription infrastructure capabilities. Glanbia plc anchors the ingredient supply tier through in-house production of protein isolates for senior-focused formulations.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Abbott Laboratories |
| Haleon PLC |
| Bayer AG |
| Amway Corporation |
| Glanbia plc |
| Otsuka Pharmaceutical |
| Nature's Bounty Co. |
| Danone |
| Others |
Value Network & Pricing Analysis
Seven Chinese manufacturers controlling over 80% of global vitamin D3 raw material supply concentrate upstream margin capture in Jiangsu and Zhejiang provinces, while downstream pricing power fragments across German Apotheken networks, Japanese FOSHU-certified tiers, and United States Medicare Advantage supplemental benefit channels.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement for nursing home and assisted living facilities, with 12-24 month volume commitments locking in standard tablet and liquid format pricing. Three-tier pricing structure across premium liposomal encapsulation, standard USP-verified tablets, and economy synthetic vitamin bundles reflects certification grade and bioavailability testing investment. Pricing pressure stems from wild-caught fish oil volatility and Peruvian anchovy quota fluctuations compressing EPA/DHA concentrate margins. Home care subscribers through direct-to-patient platforms exhibit lowest price sensitivity, while retail pharmacy chain buyers drive hardest volume discount negotiations.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Glanbia plc's in-house whey protein isolate production, Abbott Laboratories' clinical nutrition heritage facilities, and specialized liposomal encapsulation foundries in Bavaria and North Rhine-Westphalia. Raw material dependencies center on Chinese vitamin D3 feedstock, marine and algal omega-3 sources, and precision fermentation-derived probiotic strains. Single-source vulnerability in cholecalciferol supply creates structural risk for osteoporosis-focused formulations. Distribution runs through pharmacist-driven recommendation networks in European retail, hospital discharge protocols in United States post-acute care, and FOSHU-certified channels in Japanese reimbursement-adjacent positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping this market as direct-to-patient subscription infrastructure displaces retail pharmacy replenishment, with Medicare Advantage supplemental benefit pilots in Florida and Arizona retirement corridors demonstrating interoperability between insurance frameworks and chronic condition management ecosystems.
For Market Incumbents: Pre-empt subscription platform consolidation by acquiring direct-to-patient fulfillment capabilities before Medicare Advantage benefit expansion locks in channel control. Defend hospital discharge protocol integration against emerging clinical nutrition entrants through backward integration into condition-specific formulation R&D. Prioritize liposomal encapsulation capacity expansion in German manufacturing clusters to capture dysphagia-format premiums before contract manufacturers scale competing texture-modified production lines.
For New Entrants and Emerging Players: Build out white-space positioning in liquid format dysphagia solutions where 40-60% price premiums and limited formulation competition create protected margin pools. Target nursing home procurement consolidation in Germany and Japan where tender specifications favor specialized delivery systems over commodity tablet suppliers. Establish go-to-market presence through pharmacist education programs that mirror Haleon PLC's European retail recommendation network architecture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers holding liposomal encapsulation and precision fermentation capabilities that pharmaceutical-grade players will need for bioavailability differentiation. Long-term viability hinges on regulatory substantiation moats for FOSHU-equivalent positioning across multiple geographies. Monitor EFSA Article 13.5 rejection rates as inflection indicator for whether novel ingredient innovators can access European market expansion or face permanent blocking.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Protein Isolate Supply | Glanbia plc's captive production secures margin control for senior-focused formulations against raw material volatility. |
| Pharmacist-Driven Recommendation Network Consolidation | Haleon PLC's European Apotheken channel access creates prescription-adjacent dispensing barriers for retail entrants. |
| Liposomal Encapsulation Capacity Expansion | German precision fermentation clusters capture dysphagia-format premiums through particle size distribution specialization. |
| Direct-to-Patient Subscription Platform Development | Medicare Advantage pilot programs in Florida and Arizona retirement corridors reshape chronic condition replenishment economics. |
| FOSHU-Certified Formulation Substantiation Investment | Japan's reimbursement-adjacent premium tier pulls R&D toward clinically validated cognitive and mobility claims. |
Research Methodology
Desk research of FDA cGMP inspection records, EFSA health claim authorization databases, and Japanese MHLW FOSHU registration filings preceded structured interviews with clinical nutrition directors, nursing home procurement managers, retail pharmacy category buyers, and regulatory affairs leads at supplement manufacturers. Secondary validation drew from USP verification program documentation, hospital discharge protocol surveys, and Medicare Advantage supplemental benefit pilot disclosures. Bottom-up volume modeling across product type, delivery mode, and end user segments was cross-referenced against top-down expenditure analysis from statutory health insurance partial coverage data and private pay subscription trends.
Assumptions held regulatory divergence between FDA, EFSA, and Japan MHLW standards constant across the projection horizon, while allowing for variable penetration rates of liposomal encapsulation and precision fermentation platform adoption. Segmentation dimensions modeled included formulation chemistry, administration practicality, care setting infrastructure, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating aging demographic trajectories and reimbursement framework evolution. Industry-specific inputs encompassed geriatric clinical trial completion rates and cold-chain logistics cost structures for probiotic distribution.
Sensitivities concentrate around EFSA substantiation standard tightening, Peruvian anchovy quota volatility, and Medicare Advantage benefit expansion scope. Forecasts reflect documented assumptions regarding institutional procurement consolidation velocity and direct-to-patient channel shift acceleration. Cross-checking against Japanese FOSHU registration approval timelines and German Apotheken reimbursement rate negotiations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
North America Beta-Glucan Market
Nutritional Supplements
Omega 3 Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Elderberry Extract Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Weight Loss Supplements Market
Nutritional Supplements
Oyster Shell Calcium Market
Nutritional Supplements
Multivitamin and Mineral Supplements Market
Nutritional Supplements
Personalized Nutrition and Supplements Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Policosanol Market