
 Vitamin D Supplements Market | 2026-2036
Vitamin D Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin D Supplements Market Analytics
The EU Green Deal's nutrition-labelling harmonization is pivoting European manufacturers toward cleaner formulation certificates. DSM Firmenich AG leverages its backward integration into algae-derived D3 precursors to secure supply continuity. Nestle S.A. anchors its pediatric portfolio through pharmacy-exclusive dosing formats. Nordic Naturals differentiates via third-party purity certifications that sustain premium shelf positioning.
Vitamin D supplements are exogenous cholecalciferol or ergocalciferol preparations, typically standardized between 400 IU and 10,000 IU per unit, manufactured through UVB irradiation of 7-dehydrocholesterol or solvent extraction from lichen biomass, primarily consumed to correct hypovitaminosis D and support calcium homeostasis. The gummies sub-segment leads growth among adult and senior users seeking palatability-driven compliance, while liquid drops dominate infant and pediatric applications where dose titration matters. Synthetic formulation still occupies the largest volume share, though organic-certified variants are carving margin pools in specialty health stores.
The FDA oversees dietary supplement cGMP compliance and adverse event reporting, while the EMA coordinates pharmacovigilance for prescription-strength vitamin D across member states; India's FSSAI enforces label-claim verification for imported and domestic products alike. These frameworks elevate compliance costs but also filter out substandard entrants, tightening quality-based competition. Stakeholders must monitor evolving upper-limit debates at Codex Alimentarius and WHO levels, as downward revisions would force immediate portfolio restructuring across dosage tiers.
Market Dynamics
Senior nutrition programs and institutional procurement channels are restructuring volume flows away from retail pharmacy toward healthcare system contracts, compressing traditional margin structures while opening bulk-format opportunities.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Tightening substantiation requirements for immune health positioning is filtering out unsubstantiated competitors and rewarding clinical-trial-backed portfolios with shelf access.
- Algae-derived D3 precursor technology:Backward integration into plant-based cholecalciferol sources is securing supply continuity for manufacturers facing animal-derived raw material volatility.
- Direct-to-consumer wellness platforms:Subscription-based replenishment models in the United States are capturing recurring revenue streams and reducing customer acquisition costs through habit-formation algorithms.
Market Restraints
- Lichen biomass supply concentration:Organic-certified D3 sourcing depends on limited Nordic and North American harvest zones, exposing pricing to climate-induced yield fluctuations.
- Upper-limit debates at Codex Alimentarius:Pending WHO-level downward revisions to daily intake thresholds would force immediate portfolio restructuring across 5,000 IU and 10,000 IU dosage tiers.
- Synthetic formulation commoditization:Standardized 400-1,000 IU tablets face margin erosion from private-label entrants with identical USP-grade specifications.
Strategic Opportunities
- Pediatric liquid drop formats:Pharmacy-exclusive dosing partnerships with neonatal care networks offer protected channels against mass-market gummy competition.
- Third-party purity certification convergence:NSF International and USP Verified co-certification is creating premium shelf positioning that commands 40-60% price separation from uncertified alternatives.
- India FSSAI import verification alignment:Early compliance with label-claim verification protocols opens access to a 1.4 billion population market with rising hypovitaminosis D prevalence.
Industry Challenges
- cGMP adverse event reporting systems:FDA-mandated post-market surveillance infrastructure requires dedicated pharmacovigilance teams that strain mid-tier manufacturer operating budgets.
- EMA pharmacovigilance coordination:Prescription-strength vitamin D tracking across 27 member states demands multilingual case processing capabilities that delay market entry timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin D Supplements Market |
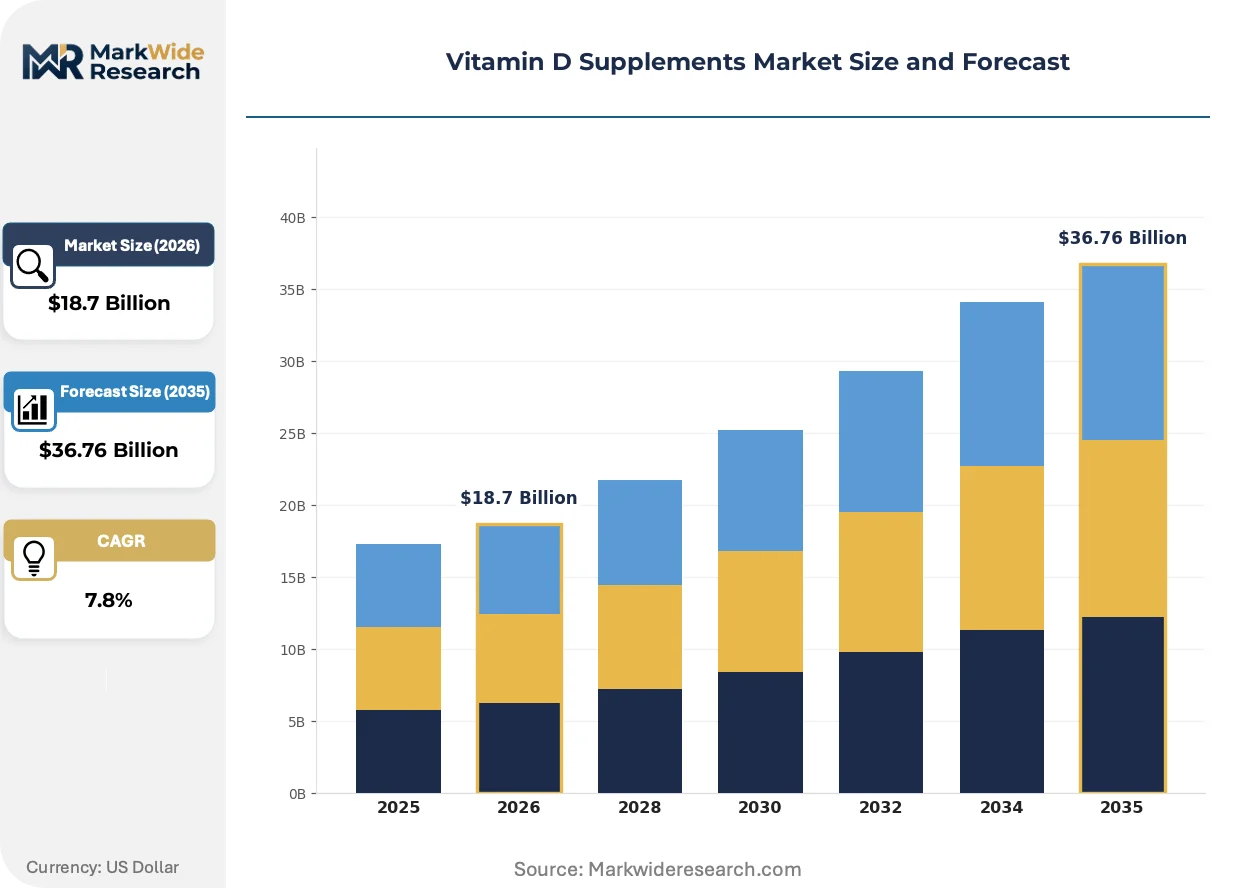
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Liquid Drops, Gummies Formulation: Synthetic, Natural, Organic, Fortified Distribution Channel: Health Stores, Online Retail, Pharmacies, Supermarkets End User: Adults, Children, Athletes, Seniors |
| Companies Covered | Nestle S.A., Haleon plc, NOW Foods, Amway Corporation, Herbalife Nutrition Ltd., Nordic Naturals, Bayer AG, Pharmavite LLC, DSM Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin D Supplements Market Evolving Landscape
Formulation science and verification protocols are bifurcating the competitive landscape into certified-premium and commodity-standard tiers, with palatability engineering emerging as the decisive compliance driver across age demographics.
Liposomal encapsulation technology for enhanced bioavailability is electrifying absorption-rate claims in the high-potency segment. Athletes and bariatric surgery patients are adopting these formats at three times the rate of standard oil-based softgels. This delivery innovation is compressing the efficacy gap between prescription and dietary supplement classifications.
EMA's tightened pharmacovigilance requirements for prescription-strength vitamin D are extending batch-record retention mandates to ten years. Manufacturers serving hospital and long-term care channels are consolidating quality management systems to avoid audit failures. Pediatric and geriatric dosage forms face the steepest compliance cost increases under these protocols.
Subscription-based replenishment models are displacing pharmacy impulse purchases among chronic-condition patients. Direct-to-consumer platforms capture two-thirds of new customer acquisitions in the United States through personalized dosing algorithms. This channel shift is most visible among millennials managing osteoporosis prevention and post-COVID fatigue protocols.
Vitamin D Supplements Market Segmentation
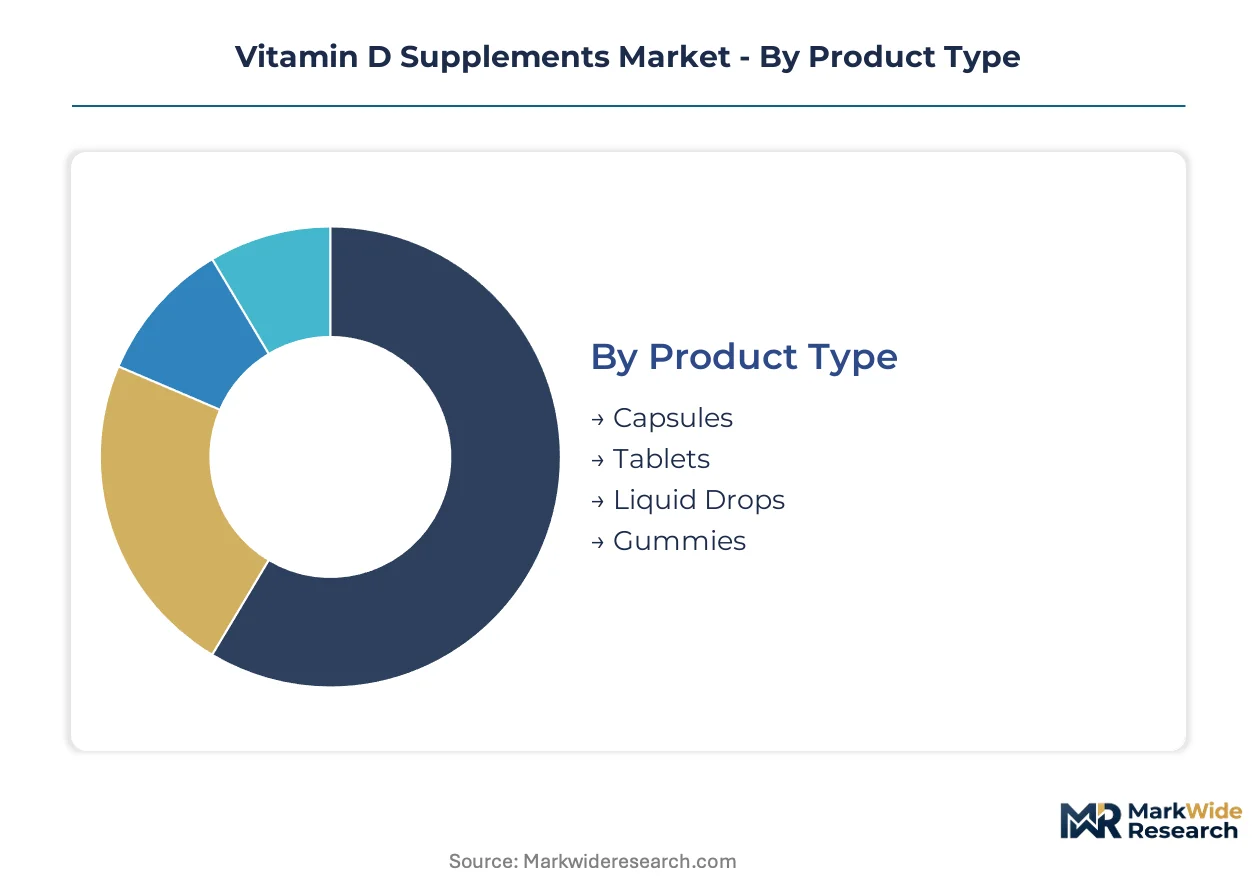
Vitamin D supplements fragment across four distinct category axes, each commanding divergent margin profiles and regulatory exposure. Product format and end-user demographics drive the steepest pricing stratification, while formulation sourcing determines supply security and certification burden.
Product Type:
Upgrade cycles in adult and senior compliance favor palatability innovations over legacy tablet formats, compressing traditional pharmacy shelf space while expanding direct-to-consumer replenishment channels.
- Gummies:Chewable gelatin or pectin matrices deliver 400-2,000 IU doses with flavor masking that sustains adherence among taste-sensitive adults and seniors. United States wellness platforms capture recurring subscriptions through habit-formation algorithms that displace pharmacy impulse purchases. Palatability engineering here commands 25-35% price premiums over equivalent-strength tablets.
- Liquid Drops:Oil-based suspensions enable precise dose titration from 400 IU to 10,000 IU per drop, critical for infant and pediatric applications where weight-adjusted dosing prevents toxicity. Neonatal care networks in Germany and France mandate pharmacy-exclusive distribution for preterm infant protocols. This format's bioavailability claims attract bariatric surgery patients with malabsorption conditions.
- Capsules:Gelatin or vegetable cellulose shells encasing oil-based cholecalciferol suspensions, standardized for 1,000-5,000 IU potencies. Sports nutrition brands favor this format for stackability with omega-3 and K2 combinations.
- Tablets:Compressed excipient matrices with USP-grade cholecalciferol, dominant in institutional procurement and senior nutrition program contracts where cost-per-unit drives selection. Private-label commoditization erodes branded margins in this segment.
Tablets sit at the top of the volume ranking, with gummies climbing the fastest.
Formulation:
Raw material sourcing tiers separate certified-premium positioning from commodity-standard competition, with algae-derived and lichen-extracted variants capturing specialty health store placement.
- Synthetic:UVB-irradiated 7-dehydrocholesterol from lanolin or pharmaceutical-grade chemical synthesis, supplying standardized potencies at lowest unit cost. This formulation occupies the largest volume share across mass-market channels, though identical USP specifications trigger margin compression from private-label entrants.
- Organic:Lichen biomass extraction from Nordic and North American harvest zones, certified to USDA Organic or EU Organic standards. Limited supply concentration exposes pricing to climate-induced yield fluctuations, restricting availability to premium specialty channels.
- Natural:Fish liver oil-derived cholecalciferol, historically standard before algae alternatives displaced marine sourcing for vegan positioning. Remains relevant in cod liver oil traditional markets.
- Fortified:Vitamin D admixture into carrier substrates like calcium carbonate or multivitamin matrices, common in combination products targeting bone health positioning.
Synthetic formulations dominate absolute volume, with organic variants gaining share fastest in specialty retail.
Distribution Channel:
Channel migration from brick-and-mortar pharmacy toward subscription-based wellness platforms restructures customer acquisition economics and inventory velocity.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capture two-thirds of new customer acquisitions in the United States through personalized dosing algorithms and replenishment subscriptions. Habit-formation data reduces churn and compresses customer lifetime value recovery timelines.
- Pharmacies:Brick-and-mortar and digital pharmacy networks retain dominance for prescription-strength vitamin D and pediatric liquid drops, with EMA pharmacovigilance requirements extending batch-record retention mandates to ten years for hospital channel suppliers.
- Health Stores:Specialty retailers emphasizing third-party purity certifications—NSF International, USP Verified, Informed Sport—create 40-60% price separation from uncertified alternatives through educated consumer self-selection.
- Supermarkets:Mass-market grocery placement for commoditized 400-1,000 IU tablets, where private-label penetration is highest and shelf space rotates on promotional funding depth.
Pharmacies retain the top volume position, with online retail expanding most quickly.
End User:
Demographic-specific dosing requirements and compliance drivers fragment product development priorities across life stages and activity levels.
- Seniors:Adults over 65 with elevated hypovitaminosis D prevalence and institutional procurement access through Medicare Advantage nutrition programs. Bulk-format contracts compress margins while securing volume stability.
- Adults:Working-age consumers managing osteoporosis prevention and post-COVID fatigue protocols through self-directed supplementation, dominant in direct-to-consumer channel economics.
- Children:Pediatric populations requiring weight-adjusted liquid drop dosing, with pharmacy-exclusive formats protecting against mass-market gummy competition through healthcare professional recommendation channels.
- Athletes:Competitive and recreational athletes adopting liposomal encapsulation formats at three times standard softgel rates for absorption-rate claims supporting training recovery positioning.
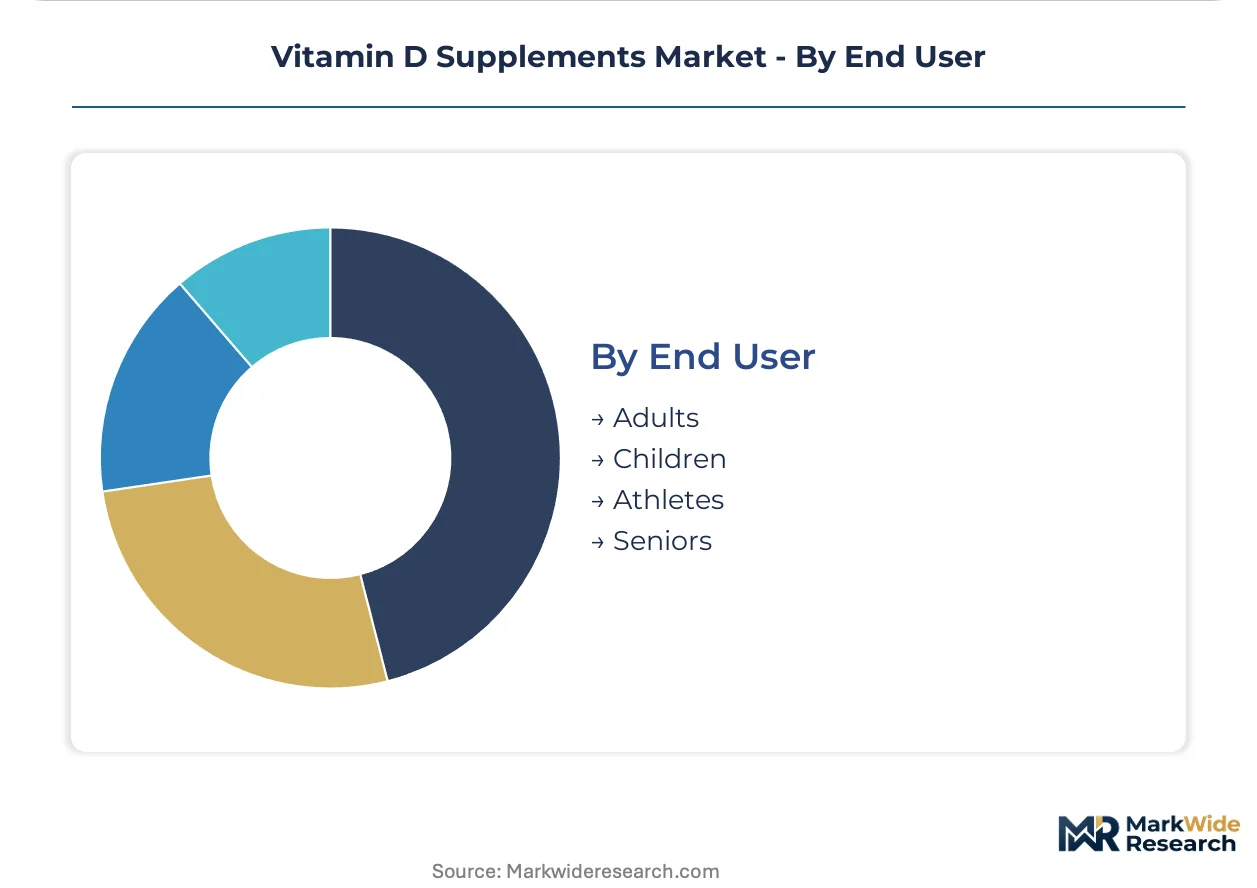
Adults represent the largest addressable population, with seniors showing the steepest expansion trajectory through institutional channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nutrition scientists and clinical research specialists concentrate in metropolitan clusters across five countries where vitamin D supplementation protocols drive institutional procurement and direct-to-consumer platform development.
United States
Direct-to-consumer wellness platforms headquartered in San Francisco and New York capture two-thirds of new customer acquisitions through subscription-based replenishment models. FDA cGMP compliance mandates elevate post-market surveillance infrastructure costs for domestic manufacturers. The Research Triangle Park cluster in North Carolina anchors clinical trial operations for immune health substantiation studies.
Germany
Neonatal care networks in Berlin and Munich mandate pharmacy-exclusive distribution for preterm infant liquid drop protocols. EMA pharmacovigilance coordination extends batch-record retention mandates to ten years for hospital channel suppliers. The Baden-Württemberg region concentrates algae-derived D3 precursor research facilities serving European organic certification demand.
India
FSSAI label-claim verification protocols for imported and domestic products filter substandard entrants from the 1.4 billion population market. Mumbai and Hyderabad host quality control laboratories aligned with international pharmacopoeia standards. Rising hypovitaminosis D prevalence in northern states drives institutional screening program adoption.
China
Synthetic vitamin D3 manufacturing clusters in Zhejiang and Jiangsu provinces supply standardized potencies at lowest unit cost for export markets. NMPA oversight of dietary supplement cGMP compliance parallels FDA frameworks for adverse event reporting. Shanghai-based e-commerce platforms distribute fortified multivitamin matrices targeting bone health positioning.
United Kingdom
Pharmacy networks in London and Manchester retain dominance for prescription-strength vitamin D tracking under MHRA coordination with EMA protocols. The Cambridge biotech corridor hosts absorption-rate research facilities developing liposomal encapsulation formats. Public health guidance on winter supplementation sustains mass-market tablet volume through National Health Service procurement channels.
Vitamin D Supplements Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation tiers where backward integration into raw material sourcing separates supply-secure players from margin-compressed assemblers. The vendor base clusters around three strategic archetypes: multinational nutrition conglomerates with captive algae cultivation, mid-tier contract manufacturers serving private-label pharmacy chains, and direct-to-consumer specialists leveraging purity certification premiums. Consolidation pressure intensifies as EMA pharmacovigilance mandates and FDA cGMP compliance costs strain independent operators. Dominant competitive moves include portfolio diversification into pediatric liquid formats and strategic partnerships with neonatal care networks.
Within the multinational conglomerate tier, DSM Firmenich AG and Nestle S.A. exemplify supply-secure positioning through captive precursor technology and pharmacy-exclusive distribution channels respectively. Nordic Naturals occupies a specialist position anchored in third-party purity certification convergence. These three entities represent divergent strategic bets: backward integration into plant-based raw materials, institutional channel capture through healthcare professional recommendation networks, and premium shelf positioning via NSF International and USP Verified co-certification.
| Leading Market Players |
|---|
| Nestle S.A. |
| Haleon plc |
| NOW Foods |
| Amway Corporation |
| Herbalife Nutrition Ltd. |
| Nordic Naturals |
| Bayer AG |
| Pharmavite LLC |
| DSM Firmenich AG |
| Others |
Value Network & Pricing Analysis
Algae-derived D3 precursor costs cascade through three distinct pricing tiers, starting with captive cultivation in Baden-Württemberg research facilities and ending at pharmacy-exclusive liquid drop formats commanding 40-60% premiums over uncertified alternatives. Raw material volatility in lichen biomass harvest zones compresses margins for organic-certified entrants while synthetic formulation producers absorb price erosion through scale economies in Zhejiang manufacturing clusters.
Pricing Analysis
Subscription bundling versus per-unit transactional splits separate recurring-revenue wellness platforms from impulse-driven pharmacy purchases. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence, with NSF International and USP Verified co-certification sustaining price separation. Cost compression in synthetic tablets intensifies because private-label entrants match USP specifications at lower brand premiums. Institutional procurement buyers exhibit highest price sensitivity, while direct-to-consumer subscribers prioritize convenience over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore orchestrate hub-and-spoke patterns for finished supplements reaching pharmacy networks and wellness platforms. Manufacturing concentrates in China, Germany, and the United States, with synthetic D3 production anchored in Zhejiang provinces and algae-derived precursors cultivated in Baden-Württemberg facilities. Supply chains draw from 7-dehydrocholesterol, lichen biomass, and fish liver oil inputs. Single-source vulnerability in Nordic lichen harvest zones threatens organic-certified availability. Distribution runs through direct-to-consumer platforms capturing two-thirds of new United States acquisitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
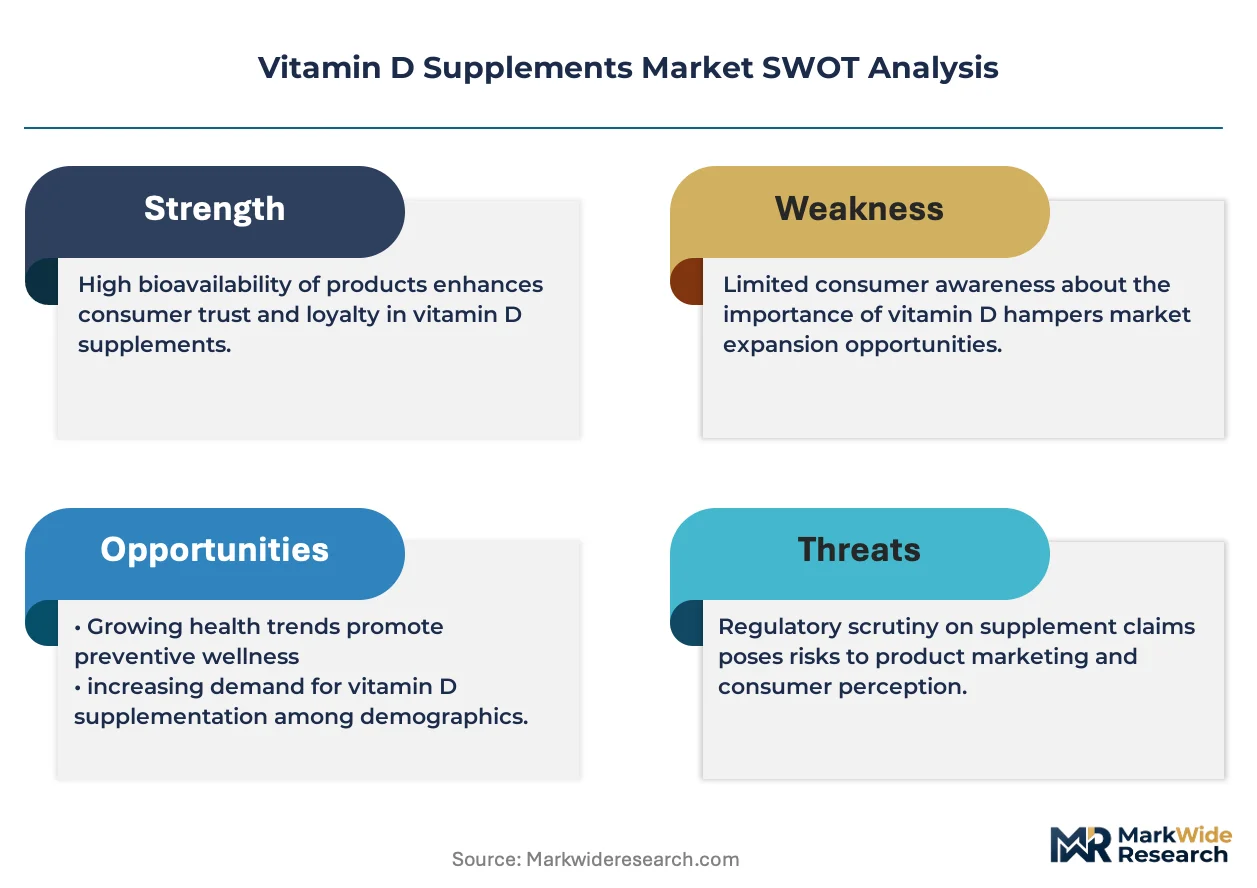
The EU Nutrition and Health Claims Regulation operates as a regulatory compounder, with tightened immune health substantiation requirements filtering unsubstantiated competitors and rewarding clinical-trial-backed portfolios with protected shelf access.
For Market Incumbents: Lock in supply continuity through backward integration into algae-derived D3 precursors, mirroring DSM Firmenich AG's captive cultivation model. Secure pharmacy-exclusive distribution partnerships with neonatal care networks to defend against mass-market gummy competition. EMA pharmacovigilance cost escalation threatens mid-tier operators lacking dedicated quality management infrastructure. For New Entrants and Emerging Players: Capture white-space in India FSSAI-aligned label-claim verification, where early compliance opens access to 1.4 billion population markets with rising hypovitaminosis D prevalence. Target pediatric liquid drop formats protected by healthcare professional recommendation channels against commoditized gummy segments. Deploy direct-to-consumer subscription models with personalized dosing algorithms to reduce customer acquisition costs. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA pharmacovigilance mandates and FDA cGMP compliance costs strain independent operators lacking ten-year batch-record retention capabilities. Long-term viability favors asset-light designers with purity certification premiums over capital-heavy assemblers facing synthetic formulation commoditization. Watch for Codex Alimentarius upper-limit revisions as inflection indicator forcing immediate 5,000 IU and 10,000 IU portfolio restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algae-Derived Precursors | DSM Firmenich AG's captive cultivation secures supply continuity against lanolin price volatility. |
| Pharmacy-Exclusive Distribution Partnerships | Nestle S.A.'s neonatal care network access protects pediatric liquid formats from mass-market erosion. |
| Third-Party Purity Certification Convergence | Nordic Naturals' NSF International and USP Verified co-certification commands premium shelf positioning. |
| Direct-to-Consumer Platform Launch | Subscription algorithms capture recurring revenue and displace pharmacy impulse purchases. |
| India FSSAI Compliance Alignment | Early label-claim verification opens institutional screening program procurement channels. |
Research Methodology
Direct dialogue with regulatory affairs leads at EMA and FDA, quality control directors at algae cultivation facilities, pharmacy procurement managers in German neonatal networks, and direct-to-consumer platform operators grounded qualitative findings. Secondary validation drew from FDA cGMP guidance documents, EMA pharmacovigilance protocols, FSSAI label-claim regulations, and ClinicalTrials.gov immune health substantiation studies. Bottom-up demand modeling triangulated against top-down market sizing across formulation, format, and channel dimensions.
Segment-level projections across gummies, liquid drops, capsules, and tablets combined with synthetic, organic, natural, and fortified formulation splits generated volume and value trajectories over the projection horizon. CAGRs emerged from regression analysis against historical adoption curves in senior nutrition programs and direct-to-consumer subscription penetration. Forecast inputs incorporated EMA batch-record retention cost escalations and Codex Alimentarius upper-limit debate probabilities.
Regulatory revision at WHO level, climate-induced lichen yield fluctuation, and synthetic raw material price volatility are the dominant revision risks warranting scenario sensitivity testing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
US Ketones Market
Nutritional Supplements
Lutein Market
Nutritional Supplements
Pulse Products Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Ketogenic Diet Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
South America Whey Protein Market
Nutritional Supplements
United States Botanical Supplements Market
Nutritional Supplements
Chewable Energy Tablet Market
Nutritional Supplements
Global Elderly Nutrition Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Omega-3 Concentrates Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Liquid Dietary Supplements Market