
 Algae Omega Market | 2026-2036
Algae Omega Market Size, Share, and Industry Trends Forecast 2026-2036
Algae Omega Market Outlook
Photobioreactor automation is tilting cost curves toward continuous cultivation systems that outpace open-pond economics. DSM Firmenich leverages its integrated nutrition platform to control pharmaceutical-grade omega-3 supply chains from strain to softgel. Corbion N.V. anchors European algal lipid production through proprietary fermentation assets in the Netherlands. Cargill competes on feedstock scale, extending its agricultural commodity infrastructure into refined algal oil distribution.
Algae omega denotes long-chain polyunsaturated fatty acids—principally DHA and EPA—extracted from photosynthetic or heterotrophic microalgae through cold-press or solvent-free supercritical CO2 methods, serving as plant-based alternatives to fish-derived lipids in human nutrition and clinical therapeutics. The application dimension shows dietary ingredients commanding margin pools due to pharmaceutical encapsulation standards, while food supplements dominate volume through direct-to-consumer channels. Source-based segmentation reveals Schizochytrium strains leading industrial output for their high DHA titers, with spirulina occupying a niche in premium vegan positioning.
FDA GRAS determinations and EFSA novel food opinions shape product access timelines for new algal strains entering European and American formulations. REACH registration requirements and EU Green Deal bioeconomy targets are redirecting capital toward domestic algae cultivation rather than imported fish oil refining. Stakeholders must monitor CRISPR regulatory classification decisions across FDA and EMA jurisdictions, as gene-edited strain approvals will determine which producers capture next-generation cost advantages.
Market Dynamics
CRISPR-edited Schizochytrium strains are compressing unit economics for DHA production, forcing incumbent fermentation operators to retool or exit as photobioreactor automation tilts cost curves toward continuous cultivation.
Growth Catalysts
- FDA GRAS pathway expansion:Broader novel food approvals for algal lipids in infant formula are unlocking procurement commitments from North American nutrition manufacturers seeking fish-free DHA sources.
- EU Green Deal bioeconomy targets:Capital subsidies for domestic algae cultivation are redirecting investment from imported fish oil refining toward Netherlands-based fermentation assets.
- Supercritical CO2 extraction:Solvent-free processing methods are qualifying algal oils for pharmaceutical encapsulation standards previously reserved for refined fish derivatives.
Market Restraints
- Feedstock cost volatility:Glucose and nitrogen source prices for heterotrophic fermentation fluctuate with agricultural commodity cycles, compressing margins for non-integrated producers.
- Strain IP concentration:Proprietary CRISPR-edited Schizochytrium lines remain concentrated among a handful of biotechnology licensors, creating supply vulnerability for second-tier manufacturers.
- REACH registration timelines:ECHA novel substance approvals for new algal strains extend market entry timelines by 18-36 months, freezing capital deployment.
Strategic Opportunities
- Clinical therapeutics penetration:Pharmaceutical-grade algal EPA formulations for cardiovascular indications represent an underexploited white space beyond dietary supplements.
- California biotech corridor expansion:Proximity to formulation R&D hubs enables integrated producers to capture value from strain development through softgel finishing.
- Direct-to-consumer channel maturation:Subscription-based algae omega platforms are disintermediating traditional supplement retail, capturing margin pools previously absorbed by distributors.
Industry Challenges
- Phycologist talent scarcity:Specialized strain optimization expertise for CRISPR-edited microalgae outstrips academic pipeline output, inflating compensation for qualified fermentation scientists.
- Photobioreactor capex intensity:Continuous cultivation systems require $50-80 million facility investments before achieving cost parity with open-pond economics, constraining new entrant participation.
- Cross-jurisdictional CRISPR classification:Divergent FDA and EMA regulatory frameworks for gene-edited organisms force dual-track approval strategies, duplicating compliance expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algae Omega Market |
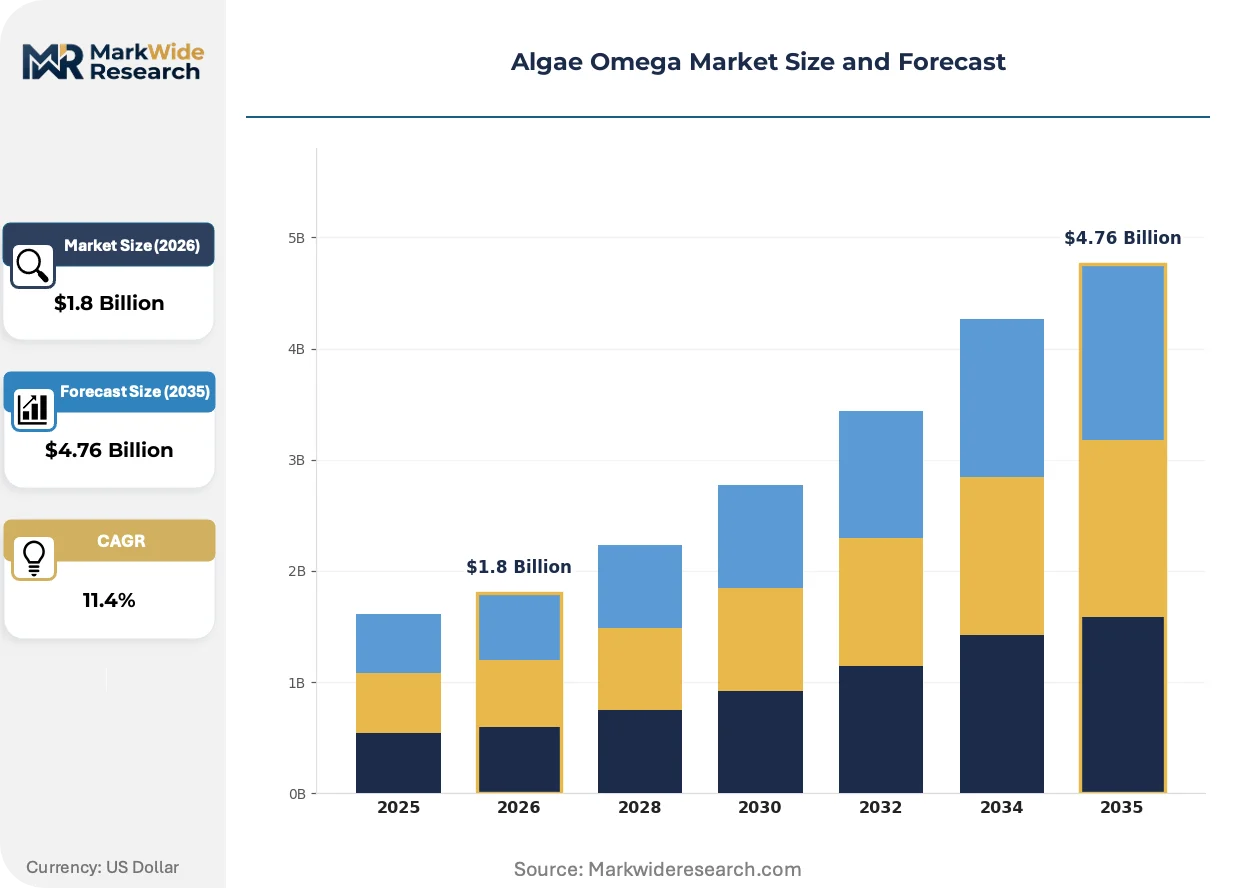
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algal Oil, Powder, Capsules, Softgels Application: Food Supplement, Dietary Ingredient, Cosmetics, Pharmaceuticals Source: Spirulina, Chlorella, Schizochytrium, Other End User: Athletes, Health-Conscious Consumers, Vegans, Children |
| Companies Covered | DSM Firmenich, Corbion N.V., BASF SE, Archer Daniels Midland Company, Cargill, Polaris Nutritional Lipids, Nordic Naturals, Cyanotech Corporation, Qualitas Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algae Omega Market Strategic Shifts
Bioprocess engineering advances are collapsing the historical trade-off between yield purity and production scale, enabling pharmaceutical-grade output from systems previously confined to commodity volumes.
Heterotrophic fermentation infrastructure is migrating from batch-fed tank systems toward continuous perfusion bioreactors with real-time metabolite monitoring. Infant formula manufacturers in the Netherlands and California are qualifying these outputs for DHA fortification at tonnage scales previously achievable only through open-pond cultivation. The structural consequence is a compression of minimum efficient scale, allowing mid-cap entrants to achieve cost parity with legacy fermentation operators.
EMA's evolving stance on novel food approvals for CRISPR-edited microalgae is accelerating strain registration timelines for producers with pre-submission engagement records. Industrial consequence includes faster market entry for DHA-optimized Schizochytrium lines relative to first-generation transgenic approvals. Dietary supplement brands with European distribution exposure are prioritizing suppliers with established EFSA novel food opinions over those with pending dossiers.
Buyer concentration among infant formula manufacturers is forcing ingredient suppliers toward outcome-guaranteed supply contracts with embedded purity specifications. Direct purchasing agreements are displacing traditional distributor intermediaries in North American and European procurement channels. California-based biotech clusters exhibit the most pronounced channel compression, with integrated producers capturing formulation partnerships previously mediated by ingredient traders.
Algae Omega Market Segmentation
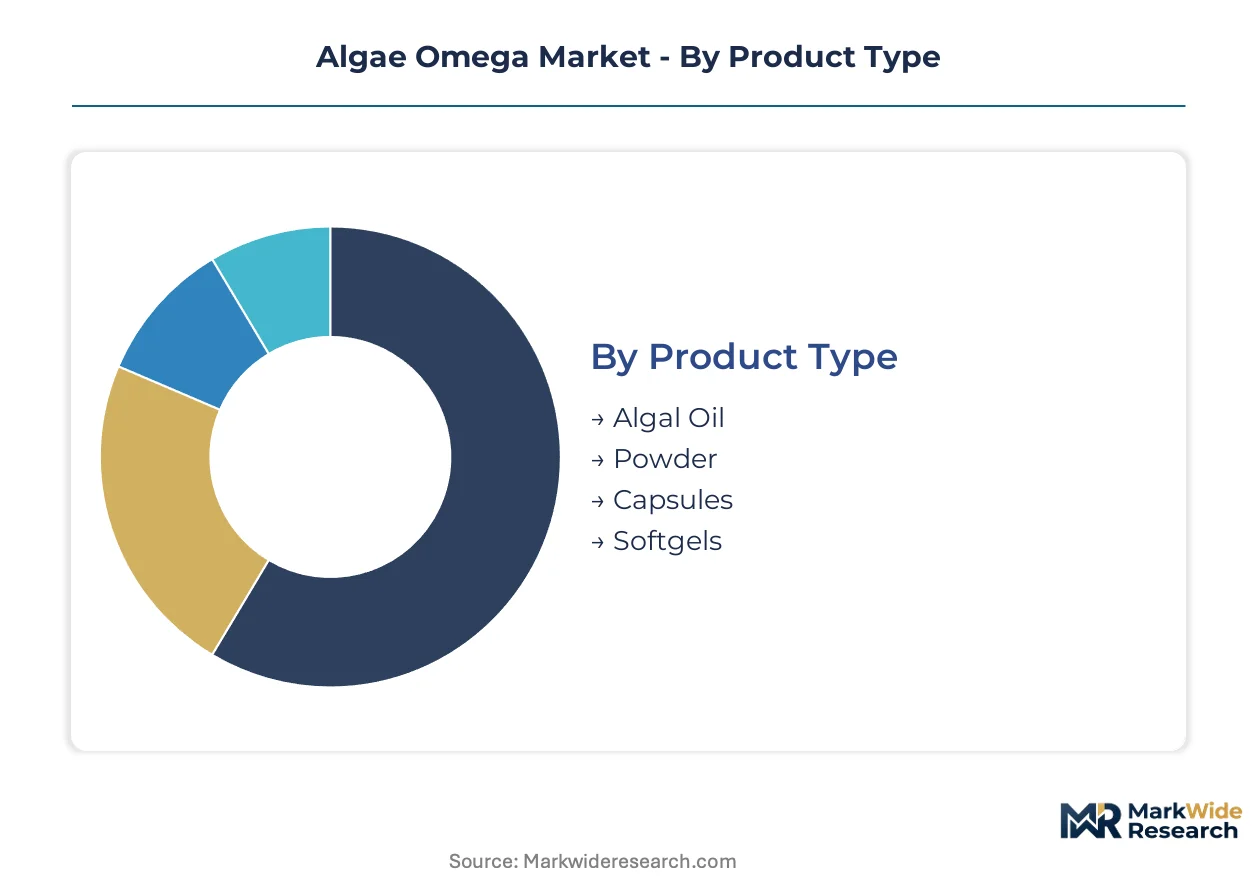
Segmentation in algae omega reveals divergent margin structures across delivery formats and customer cohorts. Product form dictates extraction investment and shelf-stability requirements, while end-user psychology separates premium positioning from commodity volume plays.
Product Type:
Inventory velocity varies dramatically across delivery formats, with bulk algal oil turning every 14-21 days for infant formula manufacturers while finished softgels sit 60-90 days in supplement retail channels.
- Algal Oil:Crude or refined lipid extracts with DHA concentrations ranging from 35% to 50% by weight. California biotech corridors and Netherlands fermentation hubs concentrate procurement for this feedstock grade, driven by infant formula manufacturers seeking GRAS-qualified DHA sources for North American product launches.
- Softgels:Encapsulated oil in gelatin or plant-based shells with oxidation protection via nitrogen flushing and amber packaging. Pharmaceutical-grade softgel demand clusters in direct-to-consumer subscription channels where unit economics favor premium positioning over mass retail.
- Powder:Spray-dried or microencapsulated lipid matrices for dry blend applications.
- Capsules:Two-piece hard shells filled with oil or powder, common in European pharmacy distribution.
Algal oil anchors the volume base while softgels gain share at the steepest rate.
Application:
Cost tier separation runs deepest in this dimension, with pharmaceutical encapsulation commanding 4-6x the per-kilogram realization of commodity food supplements.
- Dietary Ingredient:Bulk lipids supplied to finished product manufacturers under pharmaceutical-grade specifications including heavy metal limits below 0.1 ppm and peroxide values under 5 meq O2/kg. DSM Firmenich and Corbion N.V. concentrate supply contracts in this tier, serving European and North American encapsulation houses with REACH-registered material.
- Food Supplement:Direct-to-consumer omega-3 products positioned against fish oil alternatives. Amazon and specialized subscription platforms concentrate volume here, with California-based brands capturing margin through algae-origin storytelling and vegan certification.
- Pharmaceuticals:EPA and DHA formulations under drug master file submissions for cardiovascular indications.
- Cosmetics:Topical omega-3 applications in premium skincare with oxidative stability challenges.
Dietary ingredient captures the margin pool while food supplement delivers the tonnage.
Source:
Strain maturity determines supply security, with first-generation spirulina cultivation offering proven scalability against CRISPR-edited lines still navigating regulatory classification.
- Schizochytrium:Heterotrophic marine microalgae engineered for DHA titers exceeding 40% of dry cell weight through glucose-fed fermentation. Netherlands-based fermentation assets and California biotech clusters concentrate industrial output, with EFSA novel food opinions and FDA GRAS notifications determining market access timelines for new strain iterations.
- Spirulina:Photosynthetic cyanobacteria cultivated in open ponds or photobioreactors with lower DHA content but established organic certification pathways. Premium vegan positioning in European and North American natural products channels sustains demand despite inferior omega-3 potency.
- Chlorella:Single-celled green algae with EPA-rich lipid profiles.
- Other:Emerging strains including Nannochloropsis and genetically modified lines pending regulatory clearance.
Schizochytrium dominates commercial supply while spirulina retains positioning power in certified organic segments.
End User:
Customer lifetime value spreads widest here, with pediatric applications locking in 24-36 month purchase cycles against athlete segments with 90-day brand switching patterns.
- Children:Infant formula and early childhood nutrition applications where DHA fortification has become standard in North American and European products. FDA GRAS expansion for algal DHA in infant foods has accelerated procurement commitments from manufacturers seeking fish-free supply chains.
- Vegans:Consumers excluding animal-derived lipids on ethical grounds, concentrated in urban coastal markets of California, Oregon, and the Netherlands. Algae omega commands 30-50% price premiums over equivalent fish oil products in this cohort.
- Athletes:Performance-oriented consumers seeking anti-inflammatory omega-3 supplementation.
- Health-Conscious Consumers:General wellness buyers without dietary restrictions.
Children anchor long-term contract value while vegans drive fastest adoption of premium-positioned products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in algae omega tilt toward production-heavy jurisdictions with fermentation infrastructure and regulatory clearance advantages. The United States and the Netherlands run structural surpluses in refined algal lipids, while import-dependent markets concentrate in regions lacking heterotrophic fermentation scale.
United States
FDA GRAS notifications for Schizochytrium-derived DHA have unlocked procurement commitments from infant formula manufacturers seeking fish-free supply chains. The FDA's expanded novel food pathway accelerates strain approval timelines relative to European counterparts. California's biotech corridor anchors domestic production, with integrated producers capturing formulation partnerships from strain development through softgel finishing.
Netherlands
EU Green Deal bioeconomy subsidies redirect capital toward domestic algae cultivation and away from imported fish oil refining. EFSA novel food opinions for algal lipids determine market access timelines for new strain iterations. Rotterdam and Groningen fermentation clusters concentrate pharmaceutical-grade output, with Corbion N.V. anchoring European supply through proprietary assets.
China
SAMR novel food registrations for algal DHA lag FDA and EFSA timelines, compressing market entry windows for foreign suppliers. The country's dual carbon goals incentivize domestic algae cultivation as lower-emission alternatives to fish oil processing. Yangtze River Delta biotech parks host emerging fermentation capacity targeting both domestic infant formula and export markets.
Germany
REACH registration requirements for new algal strains extend market entry timelines, freezing capital deployment for non-integrated producers. ECHA classification decisions on CRISPR-edited organisms shape competitive positioning for strain licensors. Bavaria's industrial biotech corridor concentrates pilot-scale fermentation assets serving pharmaceutical encapsulation houses.
India
FSSAI novel food approvals for algal omega-3 remain underdeveloped relative to mature markets, constraining premium positioning opportunities. The PLI scheme for food processing incentivizes domestic lipid refining infrastructure. Maharashtra and Gujarat pharmaceutical clusters represent nascent demand centers for pharmaceutical-grade algal EPA formulations.
Algae Omega Market Competitive Environment
On the supply side, the industry is consolidating around integrated nutrition platforms with captive strain libraries and fermentation assets. Three archetypes dominate: biotechnology licensors controlling CRISPR-edited Schizochytrium IP, integrated nutrition conglomerates spanning strain to softgel, and agricultural commodity traders extending infrastructure into refined algal oil distribution. Competitive moves concentrate on backward integration into strain development and geographic expansion through EFSA novel food pre-submission strategies.
Within the integrated nutrition tier, DSM Firmenich and Corbion N.V. exemplify platform control from proprietary fermentation through pharmaceutical-grade finishing. Cargill occupies a position at the commodity-scale end, leveraging agricultural supply chain infrastructure into bulk algal oil distribution. These three anchors represent divergent strategic postures: biotechnology depth versus feedstock scale versus formulation integration.
| Leading Market Players |
|---|
| DSM Firmenich |
| Corbion N.V. |
| BASF SE |
| Archer Daniels Midland Company |
| Cargill |
| Polaris Nutritional Lipids |
| Nordic Naturals |
| Cyanotech Corporation |
| Qualitas Health |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp freight corridors transmit glucose and nitrogen source cost volatility directly into DHA algal oil pricing, amplifying margin compression for non-integrated fermentation operators while enabling DSM Firmenich and Corbion N.V. to sustain pharmaceutical-grade premiums through captive supply chains.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with infant formula manufacturers locking in 24-36 month supply agreements at quality-grade premiums tied to FDA GRAS certification tiers. Price differentiation separates REACH-registered pharmaceutical-grade material from commodity food supplement grades, with California biotech corridor proximity commanding delivery cost premiums. Cost compression in standard-tier bulk algal oil is intensifying because glucose feedstock prices fluctuate with agricultural commodity cycles. Contract manufacturers exhibit highest price sensitivity due to thin encapsulation margins, while integrated nutrition platforms with captive fermentation assets demonstrate lowest sensitivity.
Supply Chain Analysis
DSM Firmenich and Corbion N.V. concentrate contract manufacturing capacity for pharmaceutical-grade algal lipids, with Netherlands-based fermentation assets and California biotech clusters anchoring global supply. Geographic supply concentrates in the Netherlands, United States, and China, with Yangtze River Delta biotech parks emerging as secondary capacity. Raw material dependencies center on glucose feedstocks, nitrogen sources, and proprietary CRISPR-edited Schizochytrium seed strains. Single-source vulnerability from concentrated strain IP licensing creates supply risk for second-tier manufacturers. Distribution runs through direct purchasing agreements with infant formula manufacturers, displacing traditional ingredient distributors in North American and European channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in algae omega are tilting toward integrated nutrition conglomerates controlling strain-to-softgel value chains, with interoperability between fermentation output and pharmaceutical encapsulation standards determining which producers capture formulation partnerships.
For Market Incumbents: Entrench proprietary CRISPR-edited strain libraries through accelerated EFSA novel food pre-submission strategies, locking in regulatory moats against emerging biotechnology licensors. Expand captive fermentation capacity in California's biotech corridor to secure proximity advantages with infant formula R&D hubs. Counter feedstock cost volatility threat through backward integration into glucose supply contracts with agricultural commodity traders. For New Entrants and Emerging Players: Establish a beachhead in direct-to-consumer subscription channels where algae-origin storytelling commands 30-50% price premiums over fish oil alternatives among vegan cohorts in California and the Netherlands. Target pharmaceutical-grade EPA formulations for cardiovascular indications as the most penetrable white space beyond saturated DHA dietary supplement markets. Deploy go-to-market angle through Amazon and specialized wellness platforms, bypassing traditional retail distributor margins. For Investors and Strategic Acquirers: Carve-out targets emerge from agricultural commodity traders with underutilized fermentation infrastructure and existing glucose supply chain relationships that could be repurposed for heterotrophic algae cultivation. Long-term viability favors integrated platforms with captive strain development capabilities over pure-play extraction houses. Watch EMA's evolving CRISPR classification decisions as the critical inflection signal determining which strain licensors achieve accelerated market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Pre-Submission | Accelerated strain approval timelines unlock European infant formula procurement commitments before competitors complete REACH registration. |
| Continuous Perfusion Bioreactor Migration | Real-time metabolite monitoring collapses minimum efficient scale, enabling mid-cap entrants to achieve cost parity with legacy batch-fed operators. |
| Direct-to-Consumer Channel Development | Subscription platforms capture margin pools previously absorbed by distributors while building proprietary customer data assets. |
| Pharmaceutical-Grade EPA Drug Master File Submission | Cardiovascular therapeutic indications represent underexploited white space beyond dietary supplement saturation. |
| Backward Integration into Glucose Supply | Captive agricultural commodity contracts insulate fermentation margins from nitrogen source price volatility cycles. |
Study Parameters
The analysis maps Schizochytrium strain development, heterotrophic fermentation infrastructure, pharmaceutical encapsulation standards, and direct-to-consumer distribution channels, each validated through fermentation scientists, infant formula procurement directors, regulatory affairs specialists, and dietary supplement brand managers. Primary interview intelligence triangulates against FDA GRAS notification databases, EFSA novel food opinion registers, ECHA REACH substance dossiers, and SEC filings from integrated nutrition platforms. Bottom-up strain-by-strain capacity modeling reconciles with top-down regional production cluster assessments.
Fixed assumptions include sustained FDA GRAS pathway expansion for algal lipids, continued EU Green Deal bioeconomy subsidy flows, and stable EMA-EMA regulatory divergence on CRISPR-edited organism classification across the analysis window. Segmentation dimensions span product type, application tier, source strain, and end-user psychology. CAGRs derive from installed fermentation capacity utilization curves cross-referenced with infant formula DHA fortification penetration rates and vegan demographic expansion patterns in target geographies.
Stress conditions across glucose feedstock price bands, ECHA approval timeline extensions, and CRISPR regulatory reclassification scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume no catastrophic strain contamination events or fundamental shifts in omega-3 clinical efficacy perception. Quarterly review of FDA GRAS notification velocity, EFSA novel food opinion issuance rates, and infant formula manufacturer procurement tender volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Europe Diet Pills Market
Nutritional Supplements
Arabinogalactan Powder Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Asia-Pacific Digestive Enzymes Market
Nutritional Supplements
Psyllium-Based Supplement Market
Nutritional Supplements
Hangover Cure Products Market
Nutritional Supplements
Choline Supplement Market
Nutritional Supplements
Marine Supplements Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Digestive Enzyme Complex Market
Nutritional Supplements
Lipid Nutrition Market
Nutritional Supplements
Europe Omega-3 Products Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Bone Supplements Market