
 Freshwater Flake Ice Machine Market | 2026-2036
Freshwater Flake Ice Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Freshwater Flake Ice Machine Market Insights
Chinese equipment manufacturing clusters is rebalancing toward higher-capacity flake ice systems for export markets. Focusun leverages vertical integration in compressor sourcing to sustain cost advantages across Asian markets. Hoshizaki anchors premium positioning through precision ice-thickness controls in Japanese food retail. Scotsman Ice Systems competes in North American foodservice channels with modular footprint designs.
Freshwater flake ice machines produce thin, irregular ice fragments through a rotating drum or cylinder evaporator process, typically operating with evaporator temperatures between -20°C and -25°C to achieve rapid surface cooling and minimal freeze-burn on perishable goods. The equipment serves primary industrial purposes in seafood preservation, concrete temperature management, and chemical reaction cooling where maximum surface contact and rapid heat transfer prove critical. Vertical flake ice machines dominate installation counts in land-constrained food processing plants across East Asia, while modular configurations capture margin pools in European supermarkets requiring phased capacity expansion. Thermoelectric cooling segments remain nascent in freshwater applications but attract R&D investment for laboratory and pharmaceutical end uses where vibration-free operation matters.
The EPA regulates refrigerant phase-down timelines under AIM Act provisions, compressing hydrofluorocarbon dependency timelines for equipment sold in the United States. EMA-aligned CE marking requirements under the EU MDR framework shape material contact standards for machines deployed in European food processing facilities. China's GB standards and NMPA food-equipment certifications govern safety and hygiene benchmarks for domestic and export-bound manufacturing. Stakeholders must monitor refrigerant transition pathways and regional certification divergence to preserve market access across major demand centers.
Market Dynamics
Energy-efficiency mandates under the EU F-Gas Regulation are compressing refrigerant choices for equipment manufacturers, forcing rapid transitions to low-GWP alternatives while Southeast Asian seafood processors expand capacity.
Growth Catalysts
- EU F-Gas Regulation:The phasedown schedule for hydrofluorocarbons accelerates equipment replacement cycles across European food processing facilities, creating pull for next-generation systems.
- Seafood processing clusters:Vietnam's Mekong Delta aquaculture zones and Indonesia's tuna processing corridors are scaling flake ice adoption for catch preservation.
- Rotating drum evaporators:Thin, irregular ice fragments achieve rapid surface cooling at -20°C to -25°C, minimizing freeze-burn on perishable goods in high-value applications.
Market Restraints
- Refrigerant input cost volatility:Transition to R-290 and CO₂ systems requires compressor redesigns and raises manufacturing complexity for mid-tier producers.
- Supply concentration in Chinese manufacturing:Equipment production clusters around Jiangsu and Zhejiang provinces create geographic dependency risk for export markets.
- Technical limitation in thermoelectric cooling:Low coefficient of performance restricts freshwater flake ice applications to laboratory and pharmaceutical niches.
Strategic Opportunities
- Underpenetrated Indian cold chain:FSSAI hygiene mandates and PLI scheme incentives for food processing infrastructure create white space for modular flake ice deployments.
- Concrete temperature management:Infrastructure projects in tropical climates require on-site ice production for batch cooling, extending addressable demand beyond food.
- EU MDR material contact standards:CE marking requirements for food-equipment certification favor stainless steel evaporator designs with documented surface compliance.
Industry Challenges
- Refrigerant technician skill gap:Safe handling of flammable A3-class refrigerants requires certified installation and maintenance workforces that remain scarce outside major urban centers.
- Legacy system integration friction:Phased capacity expansion in European supermarkets demands backward compatibility with existing control architectures and water treatment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freshwater Flake Ice Machine Market |
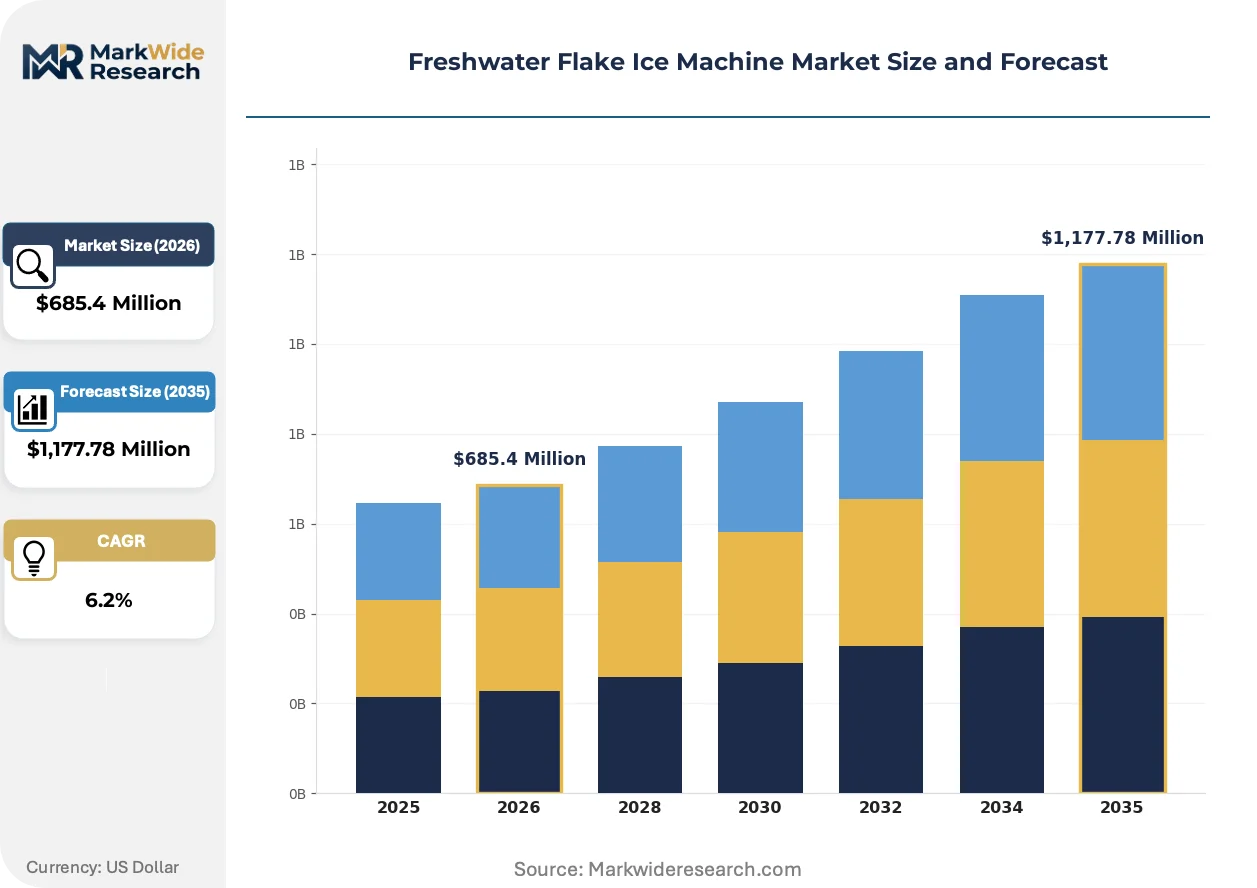
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Flake Ice Machine, Horizontal Flake Ice Machine, Modular Flake Ice Machine, Mobile Flake Ice Machine Technology: Refrigeration Compression, Absorption Refrigeration, Cascade Refrigeration, Magnetic Refrigeration, Thermoelectric Cooling Application: Seafood Processing, Concrete Cooling, Chemical Industry, Beverage Production, Poultry Processing End User: Supermarkets, Laboratories, Food Processing Facilities, Hospitality Establishments, Fisheries |
| Companies Covered | Focusun, Hoshizaki, Manitowoc Ice, Scotsman Ice Systems, GEA, Ice-O-Matic, North Star, KTI, ICEMAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freshwater Flake Ice Machine Market Trends and Innovations
Equipment architecture is pivoting toward modular configurations that accommodate phased capacity expansion, while refrigerant chemistry undergoes forced migration under tightening environmental regulations.
Rotating cylinder evaporator designs with precision ice-thickness controls are consolidating market share in premium food retail segments. Japanese supermarket chains specify these systems for display case integration. The technology is consolidating supplier margins by differentiating on surface-area consistency rather than pure tonnage output.
The EPA's AIM Act provisions enforce hydrofluorocarbon phase-down timelines for equipment sold in the United States. Manufacturers must recertify product lines under tightened GWP thresholds. Commercial foodservice channels face compressed redesign cycles as 2024-2026 production windows narrow.
Service contract unbundling is reshaping buyer-supplier relationships in North American foodservice. Operators now separate equipment purchase from maintenance agreements, comparing lifecycle cost models rather than upfront capital expenditure. This pattern concentrates in quick-service restaurant chains with standardized footprints across multiple climate zones.
Freshwater Flake Ice Machine Market Segmentation
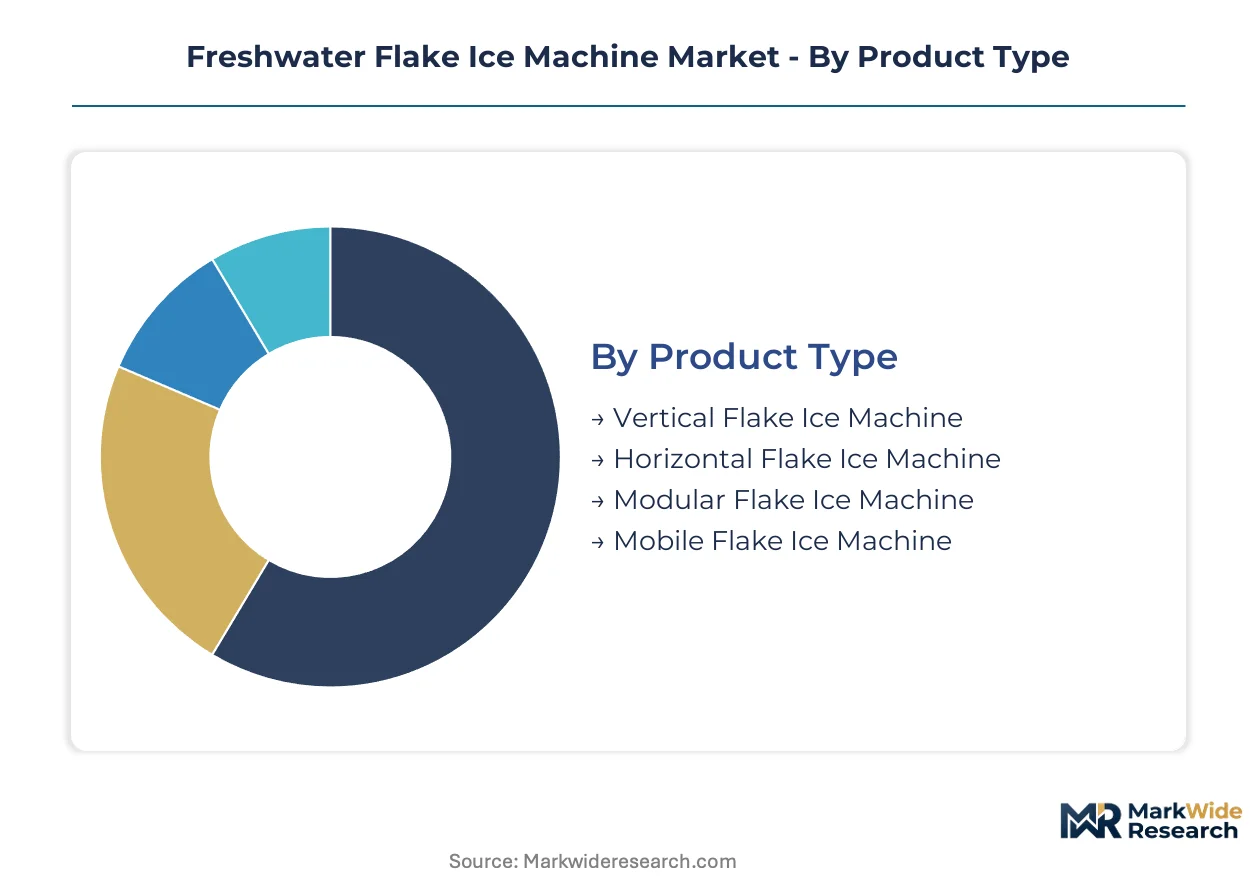
Flake ice machine segmentation reveals how equipment architecture, cooling technology, and end-use requirements create distinct procurement patterns across industrial and commercial channels. Understanding these divides helps suppliers align R&D investment with where demand is concentrating.
Product Type:
Vertical configurations dominate land-constrained installations where floor space commands premium pricing, while modular designs serve buyers planning phased capacity buildouts.
- Vertical Flake Ice Machine:Rotating drum evaporators stack vertically to minimize footprint in high-density food processing plants. Demand concentrates in Vietnam's Mekong Delta aquaculture zones where facility expansion faces strict land-use permits.
- Horizontal Flake Ice Machine:Cylinder evaporators arranged horizontally enable easier maintenance access and higher tonnage output per unit. These systems anchor capacity in Indonesia's tuna processing corridors where continuous operation demands serviceability.
- Modular Flake Ice Machine:Phased expansion capability suits European supermarkets requiring backward-compatible capacity additions.
- Mobile Flake Ice Machine:Trailer-mounted units serve remote infrastructure projects and temporary seafood landing sites.
Vertical designs lead volumes today; modular configurations are gaining share fastest.
Technology:
Refrigerant chemistry mandates are compressing viable technology pathways, with low-GWP alternatives displacing legacy hydrofluorocarbon systems across regulated markets.
- Refrigeration Compression:Mechanical vapor compression using R-290 or CO₂ refrigerants delivers the coefficient of performance required for industrial tonnage. EPA AIM Act timelines are forcing rapid redesign cycles for equipment sold in the United States.
- Thermoelectric Cooling:Solid-state Peltier modules eliminate vibration and moving parts for laboratory and pharmaceutical niches where ice purity outweighs energy efficiency constraints.
- Absorption Refrigeration:Heat-driven cycles suit sites with waste heat recovery potential.
- Cascade Refrigeration:Two-stage systems address ultra-low temperature requirements in specialized chemical applications.
- Magnetic Refrigeration:Magnetocaloric effect cooling remains pre-commercial for freshwater flake ice production.
Compression systems anchor installed base; thermoelectric segments show steepest expansion trajectory in precision end uses.
Application:
Surface-area-intensive cooling requirements differentiate high-value perishable preservation from bulk industrial temperature management.
- Seafood Processing:Thin, irregular ice fragments at -20°C to -25°C minimize freeze-burn on high-value catch. Southeast Asian processing corridors are scaling adoption as export quality standards tighten.
- Concrete Cooling:On-site flake ice production for batch temperature control serves tropical infrastructure projects where ambient heat threatens pour quality.
- Chemical Industry:Rapid heat transfer supports exothermic reaction control.
- Beverage Production:Surface contact cooling for fermentation and processing stages.
- Poultry Processing:Chilling requirements in slaughter and packaging operations.
Seafood processing leads application volumes; concrete cooling is climbing the fastest as infrastructure investment accelerates in tropical climates.
End User:
Facility scale and regulatory exposure shape procurement sophistication, with food safety certification requirements widening specification gaps between customer types.
- Food Processing Facilities:Industrial-scale installations face EU MDR material contact standards and FSSAI hygiene mandates in India, driving stainless steel evaporator specifications with documented surface compliance.
- Supermarkets:Display case integration demands precision ice-thickness controls for consistent surface area. Japanese chains specify rotating cylinder designs that consolidate supplier margins on performance rather than tonnage.
- Fisheries:Landing-site operations require durable, high-output systems for immediate catch preservation.
- Laboratories:Vibration-free operation priorities push toward thermoelectric alternatives.
- Hospitality Establishments:Foodservice channels in North America increasingly unbundle equipment purchase from maintenance agreements.
Food processing facilities dominate end-user volumes; supermarket specifications are expanding most quickly as retail integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing cost differentials between compliance-heavy European markets and Asia-Pacific production hubs are redirecting equipment sourcing patterns. Producers exploit regulatory-arbitrage gaps by locating final assembly in jurisdictions with lighter refrigerant-handling requirements.
China
Jiangsu and Zhejiang provinces concentrate flake ice machine fabrication for export markets. GB standards and NMPA food-equipment certifications govern domestic safety benchmarks while dual carbon goals pressure factory energy intensity. Yangtze River Delta manufacturing clusters are scaling higher-capacity systems for Southeast Asian seafood processors.
United States
Commercial foodservice channels drive replacement demand as EPA AIM Act timelines compress hydrofluorocarbon phase-down schedules. FDA food-contact material standards shape stainless steel specifications for evaporator surfaces. Southern states with dense poultry processing footprints anchor industrial installation volumes.
Vietnam
Mekong Delta aquaculture zones are expanding flake ice adoption for shrimp and pangasius export preservation. FSSAI-equivalent hygiene mandates from Vietnam's national food safety authority tighten landing-site equipment specifications. Can Tho and An Giang provinces concentrate new capacity additions.
Germany
EU F-Gas Regulation enforcement accelerates equipment replacement cycles across food processing facilities. EMA-aligned CE marking requirements under MDR frameworks govern material contact compliance. Bavaria's industrial machinery corridor anchors premium system engineering for European supermarket chains.
Indonesia
Tuna processing corridors in Sulawesi and Maluku scale flake ice adoption for high-value catch preservation. The country's national standards body enforces equipment safety certifications for imported machinery. Bitung and Ambon landing sites concentrate demand for durable, high-output systems.
Freshwater Flake Ice Machine Market Competitive Landscape
Chinese producers anchor the volume tier; Japanese and European specialists hold premium positioning through precision engineering. The vendor base splits between consolidated multinational refrigeration groups and regional fabrication clusters. Three archetypes dominate: vertically integrated compressor manufacturers, precision-control specialists, and modular-system fabricators. Capacity expansion in Southeast Asian markets and refrigerant-transition partnerships represent the dominant competitive moves.
Among East Asian equipment builders, Focusun and Hoshizaki occupy distinct tier positions. Focusun exemplifies the vertically integrated archetype through captive compressor sourcing. Hoshizaki represents precision-control specialization for food retail integration. Scotsman Ice Systems anchors North American foodservice presence through modular footprint designs. These three names illustrate how geographic origin and structural positioning shape competitive differentiation without overlapping segment focus.
| Leading Market Players |
|---|
| Focusun |
| Hoshizaki |
| Manitowoc Ice |
| Scotsman Ice Systems |
| GEA |
| Ice-O-Matic |
| North Star |
| KTI |
| ICEMAN |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance deadlines are compressing procurement timelines for European food processors, forcing equipment buyers to absorb premium pricing for low-GWP refrigerant systems while Chinese manufacturers scramble to certify export-bound production lines.
Pricing Analysis
Distributor margins in Southeast Asian seafood processing corridors absorb the steepest compression as buyers consolidate purchase volumes around landed-cost parity. Three-tier pricing structure across premium, standard, and economy levels separates Japanese precision-control systems from Chinese volume-tier offerings and European modular configurations. Pricing pressure stems from refrigerant transition costs and compressor redesign investments that mid-tier producers cannot fully pass through. Quick-service restaurant chains in North America exhibit highest price sensitivity through unbundled service contract negotiations, while Japanese supermarket specifications tolerate premium positioning for display-case integration performance.
Supply Chain Analysis
Skilled refrigeration technician scarcity in Jiangsu and Zhejiang provinces constrains production scaling for export-focused manufacturing clusters. Component sourcing draws from Chinese compressor foundries, German precision-control electronics, and Japanese stainless steel evaporator fabrication. Single-source vulnerability concentrates in rotary drum evaporator machining capacity concentrated in Yangtze River Delta facilities. Distribution runs through regional equipment distributors serving seafood processing zones in Vietnam, Indonesia, and Philippines with direct-to-facility installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA AIM Act phase-down timelines and EU F-Gas mandates force replacement demand regardless of underlying economic cycles.
For Market Incumbents: Hedge refrigerant transition exposure by diversifying compressor supplier relationships across R-290 and CO₂ technology pathways. Secure backward integration into stainless steel evaporator surface finishing to meet EU MDR material contact compliance without margin erosion from third-party certification costs. Defend against modular-system specialists by embedding predictive maintenance software into premium equipment tiers. For New Entrants and Emerging Players: Capture underpenetrated Indian cold chain infrastructure where FSSAI hygiene mandates and PLI scheme incentives create procurement windows for certified equipment. Target concrete cooling applications in tropical infrastructure projects as the fastest-climbing demand vertical outside food processing. Enter through equipment-as-a-service models that bundle installation, refrigerant handling, and maintenance for buyers lacking certified technician networks. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated compressor manufacturers possessing captive refrigerant system engineering capabilities and established Southeast Asian distribution. Five-to-ten year viability hinges on regulatory arbitrage positioning between compliance-heavy European markets and lighter-touch Asian certification regimes. Monitor EPA enforcement consistency and EU F-Gas quota allocation mechanisms as inflection signals for equipment replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Diversification | Dual R-290 and CO₂ system portfolios preserve market access under divergent regulatory timelines in EPA and EU jurisdictions. |
| Backward Integration into Compressor Sourcing | In-house production of low-GWP compression systems defends margin position against refrigerant input cost volatility. |
| Modular System Architecture Development | Phased capacity expansion capability captures European supermarket procurement specifications requiring backward-compatible additions. |
| Service Contract Unbundling | Separate equipment and maintenance pricing aligns with North American quick-service restaurant chain lifecycle cost modeling. |
| Geographic Manufacturing Footprint Expansion | Final assembly in jurisdictions with lighter refrigerant-handling requirements exploits regulatory-arbitrage gaps for export markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment procurement managers at Vietnamese aquaculture processors, Indonesian tuna landing site operators, European supermarket technical specification leads, and North American foodservice chain maintenance directors with secondary validation through EPA AIM Act regulatory filings, EU F-Gas Regulation implementation reports, China customs export data, and NMPA food-equipment certification records. Bottom-up installation tracking across Mekong Delta provinces and Sulawesi processing corridors triangulated against top-down manufacturer shipment disclosures.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across vertical-horizontal-modular-mobile product architectures, compression-thermoelectric-absorption-cascade-magnetic technology pathways, and seafood-concrete-chemical-beverage-poultry application verticals. CAGRs derived from equipment replacement cycle analysis under regulatory phase-down schedules, input cost trajectory assumptions for stainless steel and refrigerant chemistry transitions, and regional infrastructure investment pipeline tracking.
Underlying measurement precision varies by segment; seafood processing and concrete cooling application forecasts carry tighter precision than thermoelectric laboratory niche projections. Forecasts reflect documented assumptions regarding refrigerant transition pathway adoption rates and regional certification timeline adherence. Material deviation in EPA enforcement intensity, EU quota allocation decisions, or Southeast Asian landing site infrastructure investment flows warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Bottling Machinery Market
Food Processing Equipment
Tea Processing Equipment Market
Food Processing Equipment
Continuous Fryer Machine Market
Food Processing Equipment
Cider Brewing Equipment Market
Food Processing Equipment
Coffee Processing Machine Market
Food Processing Equipment
Food Processing and Handling Equipment Market
Food Processing Equipment
Bread Maker Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Vee Bee Consistometer Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Nigeria Cocoa Processing Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
Holding and Proofing Cabinet Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Oven Market