
 Food Recycling Machines Market | 2026-2036
Food Recycling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Food Recycling Machines Market Analytics
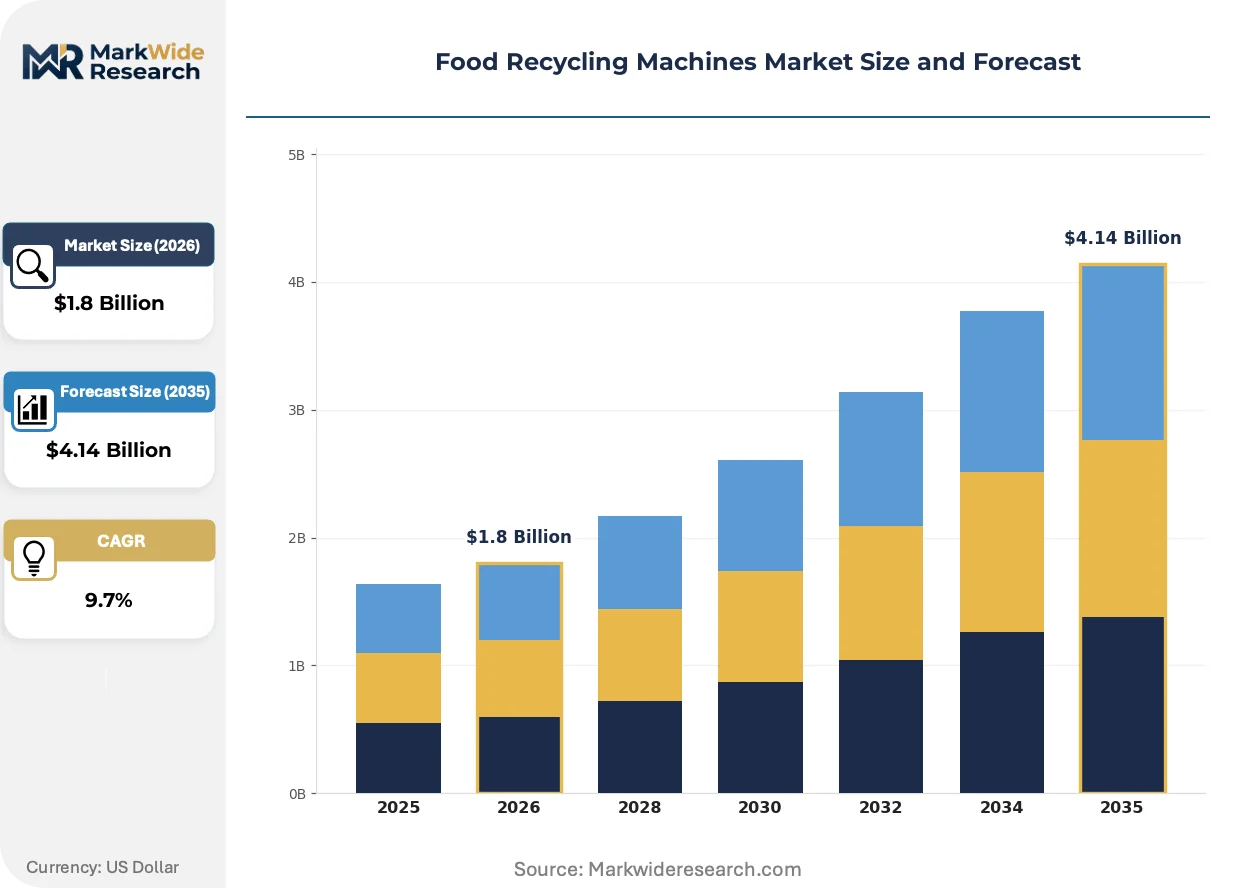
EU F-Gas Regulation is recalibrating refrigeration-dependent food recycling systems across European commercial kitchens. Oklin International leverages compact aerobic digestion designs to dominate urban restaurant installations where space constraints limit conventional composting. BioHiTech Global anchors its position through cloud-connected bio-digester fleets that sustain recurring service revenue from hospitality chains. Whirlpool Corporation competes on manufacturing scale, extending appliance-grade reliability into household food recycler segments.
Food recycling machines are electromechanical systems that reduce organic waste volume through biological decomposition, thermal drying, or mechanical size reduction, typically processing between 10 kilograms and several tonnes per day depending on unit scale. Their primary purpose is converting food scraps into compost, biogas feedstock, or dry biomass suitable for disposal or agricultural reuse. Composting units lead installed base among municipalities operating centralized organic waste programs, while bio-digesters represent the fastest-expanding segment as restaurants pursue energy-neutral waste handling. Anaerobic digestion technology commands premium pricing due to methane capture capabilities, whereas mechanical processing equipment occupies the economy tier through simpler shredder-dehydrator configurations.
The US EPA landfill diversion guidelines and EU Waste Framework Directive enforcement are tightening organic waste disposal rules, compelling food manufacturers and hospitality operators to install on-site recycling equipment rather than pay escalating collection fees. Japan's METI circular economy standards and South Korea's MFDS food waste metering policies further shape product certification requirements for export-oriented manufacturers. Stakeholders must monitor how national landfill bans and carbon accounting rules reshape total cost-of-ownership calculations for competing technology platforms.
Market Dynamics
EU F-Gas Regulation is forcing refrigeration-dependent food recycling systems toward alternative thermal processing architectures, compressing equipment design cycles and reshaping vendor R&D priorities across European commercial kitchen supply chains.
Growth Catalysts
- Landfill diversion mandates:EPA landfill diversion guidelines in the United States and EU Waste Framework Directive enforcement are compelling food manufacturers to install on-site recycling equipment rather than pay escalating collection fees.
- Anaerobic digestion technology:Food manufacturers seeking energy recovery from organic waste are driving demand for methane-capture-capable systems, particularly in Germany where municipal composting infrastructure is most developed.
- METI circular economy standards:Japan's certification requirements for export-oriented manufacturers are accelerating product standardization and opening distribution channels across East Asian hospitality markets.
Market Restraints
- Stainless steel input volatility:Equipment fabrication depends on nickel and chromium supply chains concentrated in Indonesian and South African mining operations, exposing manufacturers to price swings.
- Technical limitation in moisture handling:High-water-content food streams reduce throughput efficiency in mechanical shredder-dehydrator configurations, constraining deployment in seafood and produce processing environments.
- Regulatory friction from F-Gas:The EU F-Gas Regulation creates compliance complexity for refrigeration-integrated systems, extending certification timelines and raising engineering costs for European market entry.
Strategic Opportunities
- South Korea MFDS food waste metering:Mandatory disposal tracking policies are creating first-mover advantage for cloud-connected bio-digester fleets in Seoul's restaurant-dense districts.
- Technology convergence of IoT sensors and biological processing:Real-time composition monitoring is enabling predictive maintenance models that shift revenue from equipment sales to recurring service contracts.
- Underpenetrated India urban corridors:FSSAI food safety mandates and swelling quick-service restaurant density in Bangalore and Mumbai are opening demand for compact aerobic digestion units.
Industry Challenges
- Biological process engineering talent scarcity:Equipment manufacturers face recruitment bottlenecks for microbiologists capable of optimizing anaerobic digester performance across variable feedstock compositions.
- Legacy kitchen infrastructure integration:Retrofitting existing commercial facilities with food recycling machines requires plumbing and electrical reconfiguration that extends installation timelines and strains contractor relationships.
- Certification timeline compression:Divergent national standards across Japan METI, EU CE marking, and US NSF/ANSI requirements force parallel testing protocols that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Recycling Machines Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composting Units, Bio-digesters, Shredders, Dehydrators Technology: Aerobic Digestion, Anaerobic Digestion, Thermal Processing, Mechanical Processing End User: Households, Restaurants, Food Manufacturers, Municipalities Distribution Channel: Online Retail, Physical Stores, Direct Sales, Wholesalers |
| Companies Covered | Oklin International, BioHiTech Global, Whirlpool Corporation, Emerson Electric, Hungry Giant Recycling, Meiko, CP Manufacturing, Ridan Food Waste Composters, KCS Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Recycling Machines Market Evolving Landscape
Thermal drying architectures are absorbing design investment as refrigeration-integrated systems face regulatory headwinds, while cloud-connected monitoring platforms restructure vendor-customer relationships toward continuous service engagement.
Electrochemical oxidation modules are absorbing residual organic load in effluent streams from anaerobic digesters, enabling closed-loop water reuse. Food manufacturers with zero-liquid-discharge targets are piloting these units at scale in California and the Netherlands. This convergence is absorbing capital that previously flowed toward conventional wastewater treatment partnerships, compressing the addressable market for third-party disposal services.
EU F-Gas Regulation phase-down schedules are forcing equipment redesigns that eliminate hydrofluorocarbon refrigerants from thermal processing subsystems. Commercial kitchen operators in Germany and France are accelerating replacement cycles to preempt compliance deadlines. The regulation is absorbing engineering resources across European supply chains, delaying non-EU product line expansions by 12-18 months.
Hospitality chains are consolidating procurement decisions at regional headquarters rather than individual property levels, compressing vendor negotiation cycles and favoring suppliers with national service networks. This concentration is absorbing smaller equipment distributors into master service agreements with multi-brand hospitality groups. The shift is most visible in the United States, where Aramark and Compass Group-style contract foodservice operators are standardizing bio-digester specifications across portfolios exceeding 500 locations.
Food Recycling Machines Market Segmentation
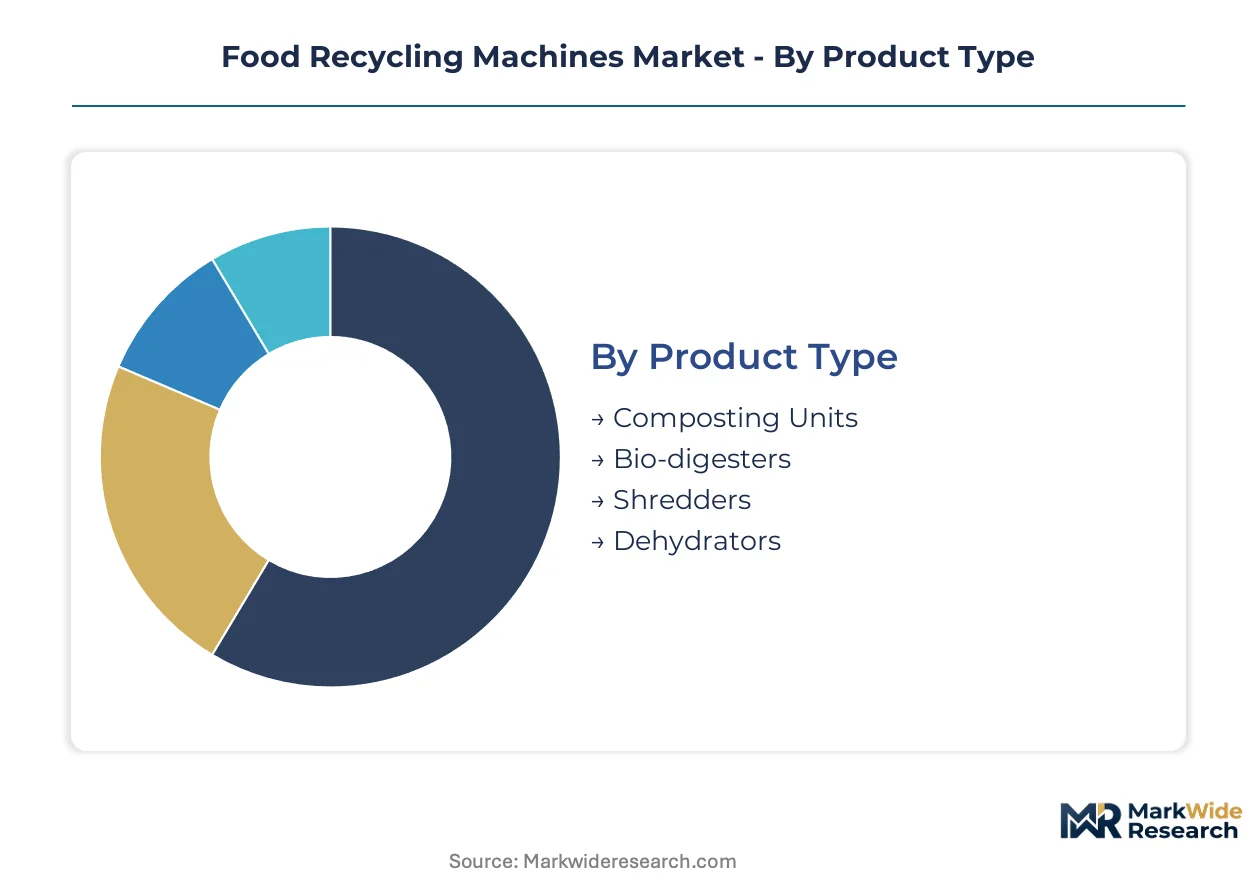
Segmentation in food recycling machines reveals how capital intensity, regulatory complexity, and operational scale reshape vendor priorities across installation environments. Understanding these divides clarifies why anaerobic digestion commands premium pricing while mechanical units penetrate cost-sensitive hospitality segments.
Product Type:
Capital requirements vary sharply across product categories, with methane-capture systems demanding substantially higher upfront engineering investment than volume-reduction equipment.
- Composting Units:Batch or continuous-flow vessels using controlled aeration and temperature management to accelerate organic decomposition into soil amendments. Municipal procurement in Germany and Japan concentrates demand where centralized collection infrastructure supports high-throughput installations.
- Bio-digesters:Sealed biological reactors processing food waste through microbial action, with anaerobic variants capturing methane for energy recovery. Restaurant chains in Seoul and New York City are deploying cloud-connected fleets to meet mandatory disposal tracking requirements.
- Shredders:Rotary or hammer-mill configurations reducing particle size for downstream processing or landfill diversion. Quick-service kitchens in India favor compact units for space-constrained back-of-house layouts.
- Dehydrators:Thermal or mechanical moisture extraction systems producing dry biomass suitable for agricultural feed or fuel pellets. California food manufacturers pilot these for zero-liquid-discharge compliance.
Composting units absorb the bulk of installed capacity; bio-digesters are expanding most quickly.
Technology:
Application environment dictates technology selection, with energy-recovery goals favoring biological processes and speed-to-output favoring thermal or mechanical alternatives.
- Aerobic Digestion:Oxygen-dependent microbial breakdown producing stable compost without methane capture. Urban restaurants across Tokyo and London deploy compact aerobic units where space constraints and odor control priorities limit anaerobic alternatives.
- Anaerobic Digestion:Oxygen-excluded fermentation generating biogas suitable for on-site energy generation or grid injection. German food manufacturers anchor demand where feed-in tariffs and carbon accounting rules improve project economics.
- Thermal Processing:Heat-based volume reduction through drying, pyrolysis, or carbonization pathways. EU F-Gas Regulation phase-down schedules are accelerating redesigns away from refrigeration-integrated thermal architectures.
- Mechanical Processing:Physical size reduction and moisture separation without biological transformation. Southeast Asian seafood processors deploy shredder-dehydrator combinations where high water content in feedstocks constrains biological alternatives.
Anaerobic digestion claims the steepest expansion trajectory as energy prices and landfill diversion mandates tighten; mechanical processing retains the largest installed base in developing markets.
End User:
Procurement authority and operational scale create divergent purchasing patterns across customer types, from centralized municipal tenders to fragmented household decisions.
- Households:Countertop or under-sink units processing 1-5 kilograms daily through dehydration or compact composting. Japanese metropolitan consumers drive premium appliance-grade demand where METI circular economy certification signals quality.
- Restaurants:Commercial-scale installations handling 50-500 kilograms daily, often with remote monitoring capabilities. Contract foodservice operators in the United States are consolidating procurement at regional headquarters, compressing vendor negotiation cycles.
- Food Manufacturers:Industrial systems processing multiple tonnes daily with integration into production waste streams. California and Netherlands facilities pilot electrochemical oxidation modules for closed-loop water reuse alongside anaerobic digestion.
- Municipalities:Centralized organic waste facilities serving residential and commercial collection zones. German and Japanese cities anchor procurement where composting infrastructure development preceded commercial kitchen mandates.
Food manufacturers command the highest average transaction values; restaurants are gaining share fastest as on-site mandates proliferate.
Distribution Channel:
Channel economics reflect equipment complexity, with direct sales dominating engineered systems and online retail penetrating standardized household units.
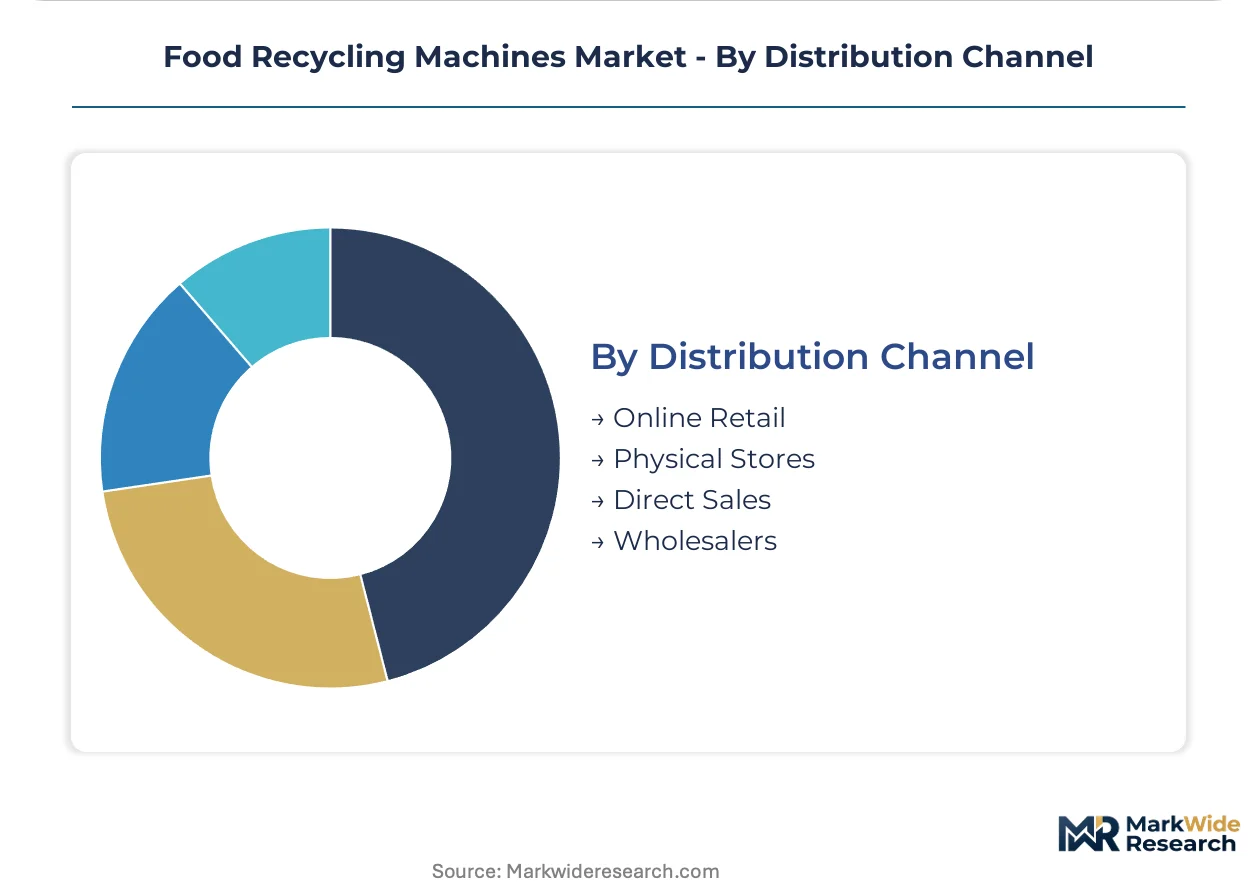
- Online Retail:E-commerce platforms and manufacturer direct-to-consumer portals. Household dehydrator sales in Japan and South Korea concentrate here where appliance-grade reliability expectations are established.
- Physical Stores:Specialty kitchen equipment dealers and home improvement retailers. US and European commercial kitchen supply houses maintain inventory for emergency replacement cycles.
- Direct Sales:Manufacturer-led specification, installation, and service contracts. Bio-digester deployments to hospitality chains and food manufacturers run almost exclusively through this channel.
- Wholesalers:Regional distributors aggregating multiple brands for contractor and facility manager procurement. Smaller restaurant operators in India and Southeast Asia rely on wholesaler networks for technical support localization.
Direct sales capture the majority of revenue value; online retail is climbing the fastest as household segment penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial parks in South Korea's capital region concentrate bio-digester deployment density, with Seoul's restaurant-dense districts driving equipment installation rates that outpace national averages by substantial margins.
United States
California food manufacturers pilot closed-loop water reuse systems alongside anaerobic digestion to meet zero-liquid-discharge targets. EPA landfill diversion guidelines tighten organic waste disposal rules, compelling hospitality operators to install on-site recycling equipment. New York City's commercial kitchen density supports rapid bio-digester fleet expansion among contract foodservice operators.
Germany
German food manufacturers anchor European demand for methane-capture-capable systems where feed-in tariffs improve project economics. EU F-Gas Regulation phase-down schedules force equipment redesigns away from hydrofluorocarbon refrigerants, compressing certification timelines. Industrial clusters in Bavaria and North Rhine-Westphalia concentrate anaerobic digestion installations serving integrated food production facilities.
Japan
Tokyo metropolitan consumers drive premium appliance-grade demand for household food recyclers where METI circular economy certification signals quality. Japan's national circular economy standards accelerate product standardization across East Asian distribution channels. Osaka and Nagoya industrial corridors support commercial-scale aerobic digestion deployments in space-constrained urban restaurant environments.
South Korea
Seoul's restaurant-dense districts create first-mover advantage for cloud-connected bio-digester fleets under MFDS food waste metering policies. Mandatory disposal tracking requirements reshape procurement patterns toward monitored equipment configurations. Daegu-Gyeongbuk manufacturing bases supply compact aerobic digestion units optimized for quick-service kitchen footprints.
India
Bangalore and Mumbai quick-service restaurant density opens demand for compact aerobic digestion units as FSSAI food safety mandates tighten waste handling protocols. Maharashtra and Karnataka industrial parks attract equipment distributors building technical support localization capabilities. Wholesaler networks in Delhi-NCR and Chennai bridge manufacturer supply chains to fragmented hospitality operator procurement.
Food Recycling Machines Market Competitive Landscape
German and Japanese producers anchor one tier; North American specialists hold cloud-connected service positions. The vendor base distributes across three tiers: multinational appliance manufacturers with manufacturing scale advantages, mid-cap technology specialists with IoT-integrated platforms, and regional fabricators serving cost-sensitive emerging markets. Strategic moves concentrate on M&A consolidation of service networks and technology licensing partnerships that accelerate geographic expansion without direct capital deployment.
Within the cloud-connected service tier, BioHiTech Global exemplifies recurring revenue models built around monitored bio-digester fleets. Among appliance-grade manufacturers, Whirlpool Corporation occupies a position representing manufacturing scale extension into household segments. Oklin International anchors the compact aerobic digestion specialist archetype for space-constrained urban installations. These three named entities represent distinct competitive positioning vectors without implying specific market share claims.
| Leading Market Players |
|---|
| Oklin International |
| BioHiTech Global |
| Whirlpool Corporation |
| Emerson Electric |
| Hungry Giant Recycling |
| Meiko |
| CP Manufacturing |
| Ridan Food Waste Composters |
| KCS Engineering |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up mid-cap specialists in North American food recycling equipment have consolidated fragmented regional fabricators, concentrating procurement leverage over stainless steel suppliers while enforcing pricing discipline across standardized bio-digester product lines. This ownership pattern feeds back into supply choices through captive service network investments that lock in recurring revenue streams and insulate premium pricing tiers from spot-market volatility.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to cloud-connected bio-digester configurations for hospitality chains facing mandatory installation deadlines under municipal organic waste ordinances. The dominant pricing structure runs through three-tier differentiation across premium NSF-certified anaerobic systems, standard CE-marked aerobic units, and economy-grade mechanical shredders without remote monitoring. Price differentiation hinges on certification grade and after-sales service bundling, with California and New York City buyers showing lowest price sensitivity due to landfill diversion penalty exposure. Cost compression in the economy tier is intensifying as Indonesian nickel supply volatility feeds stainless steel input uncertainty.
Supply Chain Analysis
Reverse-logistics networks for refurbished electrochemical oxidation modules are emerging from California zero-liquid-discharge pilot programs, creating secondary supply channels for cost-sensitive Indian quick-service operators. Manufacturing concentration rests on Germany and Japan for precision-engineered anaerobic reactors, China for compact aerobic digestion housings, and South Korea for IoT sensor integration. Nickel and chromium sourcing draws from Indonesian and South African mining operations, exposing fabricators to single-source vulnerability in critical alloy supply. Distribution runs through direct sales for engineered bio-digester fleets and wholesaler networks for standardized compact units in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biological process engineering talent scarcity props pricing power for vendors with captive microbiology capabilities, constraining supply expansion faster than landfill diversion mandate proliferation can absorb. This capacity bottleneck sustains margin premiums across anaerobic digestion technology tiers.
For Market Incumbents: Lock in service contract renewals through predictive maintenance platform investments that raise switching costs for hospitality chain customers. Defend against emerging IoT-native entrants by deepening backward integration into sensor hardware production, reducing dependency on South Korean component suppliers. Certification investment in Japan METI and South Korea MFDS standards creates regulatory moats that delay competitor product launches by twelve to eighteen months. For New Entrants and Emerging Players: Commercial kitchen equipment distributors with established contractor relationships offer the fastest channel access for compact aerobic digestion units targeting space-constrained urban restaurants. White-space concentration appears in Bangalore and Mumbai quick-service corridors where FSSAI enforcement is tightening but localized technical support remains underdeveloped. A leasing-plus-service subscription model bypasses capital expenditure barriers that constrain independent restaurant adoption. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap technology specialists with installed cloud-connected fleets in Germany and Japan where regulatory compliance timelines have compressed weaker competitors. Long-term viability centers on recurring service revenue conversion rather than equipment shipment volumes. The inflection signal to watch is consolidation of procurement authority at contract foodservice operator headquarters, which favors vendors with national service network scale.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Cloud-connected bio-digester fleets enable predictive maintenance contracts with hospitality chains. |
| Backward Integration into Sensors | In-house production of composition monitoring hardware reduces South Korean component dependency. |
| Certification Acceleration | Parallel METI and MFDS testing protocols open East Asian distribution channels faster than competitors. |
| Service Network Expansion | Regional technician density supports direct sales conversion for anaerobic digestion installations. |
| Leasing Model Introduction | Subscription pricing bypasses capital constraints for independent restaurant operators in India. |
Research Methodology
Independent corroboration across equipment manufacturer sales directors, commercial kitchen facility managers, and municipal waste procurement officers underwrites the qualitative findings presented. Primary interviews with biological process engineers and aftermarket service heads were validated against secondary sources including EPA landfill diversion filings, EU F-Gas Regulation implementation reports, Japan METI circular economy certification databases, and South Korea MFDS food waste metering policy documents. Bottom-up unit shipment estimates from national distributor channels were triangulated against top-down addressable market calculations using restaurant density and manufacturing facility counts.
Rate-of-change decomposition across the projection horizon separates volume expansion from price-mix effects in anaerobic digestion versus mechanical processing technology tiers. The analytical framework models segmentation dimensions including product type, technology pathway, end-user scale tier, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating feed-in tariff policy stability, landfill ban implementation schedules, and stainless steel price index trajectories. Industry-specific forecast inputs include hospitality chain procurement consolidation velocity and cloud-connected fleet penetration rates.
Caveats apply where EU F-Gas Regulation phase-down acceleration or Indonesian nickel export restrictions could materially shift the outlook for thermal processing equipment economics. Practitioners should monitor municipal organic waste mandate enforcement intensity and biological process engineering salary inflation for early signals of supply constraint severity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Multiple Unit Pellet Systems Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Loss-In-Weight Feeder Market
Food Processing Equipment
Food Sorting Machines Market
Food Processing Equipment
Spray Dried Food Market
Food Processing Equipment
Tortilla Machine Market
Food Processing Equipment
Conveyor Ovens and Impinger Ovens Market
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Smart Bread Machine Market
Food Processing Equipment
Global Commercial Food Dehydrators Market
Food Processing Equipment
Mushroom Fermenter Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Glass Processing Equipment Market
Food Processing Equipment
Alternative Protein Processing Equipment Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market