
 Africa Agricultural Robots and Mechatronics Market | 2026-2036
Africa Agricultural Robots and Mechatronics Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Agricultural Robots and Mechatronics Market Outlook
Aftermarket service revenue is fragmenting across Africa's agricultural robotics landscape as hardware margins compress and local technical support becomes the primary profit pool. Deere & Company leverages its established dealer network to control spare parts distribution in Southern Africa. Naio Technologies specializes in compact weeding robots suited to smallholder plot geometries. AGCO anchors its position through regional assembly partnerships that reduce import duty exposure.
Agricultural robots and mechatronics integrate electromechanical actuators, sensor arrays, and control software to execute precision farming tasks with minimal human intervention. These systems typically operate via GPS-guided navigation, real-time soil sensing, and automated implement control to optimize planting density, chemical application rates, and harvest timing. Autonomous tractors and harvesting robots capture the dominant share of current equipment expenditure as commercial farms prioritize mechanized row-crop operations. Drones equipped with multispectral imaging and AI-based analytics represent the fastest-expanding technology segment, particularly for pest control and crop monitoring applications where aerial data reduces input waste.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces equipment safety certification through the country's national standards body, while Kenya's Agricultural Finance Corporation structures loan products around precision technology collateral value. Ethiopia's agricultural transformation agency coordinates mechatronics pilot programs with cooperative farms to build localized technical capacity. Stakeholders must monitor how rapidly national agricultural banks recalibrate lending criteria to recognize automated equipment as qualified collateral against traditional machinery valuations.
Market Dynamics
Precision farming technology adoption is accelerating across Africa's commercial agricultural belt as large-scale operators replace conventional mechanization with sensor-integrated autonomous systems. This shift compresses equipment replacement cycles and restructures dealer revenue models toward service-based contracts.
Growth Catalysts
- Kenya's Agricultural Finance Corporation loan restructuring:Collateral valuation frameworks now recognize precision technology assets, unlocking capital access for automated equipment procurement.
- Commercial grain belt mechanization:South African row-crop farms deploy GPS-guided tractors to optimize planting density and chemical application rates across extensive maize and wheat operations.
- Multispectral drone imaging:AI-enabled aerial analytics reduce input waste in high-value horticulture zones, particularly Kenya's flower and vegetable export corridors.
Market Restraints
- Import duty exposure:Fully assembled robotics incur substantial tariffs across African customs unions, elevating landed costs versus regional assembly alternatives.
- Technical support scarcity:Aftermarket service infrastructure concentrates in South Africa and Nigeria, leaving East African operators dependent on extended lead times for critical repairs.
- Power grid instability:Rural electrification gaps in Ethiopia and Tanzania limit charging infrastructure for battery-dependent autonomous platforms.
Strategic Opportunities
- Ethiopian cooperative farm pilots:The agricultural transformation agency coordinates mechatronics demonstrations to build localized technical capacity and operator familiarity.
- Compact weeding robotics:Smallholder plot geometries below five hectares create demand for scaled-down autonomous platforms suited to irregular field boundaries.
- Equipment safety certification alignment:South Africa's national standards body frameworks may harmonize with SADC protocols, reducing multi-jurisdiction compliance burden.
Industry Challenges
- Control software integration:Legacy farm management information systems lack API compatibility with autonomous navigation platforms, forcing expensive middleware development.
- Electromechanical actuator maintenance:Local technician pools possess limited training in servo motor calibration and sensor array diagnostics, extending downtime incidents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Agricultural Robots and Mechatronics Market |
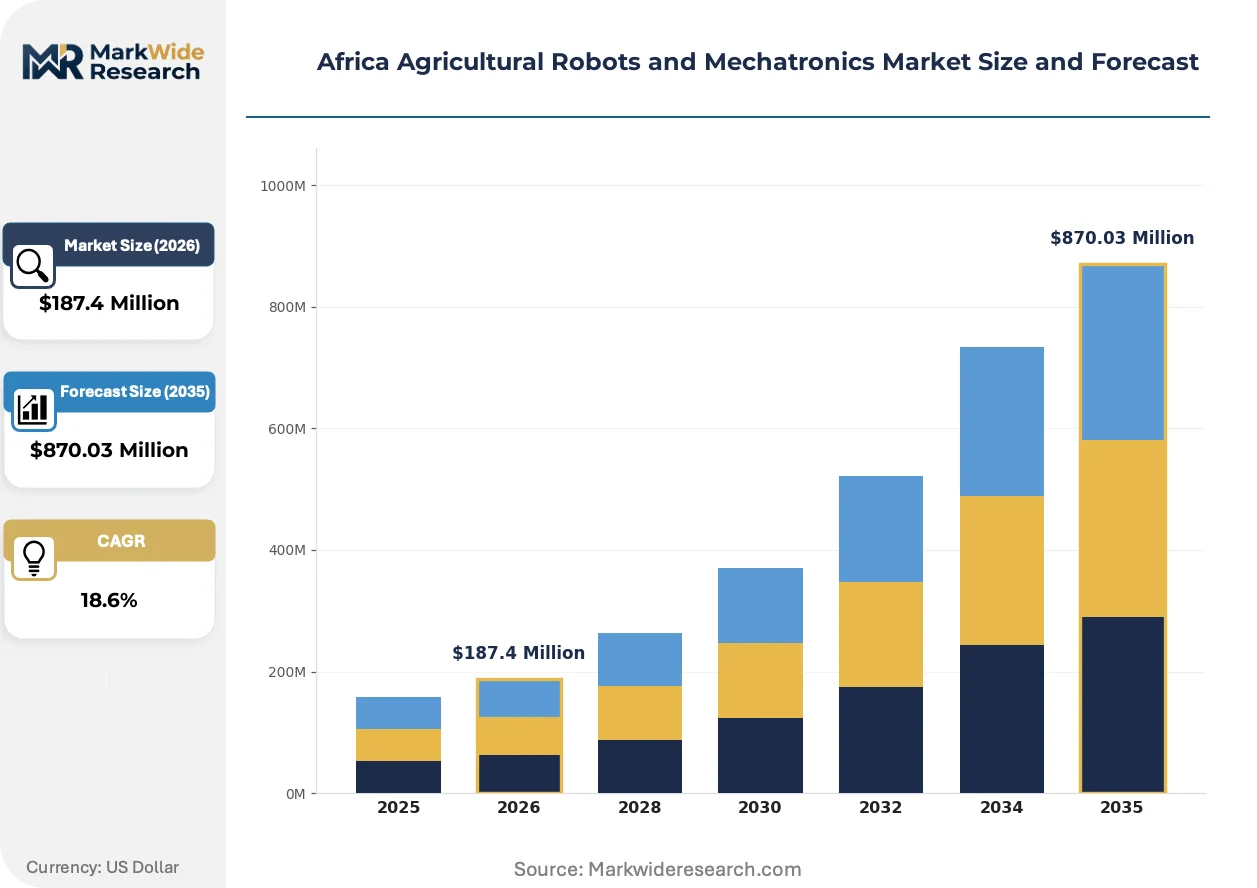
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Tractors, Drones, Harvesting Robots, Seeding Machines Technology: AI-Based Systems, GPS Navigation, Sensor Technology, Automation Software End User: Large Scale Farmers, Cooperative Farms, Agricultural Institutions, Research Facilities Application: Planting, Irrigation Management, Pest Control, Crop Monitoring |
| Companies Covered | AGCO, Autonomous Solutions (ASI), Autonomous Tractor Corporation, CNH Industrial, Deere & Company, CLAAS, GEA Group, Delaval, Naio Technologies, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Agricultural Robots and Mechatronics Market Strategic Shifts
Autonomous navigation platforms are penetrating Africa's agricultural sector through layered technology stacks combining hardware, software, and data services. This convergence is compressing traditional equipment procurement cycles and elevating service contract profitability.
Sensor fusion architectures are migrating from standalone GPS guidance to integrated soil sensing and real-time implement control systems. South African commercial grain operators adopt these platforms fastest, with Kenyan horticulture exporters following at compressed adoption timelines. This migration from basic automation to full autonomy is enabling outcome-based service pricing and displacing traditional hourly equipment rental models.
South Africa's Department of Agriculture, Land Reform and Rural Development enforces equipment safety certification through the national standards body, creating compliance bottlenecks for imported platforms. Industrial consequence includes extended type-approval timelines for autonomous tractors exceeding 100 horsepower. Commercial farms in the Western Cape and Free State provinces absorb these delays through advance procurement scheduling, while smaller operators defer purchases.
After-sales service unbundling is fragmenting revenue streams across Africa's agricultural robotics landscape. Hardware margins compress as autonomous platforms commoditize, while technical support contracts capture expanding profit pools. Dealer networks in South Africa and Nigeria pivot toward predictive maintenance subscriptions and remote diagnostics. This behavioral shift is most visible in Kenya's high-value horticulture zones, where export-oriented farms prioritize uptime guarantees over capital expenditure minimization.
Africa Agricultural Robots and Mechatronics Market Segmentation
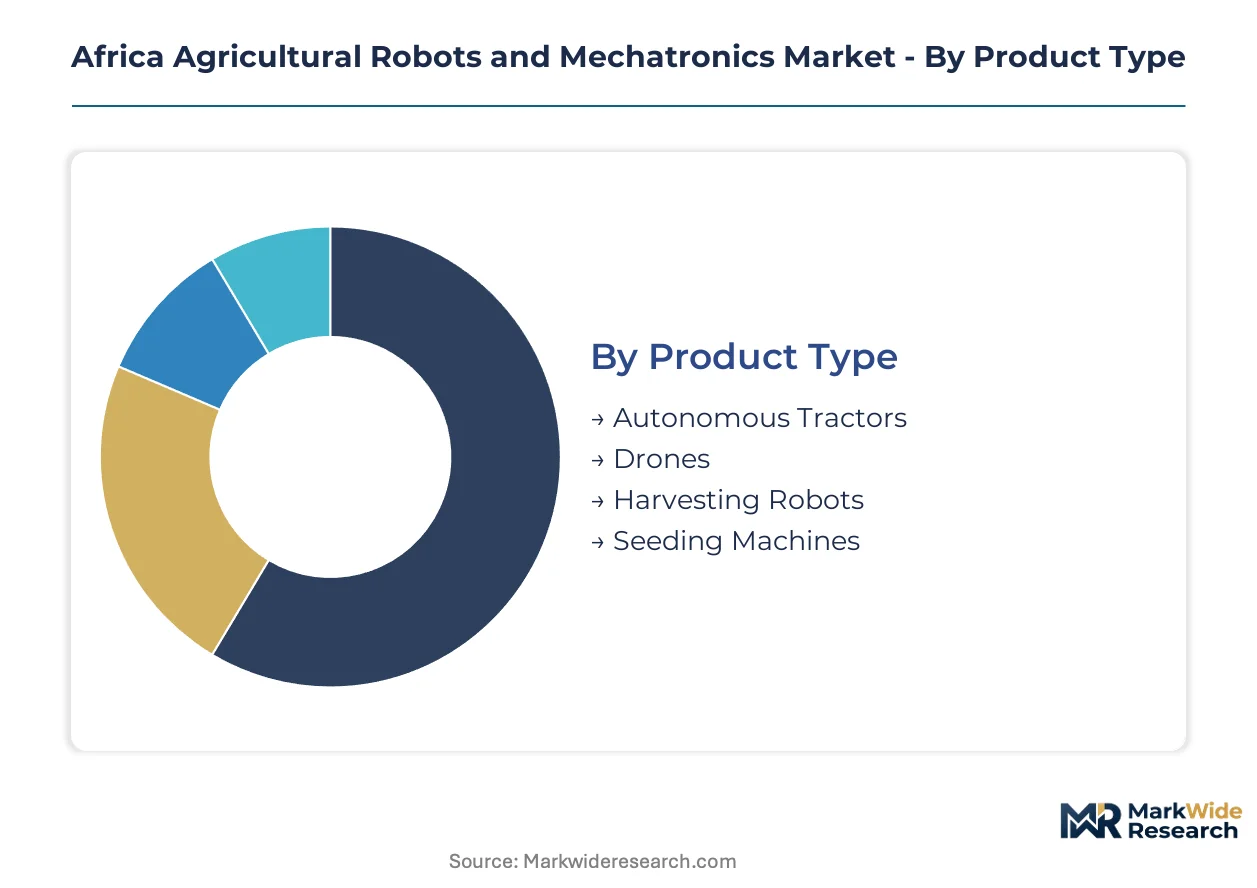
Segmentation reveals how after-sales service intensity varies sharply across equipment categories in Africa's agricultural robotics landscape. Autonomous tractors demand dense technician networks for hydraulic and navigation system maintenance, while drone fleets prioritize software update cycles and battery logistics over physical repair infrastructure.
Product Type:
After-sales service intensity peaks with autonomous tractors and harvesting robots, where hydraulic system failures and GPS calibration errors demand rapid technician response times that strain Southern Africa's concentrated service infrastructure.
- Autonomous Tractors:These platforms integrate electrohydraulic implement control with RTK-GPS guidance systems exceeding 2.5 centimeter accuracy. South Africa's commercial grain belt concentrates procurement, where maize and wheat operations prioritize planting density optimization over capital expenditure minimization.
- Drones:Multispectral imaging payloads combined with AI-based flight planning software enable pest detection and variable-rate chemical application. Kenya's flower export corridors near Naivasha and Thika drive fleet expansion, with operators accepting 48-hour battery replacement cycles to maintain aerial coverage during critical growth windows.
- Harvesting Robots:Robotic arms with computer vision sorting capabilities address labor scarcity in high-value horticulture.
- Seeding Machines:Precision metering systems reduce seed waste in large-scale row-crop operations.
Autonomous tractors hold the largest share; momentum sits with drones as battery costs compress and flight autonomy improves.
Technology:
Cost tier stratification separates premium AI-based platforms with predictive analytics capabilities from entry-level GPS navigation systems that dominate smallholder-adjacent cooperative farms.
- AI-Based Systems:Machine learning models trained on regional crop disease databases enable early pest detection and yield forecasting. Nigeria's cocoa belt and Kenya's tea highlands concentrate early adoption, where export price volatility justifies subscription-based analytics fees over capital hardware purchases.
- GPS Navigation:RTK correction signal networks deliver sub-inch accuracy for autosteering applications. South Africa's Western Cape wine farms and Free State grain operations anchor demand, with operators treating annual correction service subscriptions as non-discretionary operational expenses.
- Sensor Technology:Soil moisture and nutrient probes feed variable-rate application maps.
- Automation Software:Fleet management platforms coordinate multi-machine field operations.
GPS navigation holds the largest share; AI-based systems are climbing the fastest as cloud infrastructure penetrates rural connectivity gaps.
End User:
Customer type determines procurement financing structures, with large-scale farmers accessing equipment loans against land titles while cooperative farms depend on development agency guarantee programs.
- Large Scale Farmers:Commercial operators above 500 hectares deploy integrated technology stacks combining autonomous tractors with drone fleets and centralized farm management software. South Africa's maize triangle and Kenya's wheat belt concentrate procurement, where equipment replacement cycles compress from seven years to four years as autonomy features mature.
- Cooperative Farms:Aggregated smallholder plots create demand for shared-service robotics models. Ethiopia's agricultural transformation agency pilots compact weeding robots through cooperative structures, building operator familiarity before individual purchase decisions.
- Agricultural Institutions:Universities and extension services operate demonstration fleets for farmer training.
- Research Facilities:National agricultural research systems validate platform performance under local conditions.
Large scale farmers hold the largest share; cooperative farms are gaining share fastest as shared-service business models reduce individual capital barriers.
Application:
Application maturity correlates with input cost sensitivity, where pest control and irrigation management justify premium automation spending through immediate chemical and water savings.
- Pest Control:Drone-based targeted spraying reduces agrochemical volumes through precise boom height maintenance and variable-rate nozzles. Kenya's pyrethrum and vegetable export zones anchor demand, where European supermarket compliance requirements mandate residue minimization that automation delivers.
- Crop Monitoring:Multispectral imaging identifies nitrogen stress and irrigation deficits before visible symptoms. South Africa's Western Cape fruit operations prioritize canopy health surveillance, with stone fruit and table grape exporters integrating aerial analytics into daily harvest scheduling decisions.
- Planting:Autonomous seeding optimizes depth and spacing for germination uniformity.
- Irrigation Management:Soil sensor networks trigger precision water application schedules.
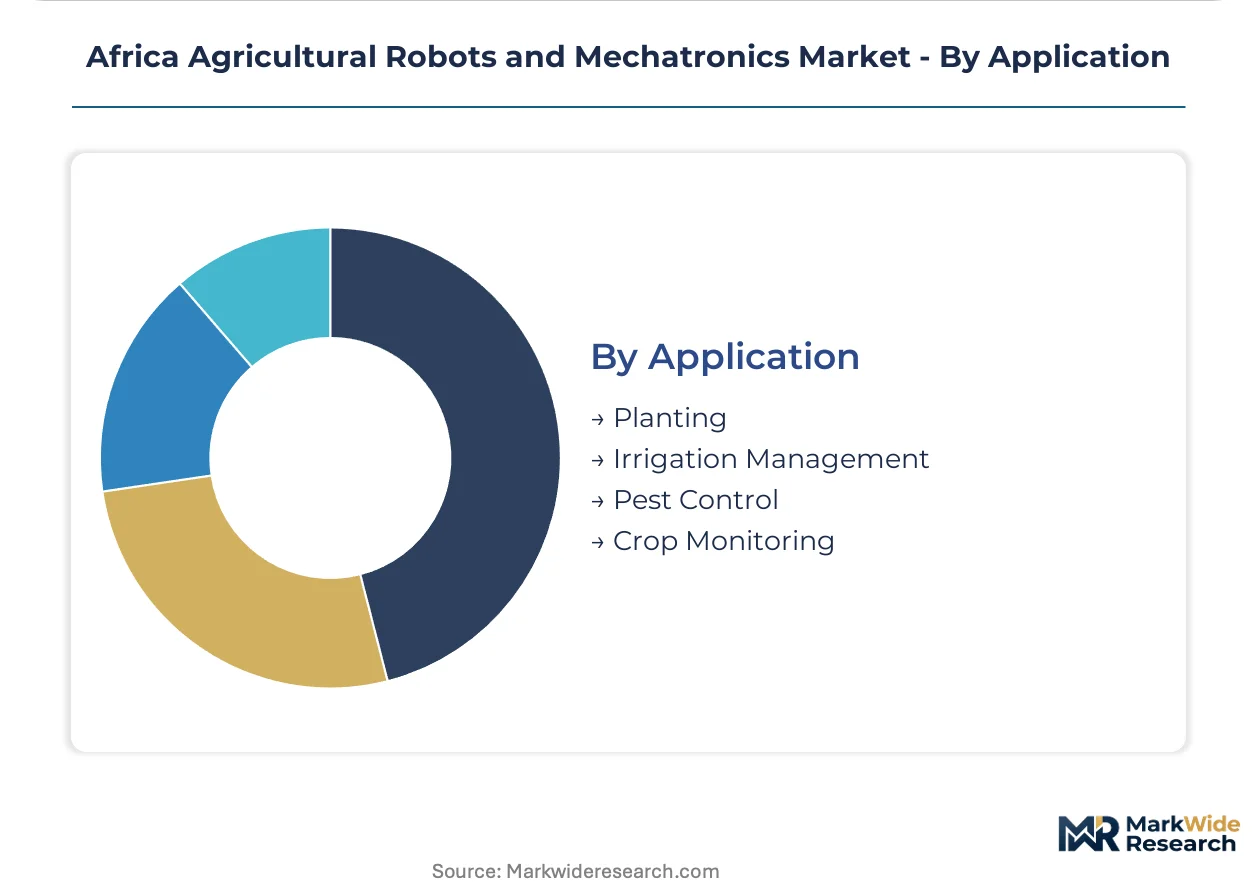
Crop monitoring holds the largest share; pest control represents the steepest expansion trajectory as chemical cost inflation accelerates precision spraying adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa consumes autonomous tractors for commercial grain operations while Kenya deploys drones for horticulture monitoring, revealing a consumption-mix differential between mechanized row-crop automation and aerial precision agriculture.
South Africa
Commercial maize and wheat operations in the Free State and Western Cape drive procurement of GPS-guided tractors with RTK accuracy below 2.5 centimeters. The Department of Agriculture, Land Reform and Rural Development enforces equipment safety certification through the national standards body, creating type-approval bottlenecks for autonomous platforms exceeding 100 horsepower. The Western Cape wine farms and fruit export corridors concentrate multispectral imaging adoption for canopy health surveillance.
Kenya
Flower and vegetable export zones near Naivasha and Thika prioritize drone fleets with 48-hour battery replacement cycles to maintain aerial coverage during critical growth windows. The Agricultural Finance Corporation restructured loan products to recognize precision technology assets as qualified collateral, unlocking capital access for automated equipment procurement. Pyrethrum and high-value horticulture operations anchor demand for targeted spraying systems that minimize chemical residues for European supermarket compliance.
Nigeria
Large-scale cocoa belt operators deploy AI-based analytics platforms for early pest detection and yield forecasting, justifying subscription fees over capital hardware purchases amid export price volatility. The country's national agricultural transformation programs coordinate with cooperative structures to build localized technical capacity for mechatronics adoption. Lagos and Abuja serve as logistics hubs for spare parts distribution, though aftermarket service infrastructure remains thinner than in Southern Africa.
Ethiopia
The agricultural transformation agency pilots compact weeding robots through cooperative farm structures, building operator familiarity before individual purchase decisions on smallholder plots below five hectares. Rural electrification gaps limit charging infrastructure for battery-dependent autonomous platforms, constraining deployment outside grid-connected zones. The Rift Valley and highland farming corridors concentrate demonstration programs for shared-service robotics models.
Tanzania
Cashew and coffee export operations in the southern highlands experiment with sensor-integrated automation, though power grid instability extends equipment downtime incidents. The country's customs union tariff structures elevate landed costs for fully assembled robotics versus regional assembly alternatives. Dar es Salaam and Arusha host emerging dealer networks pivoting toward predictive maintenance subscriptions as hardware margins compress.
Africa Agricultural Robots and Mechatronics Market Competitive Environment
Capability concentration sits with established agricultural machinery conglomerates possessing dense technician networks; scale advantage sits with emerging specialists offering compact platforms suited to smallholder geometries. The market structure tiers between premium integrated technology stacks and entry-level GPS navigation systems. Three archetypes dominate: legacy equipment manufacturers leveraging dealer infrastructure, robotics specialists targeting irregular field boundaries, and component suppliers anchoring regional assembly partnerships. Competitive moves center on service contract unbundling and predictive maintenance subscriptions displacing traditional hourly rental models.
Within the legacy equipment tier, Deere & Company and AGCO exemplify manufacturers controlling spare parts distribution through established Southern African dealer networks. Naio Technologies occupies a position among compact robotics specialists addressing plot geometries below five hectares. These three anchors represent divergent strategic postures: integrated technology stacks versus scaled-down autonomous platforms versus regional assembly partnerships reducing import duty exposure.
| Leading Market Players |
|---|
| AGCO |
| Autonomous Solutions (ASI) |
| Autonomous Tractor Corporation |
| CNH Industrial |
| Deere & Company |
| CLAAS |
| GEA Group |
| Delaval |
| Naio Technologies |
| Others |
Value Chain & Pricing Dynamics
German and Japanese electromechanical actuator manufacturers concentrate upstream supply, directing margin capture toward aftermarket service contracts rather than hardware sales across Southern African dealer networks. This upstream control shapes how procurement officers structure equipment financing around residual value guarantees.
Pricing Analysis
Long-term service contracts dominate procurement structures for autonomous tractors, with subscription-based predictive maintenance displacing transactional spare parts purchases. Price differentiation rests on RTK correction signal accuracy tiers and ISO safety certification levels. Cost compression in entry-level GPS navigation systems intensifies as Chinese component suppliers expand regional assembly partnerships. Cooperative farms exhibit highest price sensitivity, while export-oriented horticulture operators prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Lithium battery cell production feeds from China, South Korea, and Japan, with precision sensor arrays drawing from German and Israeli optical component specialists. Semiconductor dependencies for autonomous navigation platforms rest on Taiwanese foundry capacity and Dutch lithography equipment. Single-source vulnerability concentrates in RTK base station networks spanning the SADC region. Distribution runs through Johannesburg and Lagos hub-and-spoke structures with extended last-mile coverage to East African agricultural corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical capacity gaps in servo motor calibration and sensor array diagnostics constrain market expansion, with localized training infrastructure lagging hardware deployment across Ethiopia and Tanzania.
For Market Incumbents: Pre-empt emerging compact robotics specialists by embedding predictive maintenance subscriptions into equipment financing packages. Accelerate certification investment for SADC harmonized safety standards before multi-jurisdiction compliance burdens solidify. Channel control through exclusive spare parts distribution agreements defends margin pools against regional assembly partnerships reducing import duty exposure. For New Entrants and Emerging Players: Tanzania's cashew and coffee southern highlands present underpenetrated terrain where power grid instability has deferred incumbent deployment. Target cooperative farm shared-service models in Ethiopia's Rift Valley corridor, where agricultural transformation agency coordination reduces customer acquisition friction. Lead with battery-swappable drone platforms that circumvent charging infrastructure gaps. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision agriculture software platforms seeking hardware integration to complete technology stacks. Five-to-ten year viability hinges on national agricultural bank collateral recognition expanding beyond South Africa and Kenya. Watch for Ethiopian cooperative farm pilot conversion rates to individual purchase decisions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Assembly Partnership | Reduces import duty exposure for autonomous platforms entering SADC customs union markets. |
| Predictive Maintenance Subscription | Captures expanding profit pools as hardware margins compress across Southern African dealer networks. |
| Compact Robotics Platform Development | Addresses smallholder plot geometries below five hectares in Ethiopia and Kenya cooperative structures. |
| RTK Base Station Network Expansion | Enables sub-inch autosteering accuracy for South African maize and wheat commercial operations. |
| Certification Alignment Investment | Accelerates type-approval timelines for autonomous tractors exceeding 100 horsepower under national standards. |
Study Parameters
Cross-validation between dealer network interviews and agricultural finance corporation lending data anchors the qualitative findings. Primary sources encompass maintenance directors at commercial grain operations, aftermarket service heads at Southern African dealer networks, procurement officers at Kenya's Agricultural Finance Corporation, and cooperative farm managers in Ethiopia's Rift Valley. Secondary validation draws from SADC trade statistics, national standards body certification records, customs union tariff schedules, and equipment import registration databases. Bottom-up equipment procurement tracking triangulates against top-down agricultural modernization program budget allocations.
Calibration against historical replacement cycle compression patterns informs the analytical framework across the analysis window. Segmentation dimensions span product type, technology tier, end-user scale, and application intensity. CAGRs derive from equipment procurement run-rate analysis and precision technology collateral recognition expansion. Forecast inputs incorporate battery cost compression curves and rural electrification infrastructure build-out timelines.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity export prices and foreign exchange availability would shift the trajectory. Forecasts reflect documented assumptions regarding national agricultural bank lending criteria evolution and customs union tariff stability. Cross-checking against equipment safety certification backlog trends at national standards bodies is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Telepresence Robot Market
Robotics and Automation
Spain Cloud Robotics Market
Robotics and Automation
Robotic Flexible Washer Market
Robotics and Automation
Industrial Control Robotics Market
Robotics and Automation
Singapore Cloud Robotics Market
Robotics and Automation
Electric Power Intelligent Inspection Robot Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Global Adaptive Robotics Market
Robotics and Automation
Global Educational Robots Market
Robotics and Automation
Logistics Robotics Market
Robotics and Automation
Global Medical Telepresence Robot Market
Robotics and Automation
APAC Robotic Process Automation (RPA) Market
Robotics and Automation
Robot Market
Robotics and Automation
Medical Robotics Market
Robotics and Automation
Europe Articulated Robot Market
Robotics and Automation
Waste Sorting Robots Market