
 Robotic Flexible Washer Market | 2026-2036
Robotic Flexible Washer Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Flexible Washer Market Outlook
Adaptive sensor fusion in robotic cleaning cells is fragmenting traditional fixed-conveyor washer architectures into reconfigurable platform designs. ABB Group leverages its machine-vision integration to dominate high-mix aerospace applications where part geometry variability demands real-time nozzle path adjustment. BvL Oberflächentechnik GmbH anchors its position in European automotive through proprietary rotary indexing systems that sustain throughput during format changeovers. Dynamic Robotic Solutions competes on compact cell footprints for tier-2 electronics suppliers with limited floor space.
Robotic flexible washers are programmable multi-axis cleaning systems employing articulated manipulators with interchangeable end-effectors to deliver targeted aqueous, solvent, or abrasive media to complex component geometries, typically achieving cleanliness standards of ISO 16232 or VDA 19 for residual particulate contamination. Their primary purpose is to replace dedicated washing machines with adaptable cells that process diverse part families without mechanical retooling. The robotic product type captures the dominant value pool as OEMs prioritize capital equipment that amortizes across model generations rather than single-purpose lines. Ultrasonic technology leads installed base volumes while laser cleaning represents the fastest-expanding segment as manufacturers eliminate consumable media and comply with tightening effluent regulations. Aerospace application demand concentrates in precision turbine blade finishing where thermal and chemical methods face substitution pressure from dry laser ablation systems.
EMA's machinery safety directives and the EU F-Gas Regulation constrain fluorinated solvent deployment in European robotic washer specifications, while EPA NESHAP standards in the United States mandate capture and control of hazardous air pollutants from vapor degreasing operations. ISO 16232 particulate cleanliness standards govern automotive supplier qualification, creating certification barriers for equipment vendors without validated process guarantees. Stakeholders must weigh aqueous chemistry compatibility against cycle-time targets as regulatory phase-outs of chlorinated solvents accelerate capital replacement decisions across precision manufacturing supply chains.
Market Dynamics
EU F-Gas Regulation phase-down schedules are forcing capital replacement cycles across European precision manufacturing, converting solvent-based washer installations into aqueous and laser-based robotic cells ahead of regulatory deadlines.
Growth Catalysts
- Electric drivetrain component cleaning:Automotive OEMs demand ISO 16232-compliant particulate removal for battery housings and motor stators, pulling flexible robotic cells into powertrain assembly lines.
- REACH solvent restrictions:ECHA substance evaluations are eliminating chlorinated hydrocarbons from vapor degreasing, redirecting capital toward closed-loop aqueous systems with robotic manipulation.
- Laser ablation maturation:Dry cleaning eliminates effluent treatment infrastructure, reducing total cost of ownership for aerospace turbine blade finishing operations in Germany and France.
Market Restraints
- High-purity chemistry input costs:Deionized water and specialized surfactant formulations for aqueous systems face price volatility from petrochemical feedstock fluctuations.
- Control system supplier concentration:Robot kinematics and machine-vision integration depend on a narrow base of German and Japanese automation component vendors.
- Cycle-time penalties:Aqueous cleaning with drying stages extends process duration versus solvent vapor degreasing, limiting adoption in high-volume automotive fastening applications.
Strategic Opportunities
- India automotive supplier base:PLI scheme incentives for advanced manufacturing are attracting tier-1 component producers seeking first-mover robotic washer installations.
- Semiconductor capital equipment refurbishment:Vacuum chamber and wafer handling component remanufacturing creates demand for precision cleaning cells with sub-micron particulate guarantees.
- EU Green Deal funding windows:National recovery facility allocations for industrial decarbonization subsidize solvent-to-aqueous equipment conversions in Italy and Spain.
Industry Challenges
- Multi-physics simulation expertise:Cleaning process optimization requires rare cross-training in fluid dynamics, robotics programming, and surface chemistry.
- ISO 16232 validation timelines:Particulate extraction and gravimetric verification protocols extend equipment qualification periods by 4-6 months.
- Legacy SCADA integration:Brownfield manufacturing lines demand custom middleware to connect new robotic cells with existing plant data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Flexible Washer Market |
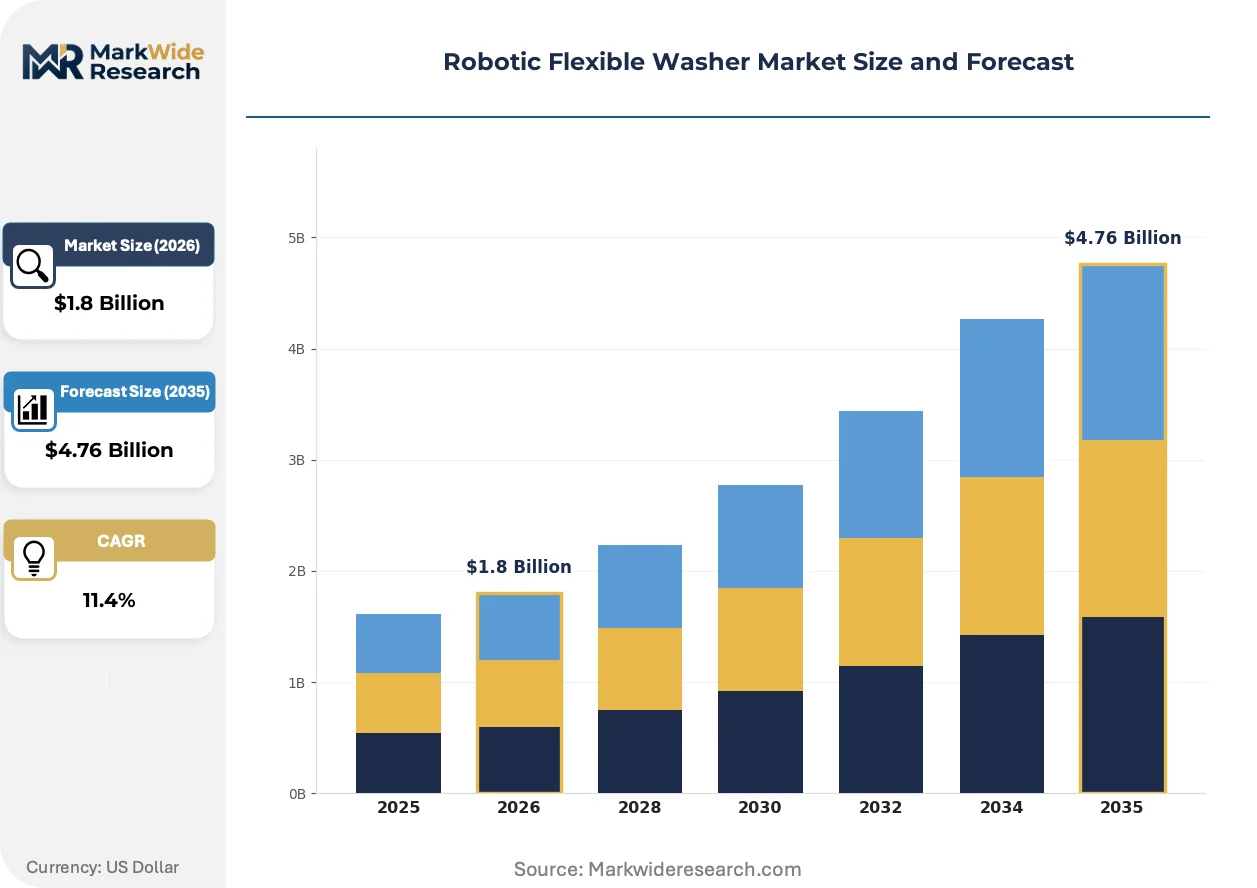
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Robotic Application: Aerospace, Automotive, Pharmaceutical, Electronics End User: Manufacturers, Service Providers, Laboratories, Automotive OEMs Technology: Ultrasonic, Laser, Chemical, Thermal |
| Companies Covered | ABB Group, Dynamic Robotic Solutions, BvL Oberflächentechnik GmbH, Durr Ecoclean, Cleaning Technologies Group, Fives Cinetic Corp, ADF Systems Ltd., Elwema Automotive GmbH, SBS Ecoclean Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Flexible Washer Market Strategic Shifts
Adaptive process control architectures are supplanting fixed-parameter washing recipes, enabling real-time adjustment of spray pressure and nozzle trajectory based on in-situ cleanliness verification.
Laser cleaning systems equipped with galvo-scanning optics and inline LIBS spectroscopy are rendering obsolete thermal and chemical methods for aerospace turbine blade refurbishment. MRO providers in Germany and the UK are retrofitting dry ablation cells at pace, compressing the installed base of vapor degreasing equipment and eliminating hazardous waste streams from precision finishing operations.
EPA NESHAP standards for halogenated solvent emissions are tightening capture efficiency mandates for vapor degreasing operations in the United States. Metalworking shops in Michigan and Ohio face capital decisions between emission control retrofits and aqueous robotic washer replacement, with tier-2 suppliers predominantly selecting closed-loop water-based systems to avoid ongoing compliance monitoring costs.
After-sales service unbundling is fragmenting traditional equipment vendor revenue models. Tier-1 automotive suppliers in Germany now procure robotic washer hardware, process chemistry, and predictive maintenance analytics from separate specialist providers, compressing OEM service contract attach rates and forcing equipment manufacturers toward modular platform architectures with open API interfaces.
Robotic Flexible Washer Market Segmentation
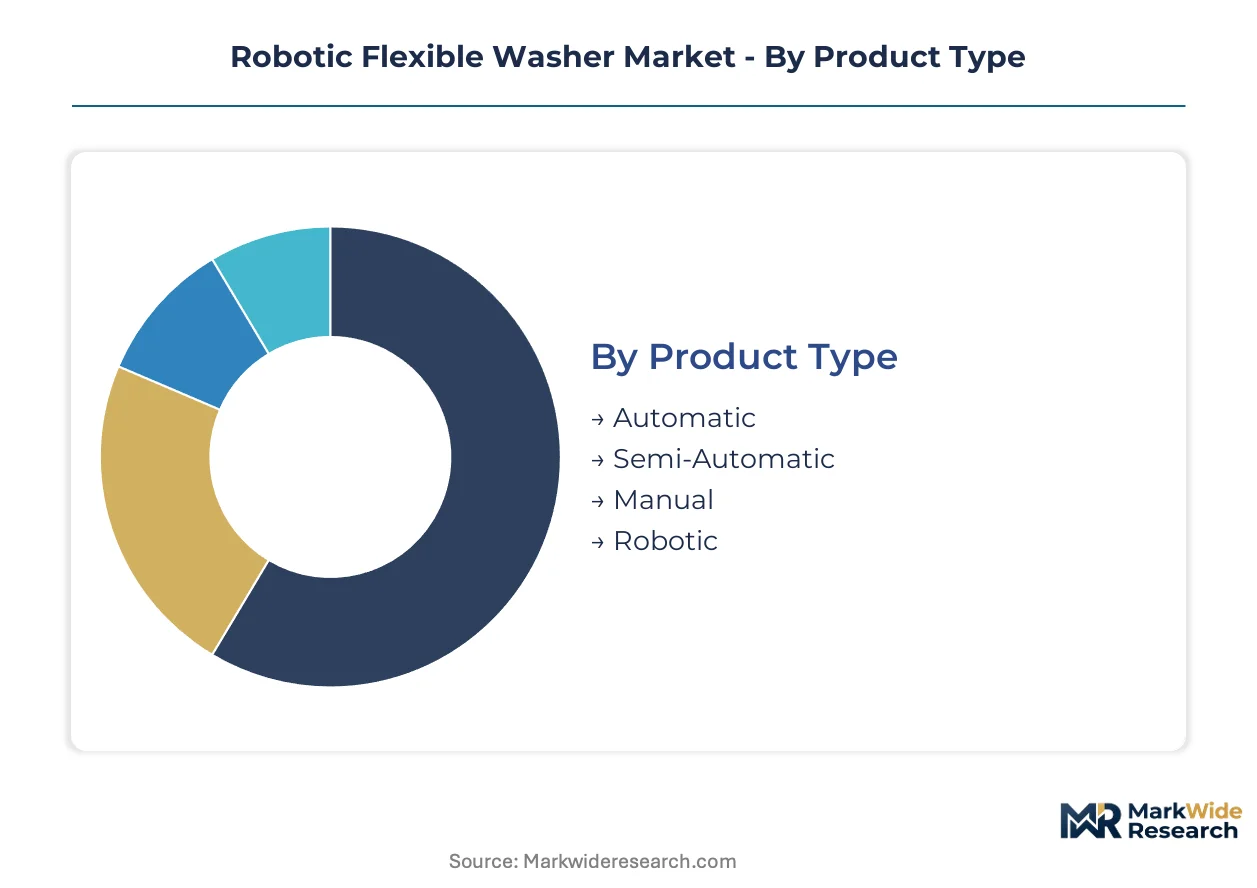
Segmentation in robotic flexible washers reveals how capital allocation priorities diverge across automation intensity levels and cleaning methodologies. Equipment specification cycles vary dramatically—some segments turn over in 3-4 years while others extend past a decade—creating distinct vendor competitive dynamics and aftermarket revenue profiles.
Product Type:
Cycle-time differentiation separates segments where format flexibility enables just-in-sequence production from fixed-architecture systems requiring mechanical retooling. Robotic cells compress changeover intervals from hours to minutes, while automatic and semi-automatic platforms trade adaptability for throughput density in stable product mixes.
- Robotic:Programmable multi-axis systems with articulated manipulators and interchangeable end-effectors deliver targeted aqueous, solvent, or abrasive media to complex geometries. Automotive OEMs in Germany's manufacturing belt prioritize these cells for electric drivetrain component cleaning where ISO 16232 particulate standards apply across battery housing and motor stator families without mechanical retooling.
- Automatic:Fixed-conveyor architectures with programmable logic controllers manage high-volume throughput for stable part families in tier-2 electronics supply chains. Michigan metalworking shops facing EPA NESHAP compliance deadlines select closed-loop automatic aqueous systems to avoid ongoing vapor degreasing emission monitoring costs.
- Semi-Automatic:Operator-assisted batch configurations bridge manual loading and automated processing for mid-volume precision manufacturers with mixed part geometries.
- Manual:Standalone wash stations with minimal automation serve laboratory validation environments and prototype production lines where throughput requirements remain below capital threshold for programmable systems.
Robotic systems dominate installed base value. Automatic platforms are where expansion concentrates in cost-sensitive tier-2 supplier tiers.
Application:
Cleanliness specification stringency creates tiered margin structures across end-use sectors, with aerospace and automotive commanding premium equipment configurations while pharmaceutical and electronics applications drive volume through standardized cell architectures.
- Aerospace:Precision turbine blade finishing demands sub-micron particulate removal where thermal and chemical methods face substitution pressure from dry laser ablation systems. MRO providers in Germany and the UK retrofit dry cleaning cells to eliminate hazardous waste streams from refurbishment operations.
- Automotive:Powertrain assembly lines pull flexible cells into just-in-sequence production for battery housings and motor stators as electric drivetrain manufacturing scales. Tier-1 suppliers retrofit existing lines to accommodate multiple vehicle platforms without dedicated washing machines per model generation.
- Electronics:Vacuum chamber and wafer handling component remanufacturing creates demand for precision cleaning with sub-micron guarantees in semiconductor capital equipment refurbishment chains.
- Pharmaceutical:Aseptic processing requirements and validated cleaning protocols drive specification toward closed-loop aqueous systems with documented traceability for regulatory submission packages.
Automotive applications anchor equipment volume. Aerospace represents the steepest expansion trajectory as laser ablation displaces solvent-based finishing.
End User:
Procurement sophistication varies sharply across customer types, with OEMs demanding open API architectures for predictive maintenance integration while service providers prioritize compact footprints for job-shop flexibility.
- Automotive OEMs:Capital equipment amortization across model generations drives preference for robotic platforms with modular chemistry compatibility and validated process guarantees for supplier qualification.
- Manufacturers:Tier-1 component producers in India's PLI scheme incentive zones seek first-mover robotic washer installations for advanced manufacturing qualification.
- Service Providers:MRO operations and job shops value compact cell footprints and rapid format changeover to accommodate diverse customer part families within limited floor space.
- Laboratories:R&D and quality assurance functions require manual and semi-automatic configurations with extensive documentation protocols for method validation and regulatory submission support.
Automotive OEMs concentrate capital deployment. Service providers are gaining share fastest as aftermarket refurbishment demand scales.
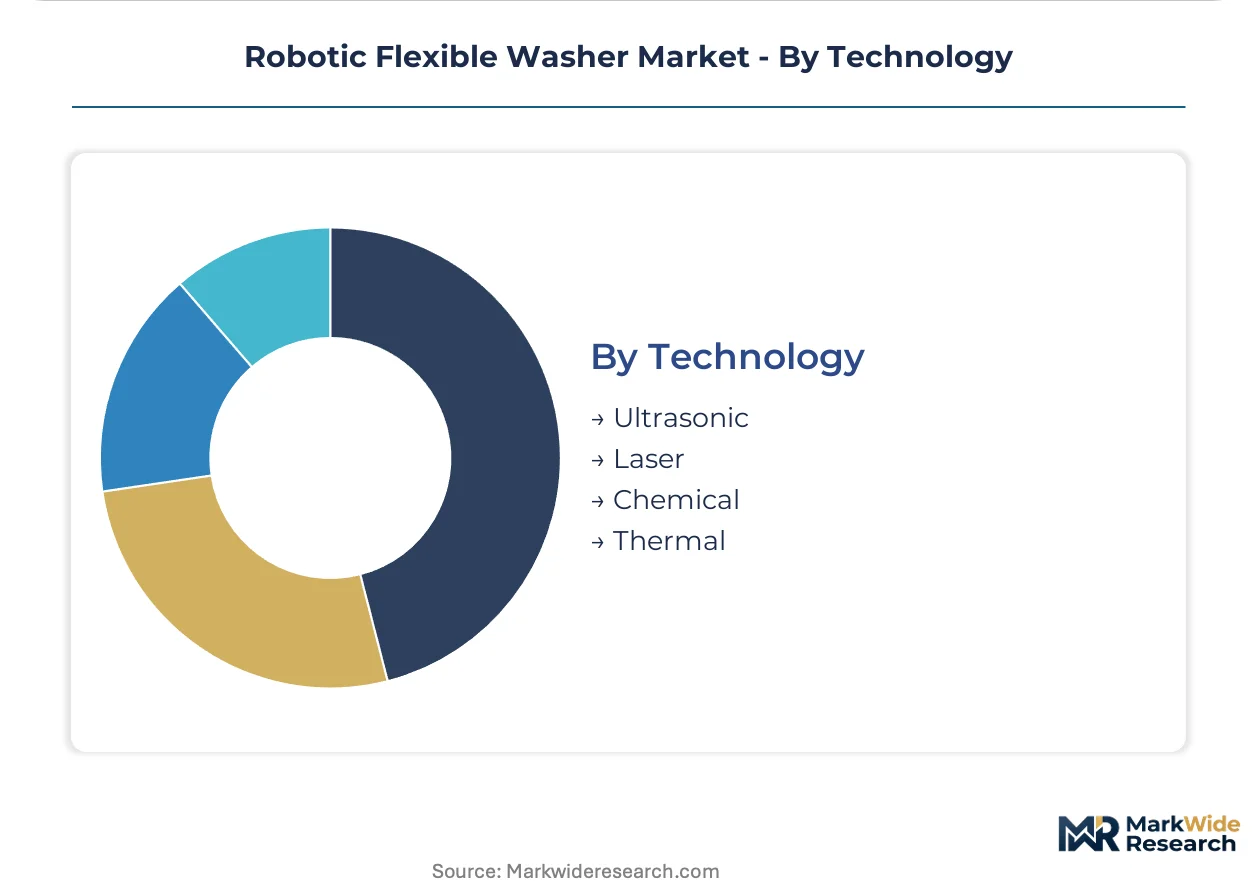
Technology:
Regulatory phase-downs of fluorinated and chlorinated solvents are resegmenting technology adoption curves, with aqueous and laser platforms capturing replacement demand while ultrasonic and thermal methods defend installed base positions.
- Ultrasonic:Cavitation-based cleaning with high-frequency transducer arrays delivers particulate removal in complex internal geometries for electronics and precision component applications.
- Laser:Galvo-scanning optics with inline LIBS spectroscopy enable dry ablation without consumable media or effluent treatment infrastructure, climbing fastest as EU F-Gas Regulation deadlines accelerate solvent system replacement.
- Chemical:Solvent vapor degreasing faces regulatory pressure from REACH substance evaluations and EPA NESHAP emission control mandates, compressing addressable market in favor of closed-loop alternatives.
- Thermal:Pyrolytic and plasma-based methods retain niche positions in specialized coating removal applications where substrate integrity constraints exclude mechanical or chemical alternatives.
Ultrasonic systems anchor installed base volumes. Laser cleaning is where vendor R&D investment and customer pilot programs concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment exports supply automotive assembly plants across Central and Eastern Europe, while Japanese precision component manufacturers serve aerospace MRO networks in Southeast Asia. Capital deployment concentrates in manufacturing corridors where regulatory deadlines for solvent phase-outs intersect with electric vehicle production scaling.
Germany
Battery housing and motor stator cleaning for electric drivetrains pulls flexible robotic cells into Stuttgart and Munich assembly corridors. The EU F-Gas Regulation accelerates solvent-to-aqueous conversions ahead of phase-down deadlines. Tier-1 suppliers in Baden-Württemberg retrofit washer cells for just-in-sequence production across multiple vehicle platforms.
United States
EPA NESHAP emission control mandates force capital decisions among Michigan and Ohio metalworking shops facing vapor degreasing compliance costs. Tier-2 suppliers select closed-loop aqueous robotic systems to eliminate ongoing monitoring overhead. Detroit-area powertrain plants integrate cleaning cells with battery module assembly lines.
China
Domestic EV production scaling creates demand for ISO 16232-compliant particulate removal in battery and motor manufacturing. MIIT industrial upgrading directives incentivize automation substitution for manual cleaning stations. Yangtze River Delta automotive clusters deploy flexible washer platforms to accommodate rapid model changeovers.
India
PLI scheme incentives for advanced manufacturing attract tier-1 automotive component producers seeking first-mover robotic washer installations. BIS standards alignment pressures equipment specification toward validated process guarantees. Tamil Nadu and Maharashtra supplier parks pilot flexible cleaning cells for export qualification to European OEMs.
United Kingdom
Aerospace MRO providers in the Midlands retrofit dry laser ablation cells for turbine blade refurbishment, eliminating hazardous waste streams. ECHA REACH substance evaluations block chlorinated hydrocarbon imports for vapor degreasing. Birmingham-area precision engineering shops transition to aqueous robotic platforms for defense subcontractor qualification.
Robotic Flexible Washer Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct value-capture tiers. The vendor base organizes around automation integrators with machine-vision capabilities, surface treatment specialists with proprietary indexing systems, and compact-cell fabricators for space-constrained installations. Consolidation pressure intensifies as automotive OEMs unbundle after-sales service contracts and demand open API architectures. Strategic moves concentrate on modular platform development and predictive maintenance analytics partnerships.
Among Germany-based surface technology specialists, BvL Oberflächentechnik GmbH and Elwema Automotive GmbH exemplify the precision-automation archetype with rotary indexing expertise. ABB Group represents the industrial-robotics integrator position with machine-vision integration capabilities. These three anchors occupy distinct competitive positions: the German specialists concentrate on automotive belt manufacturing, while the Swiss-Swedish integrator extends across aerospace and high-mix applications.
| Leading Market Players |
|---|
| ABB Group |
| Dynamic Robotic Solutions |
| BvL Oberflächentechnik GmbH |
| Durr Ecoclean |
| Cleaning Technologies Group |
| Fives Cinetic Corp |
| ADF Systems Ltd. |
| Elwema Automotive GmbH |
| SBS Ecoclean Group |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's robotic washer manufacturing cluster commands pricing leverage through concentrated machine-vision integration expertise and proximity to automotive OEM specification centers. Tier-1 suppliers face compressed negotiation windows as capacity tightens for aqueous chemistry-compatible cells ahead of EU F-Gas Regulation deadlines.
Pricing Analysis
Current-generation robotic cells carrying galvo-scanning laser modules command substantial premiums over legacy ultrasonic platforms, while next-generation adaptive process control architectures with inline LIBS spectroscopy sit at the apex of pricing hierarchies. Three-tier pricing structure across premium, standard, and economy levels separates ISO 16232-validated systems with predictive maintenance analytics from basic programmable cells and operator-assisted batch configurations. Price differentiation hinges on certification level and after-sales service bundling, with unbundled procurement models compressing vendor margins as automotive OEMs source process chemistry and maintenance analytics separately. Pricing pressure stems from tier-2 electronics suppliers in cost-sensitive segments, while aerospace MRO providers show lowest price sensitivity given hazardous waste elimination value.
Supply Chain Analysis
German and Japanese export-control frameworks on high-precision galvo-scanning optics and machine-vision components constrain component flows to non-aligned manufacturing jurisdictions. Supply concentrates in Germany, Japan, and Switzerland for robot kinematics and motion controllers, while China dominates aqueous chemistry formulation and ultrasonic transducer fabrication. Raw material dependencies span rare-earth magnets for servo motors, high-purity stainless steel for wash chambers, and specialized surfactant feedstocks from petrochemical complexes. Single-source vulnerability runs through German automation component vendors for multi-axis controllers. Distribution runs through tier-1 automotive supplier procurement consortiums and aerospace MRO service networks with direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
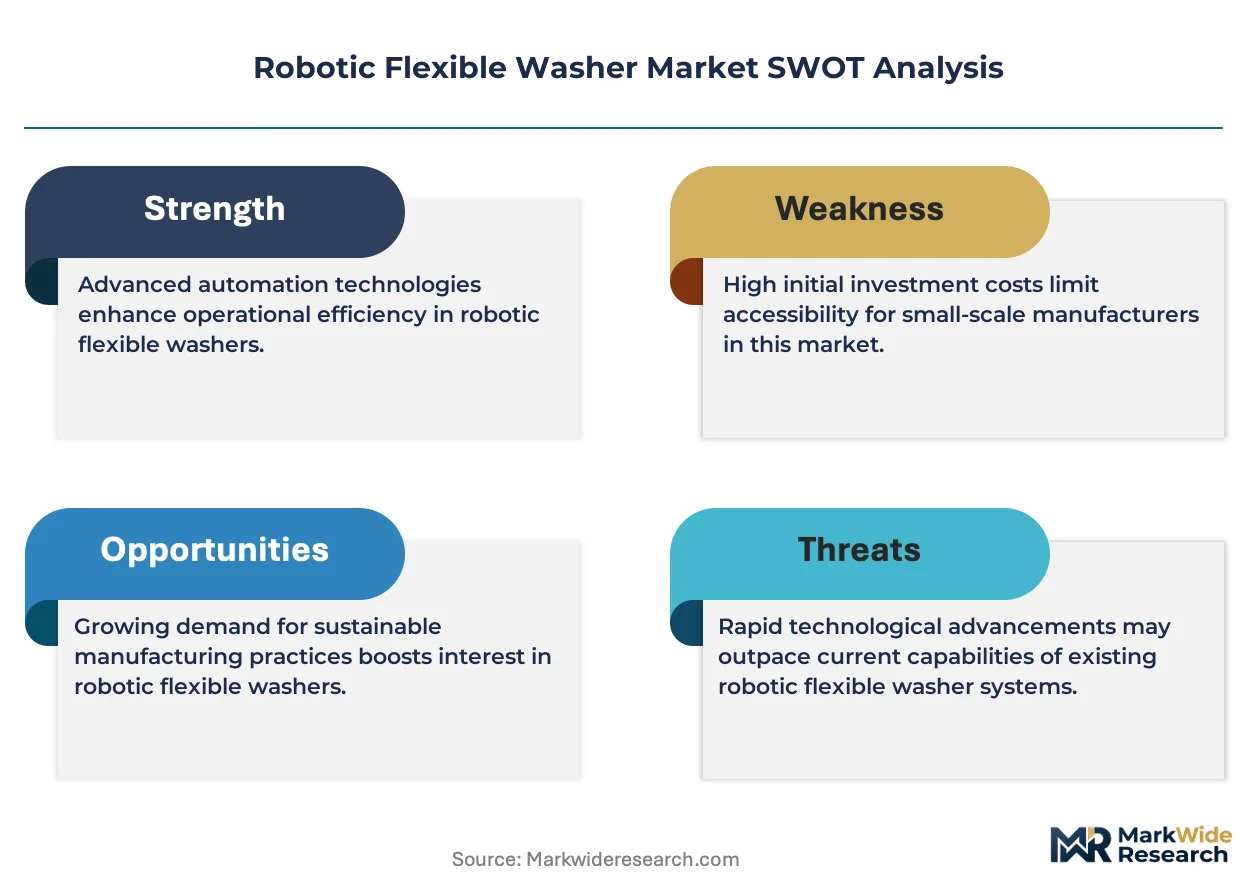
Few equipment vendors possess integrated capabilities across fluid dynamics simulation, robotics programming, and surface chemistry validation. This capability scarcity fragments competitive positioning and creates acquisition premiums for cross-trained engineering teams.
For Market Incumbents: Build switching-cost moats through predictive maintenance analytics integration and open API architectures that embed vendor ecosystems within customer SCADA infrastructures. Incumbents should secure backward integration into aqueous chemistry formulation to capture process chemistry margins now flowing to specialist providers. Laser ablation technology maturation threatens ultrasonic system incumbents; defend through accelerated R&D in adaptive nozzle path algorithms and inline cleanliness verification. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme incentive zones where tier-1 automotive component producers seek first-mover robotic washer installations for European OEM export qualification. Semiconductor capital equipment refurbishment represents penetrable white-space, with vacuum chamber remanufacturing demand outpacing specialized cleaning cell supply. Target service provider segments with compact footprint architectures for job-shop flexibility, leveraging modular platform designs that compress delivery timelines versus integrated incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with validated ISO 16232 process guarantees and installed base density in automotive belt manufacturing. Long-term viability over the next decade rests on aqueous chemistry compatibility and laser ablation integration capabilities rather than solvent-based legacy architectures. Acquisition target archetype: mid-cap specialists with rotary indexing expertise and established tier-1 automotive relationships. Watch for inflection signals in EU F-Gas Regulation enforcement acceleration or MIIT industrial upgrading directive expansion in China.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Platform Architecture Development | Enables unbundled procurement models that align with automotive OEM sourcing preferences across chemistry and analytics. |
| Laser Ablation Technology Integration | Eliminates consumable media costs and effluent infrastructure for aerospace turbine blade finishing operations in Germany. |
| Predictive Maintenance Analytics Partnership | Captures recurring revenue streams as tier-1 suppliers separate hardware procurement from service contracts. |
| Aqueous Chemistry Backward Integration | Secures margin pools currently diverted to specialist surfactant formulators facing petrochemical feedstock volatility. |
| India PLI Zone Manufacturing Footprint | Positions vendors for tier-1 supplier qualification under BIS standards alignment for European OEM export channels. |
Study Parameters
Initial hypotheses were tested against primary input from plant engineers at tier-1 automotive suppliers, aftermarket service heads at aerospace MRO providers, OEM procurement teams specifying cleaning cells, and aqueous chemistry formulators, then refined through secondary validation against SEC filings, customs and trade data on robotic washer imports, industry association technical reports, and patent filings on laser ablation innovations. Bottom-up equipment shipment tallies by technology type and application were triangulated against top-down capital expenditure surveys across precision manufacturing verticals.
Demand-supply balance modeling across the projection horizon incorporated electric drivetrain production scaling trajectories, regulatory phase-out schedules for fluorinated solvents, and replacement cycle timing for legacy vapor degreasing installations. Segmentation dimensions spanned product type, application, end user, and technology, with additional modeling of certification tier and aftermarket service bundling. CAGRs were derived from installed base turnover rates and capital equipment amortization patterns across automotive model generations. Industry-specific inputs included ISO 16232 validation timeline distributions and EU F-Gas Regulation compliance deadline clustering.
Sensitivities concentrate around enforcement acceleration of REACH substance evaluations, MIIT industrial upgrading directive expansion timelines, and petrochemical feedstock price volatility affecting aqueous chemistry input costs. Forecasts reflect documented assumptions on regulatory implementation pacing and technology substitution elasticities. Material shifts in EU F-Gas Regulation phase-down schedules or EPA NESHAP capture efficiency mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Delta Robots Market
Robotics and Automation
LAMEA Waste Sorting Robots Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Cordless Router Market
Robotics and Automation
Europe Robotics and Automation Actuators Market
Robotics and Automation
Robotic Process Automation (RPA) Market
Robotics and Automation
Articulated Robots for Injection Molding Machine Market
Robotics and Automation
Global Enterprise Robotic Process Automation Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
China Industrial Robots Market
Robotics and Automation
Robotics Technology Market
Robotics and Automation
Asia-Pacific Robotics and Automation Actuators Market
Robotics and Automation
Underwater Rescue Robot Market
Robotics and Automation
Household Robots Market