
 Pipetting Robots Market | 2026-2036
Pipetting Robots Market Size, Share, and Industry Trends Forecast 2026-2036
Pipetting Robots Market Outlook
The direct sales channel is narrowing as vendors consolidate relationships with large pharmaceutical buyers and group purchasing organizations. Beckman Coulter leverages its installed base in clinical diagnostics to sustain recurring revenue from consumables and service contracts. Eppendorf anchors its position in European academic markets through localized application support. Opentrons Labworks competes on open-source architecture, attracting contract research organizations seeking programmable flexibility without proprietary lock-in.
Pipetting robots are electromechanical systems that transfer measured liquid volumes with precision typically ranging from 0.1 microliters to milliliters, employing air displacement or positive displacement mechanisms for reproducible sample processing in analytical workflows. Their primary purpose is to eliminate human variability in repetitive liquid handling tasks across drug discovery, genomics, and clinical diagnostics. Liquid handling systems dominate current revenue due to integrated workflow automation, while software-integrated technology captures expanding margin pools as laboratories demand connectivity with laboratory information management systems. High-throughput screening applications lead volume deployment among pharmaceutical companies, though sample preparation grows fastest as proteomics and metabolomics workflows multiply.
The FDA enforces 21 CFR Part 11 compliance for electronic records in GMP environments, compelling vendors to embed audit trails and user access controls in software-integrated platforms. ISO 8655 standards govern piston-operated pipette calibration, directly affecting product design specifications and service revenue models. The EU In Vitro Diagnostic Regulation introduces new conformity assessment requirements for clinical laboratory equipment. Stakeholders must monitor evolving interoperability standards between robotic platforms and cloud-based data infrastructure as laboratories reconfigure around distributed computing architectures.
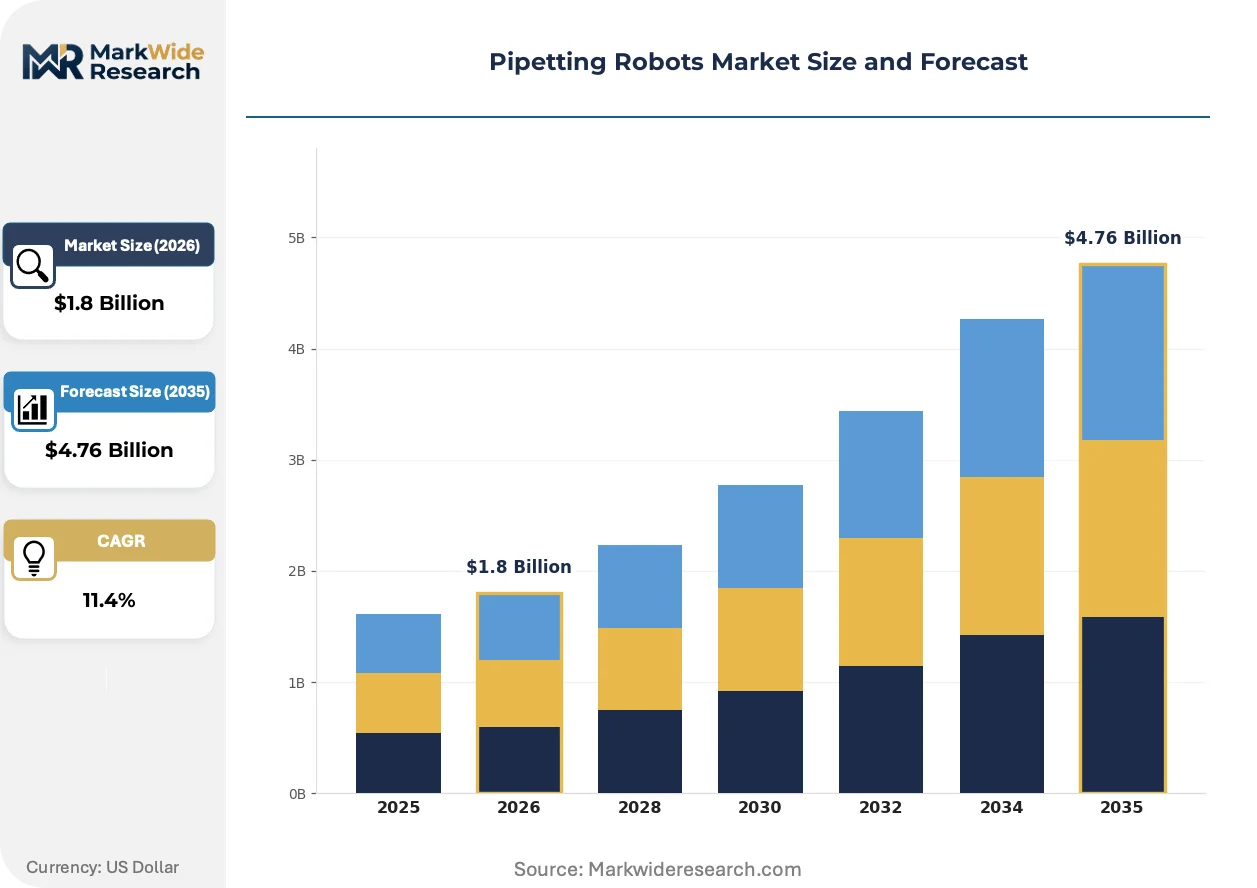
Market Dynamics
Academic research labs are consolidating liquid handling workflows around software-integrated platforms that satisfy FDA 21 CFR Part 11 audit trail requirements, compressing procurement cycles for standalone hardware vendors.
Growth Catalysts
- NIH funding cycles:Biennial grant disbursements in the United States accelerate capital equipment replacement timelines for research institutions upgrading from manual to automated pipetting systems.
- ISO 8655 calibration mandates:Piston-operated pipette accuracy standards drive recurring service contract revenue and hardware refresh demand in regulated quality control laboratories.
- Proteomics workflow expansion:Sample preparation automation for mass spectrometry-based protein analysis multiplies instrument deployment density in pharmaceutical discovery facilities.
Market Restraints
- Premium consumables lock-in:Proprietary tip and plate geometries from dominant vendors inflate per-run operating costs for high-throughput screening facilities.
- Validation documentation burden:FDA 21 CFR Part 11 compliance requirements extend software qualification timelines and strain internal quality assurance resources.
- Precision mechanism supply concentration:Linear actuator and optical sensor sourcing depends on concentrated East Asian manufacturing clusters.
Strategic Opportunities
- Contract research organization channel:Programmable open-architecture systems attract CROs seeking workflow flexibility without proprietary ecosystem commitments.
- EU In Vitro Diagnostic Regulation:New conformity assessment pathways for clinical laboratory equipment create first-mover advantages for vendors with established notified body relationships.
- Cloud-based data infrastructure convergence:Integration between robotic platforms and distributed computing architectures enables remote monitoring and predictive maintenance service models.
Industry Challenges
- Cross-functional automation expertise:Laboratories struggle to recruit personnel combining liquid handling mechanics, software scripting, and regulatory documentation skills.
- Legacy LIMS integration complexity:Proprietary communication protocols from established laboratory information management systems obstruct seamless data flow with newer robotic controllers.
- Installation qualification timelines:Site acceptance testing and operational qualification procedures delay revenue recognition and consume field service engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipetting Robots Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Pipettes, Liquid Handling Systems, Multi-Channel Pipettes, Single-Channel Pipettes End User: Pharmaceutical Companies, Academic Research Labs, Clinical Laboratories, Biotechnology Firms Technology: Robot-Assisted, Telemanipulation, Liquid Dispenser, Software-Integrated Application: High-Throughput Screening, Sample Preparation, DNA Sequencing, Assay Development |
| Companies Covered | Beckman Coulter Inc., Eppendorf AG, Thermo Fisher Scientific Inc., INTEGRA Biosciences AG, Mettler-Toledo International Inc., Tecan Group Ltd., Hamilton Company, Opentrons Labworks Inc., Agilent Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipetting Robots Market Strategic Shifts
Electromechanical precision is converging with software-defined workflow control, reshaping how laboratories configure automation around dynamic assay requirements rather than fixed hardware specifications.
Adaptive pipetting technology is hybridizing air displacement and positive displacement mechanisms within single instrument architectures. Genomics core facilities are adopting these hybrid systems to handle viscosity-spanning sample types without hardware swaps. The technology is hybridizing instrument purchasing patterns, compressing capital expenditure into unified platforms rather than specialized devices.
The EU In Vitro Diagnostic Regulation introduces expanded technical documentation and post-market surveillance obligations for equipment deployed in clinical diagnostic settings. Manufacturers must restructure quality management systems to accommodate notified body involvement previously unnecessary for research-use-only products. Clinical laboratory segments in Germany and France are accelerating procurement decisions to secure legacy-compliant inventory before transition deadlines.
Service unbundling is fragmenting traditional capital-plus-maintenance contracts into discrete software subscription, consumables auto-replenishment, and on-demand validation support components. Academic buyers with constrained capital budgets are gravitating toward operational expenditure models that preserve grant flexibility. This pattern concentrates in United States research institutions navigating irregular federal funding cycles.
Pipetting Robots Market Segmentation
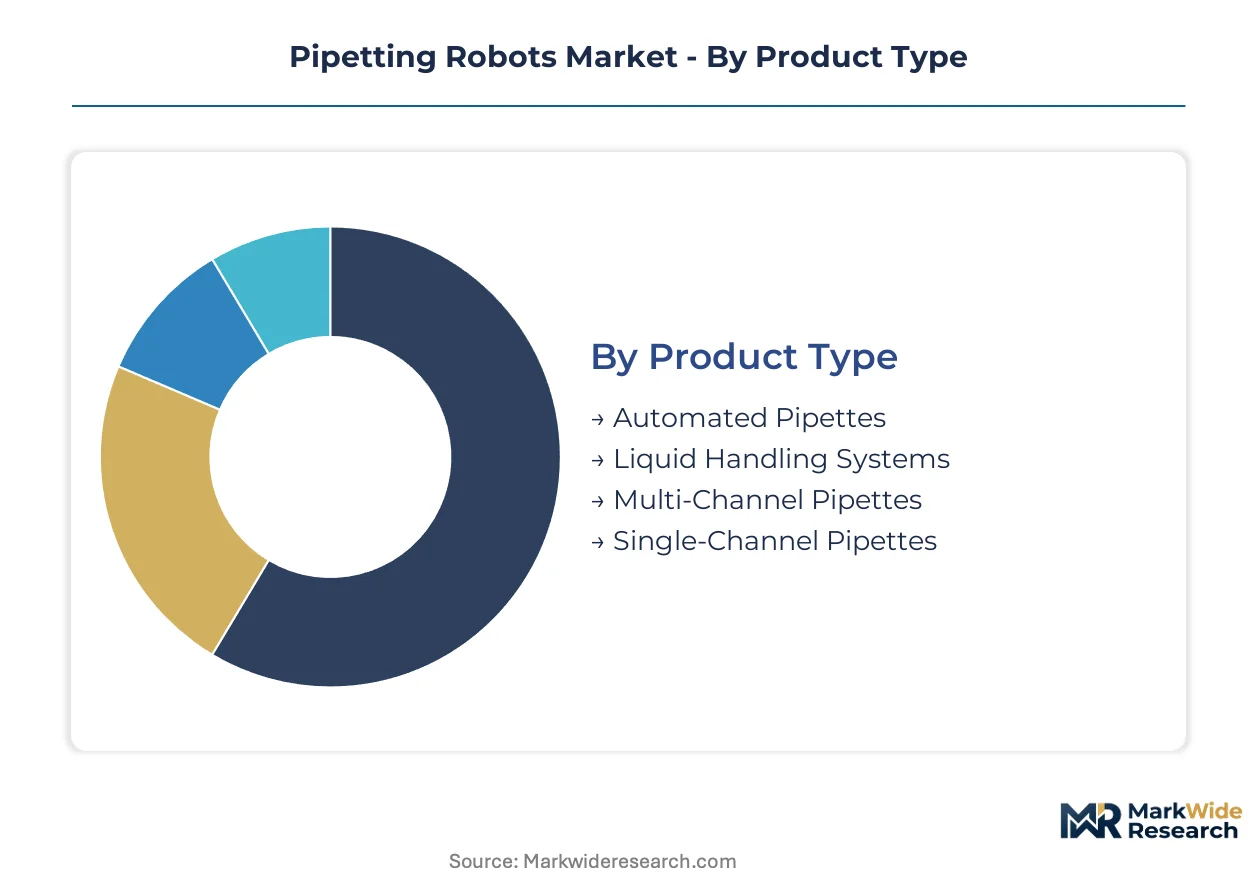
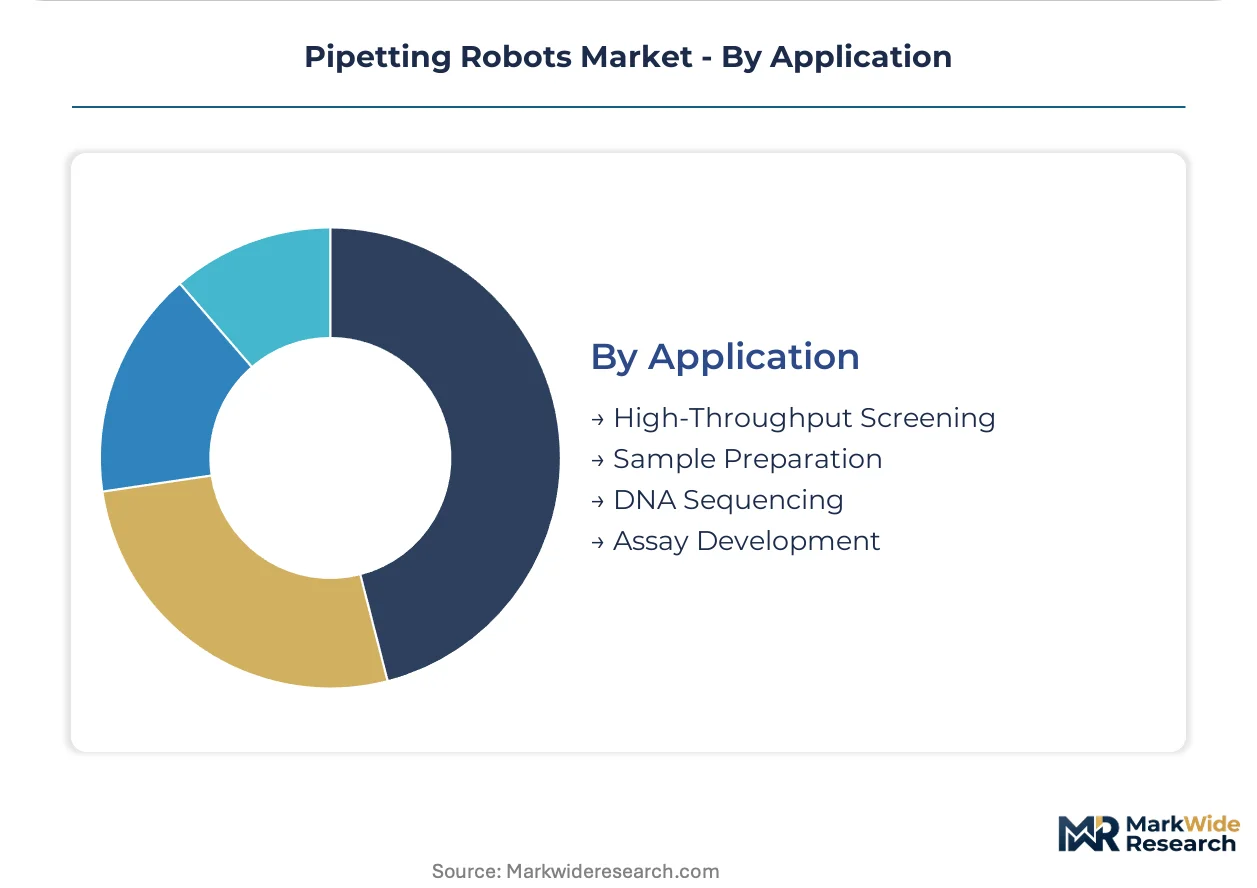
Pipetting robots serve distinct workflow intensities across discovery, diagnostic, and research environments. Segmentation reveals how hardware specifications, software depth, and throughput requirements map to customer budgets and regulatory exposure.
Product Type:
Equipment selection spans from benchtop devices for individual researchers to integrated workstations for facility-wide automation.
- Liquid Handling Systems:Integrated workstations combine pipetting mechanics with plate handling, incubation, and detection modules for walkaway automation. Pharmaceutical discovery facilities in the United States deploy these systems for campaign-scale high-throughput screening, driven by NIH funding cycles that compress procurement timelines.
- Automated Pipettes:Standalone electromechanical devices execute programmed pipetting sequences without external robotics. Academic research labs favor these units for grant-funded projects requiring flexibility between manual and automated modes.
- Multi-Channel Pipettes:Parallel dispensing heads transfer 8- to 384-well formats simultaneously. Genomics core facilities utilize these for PCR setup and next-generation sequencing library preparation.
- Single-Channel Pipettes:Individual dispensing mechanisms handle variable volumes with highest precision for low-throughput applications. Quality control laboratories specify these for ISO 8655-compliant calibration workflows.
Established volume favors liquid handling systems; emerging adoption favors automated pipettes.
End User:
Customer archetypes differ in capital availability, validation burden, and consumables commitment.
- Pharmaceutical Companies:Large-scale automation programs integrate pipetting robots into fully validated discovery and development pipelines. Boston and San Diego biotech clusters concentrate procurement from vendors offering 21 CFR Part 11-compliant audit trails.
- Academic Research Labs:Grant-dependent institutions prioritize open-architecture systems with programmable flexibility. European universities anchor demand for localized application support and training infrastructure.
- Biotechnology Firms:Venture-funded startups balance throughput requirements against capital constraints. These organizations gravitate toward subscription-based service models that preserve cash runway.
- Clinical Laboratories:Diagnostic settings demand equipment meeting EU In Vitro Diagnostic Regulation conformity standards. German and French facilities are accelerating procurement ahead of transition deadlines.
Pharmaceutical companies dominate current revenue; biotechnology firms are climbing the fastest.
Technology:
Architecture choices determine integration depth, vendor lock-in exposure, and qualification complexity.
- Software-Integrated:Platforms embed laboratory information management system connectivity, remote monitoring, and predictive maintenance capabilities. Cloud-based data infrastructure convergence is expanding margin pools as laboratories reconfigure around distributed computing architectures.
- Robot-Assisted:Collaborative robotic arms position pipetting modules for adaptive workflow reconfiguration. Contract research organizations deploy these for assay development requiring rapid protocol changes.
- Liquid Dispenser:Dedicated fluidic subsystems handle bulk reagent distribution without precision pipetting mechanics. High-throughput screening facilities use these for compound library management.
- Telemanipulation:Operator-guided remote control enables precise intervention for complex or unusual sample types. Specialized proteomics workflows employ this mode for viscosity-spanning preparations.
Software-integrated platforms command premium positioning; robot-assisted configurations gain share fastest.
Application:
Use-case segmentation tracks how automation intensity varies across the research-to-clinical continuum.
- High-Throughput Screening:Massive parallel compound testing against biological targets demands unattended operation across multi-day campaigns. Pharmaceutical companies deploy liquid handling systems at maximum density for lead identification.
- Sample Preparation:Extraction, purification, and normalization workflows precede analytical measurement. Proteomics and metabolomics expansion is multiplying instrument deployment density in discovery facilities.
- DNA Sequencing:Library construction and normalization require precise volumetric control for next-generation sequencing platforms. Genomics core facilities automate these steps to manage sample queue depth.
- Assay Development:Iterative optimization of detection methods benefits from programmable liquid handling flexibility. Biotechnology firms utilize adaptive pipetting technology during candidate validation.
High-throughput screening anchors current deployment; sample preparation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States biotech clusters while European procurement cycles elongate under regulatory transition timelines. NIH funding velocity in Boston and San Diego accelerates capital deployment faster than German academic budgets adapt to EU In Vitro Diagnostic Regulation compliance costs.
United States
NIH grant disbursements drive biennial equipment replacement cycles at research institutions upgrading from manual to automated systems. FDA 21 CFR Part 11 requirements shape validation protocols for software-integrated platforms in GMP environments. Boston and San Diego biotech clusters concentrate demand for high-throughput screening systems among pharmaceutical discovery facilities.
Germany
Academic research labs anchor European demand for localized application support and training infrastructure. EU In Vitro Diagnostic Regulation introduces expanded technical documentation obligations for clinical laboratory equipment. Bavarian precision engineering clusters supply linear actuator components while clinical facilities in Baden-Württemberg accelerate procurement ahead of transition deadlines.
China
Domestic pharmaceutical manufacturing expansion multiplies demand for quality control automation in regulated environments. NMPA medical device regulations increasingly align with international standards for software-integrated laboratory equipment. Yangtze River Delta biopharma manufacturing zones deploy liquid handling systems for contract manufacturing organization workflows.
United Kingdom
Research-intensive universities prioritize open-architecture systems preserving grant flexibility across irregular funding cycles. MHRA post-Brexit regulatory pathways create parallel conformity assessment requirements for clinical laboratory equipment. London-Oxford-Cambridge life science clusters concentrate genomics core facility automation deployments.
Switzerland
Precision instrument manufacturing heritage sustains export-oriented production of high-accuracy pipetting mechanisms. Swissmedic medical device regulations govern software validation for diagnostic applications. Basel pharmaceutical headquarters drive demand for validated automation platforms in drug discovery workflows.
Pipetting Robots Market Competitive Environment
Diversified life science conglomerates and specialized automation firms split the market along integration-depth lines. Consolidation pressure intensifies as large pharmaceutical buyers consolidate vendor relationships through group purchasing organizations. Three archetypes dominate: full-workflow integrators owning plate handling and detection modules; precision mechanics specialists controlling actuator and sensor supply; and open-architecture disruptors attacking proprietary consumables lock-in. Competitive moves center on M&A for workflow integration capabilities and strategic partnerships for cloud-based data infrastructure connectivity.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify full-workflow integration archetypes spanning sample preparation through analytical detection. Tecan Group Ltd. anchors the precision mechanics specialist tier with Swiss-engineered liquid handling architectures. Opentrons Labworks Inc. occupies the open-architecture disruptor position, attracting contract research organizations seeking programmable flexibility without proprietary ecosystem commitments.
| Leading Market Players |
|---|
| Beckman Coulter Inc. |
| Eppendorf AG |
| Thermo Fisher Scientific Inc. |
| INTEGRA Biosciences AG |
| Mettler-Toledo International Inc. |
| Tecan Group Ltd. |
| Hamilton Company |
| Opentrons Labworks Inc. |
| Agilent Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters feed precision linear actuators and optical sensors to downstream pipetting robot assemblers, concentrating component bargaining power among East Asian suppliers and compressing margin flexibility for systems integrators in North America and Europe. This geographic sourcing pattern shapes how vendors structure pricing tiers and manage cost volatility across software-integrated and hardware-centric product lines.
Pricing Analysis
Configured-to-order pricing commands a substantial premium over standard catalog configurations, with customization premiums reflecting engineering validation hours and regulatory documentation burdens. The dominant pricing structure stratifies across premium, standard, and economy tiers, with differentiation driven by ISO 8655 calibration certification level and after-sales service bundling. Pricing pressure stems from academic buyer consolidation around operational expenditure models that preserve grant flexibility. Biotechnology firms exhibit highest price sensitivity due to venture capital runway constraints, while pharmaceutical discovery facilities show lowest sensitivity given GMP compliance mandates.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for electromechanical precision components. Manufacturing concentration centers on China, South Korea, and Japan for linear actuators, optical encoders, and machined aluminum frames. Raw material dependencies include rare-earth magnets for motor assemblies, borosilicate glass for precision fluidic channels, and medical-grade polymers for consumable tips. Single-source vulnerability persists for sub-micron tolerance ball screws. Distribution runs through direct sales teams for large pharmaceutical accounts and specialized life science distributors for academic and mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pipetting robot markets are approaching a platform-economics inflection as cloud-based data infrastructure convergence reconfigures vendor value capture around software subscription rather than hardware shipment. Interoperability standards between robotic controllers and distributed computing architectures are reshaping competitive moats.
For Market Incumbents: Harden software-integrated platform architectures against open-source disruptors by embedding predictive maintenance capabilities and remote monitoring APIs that deepen customer switching costs. Consolidate relationships with group purchasing organizations to defend consumables recurring revenue streams. Invest in notified body pre-certification for EU In Vitro Diagnostic Regulation compliance to capture first-mover advantages in clinical laboratory segments.
For New Entrants and Emerging Players: German academic research labs represent underpenetrated whitespace where localized application support and training infrastructure remain undersupplied by incumbent vendors. Target contract research organizations with programmable open-architecture systems that eliminate proprietary consumables lock-in. Pursue subscription-based service models that align with irregular NIH funding cycles and preserve buyer capital flexibility.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision mechanics specialists with captive actuator manufacturing and established calibration service networks. Long-term viability rests on vendors controlling both hardware reliability and software connectivity layers. Acquisition target archetypes include hybrid pipetting technology developers bridging air displacement and positive displacement mechanisms. Watch for FDA 21 CFR Part 11 enforcement intensity as signal for validation documentation service demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Enables remote monitoring and predictive maintenance service models for distributed laboratory networks. |
| EU IVDR Certification Pathway | Secures notified body relationships ahead of clinical laboratory equipment transition deadlines in Germany and France. |
| Open-Architecture Platform Launch | Attracts contract research organizations seeking programmable flexibility without proprietary consumables lock-in. |
| Consumables Auto-Replenishment Service | Converts capital expenditure buyers to operational expenditure models preserving academic grant flexibility. |
| Precision Mechanics Acquisition | Captures linear actuator and optical sensor supply security for margin control and delivery reliability. |
Study Parameters
Initial hypotheses were tested against primary input from laboratory automation directors, regulatory affairs specialists at instrument manufacturers, academic procurement officers, and GPO contracts managers, and refined through secondary validation against FDA 21 CFR Part 11 guidance documents, ISO 8655 calibration standards, EU In Vitro Diagnostic Regulation technical documentation requirements, and SEC filings from diversified life science conglomerates. Bottom-up demand modeling across end-user segments was triangulated with top-down market sizing from equipment shipment analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end-user archetype, technology architecture, and application intensity. CAGRs were derived from equipment replacement cycle analysis, NIH funding disbursement patterns, and proteomics workflow expansion trajectories. Industry-specific forecast inputs included ISO 8655 calibration mandate compliance timelines and EU In Vitro Diagnostic Regulation transition deadlines.
Practitioners should monitor NIH appropriations volatility, East Asian manufacturing cluster disruption indicators, and FDA software validation enforcement intensity for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Smart Personal Assistance Devices Market
Robotics and Automation
Industrial Robotics Market
Robotics and Automation
Consumer Robotics Market
Robotics and Automation
Asia-Pacific AUV and ROV Market
Robotics and Automation
Robotic Desktop Automation (RDA) Market
Robotics and Automation
Internet of Robotic Things Market
Robotics and Automation
AGV Dispatch Management Platforms Market
Robotics and Automation
Robot Label Applicators Market
Robotics and Automation
Logistics Robots Market
Robotics and Automation
Underwater Jetpack Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
China Autonomous Mobile Robot Market
Robotics and Automation
Healthcare Mobile Robots Market
Robotics and Automation
Exoskeleton Systems Market
Robotics and Automation
Global Machine Vision and Vision Guided Robotics Market
Robotics and Automation
Europe Agricultural Robot Market