
 Autonomous Mobile Robots for Logistics and Warehousing Market | 2026-2036
Autonomous Mobile Robots for Logistics and Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Mobile Robots for Logistics and Warehousing Market Outlook
Buyer concentration among third-party logistics providers is repositioning procurement leverage toward fleet-scale contracts with multi-site deployment clauses. Amazon Robotics leverages captive warehouse demand to sustain high utilization rates across its fulfillment network. KION Group anchors European manufacturing scale through its Linde and Still brand assembly plants in Germany and the Czech Republic. Geek+ competes on AI-driven picking density in Asian e-commerce fulfillment centers.
Autonomous mobile robots for logistics and warehousing are self-navigating material handling systems that integrate lidar, camera arrays, and onboard computing to transport, sort, or retrieve inventory without fixed infrastructure or human operators; units typically operate at speeds up to two meters per second and coordinate through fleet management software to optimize path planning in dynamic environments. Picking robots dominate current deployment value as labor substitution in piece-picking operations commands premium pricing, while transport robots represent the fastest-expanding installed base due to simpler integration requirements in brownfield warehouses. AI-driven navigation systems concentrate margin pools as machine learning-enabled obstacle recognition reduces incident liability and enables operation in unstructured aisles shared with human workers.
OSHA workplace safety standards and the EU Machinery Directive shape product certification requirements for collaborative operation in shared human-robot zones, while the EU AI Act imposes risk classification and conformity assessment obligations on autonomous decision-making systems deployed in European logistics facilities. The FCC governs wireless spectrum allocation for fleet communication networks in US distribution centers, creating spectrum-access dependencies for cloud-coordinated multi-robot systems. Stakeholders must monitor evolving liability frameworks for autonomous incidents and assess whether regional certification divergence will fragment vendor product architectures or drive modular compliance platforms.
Market Dynamics
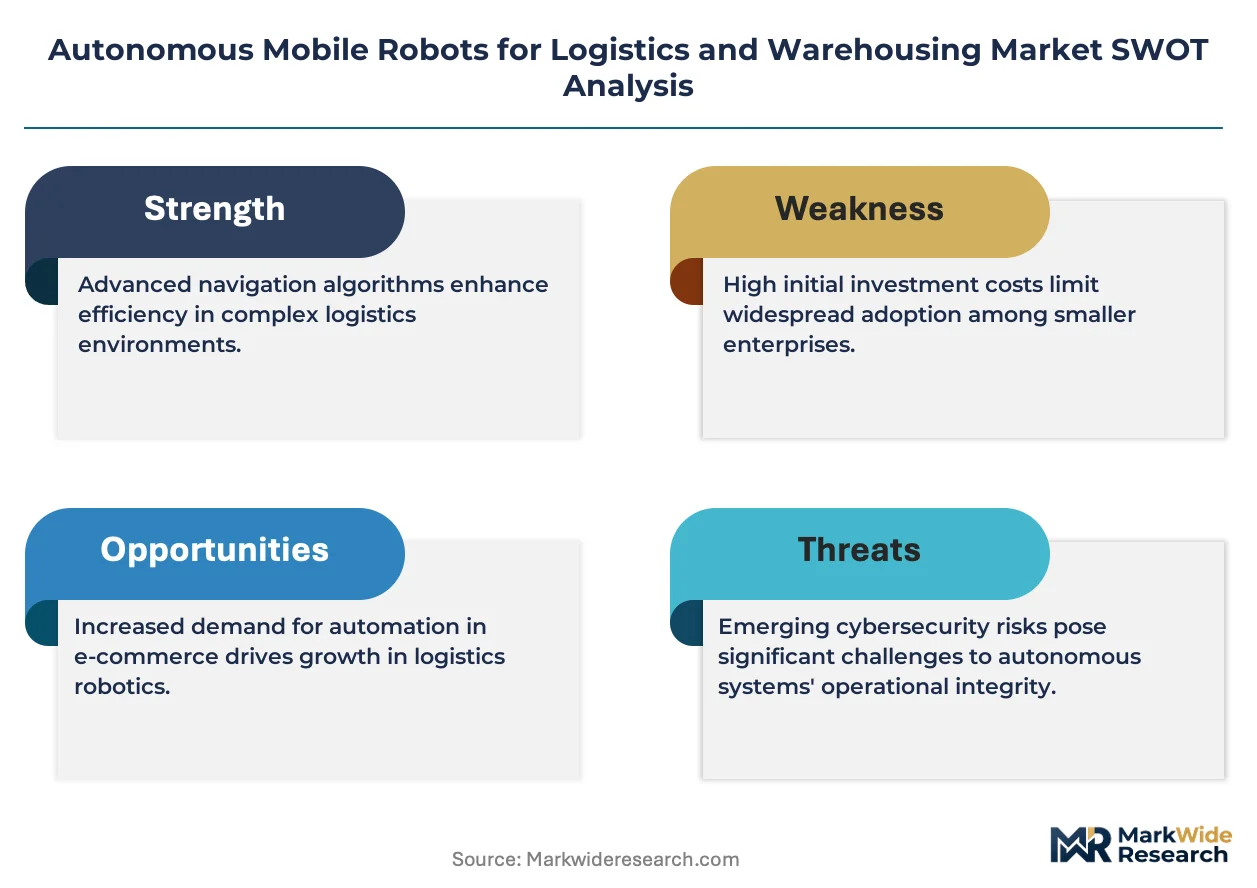
Fleet-scale procurement by third-party logistics providers is compressing vendor margins and forcing modular platform architectures that support multi-site standardization across heterogeneous warehouse footprints.
Growth Catalysts
- EU AI Act compliance mandates:Risk classification requirements for autonomous decision-making systems are accelerating replacement cycles in European distribution centers as facilities preempt 2025 enforcement deadlines.
- Same-day delivery fulfillment density:E-commerce order profiles below 24-hour windows are forcing parcel sortation hubs to deploy transport-class AMRs for inter-zone material flow optimization.
- Lidar cost deflation:Solid-state sensor manufacturing scale in Asian component clusters is collapsing per-unit navigation hardware costs below the threshold for mid-size warehouse automation.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack sourcing dependency on East Asian cathode material refining creates input cost volatility and forced allocation risk during demand spikes.
- Brownfield integration complexity:Legacy warehouse management system architectures in North American 3PL networks impose API interoperability barriers that extend deployment timelines.
- Human-robot collaborative safety certification:OSHA and EU Machinery Directive conformance testing for shared-aisle operation adds six-to-nine month pre-deployment validation cycles.
Strategic Opportunities
- Cold-chain pharmaceutical handling:Temperature-controlled AMR variants for vaccine and biologics distribution represent underpenetrated white space in German and Swiss logistics corridors.
- 5G private network deployment:Ultra-reliable low-latency communication infrastructure in Japanese automotive supplier parks enables cloud-coordinated fleet densities previously constrained by Wi-Fi spectrum contention.
- CE marking modularization:Vendors developing swappable compliance subsystems can accelerate European market entry without full platform redesigns for each member state notification body.
Industry Challenges
- Fleet orchestration software talent scarcity:Multi-agent path planning algorithm development requires robotics PhD-level expertise concentrated in select academic clusters.
- Retrofit capex allocation friction:Warehouse operators face internal competition for automation budgets against conveyor system expansions with faster depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Mobile Robots for Logistics and Warehousing Market |
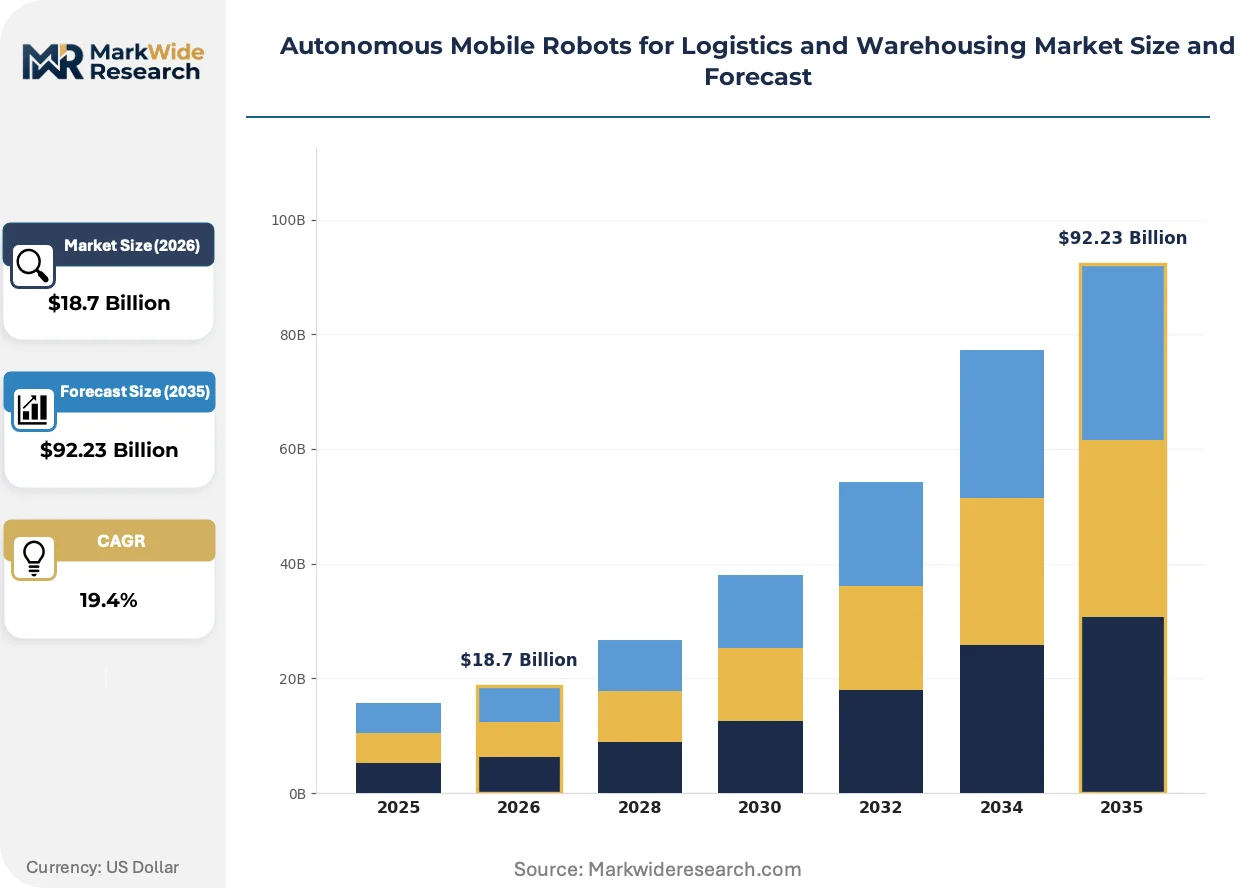
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $92.23 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Picking Robots, Transport Robots, Inventory Robots, Automated Guided Vehicles Technology: AI-Driven, Vision-Based, Laser Navigation, Magnetic Navigation End User: E-Commerce, Retail, Manufacturing, Third-Party Logistics Deployment Model: On-Premise, Cloud-Based, Hybrid, Integrated Systems |
| Companies Covered | Amazon Robotics, KION Group, ABB, Daifuku, KUKA, Geek+, Locus Robotics, Mobile Industrial Robots, Swisslog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Mobile Robots for Logistics and Warehousing Market Strategic Shifts
Navigation autonomy is migrating from infrastructure-dependent to infrastructure-agnostic modalities, collapsing the historical distinction between greenfield and brownfield deployment economics.
Computer vision-based localization is converging with edge inference accelerators to enable camera-only navigation stacks that eliminate mechanical lidar maintenance in dusty warehouse environments. Pharmaceutical distributors in the Rhine-Ruhr corridor are piloting these systems for VNA (very narrow aisle) pallet retrieval. The shift is compressing total cost of ownership curves and displacing legacy magnetic tape guidance in facilities with high SKU velocity.
The EU AI Act's risk classification framework for autonomous mobile machinery is forcing vendors to restructure software update protocols and establish European authorized representative structures. German automotive supplier parks face the steepest compliance burden given their density of collaborative human-robot operations. Vendors are responding with conformity assessment pre-certification programs that front-load documentation requirements before 2025 enforcement windows.
Third-party logistics procurement teams are consolidating vendor relationships around platform-as-a-service contracts that unbundle hardware ownership from fleet management software subscriptions. This model displaces traditional capital purchase agreements in North American parcel sortation hubs. The shift is most visible among Amazon Robotics competitors seeking to penetrate captive fulfillment networks through operational expenditure alignment rather than upfront asset sales.
Autonomous Mobile Robots for Logistics and Warehousing Market Segmentation
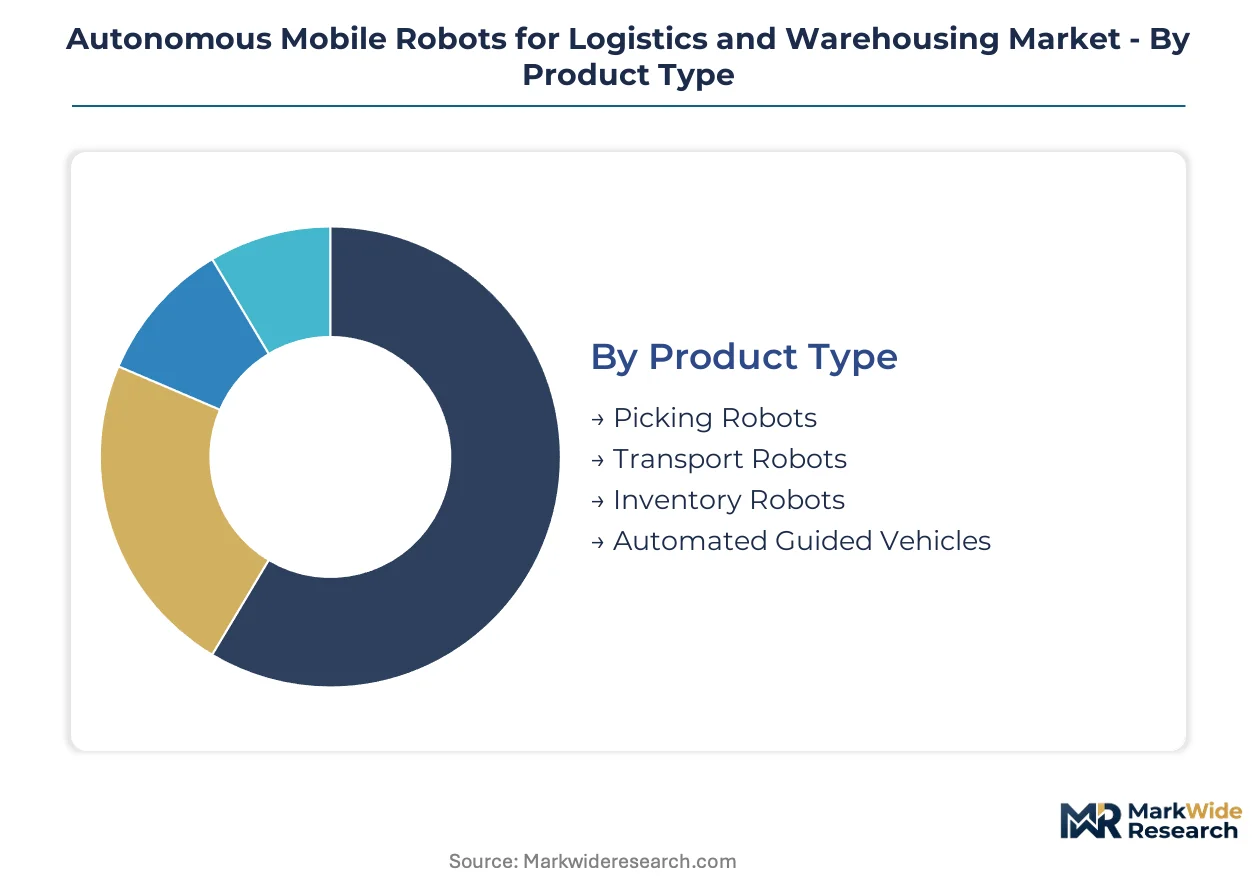
Procurement teams in logistics and warehousing evaluate AMR solutions through multiple technical and commercial lenses simultaneously. Product architecture, navigation modality, and ownership economics each reshape vendor selection criteria and deployment timelines. Understanding these segmentation layers clarifies where margin pools concentrate and which technology bets carry the highest strategic stakes.
Product Type:
Fleet managers prioritize payload flexibility and integration complexity when selecting robot categories for specific material handling workflows.
- Picking Robots:Articulated manipulator arms with suction or gripper end-effectors retrieve individual SKUs from storage totes at rates exceeding human picker throughput. Pharmaceutical distributors in Germany deploy these for high-value, low-weight biologics where picking accuracy directly impacts patient safety.
- Transport Robots:Unit-load carriers with differential drive kinematics move pallets and cartons between dock doors, mezzanines, and sortation zones without fixed conveyor infrastructure. Parcel hubs in the Netherlands rely on these for same-day delivery velocity where reconfigurable routes matter more than maximum speed.
- Inventory Robots:Autonomous scanning platforms equipped with RFID readers and barcode imagers traverse aisles to verify stock positions and cycle-count accuracy. These reduce manual audit labor in high-SKU e-commerce facilities.
- Automated Guided Vehicles:Wire-guided or tape-follower systems with deterministic routing paths serve repetitive point-to-point moves in automotive supplier parks with stable production schedules.
Volume sits with Transport Robots given their simpler deployment economics; growth tilts toward Picking Robots as labor substitution commands premium pricing in piece-picking operations.
Technology:
Navigation modality determines capital intensity, maintenance burden, and operational flexibility in heterogeneous warehouse environments.
- AI-Driven:Deep learning-based obstacle recognition and path planning algorithms enable operation in unstructured aisles shared with human workers and temporary equipment. The EU AI Act imposes risk classification and conformity assessment obligations on these systems in European distribution centers.
- Vision-Based:Camera-only localization stacks leveraging edge inference accelerators eliminate mechanical lidar maintenance in dusty fulfillment environments. Rhine-Ruhr pharmaceutical distributors pilot these for very narrow aisle pallet retrieval.
- Laser Navigation:Lidar-based simultaneous localization and mapping provides centimeter-grade positioning accuracy in facilities with dynamic obstacle profiles.
- Magnetic Navigation:Tape or wire-following guidance systems offer deterministic routing at lowest hardware cost but require infrastructure modifications for route changes.
Installed base concentrates in Laser Navigation; expansion rates are steepest for AI-Driven stacks as solid-state sensor cost deflation collapses hardware barriers.
End User:
Operational requirements and order profile characteristics shape which AMR capabilities command procurement priority across industry verticals.
- E-Commerce:Order fulfillment networks with sub-24-hour delivery windows require transport-class AMR density for inter-zone material flow optimization and returns processing velocity.
- Retail:Store replenishment and backroom automation applications prioritize compact footprints and collaborative safety certification for shared human-robot zones.
- Manufacturing:Just-in-time component delivery to production lines demands precise scheduling integration with enterprise resource planning systems.
- Third-Party Logistics:Multi-tenant facilities serving heterogeneous clients require modular platform architectures that reconfigure across contract transitions.
Procurement leverage aggregates with Third-Party Logistics providers; technology validation cycles run longest in Manufacturing due to production continuity requirements.
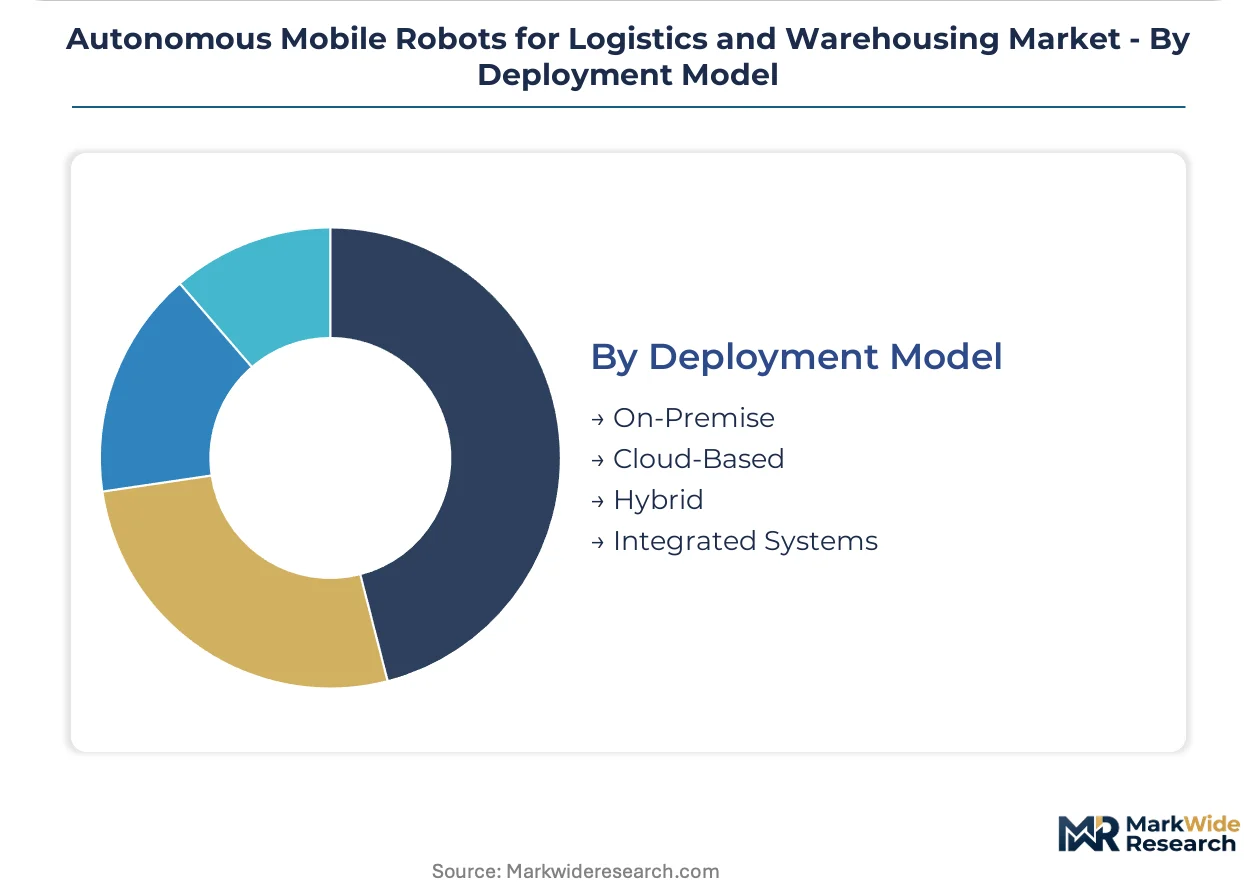
Deployment Model:
Ownership economics and data sovereignty preferences determine whether operators favor capital expenditure or operational expenditure structures.
- On-Premise:Full hardware ownership with local fleet management servers maintains data control for defense and pharmaceutical contractors with classified or patient-sensitive operations.
- Cloud-Based:Software-as-a-service fleet coordination enables continuous algorithm updates and centralized performance analytics without internal IT infrastructure.
- Hybrid:Edge computing for real-time navigation decisions combined with cloud telemetry for fleet-wide optimization balances latency and analytics depth.
- Integrated Systems:Turnkey automation contracts bundling AMR hardware with warehouse management system integration and ongoing operational support.
Contract value pools in Integrated Systems; subscription momentum builds fastest in Cloud-Based models as 3PL procurement teams unbundle hardware from software ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Third-party logistics providers concentrate procurement leverage in Germany, where dense multi-shift warehouse networks drive fleet-scale AMR deployment. Automotive suppliers and pharmaceutical distributors in the Rhine-Ruhr corridor operate the highest robot densities per square meter of any European logistics cluster.
Germany
Automotive supplier parks in Baden-Württemberg and North Rhine-Westphalia demand collaborative AMRs for just-in-time component delivery. The EU AI Act imposes risk classification obligations on autonomous decision-making systems, forcing vendors to establish European authorized representative structures. Stuttgart-based OEMs pilot camera-only navigation stacks for very narrow aisle pallet retrieval in dusty production environments.
United States
Parcel sortation hubs in Memphis and Louisville deploy transport-class AMRs to meet same-day delivery velocity requirements. OSHA workplace safety standards govern collaborative operation in shared human-robot zones, adding validation cycles for brownfield warehouse integration. Amazon Robotics sustains high utilization rates across its captive fulfillment network, compressing competitor pricing in adjacent 3PL contracts.
China
E-commerce fulfillment centers in the Yangtze River Delta and Pearl River Delta drive solid-state lidar manufacturing scale. MIIT standards for mobile robotics guide domestic certification protocols, while GB standards shape safety requirements for human-robot collaboration. Shenzhen-based component clusters collapse per-unit navigation hardware costs below thresholds for mid-size warehouse automation.
Japan
Automotive supplier parks in Aichi Prefecture and Kanagawa Prefecture require precise ERP integration for production line delivery. METI promotes 5G private network deployment to enable cloud-coordinated fleet densities previously constrained by Wi-Fi spectrum contention. Nagoya-based Tier-1 suppliers pilot ultra-reliable low-latency communication infrastructure for multi-agent path planning at scale.
Netherlands
Rotterdam port logistics and Eindhoven distribution corridors prioritize reconfigurable transport robots over fixed conveyor infrastructure. CE marking requirements for mobile machinery raise compliance thresholds for vendors entering European distribution centers. Tilburg-based parcel hubs rely on differential-drive AMRs for inter-zone material flow optimization in same-day delivery networks.
Autonomous Mobile Robots for Logistics and Warehousing Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue AI-driven navigation differentiation and platform-as-a-service contracts. The market structures around three archetypes: captive fulfillment networks with vertical integration, European manufacturing-scale incumbents with CE marking pre-certification programs, and Asian component-integrated challengers with cost-deflated sensor stacks. Consolidation pressure concentrates among fleet orchestration software providers, while hardware vendors face margin compression from lithium-ion supply volatility. Dominant competitive moves include modular platform architectures for multi-site standardization and backward integration into solid-state lidar manufacturing.
Among scale-driven incumbents, Amazon Robotics exemplifies captive demand utilization across fulfillment networks. KION Group anchors European manufacturing presence through Linde and Still brand assembly plants. Geek+ represents AI-driven picking density specialization in Asian e-commerce corridors. These three occupy distinct competitive positions without direct overlap in procurement channels or geographic concentration.
| Leading Market Players |
|---|
| Amazon Robotics |
| KION Group |
| ABB |
| Daifuku |
| KUKA |
| Geek+ |
| Locus Robotics |
| Mobile Industrial Robots |
| Swisslog |
| Others |
Value Chain & Pricing Dynamics
Fleet-scale procurement by third-party logistics providers is compressing vendor margins and forcing modular platform architectures that sacrifice customization for multi-site standardization. This buyer consolidation event is reshaping how AMR vendors structure cost recovery and what supply chain investments they prioritize to maintain pricing power.
Pricing Analysis
Volume concentrates in transport-class AMRs with simpler integration economics, while margins pool in AI-driven picking robots where labor substitution commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked European-compliant systems from OSHA-certified North American variants and uncertified Asian domestic-market units. Cost compression in the standard tier is intensifying because solid-state lidar manufacturing scale in Shenzhen component clusters collapses hardware barriers for mid-size warehouse operators. Third-party logistics providers exhibit the highest price sensitivity due to fleet-scale procurement leverage, while pharmaceutical distributors in Germany accept premium positioning for picking accuracy guarantees that directly impact patient safety.
Supply Chain Analysis
Domestic-content mandates in China's MIIT standards for mobile robotics are reshaping sourcing patterns for vendors seeking access to Yangtze River Delta fulfillment centers. Lithium-ion cell production concentrates in China, South Korea, and Japan, with cathode material refining anchored in East Asian chemical processing corridors. Navigation hardware draws from Taiwanese semiconductor foundries, Japanese precision optics manufacturers, and German industrial sensor specialists. Single-source vulnerability in rare earth magnet supply for drive motors creates forced allocation risk during demand spikes. Distribution runs through direct vendor-to-3PL contracts in North America and tiered distributor networks in European markets with notification body fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autonomous mobile robot market is becoming a vertical-integration race where control over solid-state lidar manufacturing and fleet orchestration software talent determines long-term margin sustainability. Players are pursuing backward integration into sensor component supply to escape commodity hardware pricing.
For Market Incumbents: Hedge against margin erosion by securing captive lithium-ion cell supply agreements with South Korean and Japanese cathode material refiners. Invest in CE marking pre-certification programs that front-load EU AI Act documentation requirements before enforcement windows tighten compliance timelines. Amazon Robotics' captive fulfillment network utilization remains the reference threat; competitors must match its operational expenditure alignment through platform-as-a-service contracts rather than upfront asset sales. For New Entrants and Emerging Players: The price-point gap between premium CE-marked European systems and economy-tier Asian domestic-market units creates white-space opportunity in North American mid-size warehouse automation. Target brownfield parcel sortation hubs in Memphis and Louisville corridors where OSHA validation cycles represent barrier-to-entry protection against low-cost imports. Pursue camera-only navigation stacks that eliminate mechanical lidar maintenance costs and compress total cost of ownership curves for dusty fulfillment environments. For Investors and Strategic Acquirers: The window for entry favors fleet orchestration software specialists with multi-agent path planning algorithm expertise concentrated in select academic clusters. Long-term viability over the projection horizon hinges on whether hardware vendors can escape commodity pricing through software differentiation or backward integration into sensor manufacturing. Watch for inflection signals in 5G private network deployment rates at Japanese automotive supplier parks, where ultra-reliable low-latency communication infrastructure enables cloud-coordinated fleet densities that validate platform-as-a-service economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solid-State Lidar | Shenzhen component clusters enable cost deflation below mid-size warehouse automation thresholds. |
| CE Marking Modularization | Swappable compliance subsystems accelerate European market entry without full platform redesigns. |
| Fleet Orchestration Software Acquisition | Multi-agent path planning talent scarcity concentrates in robotics PhD clusters at select institutions. |
| 5G Private Network Partnership | METI-promoted infrastructure in Aichi Prefecture enables cloud-coordinated fleet densities. |
| Cold-Chain Pharmaceutical Variant Development | Temperature-controlled AMRs address underpenetrated vaccine distribution corridors in Germany and Switzerland. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with warehouse operations directors, 3PL procurement leads, fleet management software engineers, and industrial safety compliance officers combined with secondary validation from OSHA enforcement databases, EU Machinery Directive notification body registers, FCC spectrum allocation records, and MIIT mobile robotics certification logs. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Granularity-level modeling tracked product type, navigation modality, deployment model, and end-user vertical across the analysis window. AI-driven, vision-based, laser navigation, and magnetic guidance technology stacks were modeled separately with distinct hardware cost curves and integration timeline assumptions. CAGRs derived from logistic growth curve fitting with saturation thresholds calibrated to warehouse automation penetration rates in Germany, the United States, China, and Japan. Forecast inputs included lithium-ion cell price trajectories, solid-state lidar manufacturing scale curves, and 3PL fleet procurement contract visibility.
Inputs from regulatory notification bodies and customs trade databases were available through the study window; gaps in private 3PL contract terms and pre-commercial pilot performance data introduce uncertainty bands around near-term deployment velocity assumptions. Forecasts reflect documented assumptions about enforcement timing for EU AI Act risk classification requirements and OSHA collaborative safety standard evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Autonomous Navigation Robots Market
Robotics and Automation
Quadruped Robot Market
Robotics and Automation
Robotics Software Platforms Market
Robotics and Automation
Smart Sweeper Market
Robotics and Automation
Restaurant Delivery Robot Market
Robotics and Automation
Aerospace Service Robotics Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Drone Package Delivery Market
Robotics and Automation
Wearable Robots and Exoskeletons Market
Robotics and Automation
UV-C Disinfection Robots Market
Robotics and Automation
Construction Robotics Market
Robotics and Automation
Autonomous Security Robots Market
Robotics and Automation
Japan Cloud Robotics Market
Robotics and Automation
South America AUV Market
Robotics and Automation
Global Automotive Gesture Recognition System Market
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market