
 Mexico Retail Market | 2026-2036
Mexico Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Retail Market Insights
Bundle-and-save configurations across groceries and home goods are restructuring how Mexican households allocate spending across monthly shopping trips. Walmex leverages its hypermarket footprint to anchor bulk-purchase behavior in suburban corridors. FEMSA Comercio dominates convenience proximity through OXXO's unmatched urban penetration. Liverpool differentiates via curated apparel-and-home-goods bundles targeting aspirational middle-income shoppers.
Retail in Mexico encompasses the sale of finished consumer goods through physical and digital channels, involving inventory management, point-of-sale systems, and supply chain logistics that connect manufacturers to end buyers. The sector operates through product categories spanning electronics, apparel, home goods, and groceries, each demanding distinct cold-chain, security, or display specifications. Grocery and home goods currently occupy the largest margin pools, sustained by recurring purchase frequency and private-label expansion. Electronics competes on import-duty efficiency and warranty-service networks. Customer segmentation across millennials, Generation Z, families, and professionals reveals that younger cohorts concentrate in mobile-first discovery while family units drive basket-size growth.
PROFECO enforces price transparency and consumer complaint resolution, directly shaping how retailers structure promotions and return policies. BIS-equivalent metrology standards and customs regulations under SAT govern import-heavy categories like electronics, creating compliance costs that favor scaled operators with dedicated trade teams. Stakeholders must monitor whether PROFECO expands digital-commerce disclosure requirements and how SAT enforcement on Chinese imports reshapes electronics assortment strategies.
Market Dynamics
PROFECO's tightening disclosure mandates on digital commerce are compressing promotional flexibility and forcing retailers to restructure loyalty programs around transparent unit pricing rather than bundled discounts.
Growth Catalysts
- Last-mile infrastructure densification:Mexico City metropolitan corridors are seeing refrigerated micro-fulfillment nodes proliferate, cutting grocery delivery windows to under two hours and locking in recurring purchase frequency.
- PROFECO price-transparency mandates:Digital shelf-labeling requirements are accelerating backend ERP upgrades that simultaneously enable dynamic pricing and real-time inventory visibility across channels.
- Convenience-store network effects:OXXO's urban penetration is creating pickup-point density that reduces failed delivery rates and lowers customer acquisition costs for grocery apps.
Market Restraints
- Import-duty cost volatility:SAT enforcement fluctuations on Chinese electronics shipments create margin unpredictability that scaled operators absorb better than mid-tier retailers.
- Cold-chain infrastructure gaps:Northern states lack sufficient refrigerated warehousing, forcing grocers to limit fresh-protein assortment outside central Mexico.
- Metrology compliance friction:BIS-equivalent standards for weighing and measuring equipment impose certification timelines that delay new store openings by 4-8 weeks.
Strategic Opportunities
- Guadalajara-Monterrey corridor expansion:Secondary metropolitan areas show underpenetrated convenience-store density relative to per-capita income growth, creating whitespace for format innovation.
- Private-label pharmaceutical adjacencies:PROFECO's push for ingredient transparency is opening shelf space for retailer-owned wellness brands that compete on disclosure clarity.
- QR-code payment convergence:CoDi infrastructure integration with loyalty apps is automating checkout abandonment recovery and enabling micro-targeted replenishment prompts.
Industry Challenges
- Data-science talent scarcity:Dynamic pricing and demand-forecasting capabilities require quantitative analysts that retailers compete for against fintech and telecom sectors.
- Legacy POS integration complexity:Decades-old transaction systems in established hypermarkets resist API connectivity with new omnichannel fulfillment platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Retail Market |
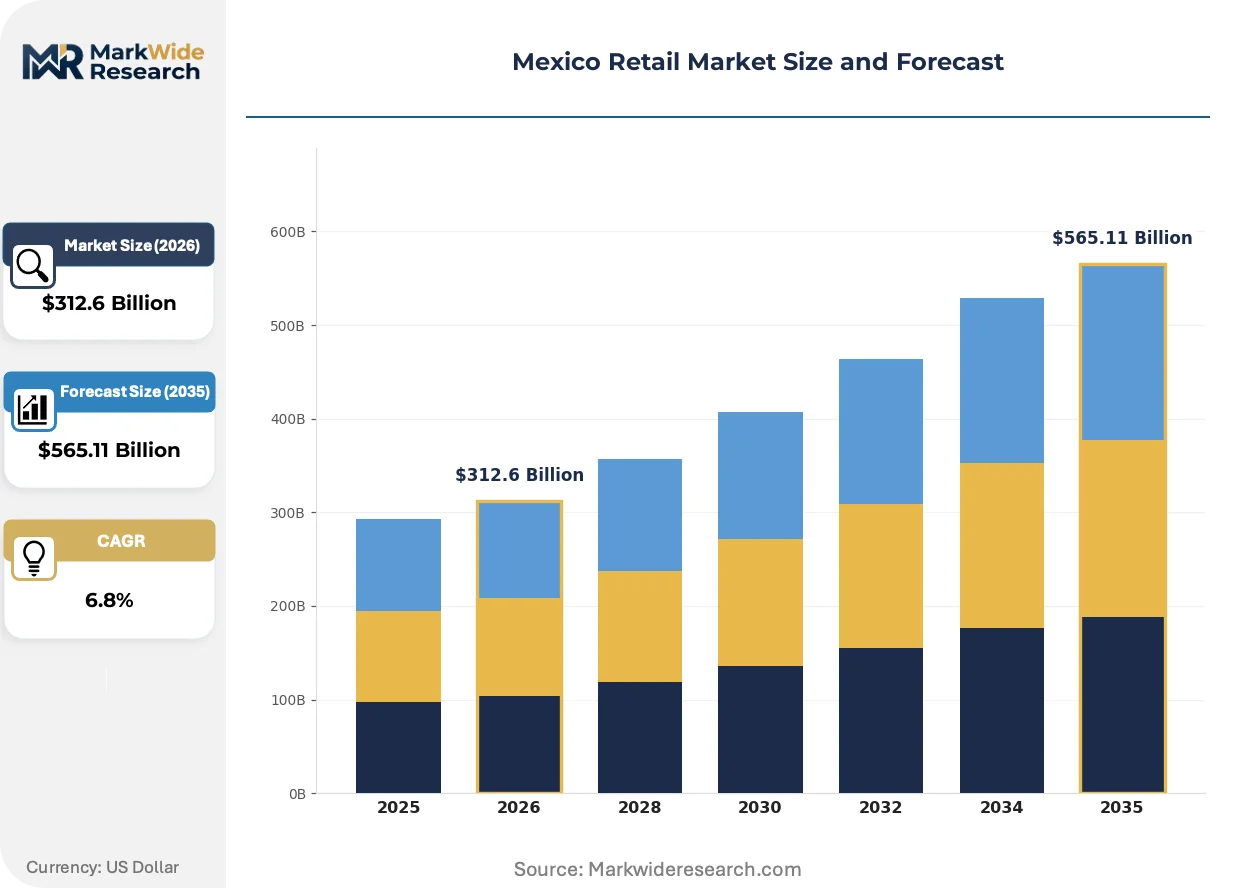
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronics, Apparel, Home Goods, Groceries Customer Type: Millennials, Generation Z, Families, Professionals Distribution Channel: Online, Offline, Department Stores, Supermarkets Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Walmart de México y Centroamérica (Walmex), Organización Soriana, FEMSA Comercio (OXXO), Chedraui, Liverpool, La Comer, Grupo Elektra, Costco México, Home Depot México, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Retail Market Trends and Innovations
Retail operations across Mexico are compressing decision cycles through sensor-driven inventory visibility and reconfiguring physical footprints around fulfillment rather than browse-and-buy experiences.
Computer vision shelf-monitoring systems are automating out-of-stock detection and planogram compliance verification in hypermarket produce sections. Liverpool and Walmex are piloting these installations in Mexico City flagships, compressing restocking response times from hours to minutes and reducing shrinkage from misplaced inventory.
PROFECO's digital-commerce disclosure expansion is mandating itemized fee breakdowns and return-policy visibility before checkout completion. This regulatory pressure is forcing marketplace operators to restructure commission displays and absorb compliance costs that previously flowed to third-party sellers, squeezing unit economics on low-margin electronics.
Mexican household purchasing is fragmenting across channel types rather than consolidating with single retailers. Family units now split grocery missions between convenience-store top-ups, hypermarket monthly stock-ups, and app-based immediate needs, forcing operators to maintain presence across all three touchpoints without duplicating inventory investment.
Mexico Retail Market Segmentation
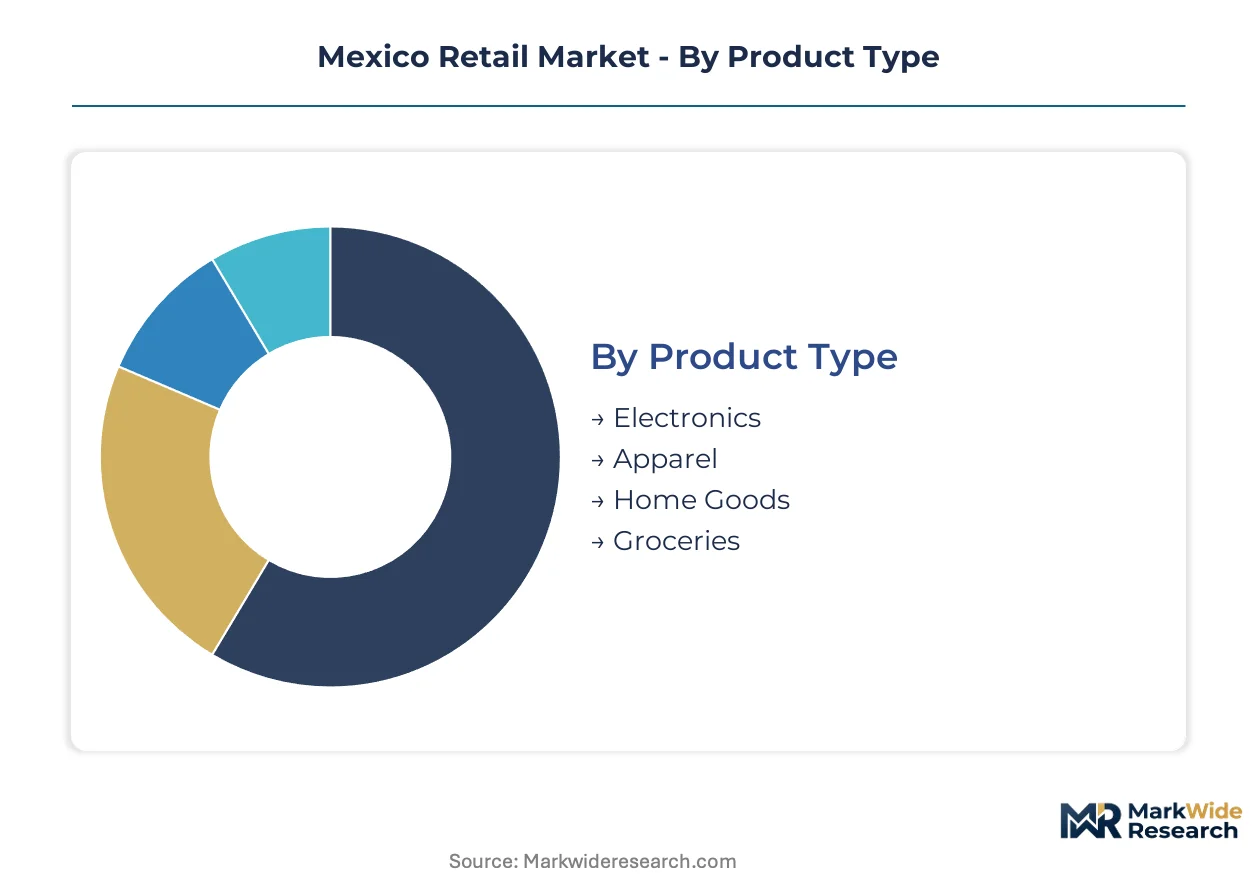
Mexican retail segmentation reveals how channel fragmentation and demographic polarization are splitting purchasing missions across incompatible fulfillment models. Understanding these divides exposes where inventory duplication costs accumulate and where single-channel dominance remains viable.
Product Type:
Specification intensity separates categories by cold-chain requirements, security protocols, and display infrastructure.
- Groceries:Temperature-controlled logistics dominate operational design, with refrigerated micro-fulfillment nodes concentrating in Mexico City corridors. Recurring purchase frequency sustains margin pools through private-label expansion, though northern states face fresh-protein assortment constraints from warehousing gaps.
- Home Goods:Bulky-dimension handling and seasonal demand spikes dictate warehouse configuration, with bundle-and-save configurations restructuring household spending allocation across monthly shopping trips. Aspirational middle-income concentration drives curated assortment strategies in suburban corridors.
- Electronics:Import-duty efficiency and warranty-service networks compete on SAT compliance capabilities.
- Apparel:Size-variation complexity and return-rate management shape fulfillment economics.
Mature deployment sits with Groceries. Newer deployment is concentrated in Home Goods.
Customer Type:
Purchase mission frequency and basket-composition logic diverge sharply across life-stage cohorts.
- Families:Monthly stock-up missions generate the largest basket sizes, with spending split across hypermarket bulk purchases and convenience-store top-ups. Channel fragmentation forces operators to maintain presence across three touchpoints without duplicating inventory investment.
- Millennials:Mobile-first discovery patterns concentrate in app-based immediate needs, with QR-code payment convergence through CoDi infrastructure automating replenishment prompts.
- Generation Z:Social-discovery pathways and influencer-curated selections dominate pre-purchase research.
- Professionals:Time-compressed purchasing favors pickup-point density and sub-two-hour delivery windows.
Volume concentration sits with Families. Digital-native engagement is expanding most quickly in Generation Z.
Distribution Channel:
Physical-digital integration depth determines capital intensity and inventory velocity requirements.
- Online:PROFECO disclosure mandates on digital commerce are compressing promotional flexibility and forcing itemized fee breakdowns before checkout. Backend ERP upgrades enable dynamic pricing and real-time inventory visibility.
- Supermarkets:Legacy POS integration complexity resists API connectivity with new omnichannel fulfillment platforms, though hypermarket footprints anchor bulk-purchase behavior.
- Offline:Convenience-store network effects create pickup-point density that reduces failed delivery rates.
- Department Stores:Curated browsing experiences target aspirational positioning through apparel-and-home-goods bundles.
Format maturity sits with Offline. Technology investment is concentrating in Online.
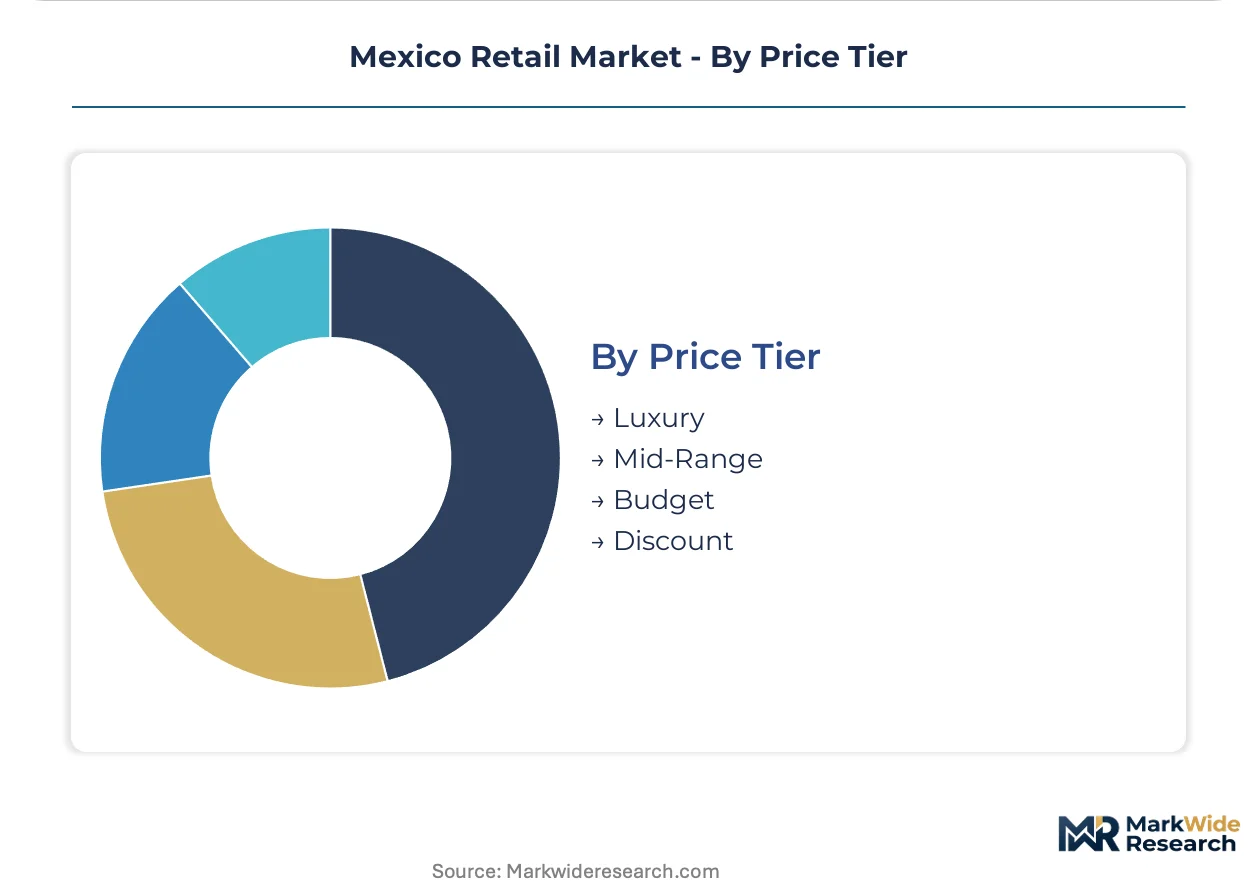
Price Tier:
Margin structure and supplier negotiation leverage scale inversely across tier positioning.
- Mid-Range:Private-label pharmaceutical adjacencies and wellness brand expansion capture PROFECO-driven ingredient transparency demand, with disclosure clarity competing against national brands.
- Budget:Unit-price sensitivity drives bundle-and-save configuration uptake, with transparent pricing mandates reshaping loyalty program structures.
- Luxury:Import-duty volatility on Chinese electronics shipments creates margin unpredictability that scaled operators absorb better than mid-tier retailers.
- Discount:High-volume-low-margin economics depend on metrology compliance efficiency to compress new store opening timelines.
Margin stability sits with Mid-Range. Volume expansion is climbing the fastest in Budget.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Retail consumption concentrates in central Mexico while production and distribution infrastructure clusters along trade corridors connecting manufacturing zones to population centers. This geographic split shapes logistics investment patterns and regulatory enforcement intensity.
Mexico City Metropolitan Area
PROFECO mandates on digital commerce transparency drive backend ERP upgrades among hypermarket operators. The country's consumer protection agency enforces itemized fee disclosure before checkout completion. Santa Fe and Polanco districts host flagship stores where computer vision shelf-monitoring systems compress restocking response times.
Nuevo León
Monterrey's industrial base generates professional-class purchasing power favoring sub-two-hour delivery windows. SAT customs enforcement on Chinese electronics shipments creates margin volatility that scaled operators absorb more efficiently. San Pedro Garza García anchors luxury retail concentration with curated apparel-and-home-goods positioning.
Jalisco
Guadalajara's middle-income expansion supports underpenetrated convenience-store whitespace against per-capita income growth. The state's metrology certification timelines delay new store openings by four to eight weeks under BIS-equivalent standards. Zapopan corridors see refrigerated micro-fulfillment node proliferation cutting grocery delivery windows.
Bajío Region
Querétaro and León manufacturing clusters generate family-unit bulk-purchase missions split across hypermarket stock-ups and convenience top-ups. Cold-chain infrastructure gaps limit fresh-protein assortment in northern Bajío sub-markets. Celaya logistics parks connect automotive supplier payroll density to retail spending corridors.
Northern Border States
Tijuana and Ciudad Juárez cross-border shopping patterns expose SAT enforcement fluctuations on duty-free allowances. Import-duty cost volatility on Chinese electronics concentrates competitive pressure on mid-tier retailers. Reynosa and Matamoros warehouse nodes serve as transshipment points for temperature-controlled grocery logistics.
Mexico Retail Market Competitive Landscape
The competitive structure tilts toward format-diversified conglomerates with hypermarket, convenience, and digital assets. Three archetypes dominate: proximity-format specialists leveraging unmatched urban penetration, bulk-purchase anchors anchoring suburban corridors, and curated-positioning department stores targeting aspirational segments. Competitive moves concentrate on last-mile infrastructure densification and loyalty program restructuring around transparent unit pricing.
Among format-diversified operators, Walmart de México y Centroamérica anchors hypermarket bulk-purchase behavior through suburban footprint density. FEMSA Comercio exemplifies proximity-format dominance via OXXO's urban network effects. Liverpool occupies curated-positioning territory through apparel-and-home-goods bundling. These three represent the structural poles around which mid-tier competitors cluster.
| Leading Market Players |
|---|
| Walmart de México y Centroamérica (Walmex) |
| Organización Soriana |
| FEMSA Comercio (OXXO) |
| Chedraui |
| Liverpool |
| La Comer |
| Grupo Elektra |
| Costco México |
| Home Depot México |
| Others |
Pricing and Supply Chain Analysis
Refrigerated micro-fulfillment node deployment across Mexico City corridors simultaneously compresses last-mile delivery costs and concentrates inventory ownership among scaled operators with capital for cold-chain infrastructure. This technology shift reshapes unit economics by forcing mid-tier retailers to absorb higher third-party logistics markups or surrender market share in fresh-protein categories.
Pricing Analysis
Margin tightening in budget tiers reflects PROFECO-mandated unit-price transparency that eliminates bundled-discount obfuscation. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold-chain certification grade and after-sales service bundling. Pricing pressure accelerates in electronics as SAT enforcement fluctuations on Chinese imports compress duty-efficiency margins. Family units demonstrate highest price sensitivity on monthly stock-up missions, while professionals show lowest sensitivity for sub-two-hour delivery premiums.
Supply Chain Analysis
Workforce availability constraints in Mexican refrigerated warehousing and Chinese electronics manufacturing hubs concentrate supply risk in temperature-controlled logistics and import-dependent categories. Geographic supply concentration centers on China for consumer electronics, the United States for packaged goods inputs, and domestic Mexican corridors for fresh produce. Raw material dependencies span lithium-ion battery components, cold-chain refrigerants, and polyester textile feedstocks. Single-source vulnerability in northern states' refrigerated warehousing limits fresh-protein assortment outside central Mexico. Distribution runs through OXXO's urban pickup-point network, hypermarket suburban footprints, and app-based immediate-need platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-driven inventory visibility systems are displacing legacy planogram compliance workflows, compressing decision cycles from hours to minutes across hypermarket produce sections.
For Market Incumbents: Lock in last-mile infrastructure densification through refrigerated micro-fulfillment node expansion in Mexico City corridors, countering the threat of failed delivery rate spikes that erode customer lifetime value. Deepen backward integration into private-label pharmaceutical manufacturing to capture PROFECO-driven ingredient transparency demand before national brands recover shelf space. For New Entrants and Emerging Players: PROFECO's digital-commerce disclosure expansion in Mexico opens a window for marketplace operators specializing in itemized fee transparency and commission clarity. Target Guadalajara-Monterrey convenience-store whitespace with format innovation around pickup-point density. Pursue CoDi-integrated loyalty apps as the go-to-market angle for QR-code payment convergence. For Investors and Strategic Acquirers: Exit pathways concentrate in format-diversified conglomerates with hypermarket, convenience, and digital assets that demonstrate ERP upgrade completion and dynamic pricing capability deployment. Long-term viability hinges on operators who compress new store opening timelines despite BIS-equivalent metrology certification friction. Watch for SAT enforcement intensity on Chinese electronics imports as the inflection indicator for margin stability in import-heavy retail categories.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Micro-Fulfillment Expansion | PROFECO-mandated ERP upgrades enable real-time inventory visibility that cuts grocery delivery windows below two hours. |
| Private-Label Pharmaceutical Adjacency Launch | Ingredient transparency requirements open shelf space for retailer-owned wellness brands competing on disclosure clarity. |
| CoDi Infrastructure Integration | Central Bank digital payment rails automate checkout abandonment recovery and micro-targeted replenishment prompts. |
| Computer Vision Shelf-Monitoring Deployment | Automated out-of-stock detection in hypermarket produce sections compresses restocking response times from hours to minutes. |
| Guadalajara-Monterrey Format Innovation | Underpenetrated convenience-store density against per-capita income growth creates whitespace for proximity-format experimentation. |
Research Methodology
Trade databases, PROFECO regulatory filings, and SAT customs records formed the secondary backbone, supplemented by Nielsen retail audit data and hypermarket operator SEC disclosures. Primary interviews with category buyers at Walmex and Liverpool, OXXO franchise operations directors, and cold-chain logistics procurement leads combined with this secondary validation. Bottom-up and top-down triangulation cross-checked store-level transaction velocity against metropolitan household spending surveys.
Bottom-up modeling aggregated channel-specific transaction frequencies and average basket compositions across groceries, home goods, electronics, and apparel. Top-down validation referenced national household consumption surveys and metropolitan income distribution data. Segmentation dimensions spanned product type, customer life-stage cohort, distribution channel integration depth, and price tier positioning. CAGRs derived from curve-fitting historical expansion patterns against infrastructure investment pipelines and regulatory enforcement trajectories. Forecast inputs incorporated refrigerated warehousing capacity additions and CoDi payment adoption curves.
Caveats apply where PROFECO disclosure mandate expansion, SAT enforcement intensity fluctuations, or cold-chain infrastructure investment delays could materially shift the outlook. Forecasts reflect assumptions around loyalty program restructuring pace and dynamic pricing capability deployment. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia Pacific Video Conferencing Hardware Market
Others
Fresh Durian Market
Others
Printing Machines Market
Others
Latin America Contract Packaging Market
Others
Connected Living Room Market
Others
Global Active Speaker Market
Others
Global Electronic Filters Market
Others
IT Device Market
Others
China Packaging Primers Market
Others
Allogeneic Human Chondrocyte Market
Others
Foldable Smartphone Market
Others
Folding Mobile Phone Market
Others
Live IP Broadcast Equipment Market
Others
Underwater Communication System Market
Others
Dry Washer Market
Others
Couscous Market