
 Asia Pacific Video Conferencing Hardware Market | 2026-2036
Asia Pacific Video Conferencing Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Video Conferencing Hardware Market Insights
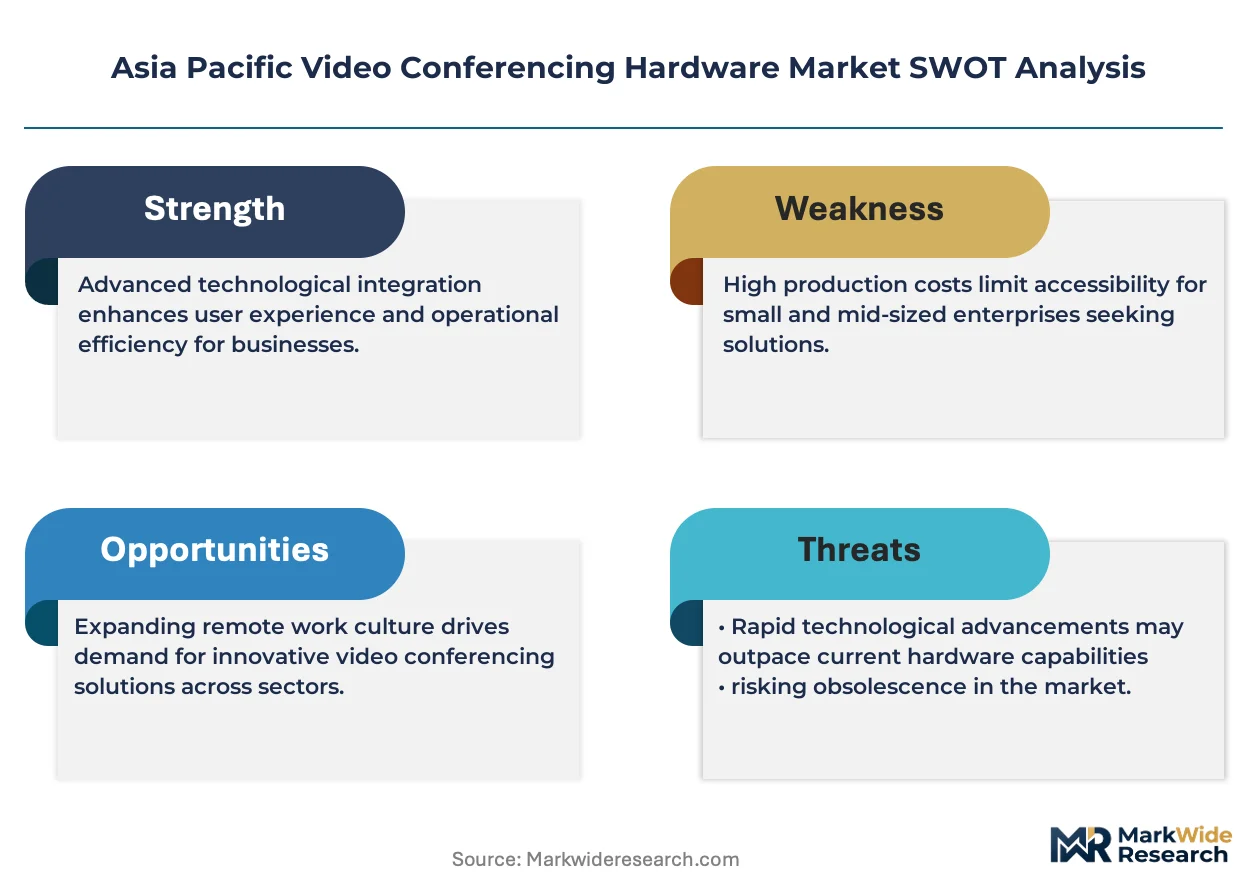
The gap between proprietary codecs and open-standard WebRTC interoperability is narrowing across enterprise-grade hardware stacks. Cisco Systems Inc leverages its installed base of networking infrastructure to bundle video endpoints with routing contracts. Huawei Technologies Co Ltd anchors its position through in-house silicon design for camera processing modules. Yealink Inc competes aggressively on price-performance ratios for small-to-mid-size meeting rooms.
Asia Pacific video conferencing hardware encompasses physical endpoint devices—including codec units, PTZ cameras, beamforming microphone arrays, and all-in-one soundbars—engineered to capture, compress, and transmit synchronized audiovisual streams over IP networks with sub-150ms latency targets. Camera Solutions command the largest revenue pool as organizations upgrade from 1080p to 4K capture for executive boardrooms. Cloud-Based Solutions represent the fastest-expanding technology segment as vendors shift firmware management and analytics processing to subscription-hosted platforms.
Japan's METI enforces radio equipment certification that delays foreign product introductions by six to twelve months. China's MIIT mandates GB-standard network access licenses for any device connecting to public telecommunications infrastructure. India's BIS compulsory registration scheme for electronic products now covers video conferencing terminals sold through domestic channels. Stakeholders must weigh certification timelines against first-mover advantages when sequencing country-level product rollouts.
Market Dynamics
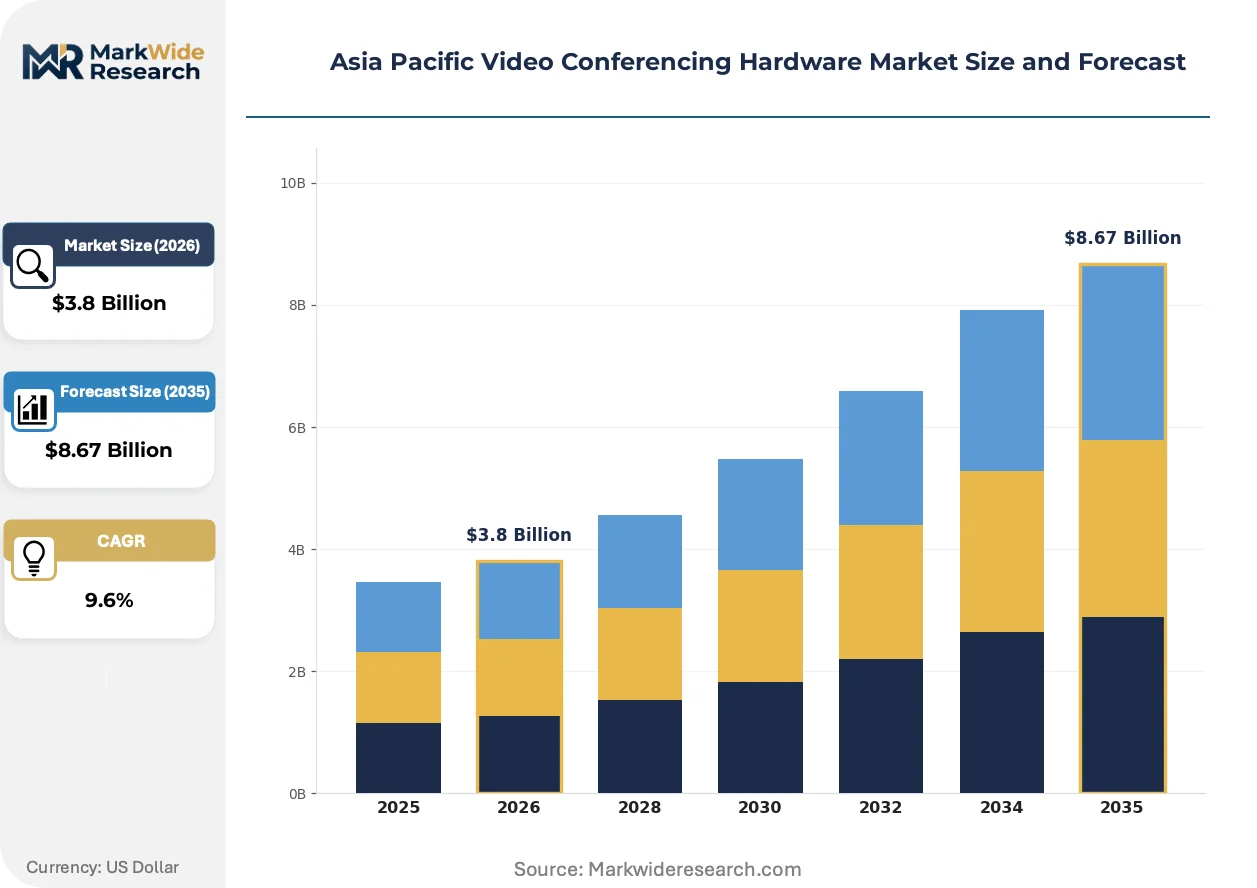
China's MIIT certification requirements for network equipment are accelerating compliance investments by local manufacturers while compressing product launch timelines for foreign entrants. This regulatory pressure is restructuring competitive positioning across the Asia Pacific video conferencing hardware landscape.
Growth Catalysts
- Hybrid work policy stabilization:India's tier-1 commercial hubs are consolidating demand as corporate offices replace legacy audio systems with integrated video endpoints.
- MIIT GB-standard mandates:China's network access license requirements are forcing domestic manufacturers to upgrade firmware security architectures ahead of foreign competitors.
- 4K camera sensor diffusion:Executive boardrooms across Southeast Asia are upgrading from 1080p capture, expanding the addressable hardware base for premium PTZ units.
Market Restraints
- Radio equipment certification delays:Japan's METI enforcement adds six to twelve months to foreign product introductions, freezing market entry windows.
- Silicon supply concentration:Camera processing module fabrication depends on a narrow supplier base concentrated in East Asian foundries.
- WebRTC codec standardization gaps:Proprietary compression protocols from incumbent vendors create interoperability friction with open-standard enterprise stacks.
Strategic Opportunities
- Cloud firmware management platforms:Vendors are shifting analytics processing to subscription-hosted architectures, creating recurring revenue streams from hardware deployments.
- BIS compulsory registration expansion:India's electronic product certification scheme now covers video conferencing terminals, opening compliant channels for organized distribution.
- Small-to-mid-size meeting room penetration:Price-performance optimized all-in-one soundbars remain underdeployed in Southeast Asian professional services firms.
Industry Challenges
- Multi-jurisdiction certification sequencing:Stakeholders must weigh METI, MIIT, and BIS timelines against first-mover advantages when planning country-level rollouts.
- Sub-150ms latency engineering:Beamforming microphone array integration with IP network synchronization demands specialized acoustic design talent scarce across the region.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Video Conferencing Hardware Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telepresence Systems, Desktop Video Systems, Camera Solutions, Microphone Units Technology: HD Video, 4K Video, WebRTC, Cloud-Based Solutions End User: Corporate Offices, Educational Institutions, Government Agencies, Healthcare Facilities Distribution Channel: Direct Sales, Online Retail, Value-Added Resellers, System Integrators |
| Companies Covered | Logitech International SA, EPOS, Jabra, Cisco Systems Inc, Huawei Technologies Co Ltd, Poly Inc, Panasonic Corporation, Yealink Inc, Lumens, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Video Conferencing Hardware Market Trends and Innovations
Enterprise-grade hardware stacks are converging around open-standard interoperability while regulatory compliance becomes a primary product differentiator. Three forces are actively restructuring how video conferencing equipment is engineered, certified, and procured.
AI-powered noise cancellation and auto-framing algorithms are embedding directly into camera firmware. Large corporate deployers in Singapore and Sydney are specifying these features in RFPs as baseline requirements. Dedicated DSP hardware for acoustic processing is rendering obsolete external audio processing units that previously sat between microphones and codec units.
China's MIIT is tightening GB-standard network security audits for any device connecting to public telecommunications infrastructure. Local manufacturers are absorbing compliance costs into product development cycles, while foreign vendors face extended certification queues. Enterprise-grade codec units with domestic encryption modules are capturing preference in government and financial verticals.
Enterprise buyers are consolidating vendor relationships around bundled networking and endpoint contracts. Systems integrators across India and Australia are displacing standalone hardware distributors as the primary procurement channel. This concentration is most visible in telecommunications and banking verticals where IT infrastructure standardization mandates favor single-source supplier arrangements.
Asia Pacific Video Conferencing Hardware Market Segmentation
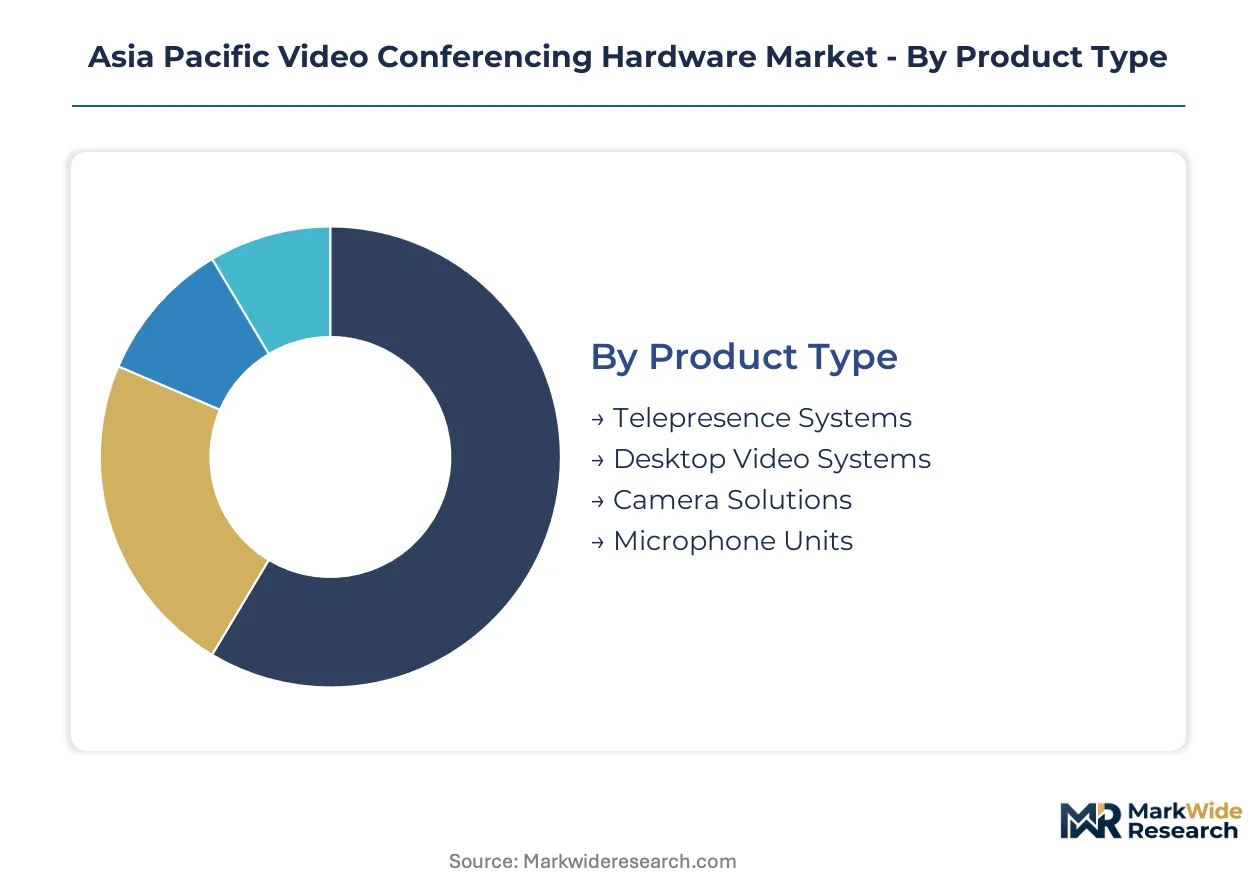
Segmentation reveals how procurement cycles, certification requirements, and end-use sophistication vary across hardware categories. Understanding these distinctions allows vendors to align product roadmaps with replacement timelines and compliance burdens specific to each segment.
Product Type:
Telepresence systems turn over every five to seven years as room infrastructure depreciates, while desktop units refresh on three-year IT cycles. Camera solutions occupy the middle ground with four-year replacement waves driven by resolution upgrades.
- Camera Solutions:PTZ and fixed-lens units capturing 4K streams with integrated auto-framing algorithms. Demand concentrates in Singapore and Sydney executive boardrooms where resolution specifications drive procurement decisions.
- Telepresence Systems:Immersive room-scale installations with multiple synchronized displays and directional audio arrays. India's tier-1 commercial hubs are consolidating demand as hybrid work policies stabilize and legacy audio systems reach end-of-life.
- Desktop Video Systems:Compact all-in-one units for individual workstations. Japan's METI radio certification delays compress viable sales windows to eighteen-month cycles.
- Microphone Units:Beamforming arrays and ceiling-tile installations with DSP-integrated acoustic processing. Southeast Asian professional services firms represent underdeployed addressable base.
Camera Solutions dominate installed base. Telepresence Systems are where expansion concentrates.
Technology:
Cost tiers separate premium 4K deployments from standard HD rollouts, with WebRTC and cloud architectures disrupting traditional capital expenditure models through subscription conversion.
- 4K Video:Ultra-high-definition capture with HEVC compression and HDR color processing. Executive boardrooms across Southeast Asia are upgrading from 1080p, expanding the addressable hardware base for premium sensor modules.
- Cloud-Based Solutions:Firmware management and analytics processing hosted on vendor subscription platforms. China's MIIT GB-standard network security audits are accelerating compliance investments by local manufacturers ahead of foreign competitors.
- HD Video:1080p60 capture with AVC encoding for mid-tier meeting rooms. India's BIS compulsory registration scheme now covers terminals sold through domestic channels.
- WebRTC:Browser-native real-time communication without proprietary plugin dependencies. Interoperability friction with incumbent vendor compression protocols creates deployment complexity.
HD Video retains volume leadership. Cloud-Based Solutions are climbing the fastest.
End User:
Application urgency varies sharply: healthcare demands sub-150ms latency for telemedicine, while educational procurement follows annual budget cycles with extended vendor qualification periods.
- Corporate Offices:Enterprise deployments spanning headquarters, regional branches, and home offices. Systems integrators across India and Australia are displacing standalone distributors as primary procurement channel.
- Government Agencies:Secure conferencing with domestic encryption modules and certified supply chains. China's MIIT mandates GB-standard network access licenses, favoring local manufacturers with in-house compliance capabilities.
- Healthcare Facilities:Diagnostic-grade video for telemedicine and specialist consultation. Australia's TGA medical device framework imposes additional validation requirements on camera systems used in clinical settings.
- Educational Institutions:Lecture capture and remote learning infrastructure. Procurement follows fiscal year cycles with consolidated RFPs across university systems.
Corporate Offices anchor revenue concentration. Government Agencies are gaining share fastest.
Distribution Channel:
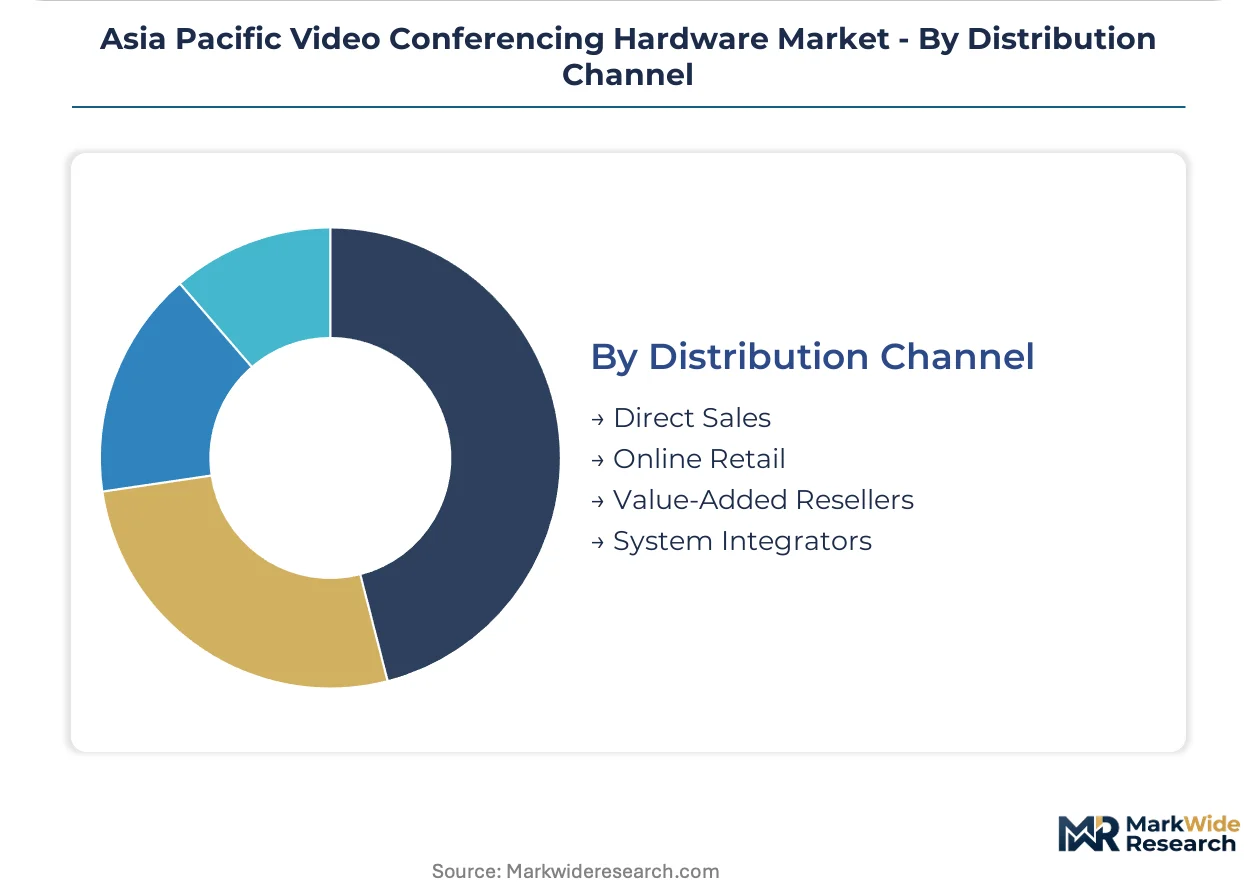
Customer type determines channel selection: direct relationships dominate enterprise accounts above five hundred endpoints, while mid-market buyers route through integrators for bundled networking and endpoint contracts.
- System Integrators:Full-stack deployment including network assessment, installation, and managed services. Telecommunications and banking verticals in India favor single-source supplier arrangements for infrastructure standardization mandates.
- Direct Sales:Vendor field teams engaging multinational accounts with customized procurement frameworks. Australia's enterprise buyers are consolidating vendor relationships around bundled networking contracts.
- Value-Added Resellers:Regional specialists with local certification expertise and installation capabilities. Japan's METI radio equipment certification requirements create six-to-twelve month entry delays that resellers navigate for foreign vendors.
- Online Retail:Self-service procurement for small-to-mid-size meeting room deployments. Price-performance optimized all-in-one soundbars remain underpenetrated in Southeast Asian professional services firms.
System Integrators capture margin expansion. Direct Sales retains enterprise account control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export codec units and camera modules to Southeast Asian corporate buyers, while Japanese and Korean component suppliers feed assembly lines across the region's tier-1 commercial hubs.
China
Domestic manufacturers upgrade firmware security architectures to meet MIIT GB-standard network access licenses ahead of foreign competitors. Government and financial verticals prefer enterprise-grade codec units with domestic encryption modules. Shenzhen and Beijing clusters concentrate production of camera processing modules for regional export.
India
Corporate offices in Mumbai, Bengaluru, and Delhi-NCR replace legacy audio systems with integrated video endpoints as hybrid work policies stabilize. BIS compulsory registration scheme now covers video conferencing terminals sold through domestic channels. Systems integrators displace standalone distributors as the primary procurement channel in telecommunications and banking verticals.
Japan
METI radio equipment certification adds six to twelve months to foreign product introductions, compressing viable sales windows for desktop video systems. Enterprise buyers consolidate vendor relationships around bundled networking contracts. Tokyo and Osaka metropolitan areas drive demand for AI-powered noise cancellation and auto-framing features in executive boardrooms.
Australia
TGA medical device framework imposes additional validation requirements on camera systems used in clinical telemedicine settings. Enterprise buyers favor single-source supplier arrangements for infrastructure standardization. Sydney and Melbourne anchor demand for 4K PTZ units in professional services and healthcare facilities.
Singapore
Executive boardrooms specify 4K capture with HEVC compression and HDR color processing as baseline procurement requirements. The city-state serves as a regional distribution hub for Southeast Asian professional services firms. Price-performance optimized all-in-one soundbars remain underdeployed in mid-market meeting rooms across the island.
Asia Pacific Video Conferencing Hardware Market Competitive Landscape
On the supply side, the industry is tiered between networking infrastructure incumbents, specialized endpoint manufacturers, and component-focused fabricators. Strategic archetypes include bundled solution providers, price-performance optimizers, and silicon-integrated designers. Dominant competitive moves center on compliance-led product differentiation and cloud firmware platform migration to subscription architectures.
Among networking-anchored vendors, Cisco Systems Inc exemplifies the bundled infrastructure archetype, while Huawei Technologies Co Ltd occupies a position reflecting in-house silicon design capabilities. Yealink Inc represents the price-performance tier targeting small-to-mid-size meeting room deployments. These three entities illustrate how competitive positioning diverges across certification compliance, vertical integration depth, and channel strategy.
| Leading Market Players |
|---|
| Logitech International SA |
| EPOS |
| Jabra |
| Cisco Systems Inc |
| Huawei Technologies Co Ltd |
| Poly Inc |
| Panasonic Corporation |
| Yealink Inc |
| Lumens |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian camera sensor foundries is compressing component costs while simultaneously eroding pricing power for finished hardware vendors. This utilization dynamic forces manufacturers to absorb MIIT compliance investments into thinner margins rather than passing them through to enterprise buyers.
Pricing Analysis
The technology-generation pricing gap separates 4K HEVC units from legacy 1080p AVC endpoints by roughly two-to-one in project quotations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with GB-standard licensed products commanding measurable premiums over uncertified alternatives. Cost compression in the HD tier is intensifying because Indian systems integrators bundle endpoints with networking contracts at volume scale. Small-to-mid-size meeting room buyers exhibit highest price sensitivity, while government agencies with domestic encryption mandates show lowest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration rests with Shenzhen and Dongguan EMS providers that assemble codec units and PTZ housings for multiple brand labels. Geographic supply concentration centers on China for final assembly, South Korea for image sensor modules, and Taiwan for DSP chip fabrication. Raw material dependencies include rare-earth magnetics for microphone motors, optical glass for lens arrays, and copper-laminate PCBs for signal processing boards. Single-source vulnerability in MIIT-certified firmware development creates supply chain risk for foreign vendors facing extended certification queues. Distribution runs through systems integrators in India and Australia, with value-added resellers navigating Japan's METI delays for foreign entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-based video collaboration platforms represent the primary substitution threat that hardware incumbents must neutralize through embedded intelligence and compliance differentiation.
For Market Incumbents: Build certification moats by pre-positioning MIIT, METI, and BIS documentation ahead of product launch windows. Anchor enterprise relationships through cloud firmware management subscriptions that create switching costs. Absorb upfront compliance investments to freeze out foreign competitors facing extended certification queues. Deepen backward integration into camera processing silicon to control sensor roadmap timing against WebRTC-native software competitors. For New Entrants and Emerging Players: Mid-market professional services firms in Southeast Asia represent the most penetrable entry point given underdeployment of price-optimized all-in-one soundbars. Cloud-native firmware architectures without legacy on-premise dependencies offer the cleanest go-to-market angle against incumbent hardware refresh cycles. Target Australian healthcare facilities with TGA-validated camera systems as a beachhead for clinical telemedicine specialization. Partner with Indian systems integrators already displacing standalone distributors in banking and telecommunications verticals. For Investors and Strategic Acquirers: Capital is best deployed toward compliance-integrated platform vendors with recurring revenue from subscription-hosted analytics. The long-term viability window favors entities that have absorbed MIIT certification costs into product development cycles rather than treating them as one-time regulatory hurdles. Vertically integrated manufacturers with in-house silicon design capabilities present the most defensible acquisition profile against margin compression. Monitor BIS registration expansion timelines as the inflection signal for organized distribution channel opening in India.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Pre-Certification Investment | GB-standard network access licenses compress foreign competitor launch windows by six to twelve months. |
| Cloud Firmware Platform Migration | Subscription-hosted analytics processing converts one-time hardware sales into recurring revenue streams. |
| In-House Silicon Design Capability | Camera processing module control insulates margins from East Asian foundry pricing volatility. |
| Systems Integrator Channel Partnership | India's telecommunications and banking verticals mandate single-source infrastructure standardization. |
| Clinical-Grade Validation Pathway | Australia's TGA medical device framework opens telemedicine camera deployments with diagnostic specifications. |
Research Methodology
A spread of perspectives from enterprise IT procurement officers, systems integration specialists, regulatory compliance consultants, and semiconductor supply chain managers converged on the working assumptions driving this analysis. Primary field engagement combined structured interviews with secondary validation against MIIT certification databases, BIS registration records, METI radio equipment filings, and customs trade data for camera module imports. Bottom-up endpoint shipment estimates triangulated against top-down enterprise IT spending surveys across the projection horizon.
Demand-supply-balance framing anchored the analytical framework, modeling procurement cycles across telepresence systems, camera solutions, desktop units, and microphone arrays throughout the forecast period. Segmentation dimensions included resolution tier, deployment architecture, end-use vertical, and distribution channel complexity. CAGRs derived from replacement wave timing, hybrid work policy stabilization trajectories, and regulatory compliance investment curves. Industry-specific forecast inputs incorporated MIIT GB-standard audit timelines and BIS compulsory registration expansion phases.
Practitioners should monitor MIIT network security audit tightening, BIS registration scheme coverage expansion, and WebRTC interoperability standardization for early signals requiring forecast revision. Quarterly review of certification queue lengths, systems integrator channel consolidation rates, and 4K sensor cost curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia Pacific Automotive LED Lighting Market
Others
Language Translation Device Market
Others
Japan Indoor LBS Market
Others
Advanced Combat Helmet Market
Others
Finished Leather Market
Others
Smart Plug Market
Others
Rotary Dial Machine Market
Others
Ceramic Machinery Market
Others
Global Military Wearable Sensors Market
Others
Heat Treatment Furnace Market
Others
Nuclear Power Cables Market
Others
Industrial Gauges Market
Others
North America Orange Market
Others
Tanned Fish Skin Leather Market
Others
Europe Air Separation Unit Market
Others
Gesture Recognition for Smart TV Market