
 Automotive Seat Climate Systems Market | 2026-2036
Automotive Seat Climate Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Climate Systems Market Analysis
Aftermarket retrofit kit revenue is rewriting margin distribution across the value chain. Continental AG leverages its integrated thermal management portfolio to anchor factory-installed programs with major European OEMs. Gentherm Incorporated specializes in thermoelectric and smart textile architectures, sustaining technology leadership in energy-efficient seat climate solutions. Aisin Corporation competes through backward integration into HVAC component manufacturing, controlling cost structures across Asian supply networks.
Automotive seat climate systems combine thermoelectric modules, PTC heating elements, forced-air circulation channels, and sensor-embedded textiles to regulate occupant thermal comfort within vehicle cabins. These systems typically operate across temperature ranges from 18°C to 42°C surface contact, drawing 35-120 watts depending on zone count and ambient conditions, with primary purpose being reduction of HVAC energy load while improving passenger satisfaction. Heated seats and integrated systems dominate current OEM fitment, while smart textile technology represents the fastest-expanding segment as conductive yarn weaving enables thinner profiles and reduced wiring complexity. Thermoelectric technology anchors premium positioning due to precise zonal control, whereas PTC heaters occupy mainstream volume tiers where cost engineering prevails.
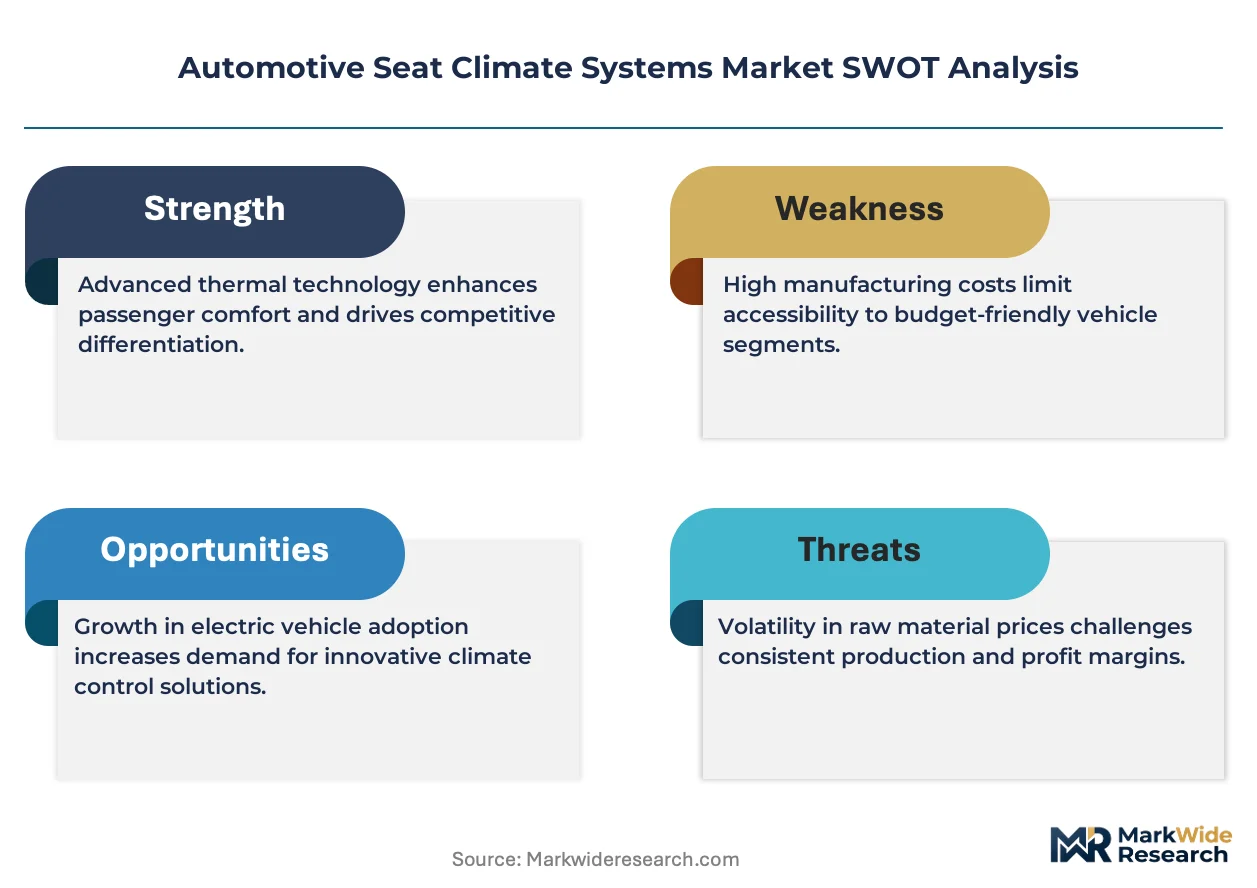
NHTSA occupant safety standards and EPA refrigerant phase-down schedules shape product architecture decisions in the United States, while EU F-Gas Regulation and REACH chemical restrictions constrain material selection across European supply chains. China's MIIT new energy vehicle efficiency mandates accelerate adoption of low-power climate seating as range preservation becomes critical. Stakeholders must monitor evolving refrigerant classifications and textile flammability standards to anticipate certification requirements that will determine market access for next-generation seat climate platforms.
Market Dynamics
Electric vehicle thermal efficiency mandates are compressing seat climate system power budgets below 50 watts per zone, forcing suppliers to abandon resistive heating in favor of thermoelectric and smart textile architectures that preserve driving range.
Growth Catalysts
- China MIIT Efficiency Mandates:New energy vehicle range preservation requirements accelerate factory installation of low-wattage climate seating across domestic OEM platforms.
- REACH Chemical Compliance:Phased restrictions on legacy flame retardants create replacement demand for certified textile laminates in European supply chains.
- Multi-Zone Thermal Architectures:Luxury EV platforms now specify independent temperature control for cushion, backrest, and bolster surfaces as standard equipment.
Market Restraints
- Copper and Rare Earth Volatility:Thermoelectric modules depend on bismuth telluride and copper interconnects subject to mining concentration in specific geographies.
- Refrigerant Phase-Down Schedules:EPA and EU F-Gas Regulation timelines compress product development cycles for compressor-based cooling systems.
- PTC Heater Commoditization:Mature ceramic heating technology faces price erosion as Asian suppliers expand capacity without differentiation.
Strategic Opportunities
- Aftermarket Retrofit Channels:Independent service networks and direct-to-consumer platforms unlock margin pools outside OEM captive supply agreements.
- Sensor-Textile Convergence:Integration of capacitive occupancy detection with heating elements enables predictive climate pre-conditioning.
- India PLI Scheme:Component manufacturing incentives attract seat climate module assembly for export to Middle East and Southeast Asian vehicle markets.
Industry Challenges
- Functional Safety Certification:ISO 26262 compliance for seat-mounted electronics extends validation timelines and requires dedicated hardware architectures.
- Cross-Functional Thermal Engineering:Shortage of engineers capable of integrating seat climate with cabin HVAC and battery thermal management constrains program staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Climate Systems Market |
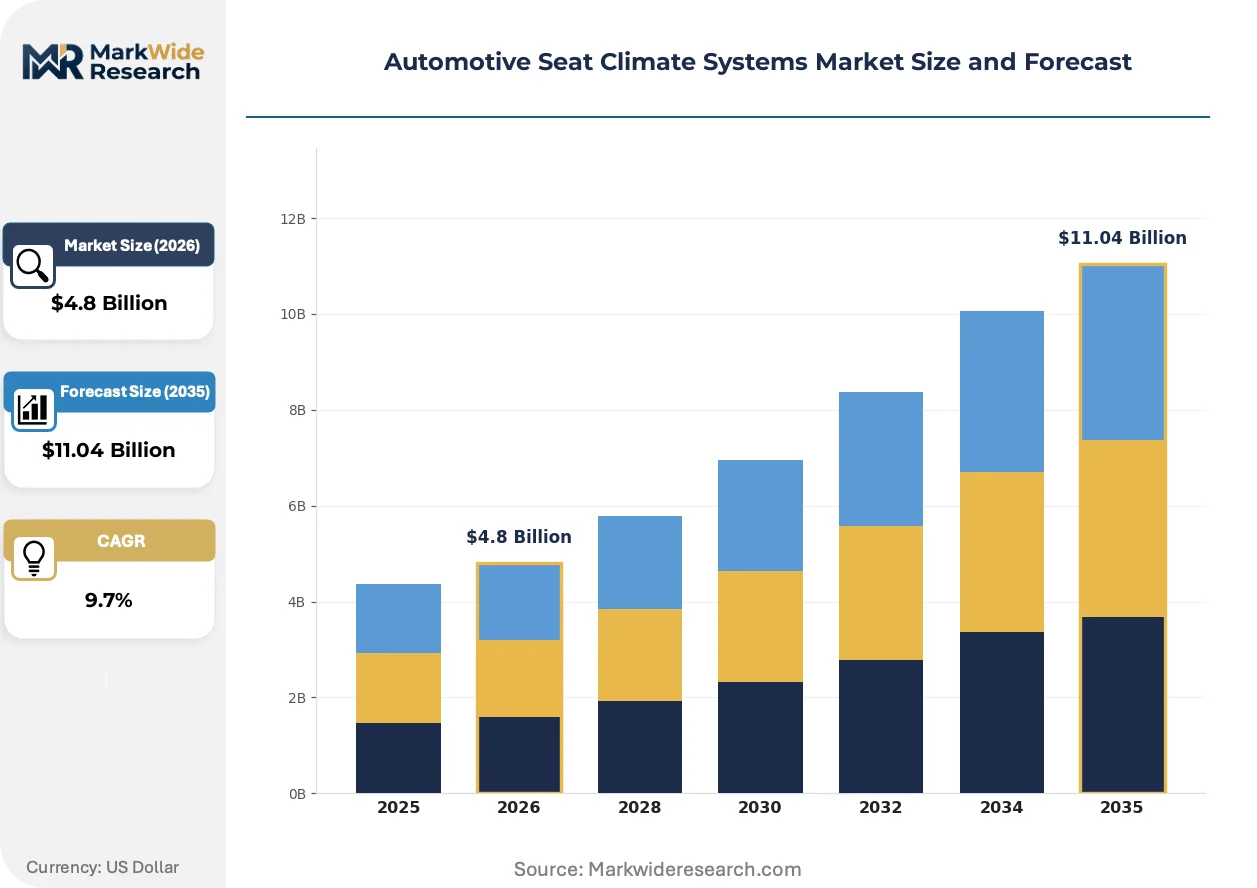
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heated Seats, Cooled Seats, Integrated Systems, Aftermarket Solutions Technology: Thermoelectric, PTC Heaters, Air Circulation, Smart Textile End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Installation: Factory Installed, Retrofit Kits, Aftermarket Add-ons, Custom Installations |
| Companies Covered | Continental AG, Aisin Corporation, Gentherm Incorporated, Denso Corporation, Magna International Inc., Adient plc, Faurecia (Forvia), Toyota Boshoku Corporation, Lear Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Climate Systems Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to eliminate conventional wired heating elements from next-generation seating platforms. Three developments dominate supplier roadmaps.
Conductive yarn weaving is virtualizing the physical infrastructure of seat climate systems. Silver-coated polymer threads embedded directly into textile substrates replace discrete heater pads and wire harnesses. Premium EV seating programs at German and Korean OEMs have adopted this architecture for 2026 model year launches. The technology is virtualizing supplier tier structures by collapsing separate textile, wiring, and heating component vendors into single-source smart material providers.
EU F-Gas Regulation refrigerant quotas are constraining compressor-based cooling options for European vehicle programs. The policy limits hydrofluorocarbon deployment across automotive HVAC and seat cooling applications. Suppliers now prioritize thermoelectric and phase-change material approaches for EU-bound platforms, while diverting compressor systems to markets without equivalent restrictions.
Fleet operators and mobility service providers now specify seat climate durability metrics in procurement contracts. Ride-hailing vehicle buyers demand 500,000-cycle heating element lifespans versus 100,000-cycle passenger car standards. This specification divergence forces suppliers to maintain parallel product lines with divergent validation protocols, compressing economies of scale for standardized modules.
Automotive Seat Climate Systems Market Segmentation
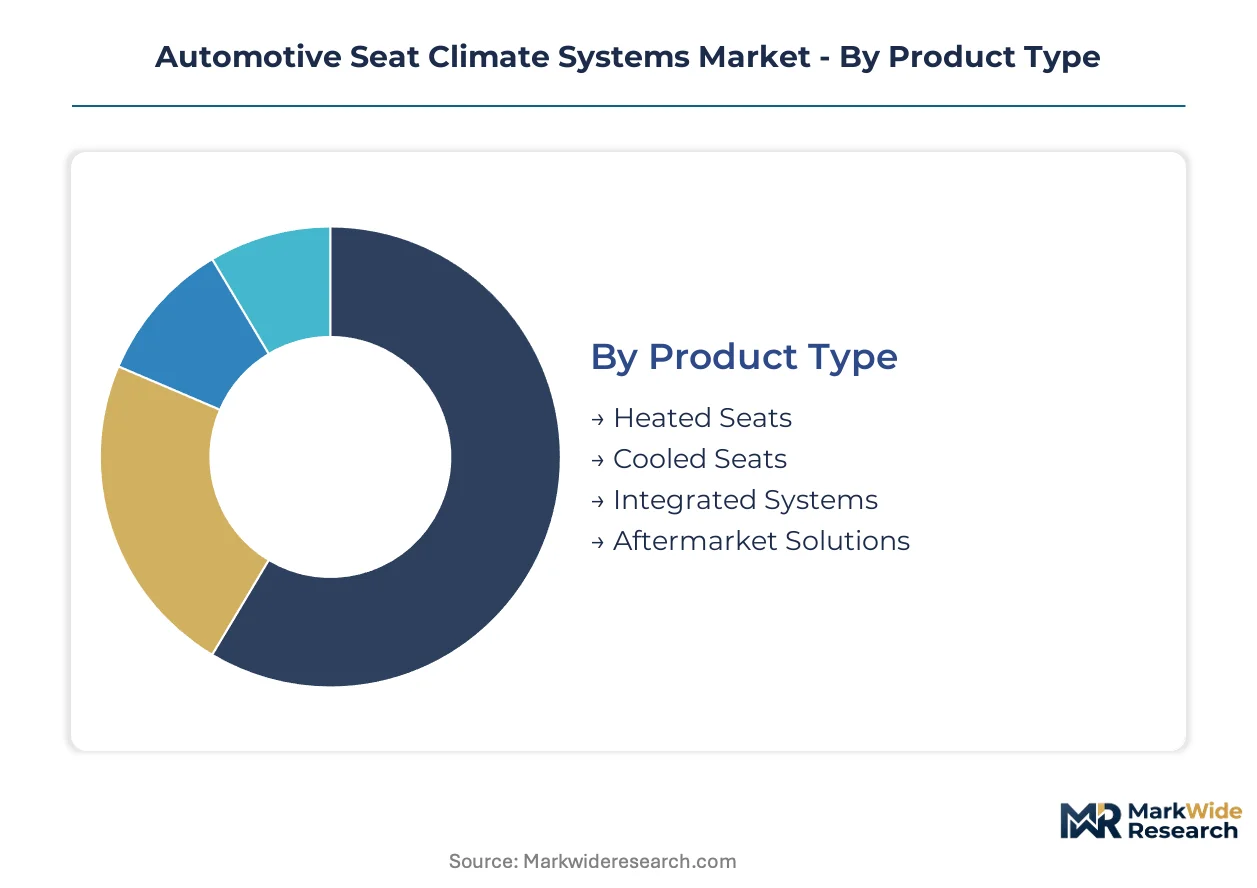
Seat climate system segmentation reveals divergent margin structures and service intensity across product tiers. Aftermarket channels demand specialized technical support that factory-installed programs rarely require, creating distinct competitive arenas for suppliers.
Product Type:
Aftermarket service intensity varies dramatically across product categories, with integrated systems requiring diagnostic calibration that standalone heating pads never need.
- Heated Seats:PTC ceramic elements and resistive wire matrices deliver surface temperatures up to 42°C through embedded pad architectures. German and Korean OEMs specify these as standard equipment across mid-tier electric vehicle platforms where MIIT efficiency mandates restrict power draw to 50 watts per zone.
- Integrated Systems:Multi-zone architectures combining heating, cooling, and ventilation through unified control modules command premium positioning. Luxury EV platforms in the United States and China now specify independent cushion, backrest, and bolster control as baseline trim requirements.
- Cooled Seats:Forced-air channels and thermoelectric modules reduce surface contact temperature through active heat exchange. EPA refrigerant phase-down schedules constrain compressor-based variants to non-European markets.
- Aftermarket Solutions:Retrofit kits and dealer-installed packages target vehicle owners seeking climate upgrades outside factory configurations. Direct-to-consumer platforms and independent service networks distribute these products.
Heated seats holds the largest share; momentum sits with integrated systems.
Technology:
Cost tier stratification separates premium thermoelectric architectures from commodity PTC implementations.
- Thermoelectric:Bismuth telluride modules enable precise zonal temperature control through solid-state heat pumping. Bismuth telluride and copper interconnect supply concentration in specific geographies creates procurement risk for European and North American assemblers.
- Smart Textile:Silver-coated conductive yarn weaving collapses discrete heater pads, wiring harnesses, and textile substrates into unified material systems. Premium EV seating programs at German OEMs adopted this architecture for recent model year launches.
- PTC Heaters:Positive temperature coefficient ceramic elements self-regulate resistance as temperature rises, simplifying control electronics. Asian supplier capacity expansion drives price erosion across mainstream volume tiers.
- Air Circulation:Blower-fed perforated foam channels distribute conditioned air across seating surfaces without active cooling elements. Fleet operators specify 500,000-cycle durability for ride-hailing applications versus 100,000-cycle passenger car standards.
PTC heaters dominate volume; smart textile technology is expanding most quickly.
End User:
Customer type determines specification authority and contract structure across the value chain.
- OEMs:Vehicle manufacturers hold final specification authority for factory-installed climate seating, dictating thermal performance, power budget, and durability metrics through platform-specific technical standards.
- Tier-1 Suppliers:Seating system integrators source climate modules from specialized thermal component vendors, managing ISO 26262 functional safety certification and vehicle-level integration.
- Vehicle Assemblers:Contract manufacturers and joint venture production facilities execute final seat installation according to OEM-provided build specifications.
- Aftermarket Providers:Independent distributors and installation networks serve consumers seeking climate upgrades for vehicles without factory-equipped systems.
OEMs control specification; aftermarket providers are gaining share fastest.
Installation:
Installation channel shapes warranty liability and technical support obligations for suppliers.
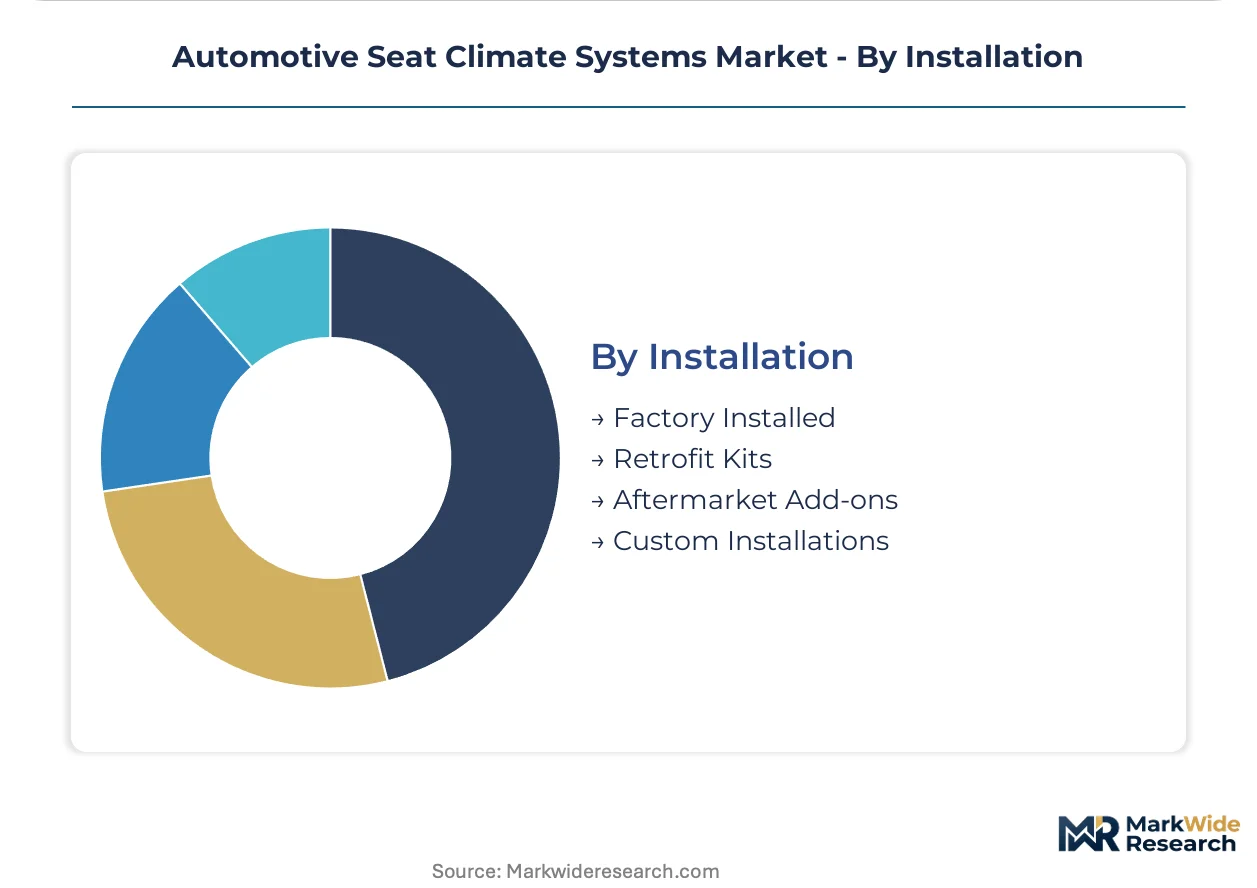
- Factory Installed:Climate systems integrated during seat assembly carry full OEM warranty coverage and undergo vehicle-level validation testing. Continental AG anchors major European OEM programs through this channel.
- Retrofit Kits:Comprehensive packages including modules, wiring, and control interfaces enable dealer or specialist installation. These products unlock margin pools outside captive supply agreements.
- Aftermarket Add-ons:Simplified heating pad and fan systems target price-sensitive consumers through retail and e-commerce distribution.
- Custom Installations:Bespoke climate integration for luxury coaches, specialty vehicles, and mobility conversion applications requires engineering support that standardized kits never demand.
Factory installed holds the largest share; retrofit kits show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity for multi-zone thermal seating, while Indian and Southeast Asian fleet operators prioritize cost-per-cycle durability over feature complexity. This demand bifurcation shapes divergent supplier strategies across major automotive manufacturing clusters.
China
Domestic EV manufacturers specify low-wattage climate seating as standard equipment to preserve battery range under MIIT efficiency mandates. Shanghai and Shenzhen assembly plants source thermoelectric modules from regional suppliers to meet compressed power budgets below 50 watts per zone.
Germany
Premium OEMs mandate independent cushion, backrest, and bolster temperature control as baseline trim requirements. EU F-Gas Regulation constrains compressor-based cooling options, redirecting R&D investment toward thermoelectric and phase-change material architectures in Stuttgart and Munich engineering centers.
United States
Luxury electric vehicle platforms absorb multi-zone thermal seating at rates exceeding mainstream volume tiers. NHTSA occupant safety standards and EPA refrigerant phase-down schedules compress product development cycles for cooling-intensive seat architectures.
India
Component manufacturing incentives under the PLI scheme attract seat climate module assembly for export to Middle Eastern and Southeast Asian vehicle markets. Tamil Nadu and Gujarat production facilities specialize in PTC heater fabrication for cost-sensitive OEM programs.
Japan
Tier-1 seating integrators source climate modules from specialized thermal component vendors for ISO 26262 functional safety certification. Nagoya and Tokyo engineering clusters concentrate on sensor-textile convergence for predictive climate pre-conditioning systems.
Automotive Seat Climate Systems Market Vendor Landscape
Integrated thermal management specialists and dedicated seating component fabricators split the market along technology-architecture lines. The vendor base concentrates around three strategic archetypes: diversified automotive suppliers with captive HVAC portfolios, pure-play thermal component specialists, and vertically integrated seating system integrators. Dominant competitive moves include backward integration into refrigerant handling and textile lamination, plus strategic partnerships with smart material developers to secure conductive yarn supply.
Among diversified automotive suppliers, Continental AG and Denso Corporation exemplify the integrated thermal management archetype. Gentherm Incorporated occupies a position within the pure-play specialist tier. These three companies anchor the competitive structure through their respective concentrations in European, Japanese, and North American supply networks.
| Leading Market Players |
|---|
| Continental AG |
| Aisin Corporation |
| Gentherm Incorporated |
| Denso Corporation |
| Magna International Inc. |
| Adient plc |
| Faurecia (Forvia) |
| Toyota Boshoku Corporation |
| Lear Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese PTC heater fabrication is compressing supplier margins and forcing tier-2 assemblers toward aftermarket retrofit channels where pricing power remains intact. Utilization rates below 70% in Jiangsu and Zhejiang production clusters have triggered inventory liquidation cycles that OEM procurement teams exploit through consolidated platform sourcing.
Pricing Analysis
Aftermarket service revenue drives lifetime value capture across seat climate system portfolios. Three-tier pricing structure across premium thermoelectric, standard PTC, and economy air-circulation levels separates OEM factory-installed programs from dealer retrofit kits and direct-to-consumer add-ons. Price differentiation hinges on ISO 26262 certification grade and MIIT efficiency compliance tier. Cost compression in PTC ceramic elements is intensifying because Asian supplier capacity expansion outpaces EV platform growth. Fleet operators exhibit lowest price sensitivity due to 500,000-cycle durability specifications, while independent vehicle owners in India and Southeast Asia demand economy-tier solutions.
Supply Chain Analysis
Export-control restrictions on bismuth telluride purification technology limit thermoelectric module flows from Chinese suppliers to European and North American assemblers. Geographic supply concentration centers on China for PTC ceramics and smart textile weaving, Germany for precision control electronics, and Japan for sensor-embedded laminates. Raw material dependencies draw from copper interconnects, silver-coated polymer yarns, and phase-change material substrates. Single-source vulnerability in bismuth telluride mining concentration creates procurement risk. Distribution runs through captive OEM supply agreements for factory-installed systems and independent service networks for retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as fleet procurement diverges from passenger car specifications, creating parallel validation protocols that specialist suppliers can exploit without competing against integrated tier-1 giants.
For Market Incumbents: Entrench factory-installed relationships through backward integration into smart textile weaving and captive refrigerant handling capabilities. Consolidate specification authority with German and Chinese OEMs by embedding predictive climate algorithms that require proprietary sensor fusion. Defend against aftermarket encroachment by extending warranty coverage only to dealer-installed retrofit kits, channeling independent service revenue into captive networks. For New Entrants and Emerging Players: Build out aftermarket retrofit distribution through direct-to-consumer platforms targeting luxury vehicle owners in the United States and Germany seeking climate upgrades for vehicles without factory-equipped systems. Focus white-space capture on sensor-textile convergence for predictive pre-conditioning, where established suppliers lack dedicated smart material partnerships. Pursue go-to-market alignment with ride-hailing fleet operators demanding 500,000-cycle durability specifications that incumbent passenger-car product lines cannot satisfy without parallel validation investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart textile architecture development as conductive yarn weaving collapses discrete component tiers into unified material systems. Long-term viability favors acquisition targets with captive smart textile supply agreements and ISO 26262 certification infrastructure already validated. Monitor bismuth telluride export-license approvals as inflection signal for thermoelectric module supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Textile Backward Integration | Captive conductive yarn supply secures German OEM 2026 platform wins against fragmented weaving vendors. |
| Aftermarket Retrofit Channel Expansion | Direct-to-consumer platforms unlock margin pools outside Continental AG's European OEM captive agreements. |
| ISO 26262 Certification Investment | Functional safety validation extends development timelines but creates barrier against unqualified Asian PTC suppliers. |
| Fleet Durability Specification Alignment | 500,000-cycle validation protocols differentiate suppliers for ride-hailing procurement in India and Middle East. |
| Refrigerant-Free Cooling Architecture | Phase-change material approaches bypass EU F-Gas Regulation quotas constraining compressor-based competitors. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and tier-1 supplier procurement patterns anchors the qualitative findings in observable build specifications. Primary interviews with seating system integrators, thermal component specialists, aftermarket distributors, and fleet procurement officers combined with secondary validation from vehicle production databases, IHS Markit registration data, EPA refrigerant phase-down filings, and MIIT efficiency mandate documentation. Bottom-up module shipment analysis triangulates against top-down OEM platform content assumptions.
Calibration against historical adoption curves for heated and ventilated seating across prior vehicle generation cycles informs the projection framework. Segmentation dimensions modeled include product type, technology architecture, installation channel, vehicle propulsion system, and regional regulatory cluster throughout the forecast period. CAGRs derive from fitted diffusion curves adjusted for MIIT efficiency mandate enforcement timelines and EU F-Gas Regulation quota trajectories. Industry-specific inputs incorporate bismuth telluride supply concentration indices and smart textile weaving capacity expansion schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric vehicle-only OEMs would shift outcomes beyond modeled parameters. Material shifts in REACH chemical restriction timelines or bismuth telluride export control designations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive Ventilated Seats Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Argentina Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Bovine Leather Market