
 Europe Automotive Market | 2026-2036
Europe Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Market Intelligence
Software engineering and battery system expertise is rotating the core competencies required within European automotive manufacturing, moving away from traditional mechanical engineering. Volkswagen Group leverages its substantial R&D investments to build out its software-defined vehicle platforms. Stellantis competes by integrating diverse brand portfolios under a unified electrification strategy across its European operations. BMW Group sustains its premium market position through a focus on high-performance electric powertrains and luxury in-car digital experiences.
The European automotive sector encompasses the design, production, and sale of passenger and light commercial vehicles. Vehicles are increasingly defined by their electrical architecture, with many new models built on dedicated EV platforms featuring high-voltage battery packs, typically ranging from 400V to 800V. The Electric and Hybrid fuel types represent the fastest-growing segments, rapidly gaining share from traditional Petrol and Diesel models. Within product types, SUVs continue to command a significant portion of new vehicle sales, with manufacturers prioritizing electrification for these models.
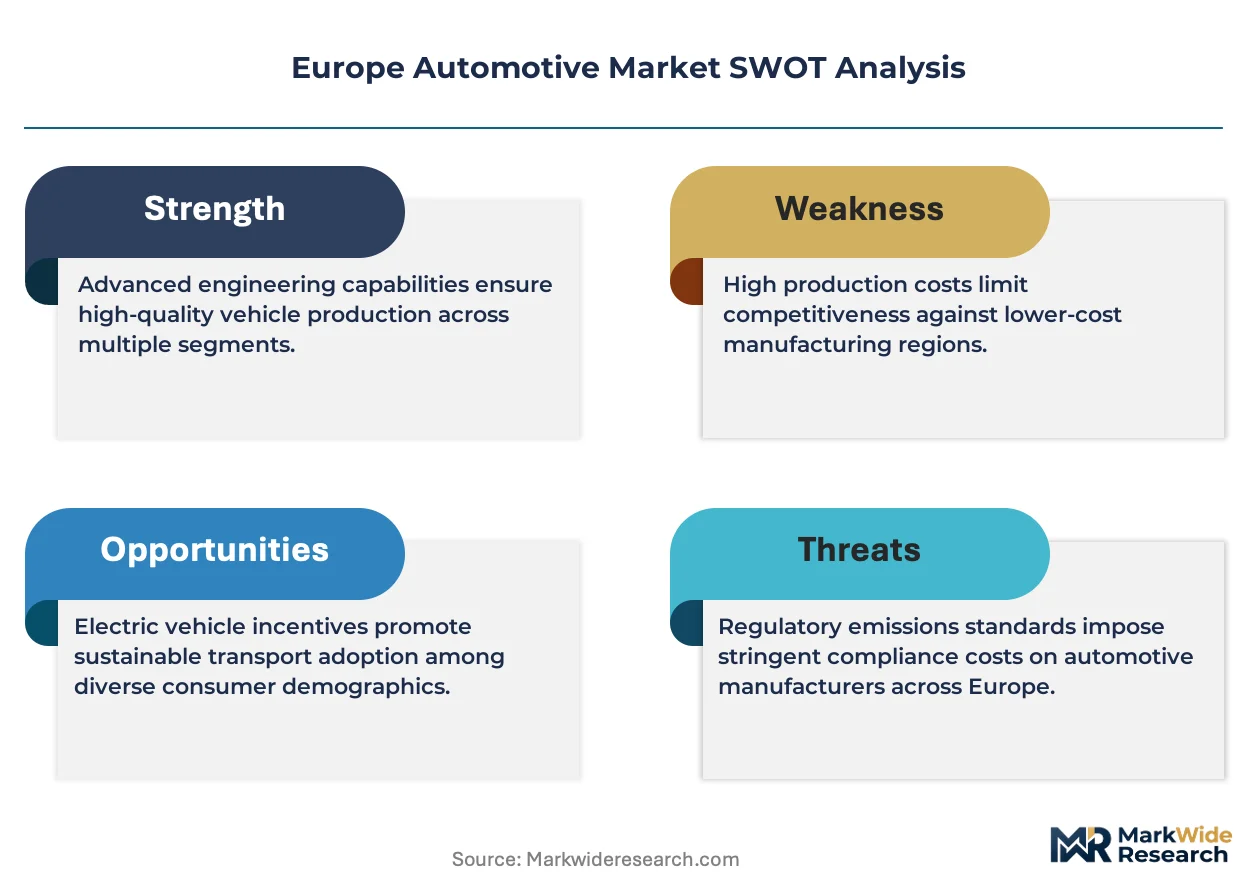
The EU Green Deal and its associated 'Fit for 55' targets are the primary regulatory forces shaping vehicle powertrain development and emissions standards across the continent. Additionally, GDPR compliance dictates how manufacturers handle vast amounts of data from connected vehicles, while CE marking remains essential for all electronic components. Stakeholder success now depends on navigating the dual challenge of securing battery supply chains while simultaneously developing compelling, software-rich user experiences.
Market Dynamics
The European automotive market's structure is being fundamentally reshaped by the regulatory imperative of decarbonization under the EU Green Deal. This single force dictates powertrain technology choices, accelerates capital allocation towards electrification, and redefines competitive advantage around software and battery supply chain control.
Growth Catalysts
- Regulatory Mandates:The European Union's 'Fit for 55' legislative package, with its stringent CO2 emission targets for new vehicles, acts as a direct catalyst for the production and consumer adoption of electric and hybrid models across the continent.
- Technology Advancement:The maturation of 800V electrical architectures enables significantly faster charging times and improved performance, making electric vehicles a more viable alternative to internal combustion engines for a wider range of European consumers.
- Fleet Electrification:Corporate and commercial fleet operators, particularly in logistics and delivery services, are accelerating the transition of their vehicle portfolios to electric to meet corporate sustainability goals and benefit from lower operating costs.
Market Restraints
- Supply Chain Dependency:The European automotive industry's heavy reliance on Asia for battery cells and critical raw materials like lithium and cobalt creates significant supply chain vulnerabilities and exposure to geopolitical risks and price volatility.
- High Capital Expenditure:Retooling existing manufacturing plants for EV production and establishing new battery gigafactories requires massive capital investment, placing significant financial strain on automakers and limiting the pace of transition.
- Infrastructure Gaps:The inconsistent availability and reliability of public charging infrastructure, especially in Southern and Eastern European countries, remains a significant barrier to widespread consumer adoption of electric vehicles.
Strategic Opportunities
- Energy Services Integration:The development of vehicle-to-grid (V2G) capabilities presents an opportunity for automakers to create new revenue streams by enabling EV owners to sell stored energy back to the grid, supporting grid stability.
- Software-as-a-Service (SaaS):Expanding in-car digital experiences and offering features-on-demand through over-the-air (OTA) updates allows for the creation of recurring revenue models, moving beyond the initial point of sale.
- Light Commercial Vehicle (LCV) Electrification:The urban delivery and trades sector remains an underpenetrated market for electrification, offering significant volume potential for purpose-built electric vans and light trucks designed for last-mile logistics.
Industry Challenges
- Talent Re-skilling:A critical shortage of software developers, battery engineers, and data scientists poses a major challenge, requiring a fundamental shift in recruitment and training away from traditional mechanical engineering expertise.
- Data Management and Privacy:Managing the enormous volumes of data generated by connected vehicles while ensuring strict compliance with the EU's GDPR presents a complex technical and legal challenge for all manufacturers.
- Legacy Systems Integration:Automakers face significant operational friction in integrating new, agile software development processes and centralized E/E architectures with decades-old legacy IT systems, supply chains, and dealership networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Market |
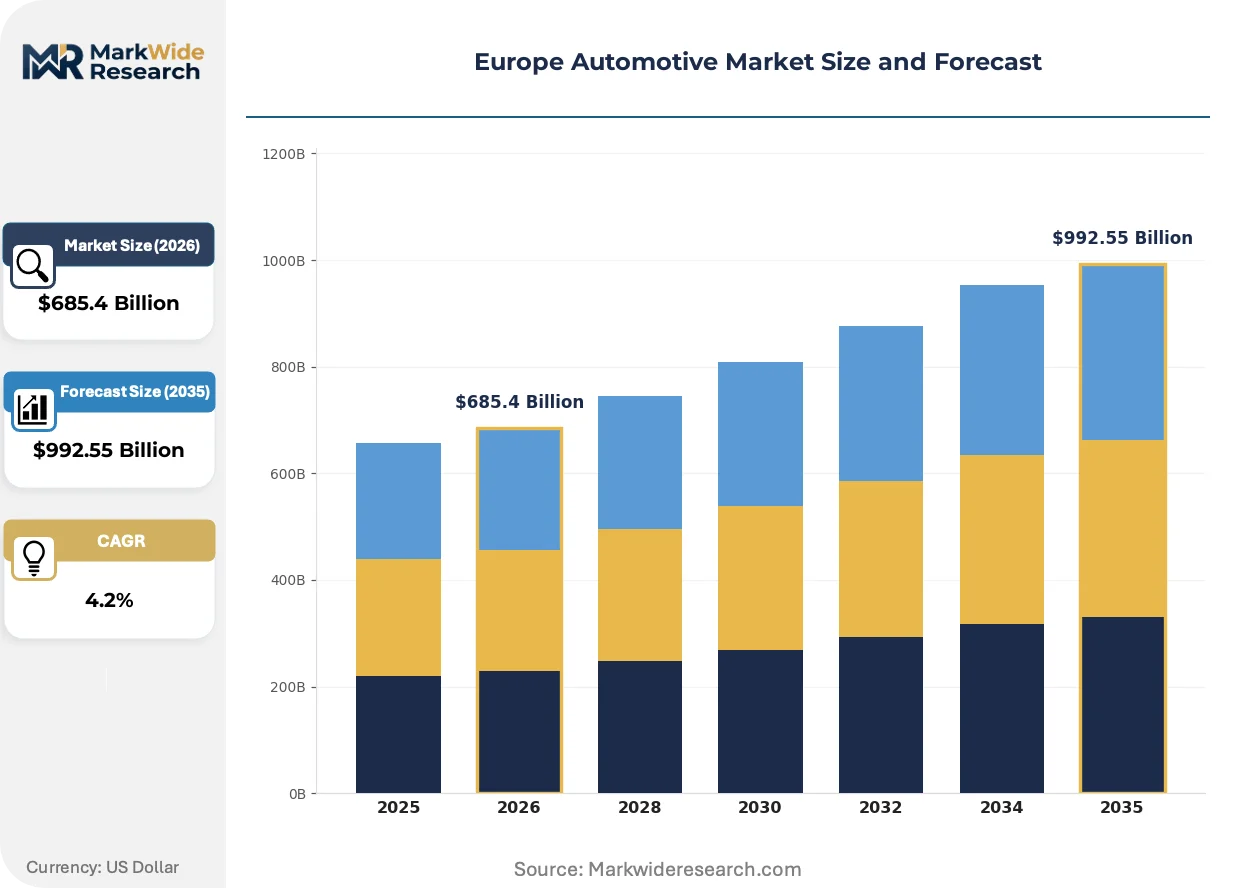
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $992.55 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sedans, SUVs, Hatchbacks, Trucks Component: Engines, Brakes, Transmissions, Infotainment Systems Fuel Type: Petrol, Diesel, Electric, Hybrid Customer Type: Private Consumers, Fleet Operators, Dealerships, OEMs |
| Companies Covered | Hyundai-Kia, General Motors, Volkswagen Group, Honda Motor, Ford Group, Stellantis, BMW Group, BYD, Toyota Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Market Strategic Shifts & Innovations
The defining transformation in the European automotive sector is the vehicle's evolution from a hardware-centric product to a software-defined platform. This shift prioritizes digital user experience, connectivity, and the potential for post-sale feature upgrades, fundamentally altering vehicle design and business models.
Zonal electrical and electronic architecture serves to consolidate computing power from dozens of individual electronic control units (ECUs) into a few high-performance domain controllers. Premium and volume automakers are rapidly adopting this approach in their dedicated EV platforms. The architectural shift is decomposing the traditional, hierarchical automotive supply chain, compelling automakers to engage directly with semiconductor and software firms.
The European Union's Corporate Sustainability Reporting Directive (CSRD) expands and standardizes ESG reporting requirements for large companies. This regulation compels automakers to provide detailed, audited disclosures on their environmental impact, supply chain ethics, and labor practices. The passenger car segment is most impacted, pushing manufacturers to implement robust data collection systems to prove compliance on everything from battery mineral sourcing to factory emissions.
A transition toward flexible, all-inclusive vehicle subscription services is challenging traditional ownership and leasing models. These direct-to-consumer offerings, which bundle the vehicle, insurance, and maintenance into a single monthly fee, are disrupting the established role of franchised dealerships. This trend is most pronounced in major urban areas across Western Europe, where consumers increasingly value access and convenience over long-term asset ownership.
Europe Automotive Market Segmentation
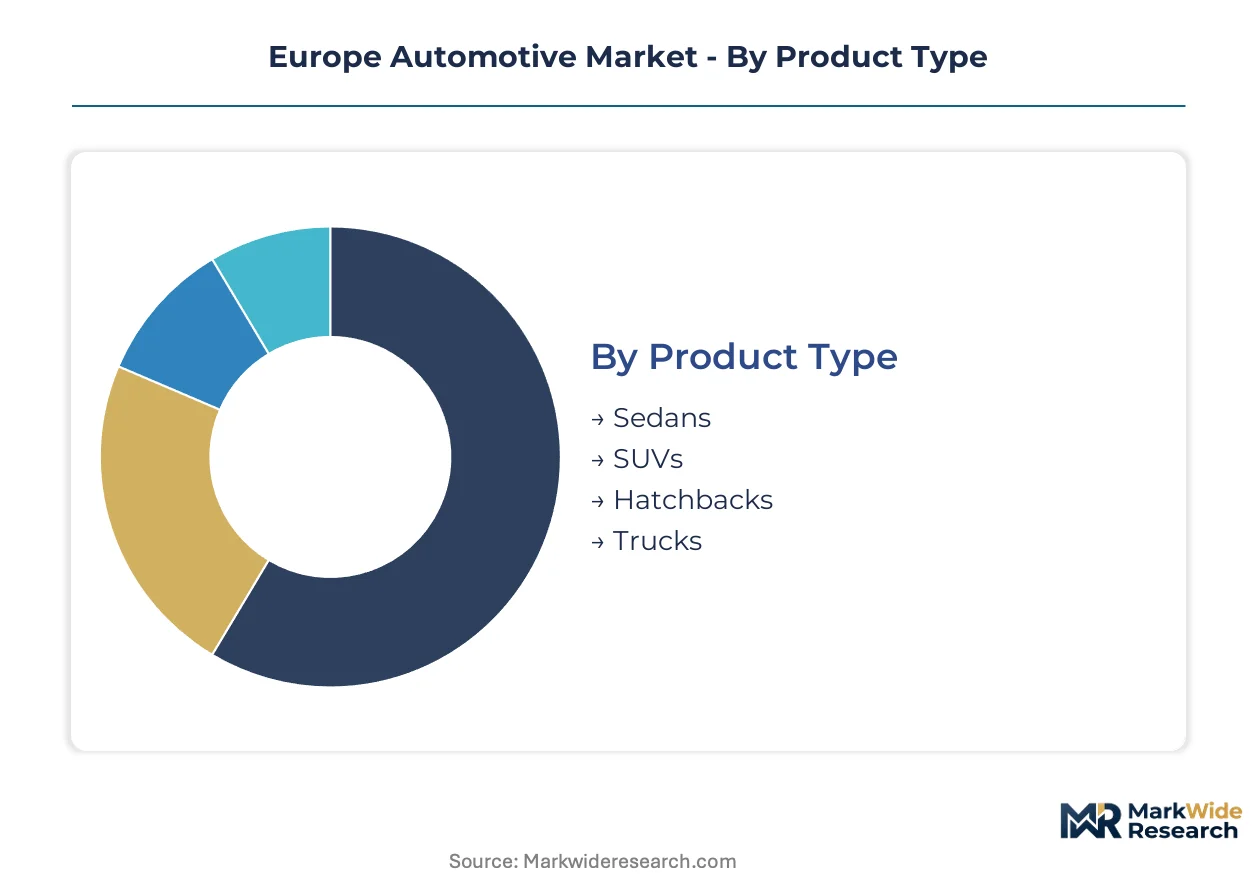
Understanding the segmentation of the Europe Automotive Market reveals key shifts in consumer preferences and strategic priorities for manufacturers. This granular view helps identify where investments in new technologies and production capabilities are most impactful, highlighting evolving demand patterns across the continent.
Product Type:
The distribution of vehicle types across sales channels reflects diverse consumer needs and evolving regulatory landscapes in Europe.
- SUVs:These versatile vehicles combine passenger car comfort with off-road capabilities and higher ride height, often featuring all-wheel drive. Demand for SUVs is concentrating in Germany and the UK, driven by family utility, perceived safety, and the availability of premium electric variants.
- Hatchbacks:Characterized by a compact body and a rear door that swings upward, hatchbacks offer flexible cargo space and urban maneuverability. Demand for these models remains strong in markets like Italy and France, supported by urban driving needs and cost-efficient ownership.
- Sedans:Traditional three-box design passenger cars, sedans maintain a consistent presence in corporate fleets across Europe for their executive appeal and comfort.
- Trucks:Heavy-duty commercial vehicles primarily used for freight and logistics, with growing interest in electric variants for regional and last-mile deliveries.
By volume, SUVs currently dominate new vehicle sales. By growth pace, Hatchbacks are expanding most quickly in specific urban markets.
Component:
The functional hierarchy of vehicle components is undergoing a significant transformation, driven by electrification and digitalization.
- Infotainment Systems:These integrated digital displays and connectivity modules provide navigation, communication, and entertainment functionalities within the vehicle. Demand for advanced infotainment systems is concentrating in premium vehicles across Germany, driven by consumer expectations for sophisticated digital experiences and over-the-air updates.
- Engines:The primary powertrain unit, historically internal combustion (petrol/diesel), is increasingly being replaced or augmented by electric motors. The focus for engine development is shifting towards electric motors in Northern Europe, influenced by stringent emission standards and robust consumer incentives.
- Brakes:Essential safety systems, braking technologies are evolving with regenerative capabilities to recover energy in electric vehicles and enhance overall efficiency.
- Transmissions:Gearbox systems responsible for power delivery from the engine to the wheels, with automatic and electric drive units displacing traditional manual options.
The shift towards software-defined vehicles is significantly elevating the strategic importance of Infotainment Systems.
Fuel Type:
The maturity and adoption curve of different fuel types illustrate the rapid transition occurring within the European automotive sector.
- Electric:Vehicles powered solely by an electric motor and battery pack, producing zero tailpipe emissions, represent a rapidly expanding segment. Demand for electric vehicles is accelerating across Germany and the Netherlands, propelled by regulatory mandates, expanding charging infrastructure, and purchase incentives.
- Hybrid:These vehicles combine an internal combustion engine with an electric motor, offering improved fuel efficiency and reduced emissions compared to conventional models. Demand for hybrid vehicles is strong in markets like Italy and Spain, serving as a bridge technology for consumers hesitant about full electrification.
- Petrol:Traditional internal combustion engines fueled by gasoline, still holding significant market share but facing declining volumes and market access restrictions in Western European cities.
- Diesel:Internal combustion engines known for high torque and fuel efficiency, experiencing a rapid decline in market share due to emission concerns and increasingly stringent urban access regulations.
The market is witnessing a profound transition, with Electric and Hybrid models rapidly gaining share from traditional fuel types.
Customer Type:
Procurement patterns among different customer groups reveal distinct drivers and challenges for vehicle acquisition in Europe.
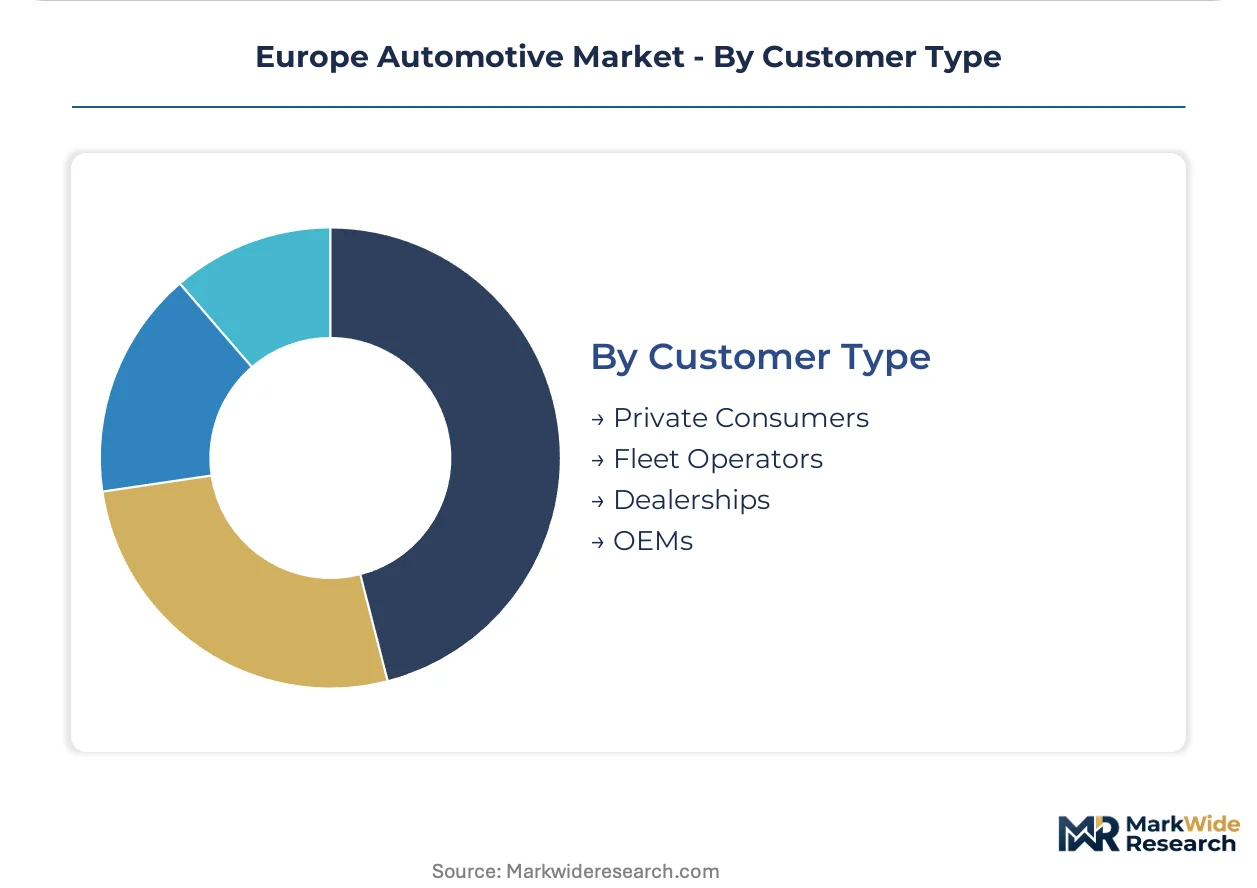
- Fleet Operators:Commercial entities managing large vehicle inventories for logistics, corporate use, or leasing services. Demand from fleet operators is concentrating in the UK and France, driven by corporate sustainability goals and the lower operating costs of electric vehicles over their lifecycle.
- Private Consumers:Individual buyers purchasing vehicles for personal use, typically influenced by brand loyalty, vehicle features, and purchase price. Demand from private consumers is shifting towards electric vehicles in countries with strong purchase incentives, such as Norway and Sweden, alongside expanding charging networks.
- Dealerships:Retail channels responsible for new and used vehicle sales, adapting to direct-to-consumer models from OEMs and evolving after-sales service requirements for electric vehicles.
- OEMs:Original Equipment Manufacturers, increasingly engaging in direct sales and subscription models to control the customer experience and data generated by connected vehicles.
Fleet Operators represent a crucial segment for accelerating electric vehicle adoption across Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and its associated 'Fit for 55' targets provide the primary regulatory framework influencing automotive development across the continent. This legislative package drives powertrain technology choices and accelerates capital allocation towards electrification in key European markets. Germany, as a central manufacturing hub, experiences concentrated demand for electric vehicles and associated charging infrastructure.
Germany
Demand for electric vehicles and advanced charging infrastructure is particularly strong in Germany, driven by national incentives and robust consumer adoption. Germany's 'Fit for 55' implementation and national EV subsidies support the transition to zero-emission mobility. Major automotive clusters in Stuttgart, Munich, and Wolfsburg are at the forefront of developing new EV platforms and battery technologies.
United Kingdom
Fleet operators in the United Kingdom are rapidly electrifying their vehicle portfolios, driven by corporate sustainability goals and lower operating costs. The UK government's net-zero targets and grants for electric vehicles accelerate this transition. Manufacturing centers in the Midlands and research hubs around London focus on battery technology and charging solutions.
France
French demand for electric vehicles and urban-friendly hatchbacks remains robust, supported by strong urban driving needs and national purchase incentives. France's 'Fit for 55' compliance mandates and local emission regulations encourage EV adoption. Automotive production in regions like Paris and Lyon is adapting to increased EV component manufacturing.
Italy
Italian consumers show strong demand for hybrid vehicles, viewing them as a practical bridge technology toward full electrification. Italy's national policies, influenced by the EU Green Deal, offer incentives for lower-emission vehicles. Industrial hubs in Turin and Milan are investing in hybrid powertrain development and compact electric vehicle production.
Netherlands
The Netherlands exhibits accelerating demand for electric vehicles, supported by an expanding charging infrastructure and progressive national policies. Dutch government incentives and the EU Green Deal promote rapid EV uptake. Cities like Amsterdam and Eindhoven are becoming testbeds for smart charging networks and urban electric mobility solutions.
Europe Automotive Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the European automotive competitive landscape. This market structure is characterized by a tiered approach, with legacy OEMs and new EV specialists forming distinct strategic archetypes. Dominant competitive moves include extensive capital allocation towards electrification and strategic partnerships for software development.
Within the established OEM tier, Volkswagen Group and Stellantis exemplify the strategic shift towards software-defined vehicle platforms and unified electrification strategies. BMW Group occupies a premium market position, anchoring its strategy around high-performance electric powertrains and luxury digital experiences. These companies are investing heavily in retooling manufacturing plants and securing battery supply chains.
| Leading Market Players |
|---|
| Hyundai-Kia |
| General Motors |
| Volkswagen Group |
| Honda Motor |
| Ford Group |
| Stellantis |
| BMW Group |
| BYD |
| Toyota Group |
| Others |
Cost & Logistics Intelligence
The EU Green Deal and its associated 'Fit for 55' targets gate both supply qualification and price differentiation for electric vehicles across Europe. This legislative framework directly influences component sourcing strategies and the final pricing of new vehicle models.
Pricing Analysis
Long-term offtake agreements for battery cells define a significant portion of component pricing within the European automotive sector. Price differentiation stems from brand premium for luxury models and advanced software feature sets. Pricing pressure stems from intense competition among OEMs in the volume segments. Private consumers exhibit the highest price sensitivity, particularly for entry-level electric vehicles, while fleet operators prioritize total cost of ownership.
Supply Chain Analysis
Extended lead times for critical components, particularly semiconductors and battery cells, impact European automotive production schedules. Geographic supply concentration for these inputs centers primarily on China and South Korea. This creates single-source vulnerability for European automakers. Raw material dependencies include lithium and cobalt, sourced predominantly from outside Europe. Downstream distribution runs primarily through established franchised dealership networks, although direct-to-consumer models are expanding for electric vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European automotive market is undergoing a high-growth disruption, driven by the rapid shift towards software-defined electric vehicles. This transformation creates both significant challenges and substantial opportunities for market participants.
For Market Incumbents: Shield core internal combustion engine revenue streams through targeted efficiency improvements and hybrid model offerings. Accelerate investment in dedicated EV platforms to counter emerging EV specialists. The threat of new software-first entrants necessitates deepening vertical integration into software development capabilities. Consolidate component sourcing to mitigate supply chain vulnerabilities.
For New Entrants and Emerging Players: Lead with purpose-built electric light commercial vehicles to address underpenetrated urban delivery markets. Target underserved Southern and Eastern European geographies with cost-effective, practical electric models. The most penetrable segment remains last-mile logistics fleets seeking lower operating costs. Offer flexible vehicle subscription services as a direct-to-consumer go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established Tier 1 automotive suppliers struggling with software integration. Long-term viability hinges on identifying firms with proprietary battery management systems or advanced sensor technologies. Acquisition targets should include software development houses specializing in automotive operating systems. The signal to watch is the increasing standardization of electrical architectures, indicating market maturity for integration plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces development costs and accelerates time-to-market for new electric vehicle models across Europe. |
| Battery Supply Agreement | Secures critical raw material access and stabilizes production for European automotive manufacturers. |
| Software-Defined Vehicle Investment | Elevates in-car digital experiences and enables new recurring revenue streams for OEMs. |
| Charging Infrastructure Partnership | Addresses consumer anxiety regarding range and supports electric vehicle adoption in key markets. |
| Light Commercial Vehicle Electrification | Capitalizes on robust demand from urban delivery services and corporate fleet operators. |
Research Approach
Cross-validation between primary interviews and secondary data anchors the qualitative findings within this analysis. Primary insights were gathered from OEM platform engineers, Tier 1 supplier procurement teams, and fleet managers across Europe. Secondary validation involved reviewing vehicle production databases, IHS Markit registration data, and EU regulatory filings. This approach ensured robust bottom-up and top-down triangulation of market dynamics.
Sensitivity analysis informed the projection of market values across the analysis window. The analytical framework modeled segmentation dimensions including vehicle class, propulsion architecture, content per vehicle, and regional production clusters. Compound annual growth rates were derived from historical data trends and anticipated technological advancements. Key inputs included battery cell cost trajectories and charging infrastructure deployment rates.
The analysis sits within stated boundaries; outcomes outside significant geopolitical shifts or raw material price volatility would require recalibration. Forecasts reflect assumptions regarding regulatory stability and technological adoption rates across Europe. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Subframe Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
North America Automotive Intercooler Market