
 Iraq Lubricants Market | 2026-2036
Iraq Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Lubricants Market Foresight
Power generation and oilfield machinery maintenance is recalibrating lubricant procurement patterns across Iraq. Shell PLC leverages its Basra blending facility to sustain supply continuity for industrial customers. TotalEnergies anchors its position through direct sales channels serving state-owned power utilities. Petromin Corporation specializes in automotive maintenance formulations for the growing vehicle fleet segment.
Lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in mechanical systems, with viscosity grades and oxidation stability determining service intervals. Engine oil dominates volume flows due to the large installed base of passenger and commercial vehicles operating in severe thermal conditions. Industrial machinery applications represent the fastest-expanding category as oilfield equipment operators extend drain intervals through synthetic formulations. Marine operations remain a niche segment constrained by port infrastructure limitations.
Iraq's Ministry of Oil enforces petroleum product quality specifications that govern base oil sourcing and additive package approvals for domestic blenders. The Central Organization for Standardization and Quality Control administers conformity assessment protocols aligned with regional technical regulations. Stakeholders must monitor evolving sulfur content limits and import licensing procedures that shape formulation strategies and supply chain configurations.
Market Dynamics
Iraq's lubricant procurement patterns are being fundamentally altered by the Ministry of Oil's tightening quality mandates for petroleum products. These formulation standards are forcing blenders to requalify additive packages and source higher-grade base oils.
Growth Catalysts
- Automotive Fleet Density:Baghdad, Basra, and Erbil are registering sustained vehicle population increases. Fleet operators are expanding scheduled maintenance programs that specify synthetic engine oils.
- REACH-Aligned Additive Approvals:Iraq's Central Organization for Standardization and Quality Control is adopting conformity assessment protocols that mirror European technical regulations. This accelerates import licensing for pre-certified formulation packages.
- Oilfield Equipment Intensification:Power generation and upstream machinery clusters are extending drain intervals through high-performance industrial lubricants. Synthetic formulations now dominate preventive maintenance schedules for gas turbines and drilling rigs.
Market Restraints
- Base Oil Import Dependency:Domestic blenders source the majority of Group II and III base stocks from external suppliers. Price volatility in Middle Eastern refining corridors compresses formulation margins.
- Sulfur Content Compliance Costs:Ministry of Oil specifications for low-sulfur lubricant grades require additive system overhauls. Small-scale blenders face capital barriers to achieving certification.
- Port Infrastructure Bottlenecks:Umm Qasr and Khor al-Zubair container handling constraints delay bulk lubricant deliveries. Marine logistics limitations restrict just-in-time inventory models for industrial customers.
Strategic Opportunities
- Kurdistan Region Industrial Corridors:Erbil and Sulaymaniyah manufacturing zones remain underpenetrated by certified lubricant distributors. Local blending capacity expansion would capture power generation and construction equipment demand.
- Extended Drain Interval Technology:Synthetic PAO and ester-based formulations enable 15,000+ kilometer service intervals. Automotive fleet operators in Baghdad are piloting these specifications to reduce downtime.
- Direct Utility Procurement Channels:State-owned power generation companies are consolidating supplier relationships. Lubricant vendors with Ministry of Oil pre-qualification can bypass distributor markups.
Industry Challenges
- Formulation Chemist Shortage:Blending facilities in Basra struggle to recruit specialists in oxidation stability testing and viscosity index modification. Technical talent pipelines from Iraqi universities remain underdeveloped.
- Additive Package Registration Timelines:Central Organization for Standardization and Quality Control approval cycles for new lubricant specifications extend 18-24 months. Product launch delays disadvantage innovators against established portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Lubricants Market |
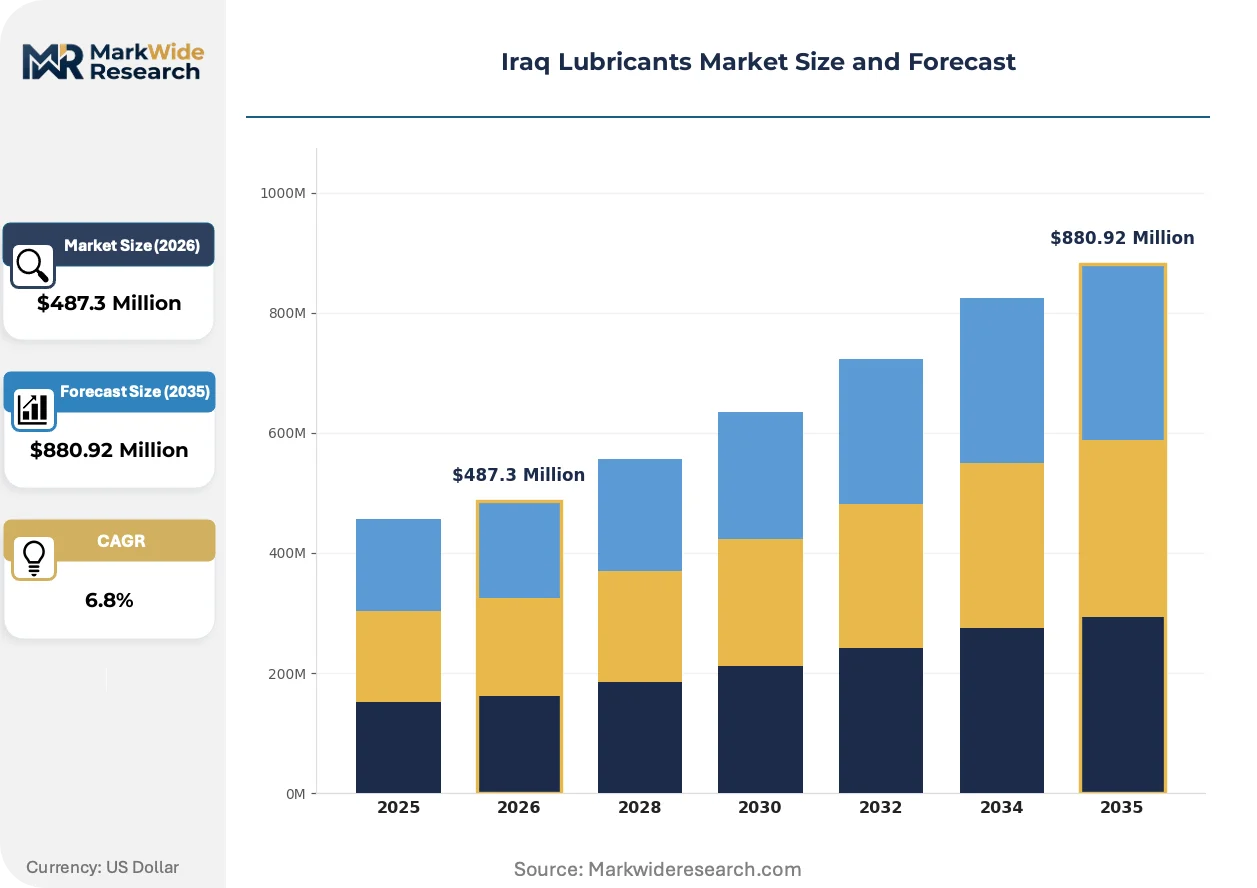
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Oil, Gear Oil, Grease End User: Automotive, Industrial, Marine, Aviation Sales Channel: Retail, Wholesale, Online, Direct Sales Application: Automotive Maintenance, Industrial Machinery, Marine Operations, Vehicle Fleet |
| Companies Covered | FUCHS, Petronas, TotalEnergies, Behran Oil Company, Rumanza, Shell PLC, Chevron, Petromin Corporation, ExxonMobil, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Lubricants Market Shifts & Advancements
Synthetic lubricant technology is penetrating Iraq's industrial maintenance sector at an accelerating pace. Three intersecting developments are compressing traditional mineral oil replacement cycles and reshaping procurement specifications across automotive and machinery segments.
Polyalphaolefin (PAO) synthetic base stocks deliver superior thermal stability and oxidation resistance compared to Group I mineral oils. Oilfield services operators in Basra are adopting these formulations for gas turbine and compressor applications. PAO technology is expanding into segments previously served by conventional mineral oils, enabling extended drain intervals that reduce maintenance downtime.
Iraq's Ministry of Oil quality mandates for petroleum products are tightening sulfur content limits and additive package certification requirements. Blenders must now submit formulation data to the Central Organization for Standardization and Quality Control for conformity assessment. Industrial machinery applications face the steepest compliance burden, as high-temperature equipment specifications demand reformulated antioxidant and anti-wear systems.
Fleet operators in Baghdad are consolidating lubricant procurement through direct distributor relationships rather than fragmented retail channels. Large commercial vehicle operators now negotiate annual volume contracts with certified blenders, bypassing traditional automotive service station networks. This concentration is most visible among construction and logistics companies operating standardized vehicle platforms across southern Iraq.
Iraq Lubricants Market Segmentation
Lubricant procurement in Iraq fragments across technical specifications, customer scale, and distribution reach. Each segmentation dimension reveals distinct margin profiles and capital requirements that shape blender investment priorities across Baghdad, Basra, and Erbil.
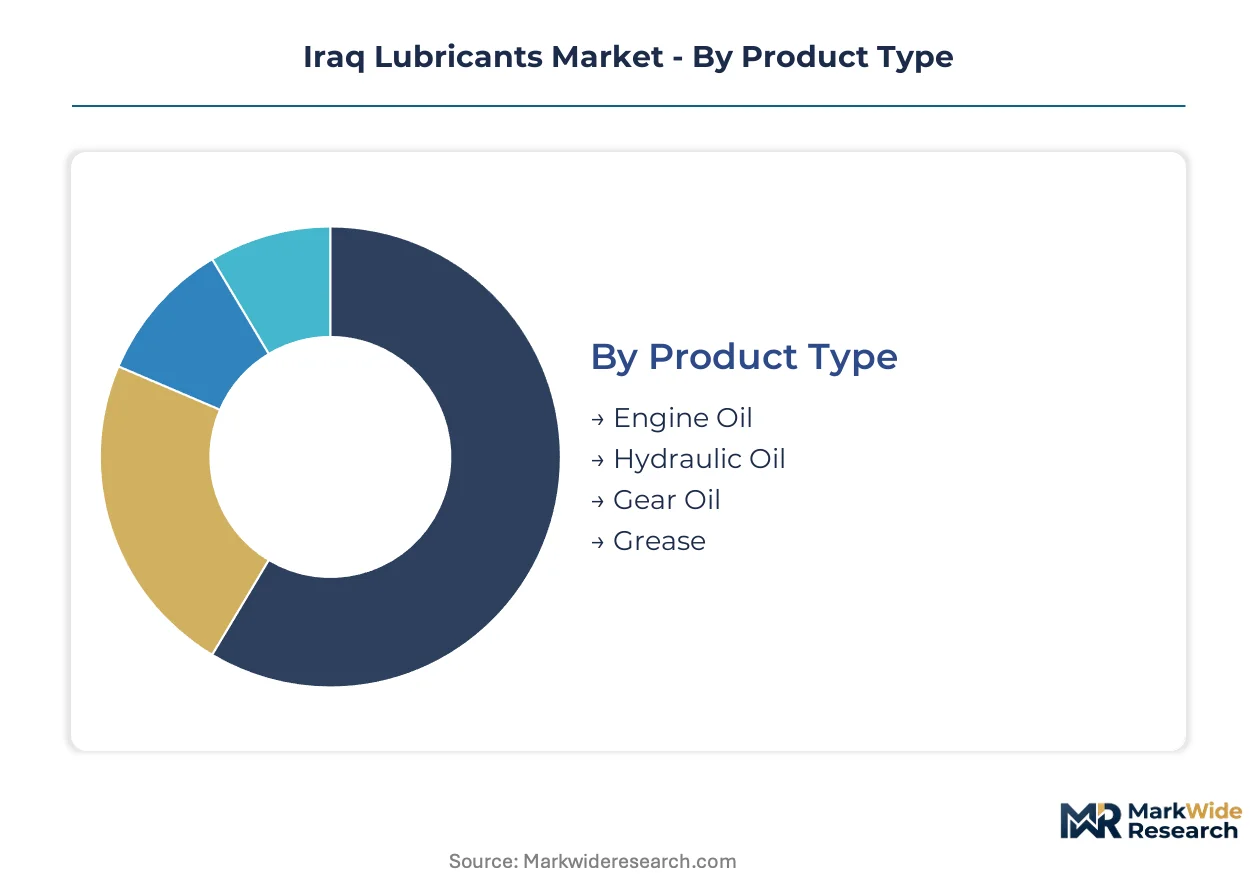
Product Type:
Capital intensity varies sharply across formulation categories, with synthetic base stock requirements and additive package complexity driving facility investment thresholds.
- Engine Oil:Formulations blend Group II/III base oils with detergent-dispersant and anti-wear additive packages calibrated for high-temperature combustion environments. Baghdad automotive service stations and Basra fleet operators consume the majority of volume, with synthetic grades commanding premium positioning as drain intervals extend.
- Hydraulic Oil:These formulations prioritize viscosity stability and oxidation resistance for high-pressure fluid power systems. Oilfield services operators in southern Iraq specify zinc-free variants for subsea equipment, creating demand concentration in Basra's petroleum engineering clusters.
- Gear Oil:Extreme-pressure additives protect transmission and differential components under heavy load conditions. Construction equipment fleets in Erbil and Sulaymaniyah generate steady procurement for multigrade hypoid formulations.
- Grease:Thickener systems suspend base oil for slow-speed, high-load bearing applications. Cement plants and steel rolling mills in central Iraq specify lithium complex and calcium sulfonate grades for kiln support rollers.
Engine oil absorbs the bulk of installed capacity; hydraulic oil is expanding most quickly as oilfield equipment intensification accelerates.
End User:
Customer scale determines procurement channel access and pricing leverage, with state-affiliated entities consolidating volume commitments.
- Automotive:Passenger vehicles, commercial trucks, and bus fleets operate across severe thermal and dust conditions. Baghdad's rising vehicle density and Erbil's logistics corridor expansion concentrate demand for API SP and ILSAC GF-6 certified formulations.
- Industrial:Power generation turbines, cement kilns, and steel processing equipment require specialized thermal stability. State-owned electricity utilities in Basra and Baghdad negotiate direct supply contracts with Ministry of Oil pre-qualified blenders.
- Marine:Port operations at Umm Qasr and Khor al-Zubair drive limited demand for trunk piston and system oils. Infrastructure bottlenecks constrain segment scale despite Iraq's coastline position.
- Aviation:Baghdad International Airport and Basra International Airport maintenance facilities specify turbine oils meeting SAE AS5780 standards. Volume remains constrained by limited commercial aviation activity.
Industrial end users concentrate the highest per-customer value; automotive accounts for the widest geographic dispersion.
Sales Channel:
Channel economics reflect inventory carrying costs, credit risk exposure, and technical service requirements that segment blender profitability.
- Retail:Automotive service stations and parts shops in Baghdad, Basra, and Erbil stock fast-moving consumer-packaged lubricants. Shelf space competition favors established brands with Ministry of Oil certification visibility.
- Wholesale:Distributors aggregate volume across multiple end users, extending credit terms and technical support. Kurdistan Region distributors maintain regional blending and warehousing to serve construction and agriculture equipment fleets.
- Online:E-commerce penetration remains nascent for bulk lubricant procurement, with limited logistics infrastructure supporting drum and tote deliveries beyond major urban centers.
- Direct Sales:Large fleet operators and state utilities bypass distributor markups through annual volume contracts. Central Organization for Standardization and Quality Control certification enables direct qualification for public procurement tenders.
Wholesale channels handle the majority of industrial volume; direct sales is climbing the fastest as fleet consolidation accelerates.
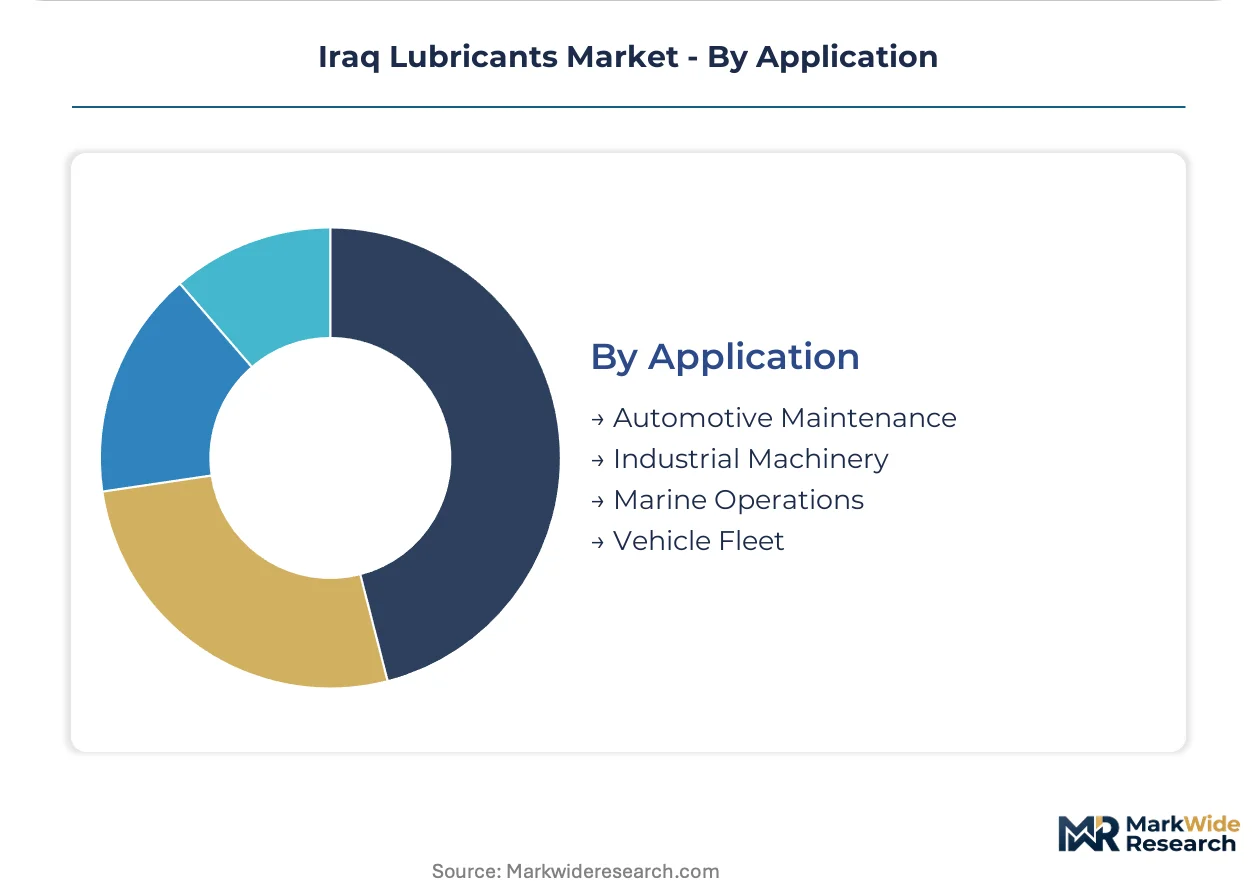
Application:
Operating environment severity and equipment criticality determine formulation specification stringency and service interval economics.
- Automotive Maintenance:Scheduled oil changes for passenger and commercial vehicles follow manufacturer warranty requirements. Synthetic formulations enabling 10,000+ kilometer intervals are displacing mineral oils in Baghdad fleet operations.
- Industrial Machinery:Gas turbines, compressors, and pumps in oilfield and power generation clusters demand predictive maintenance alignment. Basra's upstream facilities specify condition-monitoring-compatible lubricants with extended oxidation stability.
- Marine Operations:Stern tube and main engine lubrication for cargo vessels faces port handling constraints at Umm Qasr. Bunkering infrastructure limitations restrict segment development despite geographic potential.
- Vehicle Fleet:Standardized commercial vehicle platforms operated by logistics and construction companies consolidate procurement specifications. Direct blender relationships replace fragmented retail purchasing across southern Iraq corridors.
Automotive maintenance retains the largest volume base; industrial machinery is gaining share fastest as equipment uptime premiums justify synthetic formulation premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Al-Zubair Petrochemical Industrial Zone near Basra concentrates lubricant blending capacity through tax incentives for petroleum derivatives manufacturing. Ministry of Oil licensing requirements favor facilities within designated industrial corridors.
Baghdad Governorate
Automotive fleet density in Baghdad drives lubricant consumption through passenger vehicle maintenance and commercial transport operations. Ministry of Oil quality mandates require additive package certification for all formulations sold within the capital region. Sadr City and Karrada automotive service districts host the highest concentration of certified lubricant retail points.
Basra Governorate
Oilfield machinery maintenance in Basra generates industrial lubricant demand for gas turbines and drilling equipment. Central Organization for Standardization and Quality Control conformity assessment protocols govern import licensing for base stocks entering through Umm Qasr port. Al-Zubair industrial corridor clusters blending facilities serving upstream petroleum engineering contractors.
Erbil Governorate
Construction equipment fleets in Erbil create steady procurement for gear oil and hydraulic formulations. Kurdistan Regional Government industrial licensing operates parallel to federal Ministry of Oil frameworks. Ankawa and Christian quarter logistics zones concentrate wholesale distributor warehousing for northern Iraq coverage.
Sulaymaniyah Governorate
Manufacturing zone expansion in Sulaymaniyah attracts lubricant distributors serving power generation and cement processing equipment. Regional quality standards alignment with federal specifications remains incomplete. Halabja industrial corridor development plans include dedicated petroleum products storage infrastructure.
Dhi Qar Governorate
Agricultural mechanization in Dhi Qar generates seasonal lubricant demand for tractor and irrigation pump maintenance. Provincial industrial development initiatives lack dedicated petroleum products regulatory capacity. Nasiriyah equipment markets rely on Baghdad-supplied formulations with extended distribution lead times.
Iraq Lubricants Market Competitive Landscape
Top-tier vendors anchor the premium synthetic segment, while mid-scale blenders compete on formulation flexibility for industrial specifications. Market structure reflects a three-tier hierarchy: multinational petroleum majors with domestic blending assets, regional specialists with Ministry of Oil pre-qualification, and local distributors without formulation capabilities. Strategic archetypes include integrated petroleum majors leveraging upstream feedstock access, additive technology licensors partnering with domestic blenders, and fleet-focused service providers consolidating procurement relationships. Competitive moves concentrate on direct utility contract capture and extended drain interval technology licensing.
Among petroleum majors with Iraqi blending presence, Shell PLC and TotalEnergies exemplify the integrated archetype through Basra facility operations and state utility direct sales channels. Petromin Corporation occupies a position representing the fleet-service specialist tier with automotive maintenance focus. These three entities illustrate competitive positioning across the premium formulation and direct procurement vectors without implying specific market share claims.
| Leading Market Players |
|---|
| FUCHS |
| Petronas |
| TotalEnergies |
| Behran Oil Company |
| Rumanza |
| Shell PLC |
| Chevron |
| Petromin Corporation |
| ExxonMobil |
| Others |
Supply & Pricing Matrix
Baghdad fleet operators consolidating procurement through annual volume contracts are compressing distributor margins and forcing blenders to absorb logistics costs or surrender retail shelf presence. This buyer-side concentration rewards facilities with direct utility relationships while squeezing undifferentiated packagers.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with state utilities paying above-market rates for guaranteed 48-hour delivery windows while spot inventory trades at discounts. Pricing stratifies across premium synthetic, standard mineral, and economy re-refined tiers, with certification grade and volume scale as primary differentiation drivers. Cost compression in the economy tier is intensifying because small blenders lack Ministry of Oil pre-qualification for direct sales. Fleet operators show the highest price sensitivity; state-owned power utilities the least.
Supply Chain Analysis
Ministry of Oil domestic-content mandates for petroleum derivatives are reshaping sourcing toward Al-Zubair corridor facilities with local blending licenses. Base oil supply draws from Kuwait, Saudi Arabia, and the United Arab Emirates; additive packages feed from Singapore and European specialty chemical hubs. Single-source vulnerability concentrates in Group III base stock channels through the Strait of Hormuz. Distribution runs through Basra bulk terminals, with Baghdad and Erbil served by rail-tanker and road-fleet networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ministry of Oil quality mandate enforcement is accelerating consolidation, as certification costs and reformulation timelines eliminate capital-constrained blenders unable to achieve Central Organization for Standardization and Quality Control approval.
For Market Incumbents: Lock in direct procurement relationships with state-owned electricity utilities before tender consolidation closes. Extend backward integration into additive package blending at Basra facilities to reduce import licensing exposure. Defend against regional specialists by securing exclusive annual volume contracts with construction equipment fleets in Erbil and Sulaymaniyah.
For New Entrants and Emerging Players: Kurdistan Region construction equipment operators remain underserved by certified lubricant distributors with local warehousing. Capture this white-space through portable blending unit deployment at Ankawa logistics zones, bypassing federal import licensing delays. Lead with hydraulic oil formulations for cement processing and power generation equipment, then expand into gear oils.
For Investors and Strategic Acquirers: The window for entry favors additive technology licensors with existing Central Organization for Standardization and Quality Control dossiers. Long-term viability rests on owning Ministry of Oil pre-qualified blending capacity rather than distribution relationships. Watch for inflection when federal-Kurdistan regulatory alignment completes, collapsing the dual-track compliance burden.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Blending | Captures margin from imported packages and accelerates Central Organization for Standardization and Quality Control approval cycles. |
| Direct Utility Procurement Channel Development | Bypasses distributor markups and locks in multi-year offtake agreements with Ministry of Oil pre-qualified status. |
| Kurdistan Region Blending Capacity Expansion | Addresses underpenetrated Erbil and Sulaymaniyah industrial corridors with localized formulation and warehousing. |
| Synthetic Formulation Technology Licensing | Enables extended drain interval positioning for Baghdad fleet operators seeking reduced maintenance downtime. |
| Extended Drain Interval Product Line Launch | Differentiates against mineral oil competitors through PAO-based formulations for oilfield gas turbine applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across lubricant blending plant managers, Ministry of Oil certification officers, fleet procurement directors, and downstream distributor principals. Ministry of Oil petroleum product specifications, Central Organization for Standardization and Quality Control conformity assessment protocols, and Umm Qasr port import manifests provided formulation and flow validation. Bottom-up volume estimates triangulated against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling operated at product type, end user, and sales channel dimensions, with synthetic versus mineral formulation splits tracked separately. CAGRs derived from trend extrapolation of vehicle fleet growth, oilfield equipment intensification, and power generation capacity expansion. Forecast inputs incorporated Ministry of Oil quality mandate phase-in schedules and Kurdistan Regional Government industrial licensing trajectory.
Revisions become necessary when regulatory alignment between federal and Kurdistan authorities accelerates, port infrastructure bottlenecks at Umm Qasr ease, or base oil supply disruptions from Gulf refining corridors materialize. Forecasts reflect documented assumptions about additive package approval timelines and fleet operator consolidation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Contact Lubricants Market
Lubricants
Chile Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Global Aerospace Lubricant Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
South Korea Lubricants Market