
 Brazil Automotive Lubricants Market | 2026-2036
Brazil Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Lubricants Market Outlook
Brazil's lubricant blending capacity in the São Paulo industrial corridor is consolidating around integrated petrochemical complexes. Petrobras Lubrificantes leverages captive feedstock access to anchor its position in heavy-duty diesel formulations. Shell Brazil competes through retail channel control spanning posto networks across southeastern states. ExxonMobil differentiates via synthetic product specialization targeting fleet operator contracts.
Brazil automotive lubricants are formulated hydrocarbon-based fluids engineered with viscosity grades typically spanning SAE 0W-20 to 15W-40, incorporating detergent-dispersant and anti-wear additive packages to reduce friction and thermal degradation in internal combustion engines. Their primary commercial purpose is extending powertrain operational life while maintaining fuel economy compliance under tropical operating conditions. Engine oil formulations occupy the dominant margin pool given high replacement frequency in stop-start urban traffic patterns, while transmission fluid demand accelerates fastest as automatic gearbox penetration rises among passenger cars in Brazil's premium segment. Fleet operators represent a concentrated volume channel where direct sales arrangements with lubricant suppliers are displacing traditional wholesale intermediaries.
ANVISA governs chemical substance registration and toxicological disclosure for lubricant additives sold in Brazil, while Petrobras-affiliated testing laboratories enforce proprietary performance benchmarks that shape product qualification requirements. The country's national petroleum regulator monitors fuel-lubricant compatibility standards that directly affect formulation specifications for ethanol-blended gasoline engines. Stakeholders must monitor how impending updates to Brazil's chemical inventory rules will reshape additive sourcing strategies and reformulation timelines.
Market Dynamics
Fleet operators across São Paulo state's logistics corridor are compressing oil drain intervals and mandating synthetic formulations, reshaping volume flows toward premium product tiers and direct supplier contracts.
Growth Catalysts
- ANVISA additive disclosure mandates:Reformulation requirements are accelerating R&D investment in cleaner additive packages that meet tightened toxicological thresholds for Brazilian commercial registration.
- Ethanol-blended gasoline compatibility standards:Brazil's national petroleum regulator has tightened fuel-lubricant compatibility benchmarks, forcing lubricant producers to develop specialized formulations for flex-fuel engine protection.
- Automatic transmission penetration:Premium passenger car segments in southeastern manufacturing belts are driving accelerated demand for specialized transmission fluid technologies.
Market Restraints
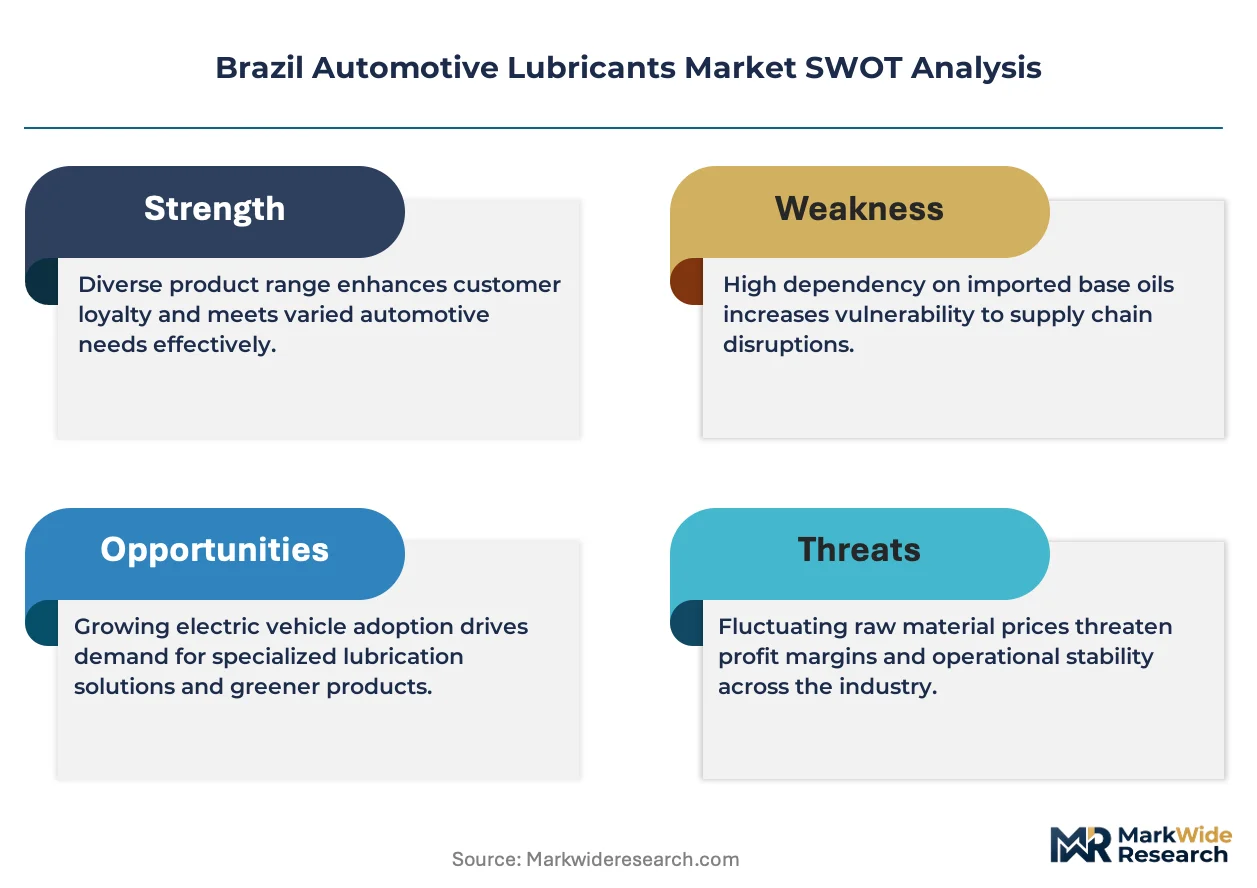
- Base oil supply concentration:Captive feedstock access at Petrobras-affinated refineries limits independent blender participation in heavy-duty diesel formulation segments.
- ANVISA registration timelines:Extended chemical substance approval cycles delay new additive introduction by 18-24 months, compressing product refresh rates.
- Extended drain interval technologies:Synthetic formulation durability advances threaten volume replacement frequency in mature fleet accounts.
Strategic Opportunities
- Minas Gerais industrial corridor expansion:Heavy machinery clusters outside São Paulo core present underpenetrated demand for specialized hydraulic and gear lubricants.
- Direct fleet contracting models:Bypassing traditional wholesale intermediaries enables margin capture through integrated fluid analysis and predictive maintenance service bundling.
- Used oil collection and re-refining infrastructure:Emerging regulatory frameworks for circular economy compliance create vertical integration possibilities in waste lubricant recovery.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in tropical-condition additive balancing remains concentrated at legacy Petrobras-affiliated technical centers.
- Multi-standard certification complexity:Simultaneous compliance with API, ACEA, and proprietary OEM specifications fragments product portfolio requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Lubricants Market |
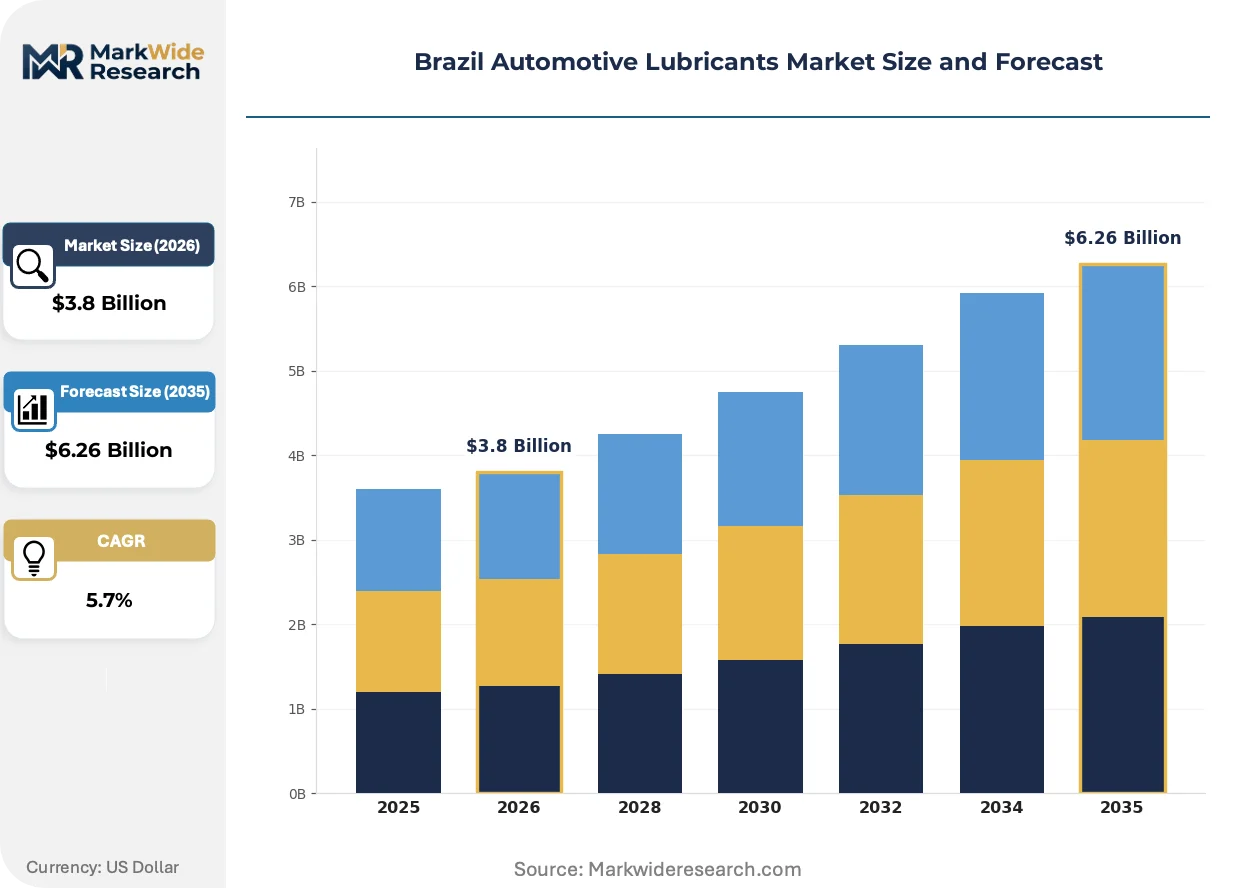
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Brake Fluid End User: Passenger Cars, Commercial Vehicles, Two-Wheelers, Fleet Operators Application: Petrol Engines, Diesel Engines, Heavy-Duty Applications, Marine Applications Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | PETRONAS Lubricants International, TotalEnergies, ExxonMobil Corporation, Shell Brazil, Chevron Corporation, Iconic Lubrificantes, Royal Dutch Shell Plc, Petrobras Lubrificantes, Petrobras, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Lubricants Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing parallel transformation as Brazilian lubricant markets adapt to tighter chemical oversight and compressed buyer decision cycles.
Polyalphaolefin (PAO) and Group III+ base oil technologies are consolidating market share in fleet operator specifications, displacing mineral-derived alternatives in high-temperature, high-load operating environments. São Paulo-based logistics fleets with centralized procurement functions have accelerated synthetic adoption to 12-month drain intervals. This consolidation is compressing price differentiation between mid-tier and premium product categories.
ANVISA's updated chemical substance registry framework is tightening additive disclosure thresholds and mandating toxicological data submission for imported additive packages. The industrial consequence is a restructuring of supply relationships toward suppliers with established Brazilian registration capabilities. Engine oil additive packages face the most acute compliance burden, with reformulation timelines extending qualification cycles for new product introductions.
Fleet procurement functions are consolidating lubricant purchasing through centralized technical specifications and direct supplier negotiations, displacing decentralized posto-based procurement patterns. Traditional wholesale intermediaries in southeastern distribution networks are losing volume share to manufacturer-direct service contracts. This concentration is most visible in São Paulo state's refrigerated transport and last-mile delivery segments.
Brazil Automotive Lubricants Market Segmentation
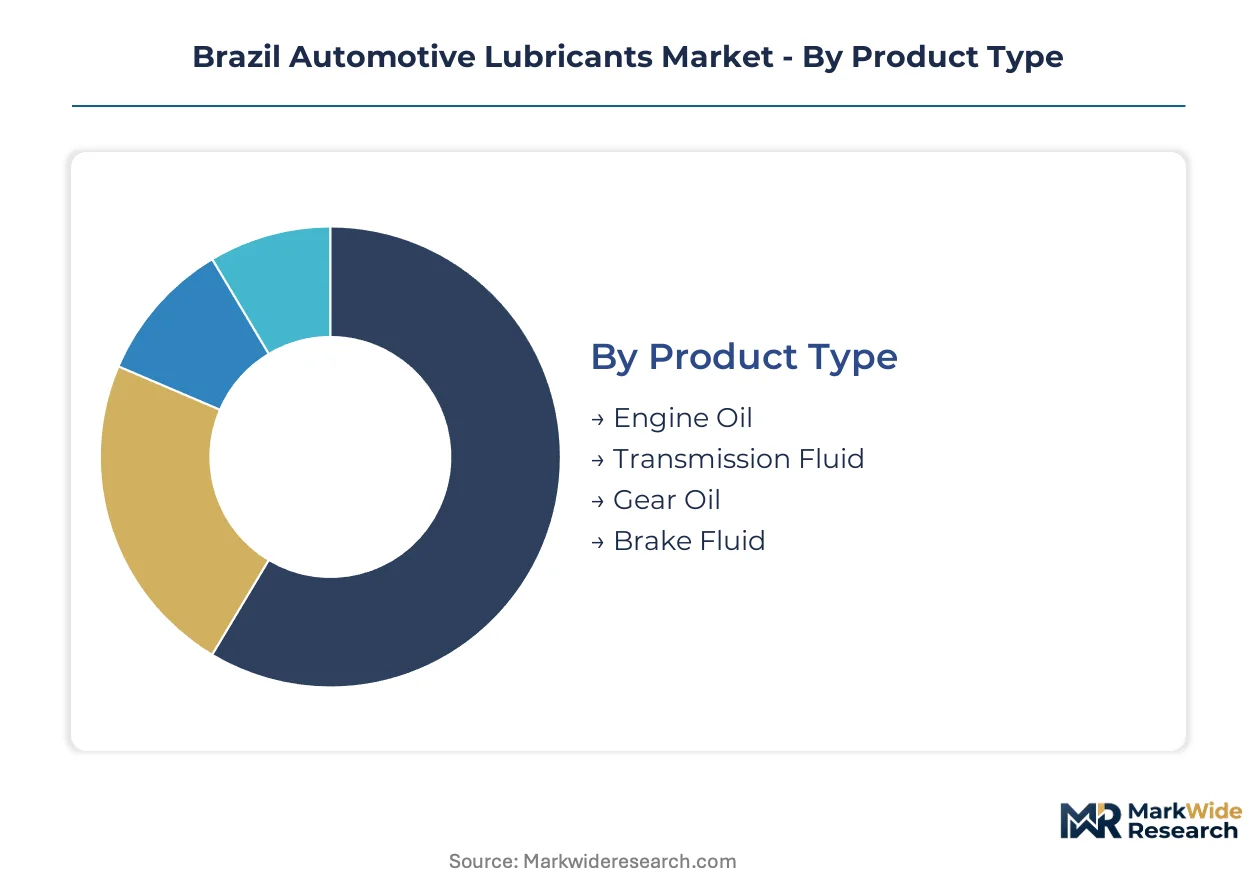
Segmentation in Brazil's automotive lubricants market reflects divergent regulatory burdens and procurement patterns across product categories. Fleet operators and independent workshops face distinct certification requirements that reshape channel economics and formulation priorities.
Product Type:
ANVISA registration intensity varies sharply across product categories, with engine oils carrying the heaviest additive disclosure burden while brake fluids face lighter toxicological scrutiny.
- Engine Oil:Hydrocarbon-based formulations span SAE 0W-20 to 15W-40 viscosity grades with detergent-dispersant packages. São Paulo fleet operators are compressing drain intervals and mandating synthetic specifications, concentrating volume in premium API SP and ILSAC GF-6 certified tiers. ANVISA's updated chemical registry extends reformulation timelines for new additive packages.
- Transmission Fluid:Specialized ATF and CVT formulations incorporate friction modifiers and oxidation inhibitors. Automatic gearbox penetration in southeastern Brazil's premium passenger segment is accelerating demand for OEM-specific fill specifications. ANVISA's disclosure thresholds for friction modifier chemistries are tightening qualification requirements.
- Gear Oil:Hypoid gear lubricants with extreme-pressure additives serve differential and transmission applications. Heavy machinery clusters in Minas Gerais industrial corridors generate concentrated demand for SAE 80W-90 and 85W-140 grades.
- Brake Fluid:Glycol-ether and silicone-based formulations meet DOT 3, DOT 4, and DOT 5.1 specifications. Replacement frequency in Brazil's tropical humidity conditions sustains steady aftermarket volume through retail and workshop channels.
Leading the category by volume: Engine Oil. Growing fastest: Transmission Fluid.
End User:
Procurement centralization divides end users into fragmented retail-driven segments versus concentrated direct-contract accounts with diverging price elasticity.
- Passenger Cars:Individual owners purchase through posto networks and independent workshops. Synthetic penetration lags fleet adoption due to price sensitivity and irregular maintenance patterns in Brazil's used-vehicle majority market.
- Commercial Vehicles:Owner-operators and small fleets balance cost against OEM warranty requirements. Heavy-duty diesel formulations dominate with API CK-4 and FA-4 specifications for newer engine platforms.
- Two-Wheelers:Motorcycle lubricant demand concentrates in urban delivery and commuter segments. JASO MA and MA2 certification requirements for wet clutch compatibility constrain formulation flexibility.
- Fleet Operators:Centralized procurement functions in São Paulo logistics corridors are displacing traditional wholesale intermediaries. Direct supplier contracts bundle fluid analysis, predictive maintenance services, and extended drain interval guarantees.
Fleet Operators capture margin concentration through service bundling. Passenger Cars retain volume dominance.
Application:
Fuel-lubricant compatibility standards from Brazil's national petroleum regulator fragment formulation requirements across engine types.
- Petrol Engines:Ethanol-blended gasoline compatibility mandates specialized corrosion inhibitor packages. Flex-fuel engine protection requirements drive additive reformulation for fuel dilution resistance.
- Diesel Engines:Heavy-duty formulations incorporate soot dispersants and TBN retention additives. Petrobras-affiliated refineries anchor supply concentration in this high-volume segment.
- Heavy-Duty Applications:Off-road machinery and agricultural equipment operate under severe load and contamination conditions. Hydraulic fluid and gear oil demand clusters in Minas Gerais mining and agribusiness corridors.
- Marine Applications:Coastal and inland waterway operations require specialized corrosion protection and biodegradability compliance. Regulatory frameworks for aquatic toxicity are emerging under ANVISA environmental assessments.
Diesel Engines lead absolute volume. Heavy-Duty Applications expand most quickly outside core southeastern states.
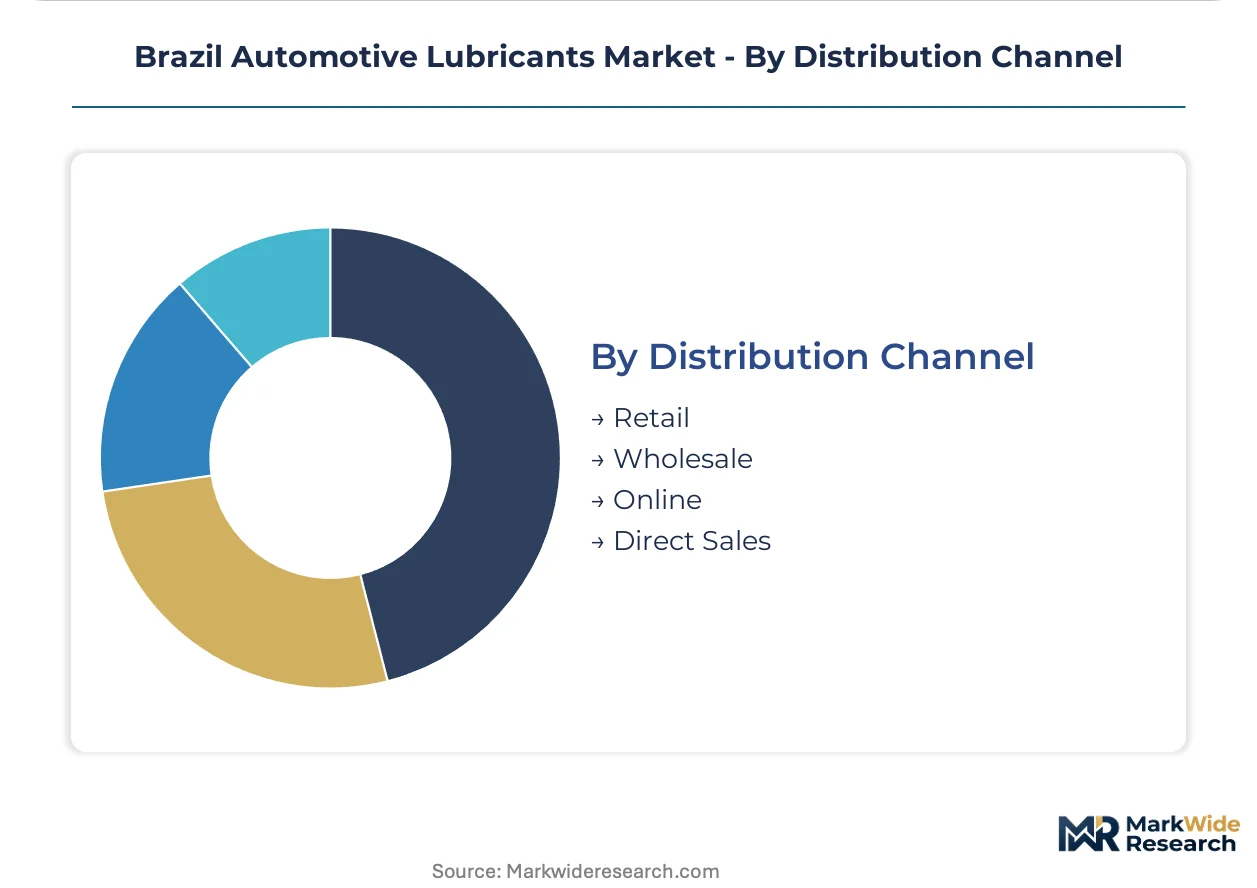
Distribution Channel:
Channel selection determines margin capture and technical service intensity, with direct sales enabling fluid analysis bundling that retail cannot replicate.
- Retail:Posto networks and auto parts chains serve fragmented individual owners. Price transparency and promotion sensitivity compress margins in mineral oil tiers.
- Wholesale:Traditional distributors face volume erosion as fleet procurement centralizes. Remaining relevance concentrates in rural and secondary city coverage gaps.
- Online:E-commerce penetration accelerates in premium synthetic tiers where specification clarity reduces purchase risk. Logistics costs limit bulk fluid viability.
- Direct Sales:Manufacturer-to-fleet contracts integrate technical support, oil analysis programs, and waste oil collection. São Paulo refrigerated transport and last-mile delivery segments show highest adoption.
Direct Sales climbs the fastest. Retail retains volume leadership through posto network density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrobras-operated refineries in the São Paulo industrial corridor anchor Brazil's base oil supply infrastructure. Captive feedstock access concentrates blending capacity in southeastern states. State-level regulatory variations and industrial clustering patterns fragment demand concentration across five key sub-regions.
São Paulo
São Paulo state's logistics corridor generates concentrated fleet operator demand for synthetic diesel formulations. ANVISA's chemical registry updates extend additive qualification timelines for lubricant suppliers headquartered in the metropolitan region. The ABC industrial belt hosts Petrobras-affiliated testing laboratories that enforce proprietary performance benchmarks shaping national formulation standards.
Minas Gerais
Heavy machinery clusters in Minas Gerais mining and agribusiness corridors drive specialized hydraulic and gear lubricant demand. The state's environmental regulator monitors used oil collection compliance under emerging circular economy frameworks. Belo Horizonte's industrial periphery presents underpenetrated demand for off-road equipment fluids outside the core southeastern manufacturing belt.
Rio de Janeiro
Rio de Janeiro's port infrastructure handles imported additive packages and base oil feedstocks for southeastern blenders. ANVISA's toxicological disclosure requirements delay customs clearance for chemical substances entering through the state's maritime terminals. The Campos Basin offshore operations sustain marine lubricant demand with specialized corrosion protection specifications.
Rio Grande do Sul
Rio Grande do Sul's automotive manufacturing footprint sustains OEM fill lubricant demand for passenger vehicle production lines. The state's agricultural machinery base generates seasonal demand spikes for hydraulic fluids during planting and harvest cycles. Porto Alegre's distribution networks extend coverage into southern Mercosur border regions.
Paraná
Paraná's diversified industrial base spans food processing equipment and metalworking machinery with distinct lubricant viscosity requirements. The state's logistics sector connects São Paulo supply corridors to southern export routes through Curitiba's freight terminals. Refrigerated transport fleets operating the BR-376 corridor are adopting compressed drain interval programs.
Brazil Automotive Lubricants Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue service-bundled contracting models with fleet operators. Market structure consolidates around integrated petrochemical complexes with captive feedstock access, while independent blenders compete through specialized formulation niches. Three archetypes dominate: state-affiliated refiners with vertical supply control, multinational majors with retail channel density, and regional specialists with direct technical service capabilities. Competitive moves center on direct fleet contracting displacement of wholesale intermediaries and synthetic formulation portfolio upgrades.
Within the multinational tier, Shell Brazil and ExxonMobil Corporation exemplify divergent positioning strategies. Shell Brazil leverages retail channel control spanning posto networks across southeastern states. ExxonMobil Corporation differentiates through synthetic product specialization targeting fleet operator contracts. Petrobras Lubrificantes anchors the state-affiliated archetype with captive feedstock access at integrated refining complexes.
| Leading Market Players |
|---|
| PETRONAS Lubricants International |
| TotalEnergies |
| ExxonMobil Corporation |
| Shell Brazil |
| Chevron Corporation |
| Iconic Lubrificantes |
| Royal Dutch Shell Plc |
| Petrobras Lubrificantes |
| Petrobras |
| Others |
Value Chain & Pricing Dynamics
Synthetic-mineral formulation divergence splits Brazil's lubricant market into warranty-backed premium tiers and commodity mineral segments, with this bifurcation manifesting in divergent procurement models and supply chain configurations across São Paulo's logistics corridor. Fleet operators with centralized technical specifications capture pricing power through direct supplier negotiations, while fragmented posto retail channels absorb margin compression from base oil supply concentration at Petrobras-affiliated refineries.
Pricing Analysis
Warranty-backed service bundling separates fleet-direct contracts from unbundled retail transactions, with synthetic formulations commanding premium positioning through fluid analysis programs and extended drain interval guarantees. Price differentiation rests on API certification tier and volume scale, with API SP and ILSAC GF-6 certified products capturing margin premiums over legacy SN-tier mineral oils. Cost compression in mineral formulations is intensifying as captive feedstock access at integrated refineries limits independent blender participation. Owner-operators and small commercial fleets exhibit highest price sensitivity, while refrigerated transport fleets with predictive maintenance mandates show lowest elasticity.
Supply Chain Analysis
Formulation chemist scarcity in tropical-condition additive balancing concentrates technical expertise at São Paulo-based Petrobras-affiliated laboratories, constraining independent R&D capacity. Base oil feedstock draws from domestic refinery output and imported Group III+ supplies, while additive packages hinge on established ANVISA registration capabilities. Single-source vulnerability runs through Petrobras-operated refining complexes that anchor southeastern blending capacity. Distribution runs through manufacturer-direct fleet contracts displacing traditional wholesale intermediaries, with posto networks retaining residual retail volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Base oil supply concentration at Petrobras-affiliated refineries props pricing power for integrated producers, constraining independent blender margin recovery and sustaining premium tier premiums through qualified feedstock access.
For Market Incumbents: Extend direct fleet contracting models beyond São Paulo's refrigerated transport segment into last-mile delivery and agribusiness logistics corridors. Anchor defensive positioning through backward integration into used oil collection and re-refining infrastructure under emerging circular economy frameworks. Deepen synthetic formulation portfolios to capture compressed drain interval mandates from centralized procurement functions. For New Entrants and Emerging Players: ANVISA's updated chemical substance registry in Brazil opens a window for specialized additive suppliers with established toxicological registration capabilities to bypass incumbent reformulation bottlenecks. Target underpenetrated hydraulic and gear lubricant demand in Minas Gerais mining clusters outside the core southeastern manufacturing belt. Pursue technical service bundling with fluid analysis programs as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists possessing direct fleet technical service capabilities given procurement centralization tailwinds across Brazilian logistics corridors. Long-term viability frames around five-to-ten year synthetic penetration trajectories in commercial vehicle segments. Monitor ANVISA registration timeline compression as the inflection signal for additive sourcing strategy disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Fleet Contracting Expansion | Captures margin through fluid analysis bundling with São Paulo logistics operators. |
| Synthetic Formulation Portfolio Upgrade | Aligns product mix with API SP and ILSAC GF-6 certification mandates from fleet procurement. |
| Used Oil Re-refining Infrastructure | Creates circular economy compliance advantage under Minas Gerais environmental frameworks. |
| Additive Package Registration Investment | Accelerates ANVISA qualification timelines for cleaner additive chemistries. |
| Technical Service Center Expansion | Extends predictive maintenance capabilities to underpenetrated agribusiness corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fleet procurement directors, lubricant blending plant managers, ANVISA regulatory affairs specialists, and aftermarket distribution channel partners. Secondary validation drew from ANVISA chemical registry submissions, Petrobras operational disclosures, and Brazilian petroleum regulator fuel-lubricant compatibility standards. Bottom-up volume modeling triangulated against top-down macroeconomic drivers across the analysis window.
Data-stream reconciliation combined production capacity assessments with end-use demand segmentation across product type, end user, application, and distribution channel dimensions. CAGRs were derived through regression analysis of historical volume trajectories and elasticity-adjusted projection inputs. Forecast inputs incorporated ethanol-blended gasoline engine penetration rates, automatic transmission adoption curves in premium passenger segments, and fleet procurement centralization velocity across southeastern states.
Caveats apply where ANVISA registration timeline extensions or base oil supply disruptions at Petrobras-affiliated refineries could materially shift the outlook. Forecasts reflect assumptions around synthetic formulation adoption elasticity and fleet operator contract renewal rates. Material deviation in chemical substance approval cycles or flex-fuel engine protection standard revisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Global Grease Cartridges Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Qatar Automotive Lubricants Market
Lubricants
Singapore Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Industrial Gear Oil Market
Lubricants
Spain Automotive Engine Oils Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
US Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Sri Lanka Lubricants Market
Lubricants
Israel Lubricants Market
Lubricants
Heavy Equipment Lubricants Market
Lubricants
Global Mineral Oil Market