
 Industrial Hooters Market | 2026-2036
Industrial Hooters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hooters Market Foresight
A widening capability gap between integrated manufacturers and component assemblers is rotating competitive dynamics across the Industrial Hooters Market. Federal Signal Corporation leverages captive supply of explosion-proof housings to sustain premium positioning in North American petrochemical corridors. Honeywell International Inc. anchors its portfolio through deep channel control over fire and gas detection distribution networks. Moflash Signalling Ltd competes from a specialized base in marine and heavy-industrial audible warning systems.
Industrial hooters constitute electromechanical audible signaling devices engineered to deliver sound pressure levels typically spanning 100 to 130 decibels, constructed from die-cast aluminum or reinforced thermoplastic housings with internal diaphragm or horn-driver mechanisms. These devices serve critical safety functions across hazardous environments, initiating emergency alerts, shift transitions, and process fault notifications in facilities where visual signaling proves inadequate. Electric technology dominates installed volumes due to grid reliability and precise activation control, though pneumatic variants retain structural share in offshore platforms and volatile atmosphere zones where spark ignition risks persist. Manufacturing plants represent the most mature end-user segment with replacement-driven demand, while chemical processing applications generate the fastest growth trajectory as facilities retrofit legacy steam whistles with addressable electronic hooter networks.
OSHA mandates enforce permissible exposure limits and workplace alarm system standards that directly shape product decibel ratings and synchronization protocols across United States industrial sites. EPA regulations on noise pollution constrain operational parameters for facilities near residential boundaries, pushing demand toward directional horn designs with attenuated side-lobe propagation. BIS certification requirements in India block market access for uncertified imports while elevating compliance costs for domestic manufacturers. Stakeholders must monitor evolving harmonization between regional hazardous area standards and IECEx certification frameworks to anticipate product redesign cycles and qualification timelines.
Market Dynamics
OSHA and EPA mandates in the United States are compressing decibel thresholds and tightening hazardous area certifications, forcing manufacturers to redesign housings and synchronization protocols while chemical processing facilities accelerate replacement of legacy steam whistles with addressable electronic networks.
Growth Catalysts
- Factory Modernization Programs:India's state industrial corridors are accelerating replacement cycles as BIS standards enforcement blocks uncertified imports and elevates compliance requirements for domestic installations.
- Emergency Evacuation Protocol Expansion:Chemical processing facilities are retrofitting legacy audible warning systems with networked electronic hooters capable of zone-specific activation and centralized monitoring.
- OSHA Workplace Alarm Standards:Tightened permissible exposure limits are mandating synchronized multi-point hooter deployments across United States manufacturing sites to eliminate auditory dead zones.
Market Restraints
- Aluminum Die-Cast Input Volatility:Primary aluminum price swings directly compress margin structures for housing manufacturers, particularly those without captive foundry operations or long-term supply agreements.
- Certification Timeline Friction:IECEx and ATEX qualification cycles extend 14-18 months, freezing product portfolios and delaying revenue recognition for new explosion-proof designs.
- Pneumatic System Persistence:Offshore platforms and volatile atmosphere zones retain compressed air infrastructure, limiting electric hooter penetration where spark ignition risks dominate safety protocols.
Strategic Opportunities
- IoT-Audible Convergence:Integration of hooters with facility management systems and predictive maintenance platforms opens premium pricing for addressable, diagnostic-capable devices in smart factory deployments.
- Marine Certification Gap:Specialized marine audible warning systems face limited qualified suppliers, creating white space for manufacturers with DNV-GL or Lloyd's Register approvals to capture vessel retrofit cycles.
- India State Corridor Expansion:Tamil Nadu, Gujarat, and Maharashtra industrial zones are modernizing under state-level manufacturing incentives, concentrating demand for BIS-certified hooter replacements.
Industry Challenges
- IECEx-ATEX Harmonization Complexity:Divergent testing protocols between regional hazardous area standards force redundant certification investments and fragment product qualification roadmaps.
- Legacy Steam Whistle Integration:Retrofit projects require custom mounting adaptations and pneumatic-to-electric infrastructure conversion, extending deployment timelines and elevating project engineering costs.
- Acoustic Engineering Talent Scarcity:Specialized expertise in directional horn design and side-lobe attenuation remains concentrated among a narrow supplier base, constraining R&D velocity for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hooters Market |
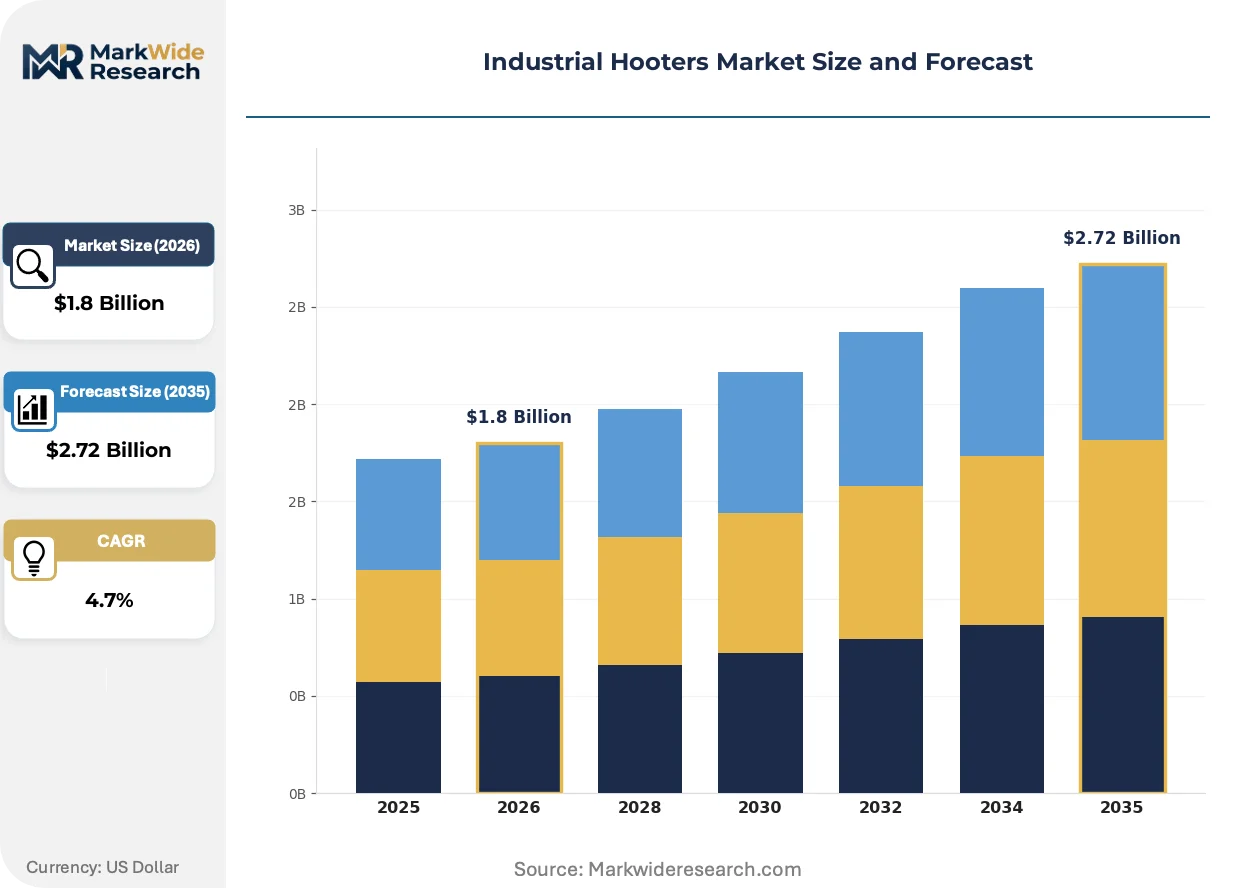
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Axial Fans, Centrifugal Fans, Exhaust Fans, Blower Units Application: Ventilation, Cooling, Heating, Air Circulation End User: Manufacturing Plants, Warehouses, Power Generation, Chemical Processing Technology: Electric, Hydraulic, Pneumatic, Solar |
| Companies Covered | Moflash Signalling Ltd, Klaxon Signalling Solutions, Federal Signal Corporation, Rockwell Automation, Honeywell International Inc., NHP Electrical Engineering Products, Paramount Electronics Pvt. Ltd., Alan Electronic Systems Pvt. Ltd., Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hooters Market Shifts & Advancements
Digital addressability and predictive diagnostics are transforming electromechanical audible signaling from standalone safety hardware into networked facility infrastructure, compressing replacement cycles and elevating specification requirements.
Addressable electronic hooter networks are supplanting hardwired, single-point steam whistles and electromechanical sirens in chemical processing and heavy manufacturing facilities. Site engineers are specifying IP-enabled devices with zone-selective activation and centralized monitoring dashboards. This shift is compressing the installed base of legacy pneumatic systems while opening premium pricing tiers for diagnostic-capable hardware.
EPA noise pollution enforcement near residential boundaries is mandating directional horn designs with attenuated side-lobe propagation for facilities in the United States. Industrial sites within 500 meters of populated zones must now demonstrate compliance with octave-band analysis and documented sound mapping. Manufacturers are responding with parametric horn geometries and active noise cancellation prototypes for the most constrained installations.
Procurement centralization through integrated facility management contractors is displacing direct OEM relationships for hooter specification and installation. Large manufacturing conglomerates in India are consolidating safety system procurement under single-source fire and gas detection integrators. This channel compression elevates the importance of Honeywell and Federal Signal distribution networks while marginalizing smaller component assemblers lacking certified integration partnerships.
Industrial Hooters Market Segmentation
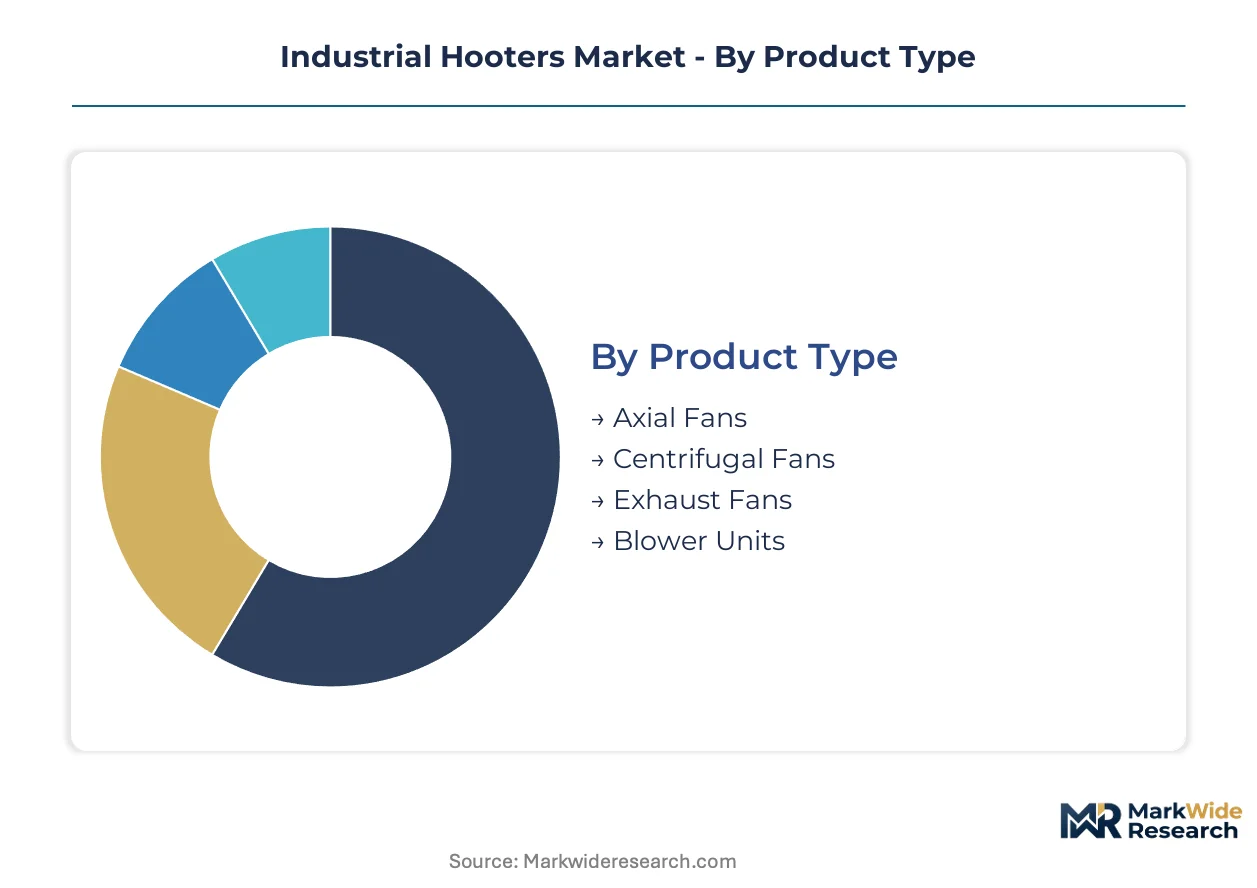
Industrial hooter segmentation reflects divergent certification requirements across hazardous area classifications. Product design, activation technology, and end-use environment each impose distinct regulatory burdens that reshape supplier economics.
Product Type:
Regulatory differentiation separates explosion-proof housings from standard industrial enclosures through IECEx and ATEX qualification tiers.
- Axial Fans:These units move air parallel to the shaft axis using propeller-style blades mounted in cylindrical housings. Chemical processing facilities in Gujarat and Maharashtra specify axial designs for fume extraction zones where BIS-certified spark-resistant construction is mandatory.
- Centrifugal Fans:Radial blade configurations generate higher static pressure for ducted distribution systems. Power generation utilities across Tamil Nadu industrial corridors deploy centrifugal hooters for boiler room ventilation where OSHA-mandated redundancy requires dual-fan architectures.
- Exhaust Fans:Wall-mounted or roof-vented configurations for direct atmosphere discharge.
- Blower Units:Positive-pressure systems for forced-air distribution across large manufacturing bays.
Axial fans handle the majority of throughput; centrifugal fans are the fastest mover on share.
Application:
Cost tier stratification separates life-safety ventilation from comfort cooling on specification intensity.
- Ventilation:Continuous or demand-controlled air exchange systems for contaminant dilution and worker protection. EPA enforcement near residential boundaries in the United States is mandating directional exhaust configurations with attenuated noise propagation for facilities within 500 meters of populated zones.
- Cooling:Process heat rejection and equipment thermal management applications. Data center operators in India state industrial corridors specify redundant cooling hooters with BIS-mandated electrical isolation for critical infrastructure protection.
- Heating:Combustion air supply and space warming in cold-climate manufacturing.
- Air Circulation:General environmental uniformity without temperature or contaminant control targets.
Ventilation commands premium pricing; cooling is expanding most quickly on specification volume.
End User:
Customer type determines procurement channel and integration complexity across facility management structures.
- Manufacturing Plants:Assembly, fabrication, and discrete production facilities with shift-based operations. Automotive and electronics manufacturers in Tamil Nadu consolidate safety system procurement under single-source fire and gas detection integrators, elevating channel control for certified suppliers.
- Chemical Processing:Petrochemical, specialty chemical, and pharmaceutical synthesis operations. OSHA workplace alarm standards mandate synchronized multi-point hooter deployments to eliminate auditory dead zones in United States chemical corridors.
- Warehouses:Storage and distribution facilities with intermittent occupancy patterns.
- Power Generation:Thermal, renewable, and grid infrastructure with continuous operational profiles.
Manufacturing plants absorb the largest installed base; chemical processing is climbing the fastest on retrofit demand.
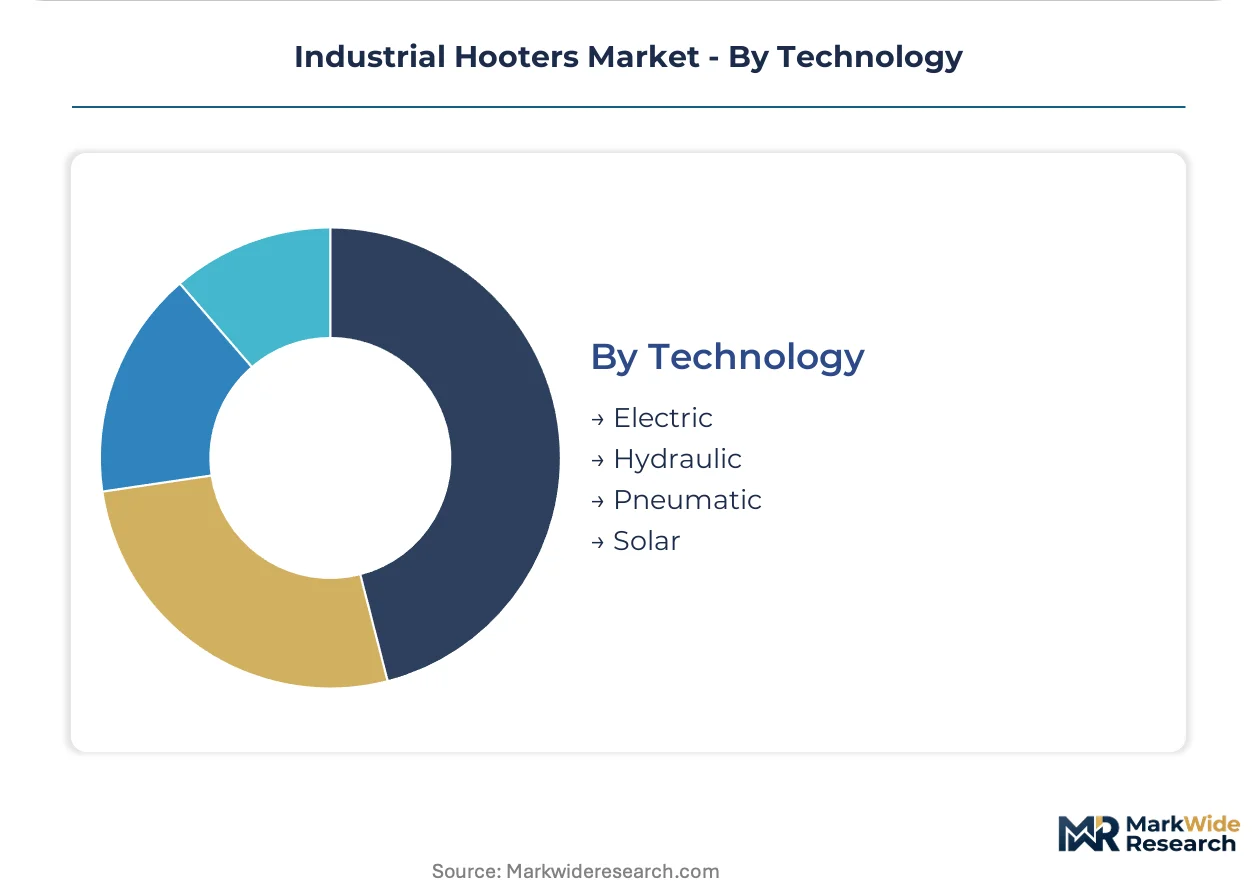
Technology:
Supply concentration in electric motor manufacturing contrasts with pneumatic infrastructure persistence in volatile atmospheres.
- Electric:Grid-powered electromechanical activation with precise control and diagnostic integration. Honeywell and Federal Signal distribution networks dominate electric hooter specification through fire and gas detection channel control in North American petrochemical corridors.
- Pneumatic:Compressed air-driven systems for explosion-risk environments where spark ignition is prohibited. Offshore platforms in volatile atmosphere zones retain pneumatic infrastructure, limiting electric penetration where ignition safety protocols dominate.
- Hydraulic:Fluid-power activation for heavy-industrial applications with existing hydraulic infrastructure.
- Solar:Photovoltaic-powered standalone units for remote or grid-unreliable installations.
Electric technology commands dominant share; pneumatic retains structural position in hazardous zone applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in United States petrochemical corridors where OSHA mandates enforce synchronized multi-point deployments, while Indian state industrial corridors compete on volume through BIS-certified replacement cycles at compressed margins.
United States
Chemical processing facilities along the Gulf Coast are retrofitting legacy steam whistles with addressable electronic hooter networks. OSHA workplace alarm standards mandate synchronized deployments to eliminate auditory dead zones. Houston and Port Arthur industrial zones drive specification intensity for explosion-proof housings with IECEx qualification.
Germany
Automotive and heavy machinery manufacturers specify integrated fire and gas detection systems with audible signaling components. REACH compliance and ATEX directives shape hazardous area certification requirements for suppliers. The Ruhr industrial region and Baden-Württemberg manufacturing belt concentrate demand for diagnostic-capable devices.
India
State industrial corridors in Tamil Nadu, Gujarat, and Maharashtra are modernizing under manufacturing incentive programs. BIS standards enforcement blocks uncertified imports and elevates compliance costs for domestic installations. Mundra, Hazira, and Sriperumbudur industrial clusters accelerate replacement cycles for legacy audible warning systems.
China
Chemical and petrochemical expansion along the eastern seaboard generates demand for hazardous area audible signaling. GB standards and MIIT industrial safety protocols govern product certification and facility compliance. The Yangtze River Delta and Shandong Peninsula petrochemical bases specify explosion-proof electronic hooters for new construction.
Saudi Arabia
Offshore platforms and volatile atmosphere processing facilities retain pneumatic infrastructure for spark-risk environments. The country's national industrial safety regulator mandates hazardous area certifications aligned with IECEx frameworks. The Eastern Province industrial cities of Jubail and Yanbu concentrate petrochemical facility construction and hooter deployment.
Industrial Hooters Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated safety system manufacturers commanding premium positioning through distribution network control while component specialists compete on marine and heavy-industrial certifications. The vendor base organizes into three tiers: multinational conglomerates with captive hazardous area expertise, mid-scale specialists with vertical integration into explosion-proof housings, and regional assemblers dependent on imported certifications. Dominant competitive moves include strategic partnerships with fire and gas detection integrators and portfolio diversification into IoT-addressable device platforms.
Within the multinational tier, Federal Signal Corporation and Honeywell International Inc. exemplify archetypes with deep channel control over North American petrochemical distribution. Moflash Signalling Ltd occupies a specialized position among marine and heavy-industrial audible warning specialists. These three anchors represent distinct competitive vectors: captive supply integration, distribution network dominance, and certification-specialized segmentation.
| Leading Market Players |
|---|
| Moflash Signalling Ltd |
| Klaxon Signalling Solutions |
| Federal Signal Corporation |
| Rockwell Automation |
| Honeywell International Inc. |
| NHP Electrical Engineering Products |
| Paramount Electronics Pvt. Ltd. |
| Alan Electronic Systems Pvt. Ltd. |
| Eaton |
| Others |
Supply & Pricing Matrix
Foundry utilization rates above eighty percent at Chinese and Indian die-cast aluminum suppliers compress margin buffers for housing manufacturers lacking captive melting capacity or long-term offtake agreements. This concentration of primary metal processing in Asia anchors price floors for explosion-proof enclosures while elevating working capital requirements for Western assemblers dependent on spot-market aluminum purchases.
Pricing Analysis
The customization-premium spread separates configured-to-order explosion-proof housings from standard industrial enclosures by three-to-five multiples. Project-based pricing dominates large chemical processing retrofits where pneumatic-to-electric infrastructure conversion requires engineering services bundling. Certification grade—specifically IECEx versus standard UL listings—drives the steepest price differentiation. Price erosion runs through standard industrial hooters as Indian domestic manufacturers absorb BIS compliance costs to displace uncertified imports. State industrial corridor procurement offices in Tamil Nadu and Gujarat exhibit highest price sensitivity; Gulf Coast petrochemical operators show lowest sensitivity given OSHA-mandated safety specifications.
Supply Chain Analysis
Strategic stockpiling of aluminum ingot and copper magnet wire characterizes procurement behavior among tier-one hooter manufacturers facing fourteen-to-eighteen-month IECEx qualification timelines. Supply concentration rests on China for die-cast aluminum housings, India for wound copper components, and Germany for precision diaphragm assemblies. Raw material dependencies include primary aluminum, neodymium for horn-driver magnets, and thermoplastic resins for non-metallic enclosures. Single-source vulnerability concentrates in explosion-proof casting foundries qualified to ATEX standards. Distribution runs through fire and gas detection integrators in North American petrochemical corridors and state-level electrical distributors in Indian industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Indian manufacturing conglomerates consolidate safety system procurement under single-source fire and gas detection integrators, compressing channel access for component assemblers lacking certified partnerships.
For Market Incumbents: Consolidate distribution network control through exclusive integration partnerships with facility management contractors serving Gulf Coast and Gujarat chemical corridors. Deepen captive supply of explosion-proof housings to defend margin position against Asian die-cast competitors. Prioritize certification investment in marine-grade DNV-GL approvals to capture vessel retrofit cycles where qualified supplier scarcity persists. For New Entrants and Emerging Players: Differentiate on IoT-addressable diagnostics for smart factory deployments where Honeywell and Federal Signal distribution lock-in remains incomplete. Target marine audible warning systems as the most penetrable segment given limited DNV-GL and Lloyd's Register qualified suppliers. Pursue direct specification relationships with Tamil Nadu and Maharashtra state industrial corridor engineering departments as a go-to-market angle bypassing consolidated procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated safety system manufacturers with fire and gas detection service contracts anchoring hooter replacement cycles. Long-term viability favors acquirers of mid-scale specialists with backward integration into explosion-proof housing production and existing IECEx qualification portfolios. The signal to watch is BIS enforcement intensity across Indian state corridors as an inflection indicator for certified domestic manufacturer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Explosion-Proof Housing | Captive foundry capacity insulates margin structures from aluminum price volatility and IECEx qualification delays. |
| Marine Certification Acquisition | DNV-GL or Lloyd's Register approval opens vessel retrofit demand with limited qualified competitor presence. |
| IoT-Addressable Platform Development | Diagnostic-capable hooters command premium pricing in smart factory deployments with predictive maintenance integration. |
| State Corridor Direct Specification | Engineering relationships in Tamil Nadu and Maharashtra bypass consolidated procurement channel compression. |
| Pneumatic-to-Electric Retrofit Service Bundling | Custom mounting adaptation and infrastructure conversion services extend project value capture in chemical processing facilities. |
Research Methodology
A spread of perspectives from plant engineers, fire and gas detection integrators, procurement leads at chemical processing facilities, and aftermarket service heads converged on the working assumptions underlying demand segmentation. Primary fieldwork combined structured interviews with secondary validation through OSHA enforcement records, EPA noise pollution compliance filings, BIS certification databases, and customs trade data for aluminum die-cast imports. Bottom-up installation counts across Indian state industrial corridors and top-down chemical processing capital expenditure patterns were triangulated to anchor volume estimates.
Segmentation dimensions modeled include product type across explosion-proof and standard industrial enclosures, activation technology spanning electric and pneumatic systems, end-use environment across chemical processing and manufacturing plants, and geographic regulatory clusters reflecting OSHA, ATEX, and BIS compliance frameworks. CAGRs were derived from replacement cycle analysis and facility modernization program timelines. Forecast inputs incorporated aluminum price trajectory assumptions and IECEx-ATEX harmonization progress across the analysis window.
The analysis sits within stated boundaries; outcomes outside sustained BIS enforcement intensity, stable primary aluminum supply conditions, or continued OSHA workplace alarm standard tightening would require recalibration. Forecasts reflect assumptions regarding chemical processing retrofit momentum and Indian state corridor manufacturing incentive continuity. Revision becomes warranted when aluminum price volatility crosses thresholds that compress housing manufacturer margins below viable certification investment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Three Proofing Rugged Tablet Market
Others
Europe Video Encoder Market
Others
Durian Market
Others
Lychee Market
Others
North America Printed Signage Market
Others
Trusted Platform Module (TPM) Market
Others
Asia-Pacific Adtech Market
Others
Cloud Broadcasting Solutions Market
Others
China Online Gambling Market
Others
Aboveground Storage Tanks Market
Others
Depth Gauge Market
Others
Rotary Dial Machine Market
Others
Digital LUX Meter Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Electric Chainsaw Market
Others
Asia-Pacific Telecom Transformers Market