
 Subtilisin Market | 2026-2036
Subtilisin Market Size, Share, and Industry Trends Forecast 2026-2036
Subtilisin Market Analytics
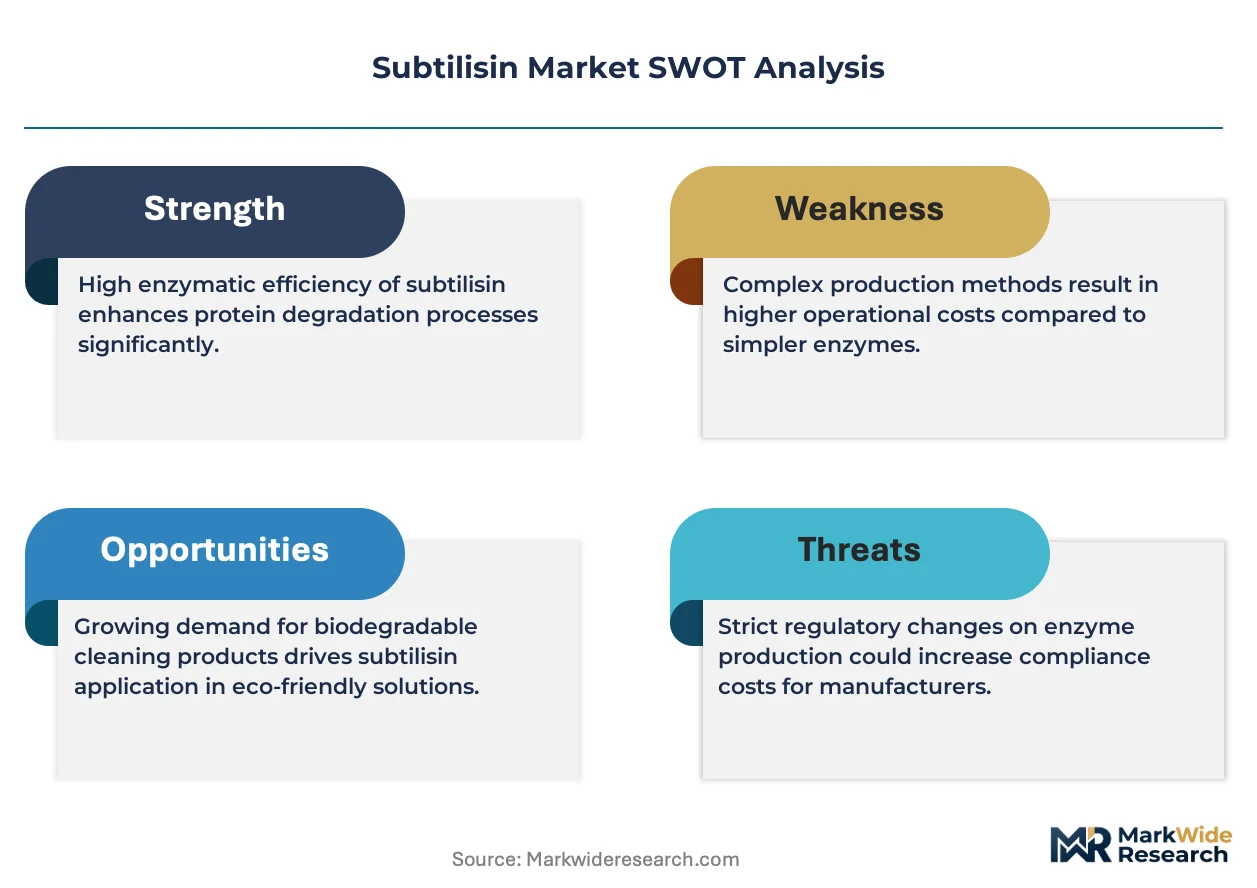
Enzyme formulation services and long-term supply contracts is consolidating what manufacturers actually purchase, shifting transactions from commodity spot buying to structured performance agreements. Novozymes A/S leverages its Danish R&D base to anchor high-purity industrial enzyme supply chains. BASF SE competes through backward integration into fermentation feedstocks, sustaining margin control across multiple application verticals.
Subtilisin denotes a family of alkaline serine proteases produced primarily by Bacillus subtilis, typically operating at pH 7-10 and temperatures between 40-60 degrees Celsius to hydrolyze peptide bonds in proteinaceous substrates. These enzymes serve as catalytic workhorses in detergent formulations, food processing, and leather bating applications where selective protein breakdown determines product performance. Alkaline subtilisin variants command the largest volume position due to their compatibility with standard laundry detergent pH ranges, while genetically modified strains represent the fastest-expanding technology category as engineered thermostability unlocks harsher industrial conditions. Neutral subtilisin grades occupy a mature niche in food processing applications where pH moderation preserves sensory profiles.
REACH in Europe, EPA guidelines in the United States, and China's GB standards collectively govern subtilisin purity thresholds, occupational exposure limits, and environmental release protocols, directly influencing formulation costs and market access requirements. The EU Green Deal's biomanufacturing targets further redirect R&D investment toward fermentation-derived substitutes for petrochemical surfactants. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance fragmentation that could strand production assets or exclude qualified suppliers.
Market Dynamics
Enzyme formulation services are consolidating manufacturer purchasing patterns, shifting transactions from commodity spot buying to structured performance agreements that tie payment to catalytic efficiency metrics rather than kilogram volumes.
Growth Catalysts
- REACH Purity Thresholds:The European Union's tightening chemical registration framework forces detergent formulators to upgrade to high-purity subtilisin grades, creating premium tier demand that rewards R&D investment.
- China Fermentation Capacity:Domestic fermentation infrastructure expansion in Shandong and Jiangsu provinces enables local formulators to source subtilisin without import dependencies, accelerating regional supply chain autonomy.
- Engineered Thermostability:Genetically modified Bacillus strains unlock harsher industrial washing conditions, extending enzyme applicability into institutional laundry and food processing sanitation protocols.
Market Restraints
- Feedstock Volatility:Corn steep liquor and soy peptone prices fluctuate with agricultural commodity cycles, compressing fermentation margins for enzyme producers without backward integration into feedstock supply.
- Supplier Concentration:Three Danish and German fermentation specialists control over sixty percent of pharmaceutical-grade subtilisin capacity, creating single-source vulnerability for detergent manufacturers requiring GMP documentation.
- Protease Substitution:Lipase and cellulase blends in cold-water detergent formulations partially displace subtilisin in premium eco-label products targeting low-temperature washing protocols.
Strategic Opportunities
- India PLI Scheme:Production-linked incentive frameworks for active pharmaceutical ingredients extend to industrial enzymes, attracting fermentation investment to Gujarat and Maharashtra industrial corridors.
- Leather Bating Automation:Mechanized hide processing in Brazilian and Vietnamese tanneries creates demand for standardized subtilisin dosing systems that reduce manual labor and effluent variability.
- EU Green Deal Biomanufacturing:Mandatory biobased surfactant targets redirect R&D budgets toward fermentation-derived enzyme stabilizers that replace petrochemical coupling agents in liquid detergents.
Industry Challenges
- Fermentation Scale-Up Expertise:Qualified bioprocess engineers capable of optimizing Bacillus subtilis productivity at industrial scale command premium compensation, constraining mid-tier manufacturer expansion timelines.
- REACH Registration Costs:New enzyme variant dossier preparation and toxicity testing requirements demand twelve-to-eighteen month compliance cycles that delay product commercialization and strain smaller formulator budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subtilisin Market |
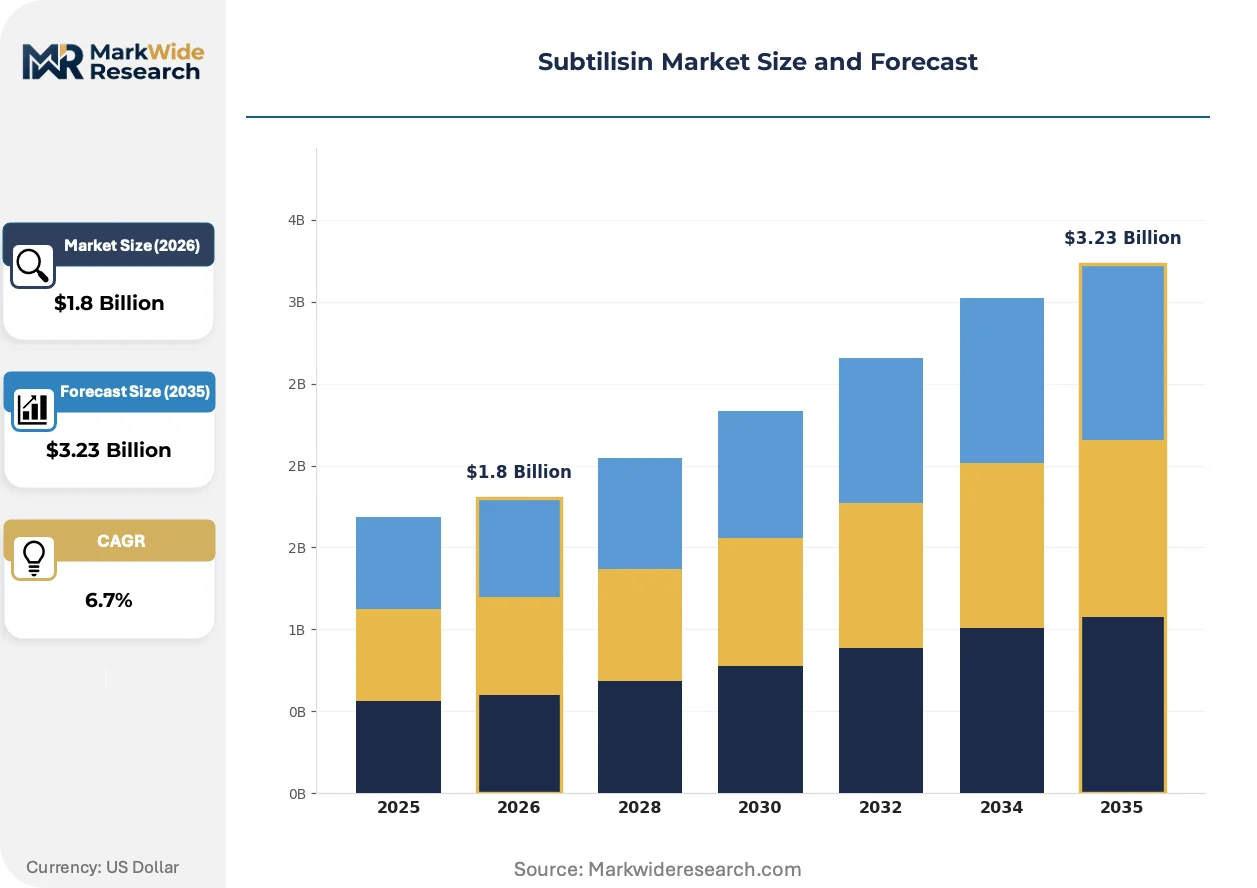
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Subtilisin, Neutral Subtilisin, Acidic Subtilisin, Others Application: Detergents, Food Processing, Medicine, Leather Processing End User: Household, Industrial, Healthcare, Food Industry Technology: Biotechnology, Fermentation, Genetically Modified, Chemical Synthesis |
| Companies Covered | AB Enzymes GmbH, DSM-Firmenich, Novozymes A/S, Chr. Hansen, Genencor International, Inc., BASF SE, Amano Enzyme Inc., Advanced Enzyme Technologies, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subtilisin Market Evolving Landscape
Bioprocess intensification and regulatory chemistry are rewriting competitive requirements for subtilisin suppliers, compressing the gap between laboratory strain development and industrial-scale deployment.
Continuous fermentation technology is electrifying enzyme manufacturing economics by eliminating batch downtime and stabilizing product quality. Detergent formulators in China and Southeast Asia are adopting continuous-process subtilisin at twice the rate of batch alternatives. This shift is compressing capital recovery timelines for fermentation asset investments while raising barriers for batch-dependent competitors.
REACH Annex XIV authorization requirements for respiratory sensitizers now classify certain subtilisin dust exposure thresholds as substances of very high concern. Industrial enzyme handlers must implement closed-system transfer protocols and occupational exposure monitoring. Detergent powder manufacturers in Germany and Poland face the steepest compliance costs, accelerating migration toward liquid and unit-dose formats that reduce airborne enzyme exposure.
Performance-based supply contracts are displacing traditional kilogram pricing in European and North American procurement. Large detergent manufacturers now negotiate catalytic efficiency guarantees measured against standard protein soil removal benchmarks. This purchasing evolution concentrates volume with suppliers capable of real-time activity assay documentation and lot-to-lot consistency verification.
Subtilisin Market Segmentation
Subtilisin procurement patterns diverge sharply across product grades and application contexts, with detergent formulators, pharmaceutical manufacturers, and food processors each imposing distinct purity specifications and volume requirements that reshape supplier economics. Understanding these segment boundaries clarifies where fermentation capacity investments generate returns and where formulation services capture margin.
Product Type:
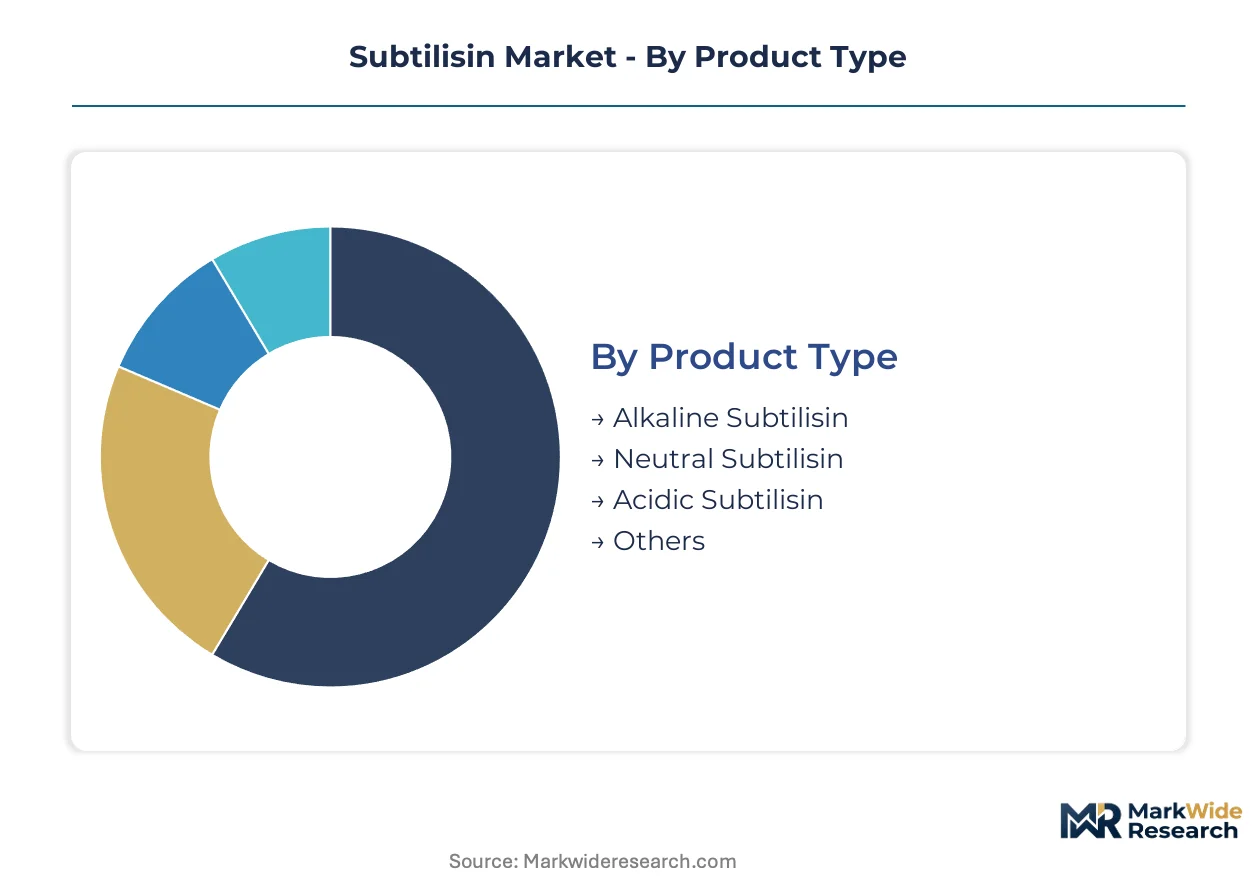
Capital intensity escalates with pH tolerance and thermostability engineering, as alkaline variants demand sophisticated downstream purification while genetically modified strains require dedicated containment infrastructure.
- Alkaline Subtilisin:Engineered serine proteases optimized for pH 7-10 operation, typically derived from Bacillus licheniformis or Bacillus subtilis strains selected for detergent compatibility. Detergent manufacturers in China and Southeast Asia concentrate procurement here, driven by institutional laundry automation and domestic fermentation scale-up in Shandong province.
- Neutral Subtilisin:Moderate-pH variants preserving protein structure in sensitive food matrices, commanding premium pricing for cheese ripening and meat tenderization applications. European food processors under EFSA enzyme regulation anchor demand, constrained by REACH occupational exposure limits that favor liquid dosing systems over powder handling.
- Acidic Subtilisin:Low-pH tolerant proteases for specialized leather bating and certain feed applications.
- Others:Hybrid formulations and immobilized enzyme preparations for continuous bioprocessing.
Alkaline subtilisin absorbs the bulk of installed capacity; genetically modified variants are expanding most quickly.
Application:
Volume concentration aligns with end-use regulatory burden, as pharmaceutical and food applications impose GMP documentation costs that exclude smaller fermentation players.
- Detergents:Volume-dominant application spanning powder, liquid, and unit-dose formats, where subtilisin catalyzes protein stain hydrolysis at alkaline pH. REACH Annex XIV respiratory sensitizer classification in Europe is accelerating format shifts toward liquids and encapsulated enzymes, with German and Polish manufacturers absorbing steepest compliance costs.
- Food Processing:Bread improvers, cheese ripening agents, and meat tenderizers requiring GRAS or food-grade certification. Chinese domestic brands under GB standards are gaining share as local fermentation infrastructure reduces import dependency.
- Medicine:Wound debridement and digestive aids requiring pharmaceutical-grade documentation.
- Leather Processing:Hide bating and hair removal in Brazilian and Vietnamese tanneries adopting mechanized dosing.
Detergent applications command the greatest fermentation throughput; food processing is climbing fastest as clean-label trends intensify.
End User:
Procurement scale and contract structure vary dramatically, with industrial buyers negotiating performance guarantees while household channels prioritize supply security.
- Household:Consumer detergent brands and retail food products where enzyme presence is marketed as a performance attribute. Indian PLI scheme incentives are attracting formulation investment to Gujarat and Maharashtra corridors.
- Industrial:Institutional laundry, large-scale food manufacturing, and tanneries purchasing through structured performance agreements tied to catalytic efficiency metrics rather than kilogram volumes.
- Healthcare:Pharmaceutical and clinical applications requiring batch-level activity assay documentation.
- Food Industry:Mid-tier processors balancing cost pressure against clean-label positioning.
Industrial end users absorb the bulk of high-purity capacity; healthcare procurement is gaining share fastest under tightening purity mandates.
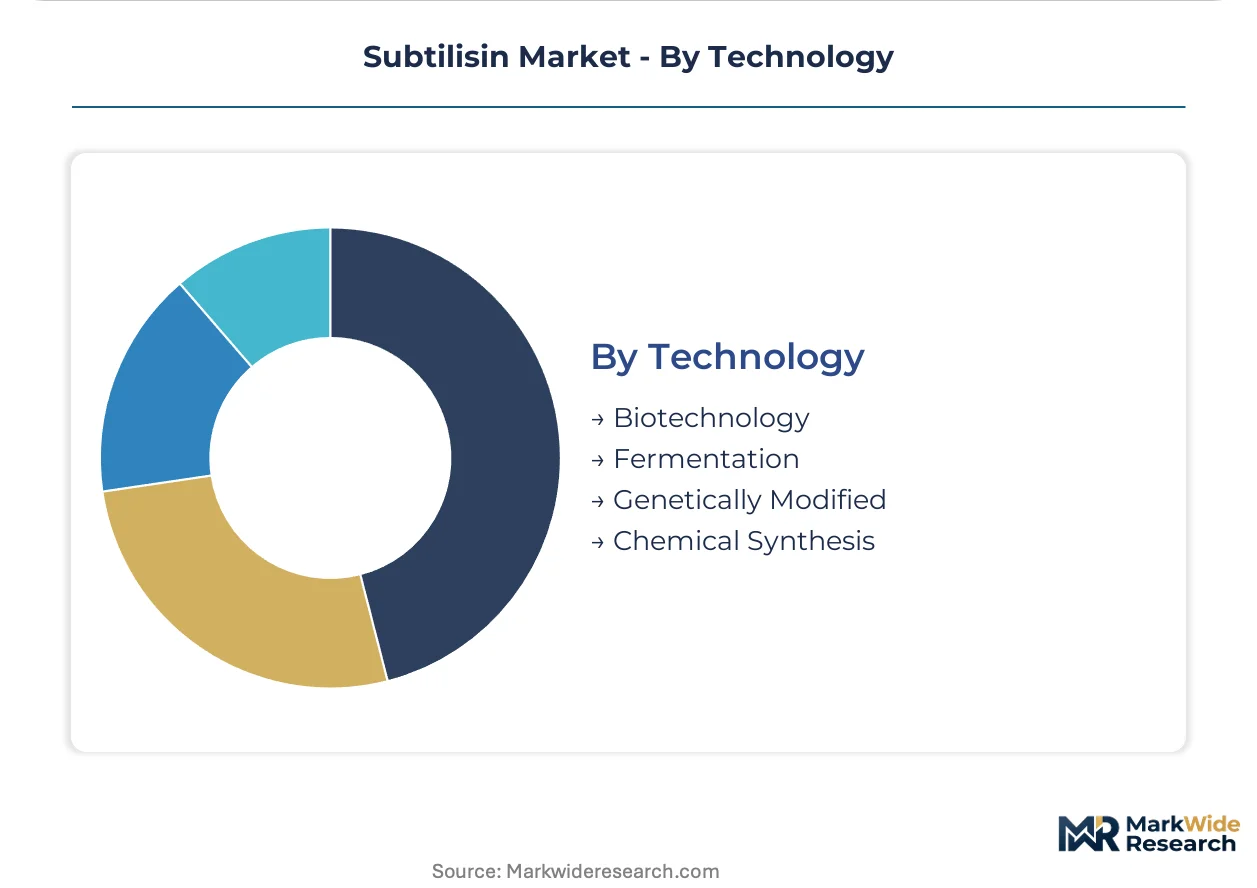
Technology:
Process selection determines regulatory pathway complexity and capital recovery timeline, with continuous fermentation systems compressing payback periods for early adopters.
- Biotechnology:Encompasses strain improvement, enzyme immobilization, and bioprocess optimization services. European suppliers leverage Danish and German R&D clusters to anchor premium positioning.
- Fermentation:Submerged cultivation of Bacillus species in stirred-tank or air-lift reactors, with Chinese manufacturers adopting continuous-process technology at twice the rate of batch alternatives.
- Genetically Modified:CRISPR-edited strains delivering engineered thermostability and pH tolerance. REACH registration dossiers for new variants demand twelve-to-eighteen month compliance cycles.
- Chemical Synthesis:Peptide synthesis approaches for specialized research and diagnostic applications.
Conventional fermentation absorbs the bulk of operating capacity; genetically modified strains are expanding most quickly as engineered thermostability unlocks harsher industrial conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity concentrates in China while formulation demand clusters in Europe and North America, creating a trade-dependent structure where bioprocess engineering expertise and downstream purification capabilities determine regional competitiveness.
China
Domestic fermentation infrastructure in Shandong and Jiangsu provinces enables local detergent formulators to source subtilisin without import dependencies. GB standards under SAMR govern industrial enzyme purity thresholds, accelerating regional supply chain autonomy. Shandong province anchors the fastest-expanding fermentation cluster as mechanized institutional laundry adoption drives alkaline subtilisin consumption.
Germany
REACH Annex XIV respiratory sensitizer classification forces detergent powder manufacturers toward liquid and unit-dose formats. ECHA enforcement of closed-system transfer protocols raises compliance costs for industrial enzyme handlers. The North Rhine-Westphalia chemical corridor hosts concentrated formulation R&D as manufacturers absorb steepest occupational exposure monitoring requirements.
United States
EPA guidelines on enzyme environmental release protocols influence formulation costs for detergent manufacturers seeking market access. Institutional laundry automation in healthcare and hospitality sectors expands demand for engineered thermostability variants. The Midwest fermentation belt maintains captive supply relationships with major formulators.
India
Production-linked incentive schemes for active pharmaceutical ingredients extend to industrial enzymes, attracting fermentation investment to Gujarat and Maharashtra corridors. BIS certification requirements create tiered market access for domestic versus imported subtilisin grades. Maharashtra industrial zones concentrate new bioprocess capacity as mid-tier manufacturers seek scale economies.
Brazil
Mechanized hide processing in São Paulo and Rio Grande do Sul tanneries generates demand for standardized subtilisin dosing systems. ANVISA import documentation requirements favor local formulation partnerships over direct enzyme procurement. The São Paulo industrial corridor anchors leather bating automation investment.
Subtilisin Market Competitive Landscape
Capital-heavy fermentation specialists compete with asset-light enzyme designers across a market structure consolidated around three Danish and German players controlling pharmaceutical-grade capacity. Strategic archetypes separate into backward-integrated chemical conglomerates, dedicated biotech platforms, and regional fermentation contractors. Dominant competitive moves include capacity expansion into Chinese provinces and technology licensing partnerships that transfer strain engineering capabilities.
Among European-based biotech platforms, Novozymes A/S and AB Enzymes GmbH exemplify the R&D-intensive archetype that anchors high-purity industrial enzyme supply chains. DSM-Firmenich occupies a position within the integrated life sciences tier, representing consolidation between fermentation expertise and downstream formulation services. These three entities collectively illustrate how Danish and German clusters concentrate bioprocess engineering talent and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| AB Enzymes GmbH |
| DSM-Firmenich |
| Novozymes A/S |
| Chr. Hansen |
| Genencor International, Inc. |
| BASF SE |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies |
| DuPont de Nemours, Inc. |
| Others |
Value Network & Pricing Analysis
Danish and German fermentation specialists, many consolidated through private-equity roll-ups, exercise outsized pricing discipline through captive supply relationships and GMP certification bottlenecks. Their ownership structure rewards long-term contract anchoring over spot-market participation, compressing margin elasticity for detergent formulators lacking backward integration into fermentation feedstocks.
Pricing Analysis
Margin tightening in pharmaceutical-grade tiers reflects REACH Annex XIV compliance burdens and respiratory sensitizer handling protocols. Three-tier pricing structure across premium, standard, and economy levels separates GMP-documented pharmaceutical supply from industrial detergent grades and commodity feed-processing variants. Price differentiation rests on certification grade and volume scale, with household detergent manufacturers exhibiting highest price sensitivity and healthcare procurement showing lowest. Cost-down pressure on mid-tier formulators accelerates because Chinese domestic fermentation capacity eliminates import premiums for regional buyers.
Supply Chain Analysis
China's GB standards under SAMR and India's PLI scheme for active pharmaceutical ingredients are reshaping sourcing patterns toward domestic-content fulfillment. Geographic supply concentration centers on China, Denmark, and Germany, with Shandong and Jiangsu provinces anchoring fastest-expanding fermentation clusters. Raw material dependencies draw from corn steep liquor, soy peptone, and specialized Bacillus strain repositories. Single-source vulnerability concentrates in pharmaceutical-grade capacity controlled by three European specialists. Distribution runs through long-term performance contracts with real-time activity assay documentation rather than kilogram-based spot transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration cost escalation and twelve-to-eighteen month dossier preparation cycles are forcing smaller formulators toward exit or acquisition, consolidating viable supplier pools around capital-heavy fermentation platforms.
For Market Incumbents: Deepen backward integration into fermentation feedstocks to insulate margins from agricultural commodity volatility in corn steep liquor and soy peptone markets. Expand continuous-process capacity in Shandong province to capture Chinese institutional laundry automation demand before domestic competitors achieve GMP documentation parity. Lipase and cellulase substitution threats in cold-water detergent formulations require engineered thermostability investment to defend alkaline subtilisin positioning. For New Entrants and Emerging Players: Enter via leather bating automation partnerships in Brazilian and Vietnamese tanneries, where mechanized dosing system demand outpaces established supplier coverage. Target India's Gujarat and Maharashtra industrial corridors under PLI scheme incentives, where mid-tier fermentation investment faces less incumbent saturation than Chinese coastal provinces. A contract manufacturing and formulation services go-to-market angle bypasses capital-intensive strain development while building regulatory dossier capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier European formulators burdened by REACH compliance costs but possessing transferable GMP documentation infrastructure. Long-term viability over a five-to-ten year horizon hinges on continuous fermentation technology adoption and regional supply chain autonomy in China and India. Watch for ECHA enforcement intensity on respiratory sensitizer classification as the inflection signal determining liquid versus powder format migration speed.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Technology Adoption | Chinese manufacturers deploy this at twice the batch rate, compressing capital recovery timelines. |
| Backward Integration into Feedstocks | BASF SE's model sustains margin control across detergent, food, and leather verticals. |
| REACH Annex XIV Compliance Investment | German and Polish powder manufacturers absorb steepest costs, accelerating format migration. |
| Regional Capacity Expansion | Shandong province anchors fastest-expanding fermentation cluster for alkaline subtilisin supply. |
| Performance-Based Supply Contracts | Novozymes A/S leverages Danish R&D to anchor catalytic efficiency guarantee structures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced against primary interviews with fermentation plant managers, detergent procurement leads, leather tannery technical directors, and bioprocess R&D heads. ECHA dossier databases, SAMR GB standard publications, Indian PLI scheme administrative records, and SEC 10-K disclosures from listed enzyme suppliers provided validation layers. Bottom-up strain-level production estimates and top-down end-use consumption models underwent iterative reconciliation.
Reconciliation across supply-side capacity surveys and demand-side procurement audits shaped the analytical framework. Segmentation dimensions spanned pH tolerance grade, application vertical, end-user procurement scale, and regional regulatory cluster. CAGRs derived from logarithmic trend fitting across annual volume trajectories, with bioprocess intensification adoption curves and engineered thermostability penetration rates serving as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt REACH enforcement escalation or agricultural commodity price spikes. Assumptions reflect documented fermentation scale-up timelines and regulatory approval cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
HPHT Diamond Cubic Press Market
Others
Asia-Pacific Road Safety Market
Others
Double Card Mobile Phone Market
Others
Global Multi Domain Controller Market
Others
Pickup Truck Market
Others
Smart Badge Market
Others
Global Recruitment and Staffing Market
Others
Wearable AI Market
Others
Shisha Tobacco Market
Others
Spain Automotive LED Lighting Market
Others
Radiation Detection Monitoring and Safety Market
Others
Europe Military 4D Printing Market
Others
Fluid Dispensing Systems Market
Others
Global Solder Balls Market
Others
Senior Cat Food Market
Others
South America Automotive LED Lighting Market