
 Methyl Acetate Market | 2026-2036
Methyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
Methyl Acetate Market Analysis
Buyer concentration in automotive coatings is hardening as tier-one suppliers consolidate procurement volumes across fewer approved chemical vendors. BASF leverages its integrated acetyls chain to secure feedstock cost advantages for methyl acetate output. Celanese Corporation anchors North American supply through its Texas manufacturing complex, while Eastman Chemical Company competes on specialty-grade purity standards for pharmaceutical clients.
Methyl acetate is an organic ester with the chemical formula CH₃COOCH₃, produced through esterification of acetic acid with methanol or carbonylation of dimethyl ether, and functions primarily as a fast-evaporating solvent with low residual odor. Solvent-grade material dominates volume flows into paints and coatings formulations where rapid dry times reduce process energy. Industrial-grade supply is accelerating fastest in adhesives for electronics assembly, while reagent-grade commands premium pricing in pharmaceutical analytical laboratories.
EPA hazardous air pollutant standards and REACH substance restrictions shape product specifications and market access conditions for methyl acetate producers across multiple jurisdictions. China's MEE enforces emission caps on esterification plants operating near the Yangtze River basin. Stakeholders must monitor evolving VOC thresholds and carbon-intensity benchmarks to sustain formulation approvals and manufacturing licenses.
Market Dynamics
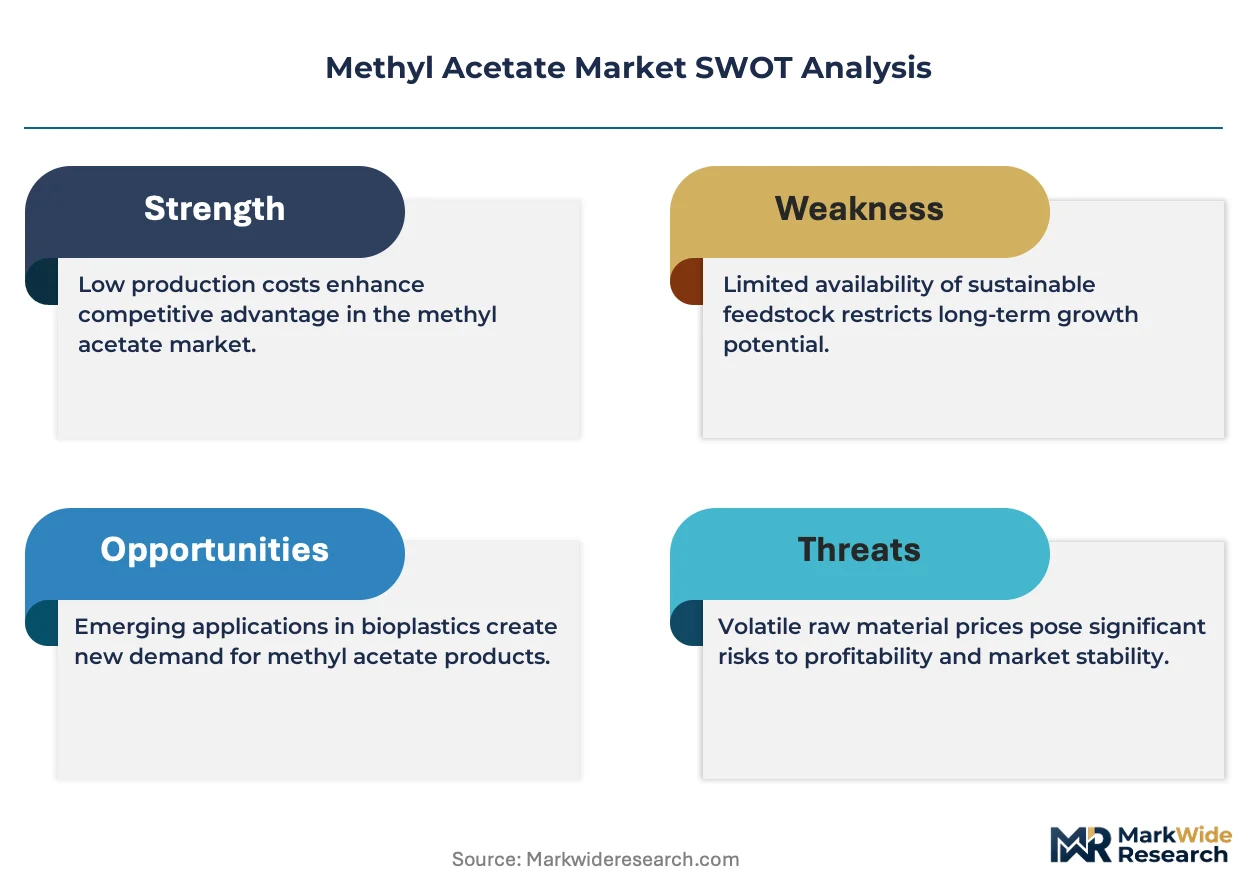
Automotive coatings procurement consolidation is compressing vendor margins while REACH VOC limits force solvent reformulation across European supply chains. Tier-one suppliers now mandate methyl acetate purity certifications that smaller producers cannot meet.
Growth Catalysts
- REACH VOC restrictions:European automotive OEMs are accelerating methyl acetate adoption in waterborne coating systems to comply with tightened emission thresholds.
- China's Yangtze River esterification cluster:Petrochemical integration around Nanjing and Shanghai delivers feedstock cost advantages for regional solvent-grade output.
- Fast-evaporating solvent demand:Electronics adhesives manufacturers favor methyl acetate for rapid-dry assembly processes in smartphone and tablet production.
Market Restraints
- Methanol price volatility:Feedstock cost swings from natural gas and coal-to-methanol capacity imbalances destabilize methyl acetate margin structures.
- China supply concentration:Over half of global esterification capacity sits within 200 kilometers of the Yangtze Delta, creating geographic risk exposure.
- Dimethyl carbonate substitution:Lower-toxicity alternatives are capturing share in European decorative paints where odor sensitivity drives specification changes.
Strategic Opportunities
- Indian pharmaceutical reagent-grade:CDSCO import substitution policies and expanding analytical laboratory infrastructure create premium purity demand.
- US IRA clean manufacturing credits:Carbon-intensity benchmarks for chemical production incentivize low-emission esterification process investments.
- Bio-based acetic acid convergence:Fermentation-derived feedstock integration with conventional methanol carbonylation opens sustainability-certified product lines.
Industry Challenges
- Process safety engineering talent:Esterification plant operators face acute shortages of professionals certified for high-pressure reactor management.
- REACH registration timelines:Extended substance evaluation periods for methyl acetate impurities delay market access for new production entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Methyl Acetate Market |
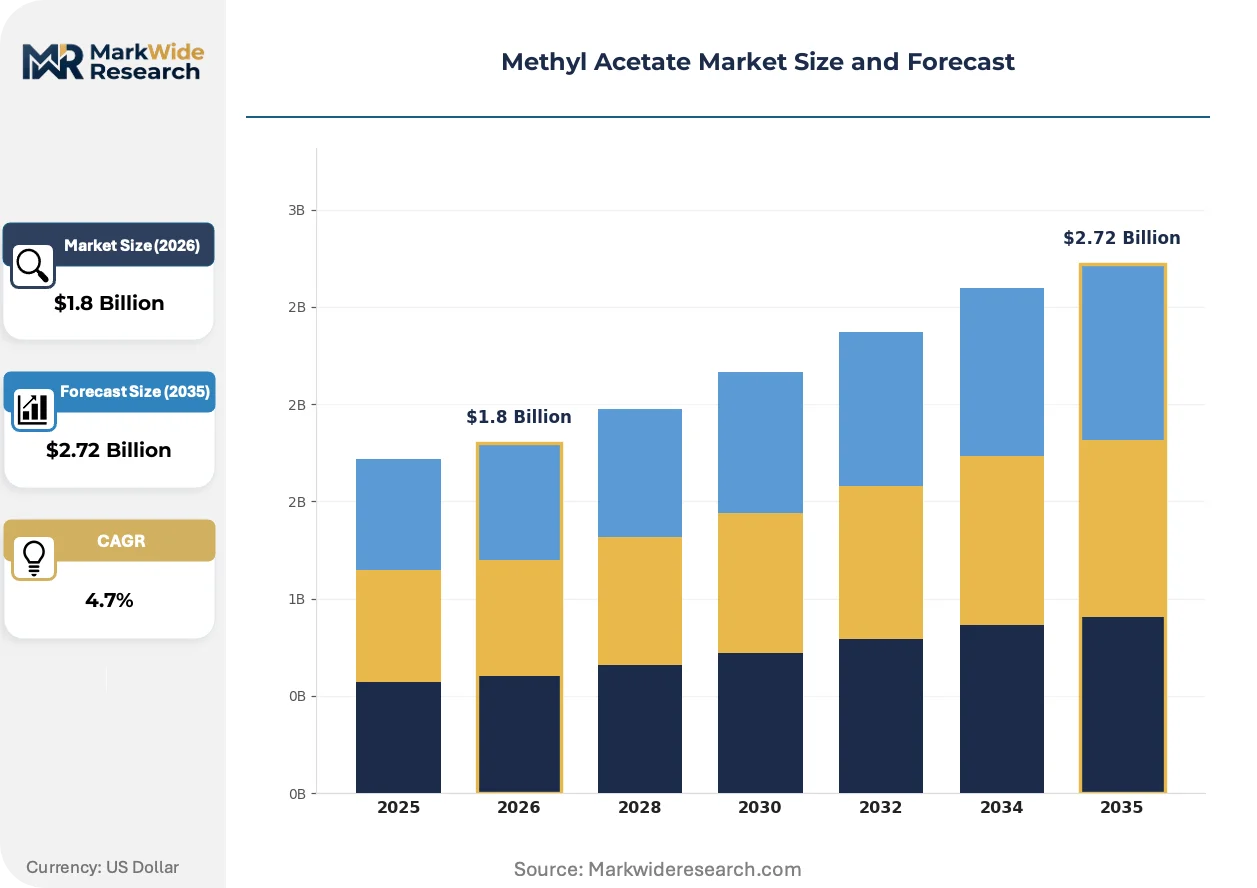
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent Grade, Industrial Grade, Reagent Grade, Specialty Grade Application: Paints, Coatings, Adhesives, Pharmaceuticals End User: Automotive, Construction, Electronics, Textiles Packaging Type: Drum, Tote, Bottle, Bulk |
| Companies Covered | BASF, Celanese Corporation, Eastman Chemical Company, Thermo Fisher Scientific Inc., Merck KGaA, Wacker Chemie AG, Anhui Wanwei Group Co. Ltd., China Petrochemical Corporation, Chang Chun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Methyl Acetate Market Emerging Trajectories
Process intensification and regulatory chemistry are rewriting competitive boundaries. Technology investments now prioritize emission reduction over throughput expansion.
Membrane separation technology is absorbing residual methanol and water from crude esterification output, enabling continuous processing that batch reactors cannot match. Specialty chemical producers in Germany and Japan are retrofitting existing acetyls plants with this capability. The technology is absorbing capital that would otherwise flow to greenfield capacity, compressing regional supply expansion timelines.
EPA hazardous air pollutant standards for synthetic organic chemical manufacturing are tightening monitoring requirements for fugitive emissions from methyl acetate storage and loading operations. Facilities must install enhanced leak detection systems and report quarterly to state environmental agencies. US Gulf Coast producers face the steepest compliance costs due to aged tank farm infrastructure.
Specification-driven procurement now dominates automotive tier-one solvent buying, with technical data packages replacing spot-market transactions. Coatings formulators in Germany and China are consolidating approved vendor lists to three or fewer methyl acetate suppliers per plant. This concentration is most visible in waterborne basecoat applications where trace impurity tolerances have tightened tenfold since 2020.
Methyl Acetate Market Segmentation
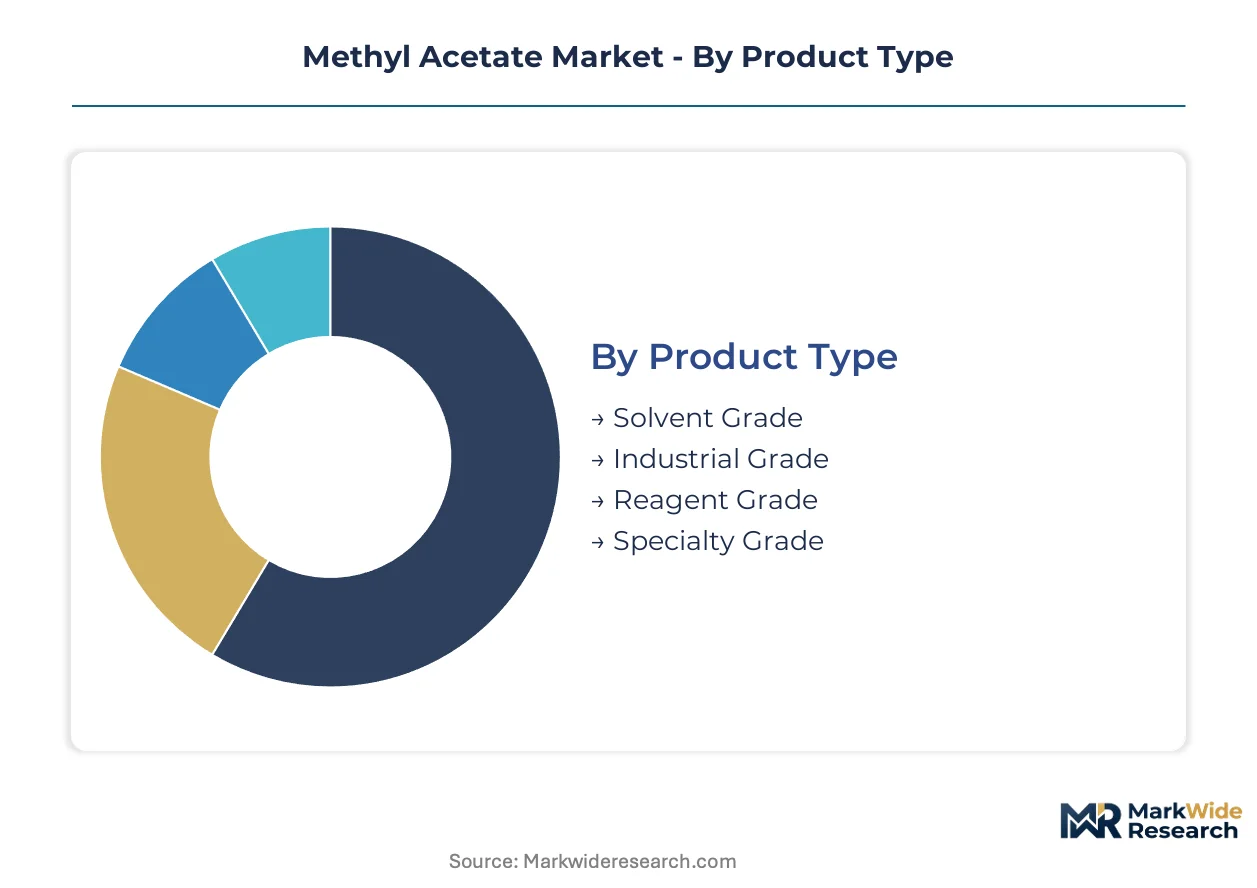
Product purity tiers and packaging formats determine margin capture in methyl acetate supply chains. End-use specifications from automotive coatings to pharmaceutical synthesis create divergent technical requirements that fragment procurement patterns across buyer categories.
Product Type:
Buyers select purity grades based on residual tolerance specifications and downstream process sensitivity.
- Solvent Grade:Contains 85-95% methyl acetate with controlled moisture and acid content for general industrial dissolution. Automotive coatings manufacturers in Germany and China specify this grade for waterborne basecoat formulations where rapid evaporation reduces booth energy consumption.
- Industrial Grade:Standard purity for adhesives and general chemical processing where trace impurities do not compromise bond performance. Electronics assembly plants in China's Pearl River Delta favor this grade for smartphone component adhesives requiring consistent dry times.
- Reagent Grade:High-purity material meeting analytical laboratory standards for chromatography and synthesis.
- Specialty Grade:Ultra-pure variants with custom impurity profiles for pharmaceutical manufacturing.
Solvent Grade leads on scale; Reagent Grade leads on momentum.
Application:
Formulation chemistry dictates solvent selection across surface treatment and bonding processes.
- Paints:Decorative and protective coatings leverage methyl acetate's low residual odor and fast flash-off. Architectural formulators in Europe specify this solvent for interior applications where occupant exposure limits are tightening under REACH amendments.
- Coatings:Industrial finishes for metal and plastic substrates require controlled evaporation profiles. Automotive OEMs in Germany mandate methyl acetate in clearcoat systems to meet VOC reduction targets without sacrificing appearance quality.
- Adhesives:Pressure-sensitive and structural bonding formulations use methyl acetate as a carrier solvent.
- Pharmaceuticals:Active ingredient extraction and tablet coating applications demand certified purity documentation.
Coatings dominates volume contribution; Adhesives expands most quickly.
End User:
Industry-specific process conditions drive specification divergence and certification requirements.
- Automotive:OEM and tier-one supplier paint shops require batch-traceable solvent with guaranteed impurity ceilings. Waterborne coating system conversions at German and Chinese assembly plants are accelerating methyl acetate procurement volumes.
- Construction:Architectural coatings and sealant manufacturers specify solvent-grade material for field-applied products.
- Electronics:Precision assembly operations demand consistent evaporation rates for automated dispensing equipment.
- Textiles:Fiber treatment and printing applications use methyl acetate in dye carrier formulations.
Automotive anchors procurement scale; Electronics gains share fastest.
Packaging Type:
Volume per delivery point and handling infrastructure determine container economics.
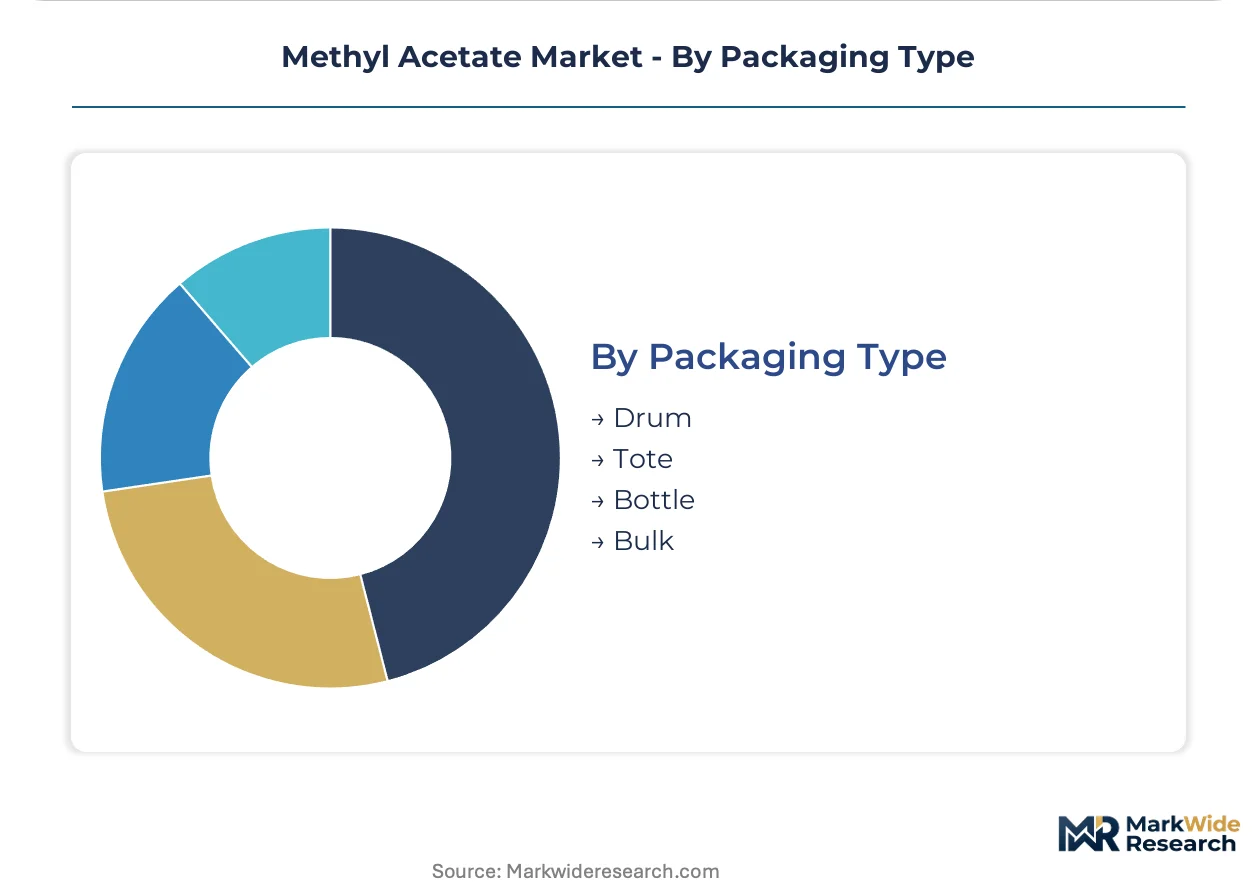
- Drum:200-liter steel containers serve mid-volume coatings formulators lacking bulk storage. Regional distributors in India stock drum inventory for construction sector customers with intermittent demand patterns.
- Tote:Intermediate bulk containers reduce per-liter handling costs for multi-ton monthly offtake.
- Bottle:Laboratory and pilot-scale quantities for analytical and R&D applications.
- Bulk:Tanker and railcar delivery for integrated chemical plants with dedicated storage.
Bulk commands the highest throughput; Tote shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chemical engineering talent clusters around the Yangtze River Delta, the US Gulf Coast, and Germany's acetyls corridor anchor methyl acetate production geography. These workforce concentrations determine where capacity expands and where regulatory compliance expertise accumulates.
China
Automotive waterborne coating conversions and electronics adhesives manufacturing drive solvent-grade consumption. MEE emission caps on Yangtze River basin esterification plants tighten discharge standards for volatile organics. Nanjing and Shanghai petrochemical complexes integrate methanol-to-acetate chains that supply coatings formulators across Jiangsu and Zhejiang provinces.
Germany
REACH VOC restrictions accelerate methyl acetate substitution in automotive OEM clearcoat systems. ECHA substance evaluation timelines extend registration burdens for new market entrants. The acetyls corridor between Ludwigshafen and Frankfurt hosts integrated producers supplying tier-one automotive paint shops with batch-traceable solvent.
United States
IRA clean manufacturing credits incentivize low-emission esterification investments for pharmaceutical-grade output. EPA hazardous air pollutant standards mandate enhanced leak detection at Gulf Coast storage facilities. Texas chemical complexes anchor North American supply chains for industrial-grade material serving electronics assembly plants.
India
CDSCO import substitution policies expand domestic reagent-grade production for pharmaceutical analytical laboratories. Central Pollution Control Board emission norms tighten on esterification units in Gujarat and Maharashtra. Mumbai-Pune industrial belt distributors stock drum-format inventory for construction sector coatings customers.
Japan
Electronics precision assembly operations demand consistent evaporation rates for automated methyl acetate dispensing equipment. METI carbon neutrality roadmaps pressure chemical producers toward process efficiency investments. Chubu region acetyls plants serve Nagoya automotive supplier clusters with specialty-grade purity certifications.
Methyl Acetate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across methyl acetate supply tiers. The market structure concentrates around integrated acetyls producers with captive methanol supply and independent esterification specialists serving regional coatings clusters. Three archetypes dominate: petrochemical majors with backward integration into feedstock, regional chemical processors with flexible batch capacity, and laboratory chemical distributors with reagent-grade certification capabilities. Capacity expansion and purity certification investments constitute the dominant competitive moves as procurement consolidation hardens vendor qualification requirements.
Within the integrated petrochemical tier, BASF and Celanese Corporation exemplify archetypes with upstream control over acetyls feedstock chains. Eastman Chemical Company occupies a position emphasizing specialty-grade purity standards for pharmaceutical and coatings applications requiring documented impurity ceilings. These three anchors represent the competitive spectrum from commodity solvent-grade volume to certified reagent-grade premium positioning.
| Leading Market Players |
|---|
| BASF |
| Celanese Corporation |
| Eastman Chemical Company |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Wacker Chemie AG |
| Anhui Wanwei Group Co. Ltd. |
| China Petrochemical Corporation |
| Chang Chun Group |
| Others |
Supply Flow & Price Mechanics
Integrated petrochemical majors with sovereign wealth backing anchor supply discipline across the Yangtze River Delta and US Gulf Coast, translating captive methanol positions into pricing power that independent esterification specialists cannot match. Their long-term offtake contracts with automotive tier-one suppliers insulate volume commitments from spot-market volatility.
Pricing Analysis
Certification-bundled supply agreements separate solvent-grade spot transactions from reagent-grade contracts with documented impurity ceilings. Price differentiation hinges on REACH registration status and ISO-certified purity documentation. Pricing pressure stems from methanol feedstock volatility destabilizing margin structures for non-integrated producers. Automotive OEMs show lowest price sensitivity due to specification lock-in, while construction sector drum buyers exhibit highest elasticity.
Supply Chain Analysis
Methyl acetate output rests on methanol carbonylation and acetic acid esterification pathways drawing from coal-to-chemical complexes in China and natural gas-derived feedstock in the United States. Critical inputs span methanol, acetic acid, and sulfuric acid catalysts. Single-source vulnerability concentrates in Yangtze River basin esterification clusters exposed to MEE emission enforcement. Distribution runs through integrated petrochemical complexes supplying bulk tanker deliveries to coatings formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive waterborne coating conversions and pharmaceutical reagent-grade specifications reward purity certification investments over commodity volume plays.
For Market Incumbents: Extend backward integration into methanol supply to neutralize feedstock volatility compressing non-integrated margins. Lock in three-year purity certification contracts with German automotive OEMs before REACH evaluation timelines extend further. Dimethyl carbonate substitution in European decorative paints demands proactive specification defense through technical service partnerships. For New Entrants and Emerging Players: IRA clean manufacturing credits in the United States open a window for low-emission esterification investments serving pharmaceutical-grade demand. Target Indian reagent-grade supply gaps created by CDSCO import substitution policies. Pursue toll manufacturing arrangements with Yangtze River Delta facilities facing MEE emission cap constraints. For Investors and Strategic Acquirers: Valuations sit cheapest among regional chemical processors lacking REACH registration completion. Five-to-ten-year viability favors integrated acetyls producers with captive feedstock and established automotive qualification status. Watch EPA hazardous air pollutant enforcement intensity at Gulf Coast tank farms as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive methanol supply from Texas and Nanjing complexes neutralizes feedstock volatility eroding independent esterification margins. |
| Green Manufacturing Transition | Bio-based acetic acid fermentation integration opens sustainability-certified product lines for European automotive OEM procurement. |
| Long-term Supply Agreement | Three-year purity certification contracts with German tier-one suppliers lock out spot-market competitors from waterborne coating formulations. |
| Capacity Expansion | Membrane separation retrofits at Ludwigshafen acetyls plants enable continuous processing without greenfield construction timelines. |
| Joint Venture | Indian pharmaceutical distributor partnerships bypass CDSCO import barriers for reagent-grade laboratory chemical supply. |
Methodological Framework
Bottom-up coatings and adhesives formulation modeling reconciled against top-down esterification capacity tracking forms the analytical core of this study. Primary interviews with plant managers at Yangtze River Delta facilities, procurement leads at German automotive tier-one suppliers, and distribution channel partners in India's Mumbai-Pune belt combined with secondary validation from customs trade data, Cefic solvent market reports, and SEC chemical sector filings. Triangulation across these sources ensures demand estimates align with verified production volumes.
Input-output matrices mapping methanol feedstock costs through acetyls chain economics to methyl acetate purity tier pricing generate volume and value outputs across the projection horizon. Segmentation dimensions span solvent-industrial-reagent-specialty grade tiers, automotive-electronics-pharmaceutical end-use industries, and drum-tote-bulk packaging formats. CAGRs derive from regression analysis against automotive production forecasts and REACH VOC compliance timelines. Industry-specific inputs include MEE emission cap enforcement intensity and IRA clean manufacturing credit qualification thresholds.
Revisions become necessary when methanol price volatility exceeds historical bands or when REACH substance evaluation timelines extend beyond modeled assumptions. Forecasts reflect documented assumptions about regulatory enforcement consistency and automotive waterborne coating conversion rates. A small set of named triggers—EPA hazardous air pollutant standard tightening, CDSCO import substitution acceleration, and dimethyl carbonate substitution penetration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
High Purity Solvents Market
Solvents
Europe Hydrocarbon Solvents Market
Solvents
Glycerol Market
Solvents
Green Solvents Market
Solvents
Butyl Acetate (BAC) Market
Solvents
North America Toluene Market
Solvents
Global Furfural Solvent Market
Solvents
Diethanolamide Market
Solvents
Solvent Green 7 Market
Solvents
Global Chloroform Market
Solvents
Para Nitrochlorobenzene Market
Solvents
6-Xylenol Market
Solvents
Ethoxydiglycol Market
Solvents
Ethane Market
Solvents
Hydrosol Market
Solvents
Benzene and Its Derivatives Market