
 Canada Pharmaceutical Market | 2026-2036
Canada Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Pharmaceutical Market Analysis
Market Context
Biologics manufacturing is fragmenting as contract development organizations multiply across Canadian provinces. Bausch Health Companies anchors its dermatology and gastrointestinal portfolio through captive manufacturing infrastructure in Quebec. Knight Therapeutics leverages specialty licensing agreements to sustain access to niche hospital-administered therapies.
Technical and Segment Structure
Canada pharmaceutical output encompasses small-molecule synthesis, biologic fermentation, and sterile fill-finish operations governed by Health Canada Good Manufacturing Practice standards, with primary purpose to supply prescription and non-prescription therapeutics to provincial drug plans and private payers. Prescription drugs dominate reimbursement volume under the Canada Health Act framework, while biologics capture concentrated margin pools due to cold-chain complexity and biosimilar transition dynamics. Oncology applications within hospital end-user settings represent the fastest-growing demand segment as provincial cancer agencies expand immunotherapy formularies.
Regulatory Frame and Outlook
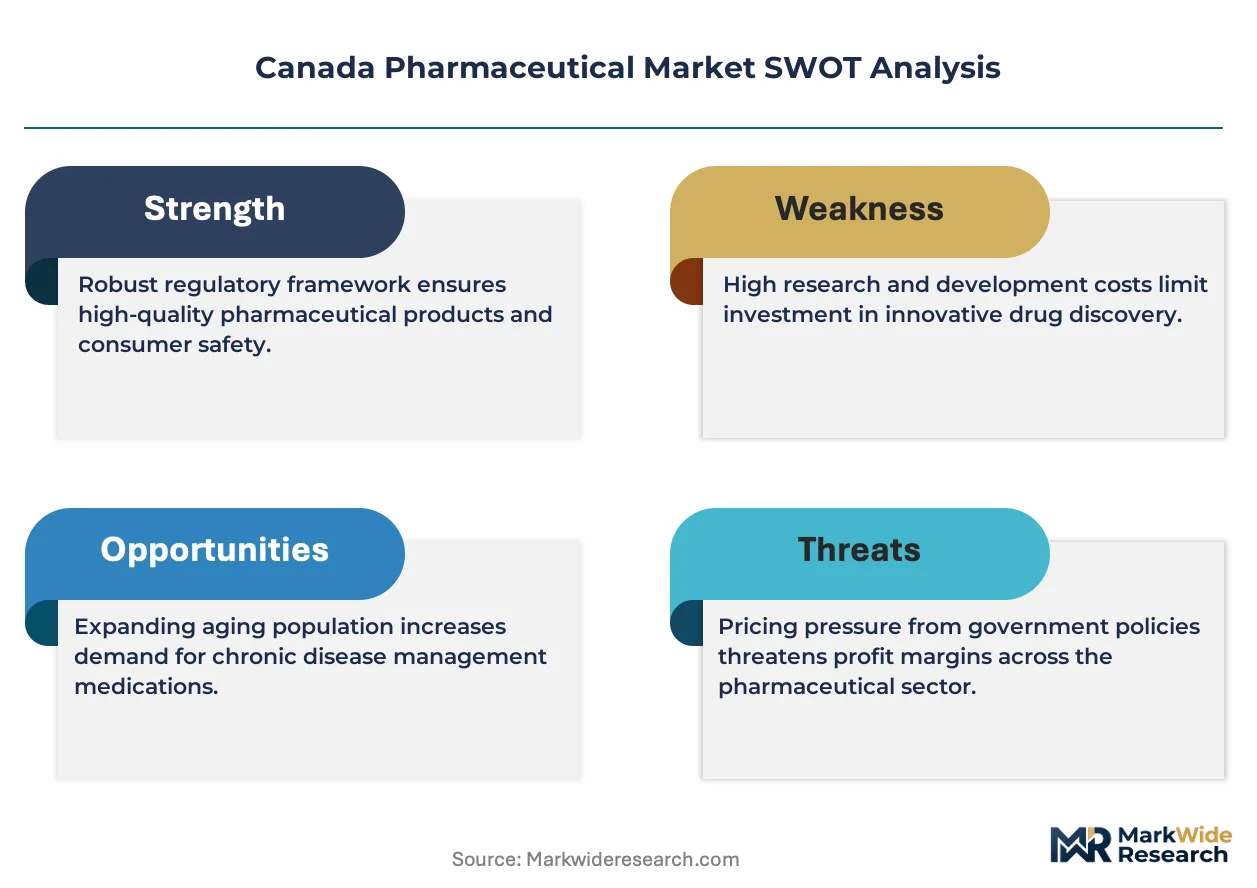
Health Canada, the Patented Medicine Prices Review Board, and provincial public drug programs collectively shape market access through pricing negotiations, reference-based reimbursement, and mandatory biosimilar switching policies. Health Canada's ICH Q12 implementation for post-approval management is streamlining manufacturing change reporting for established products. Stakeholders must monitor the interplay between federal patent term restoration proposals and provincial bulk purchasing consortia to anticipate margin compression timelines.
Market Dynamics
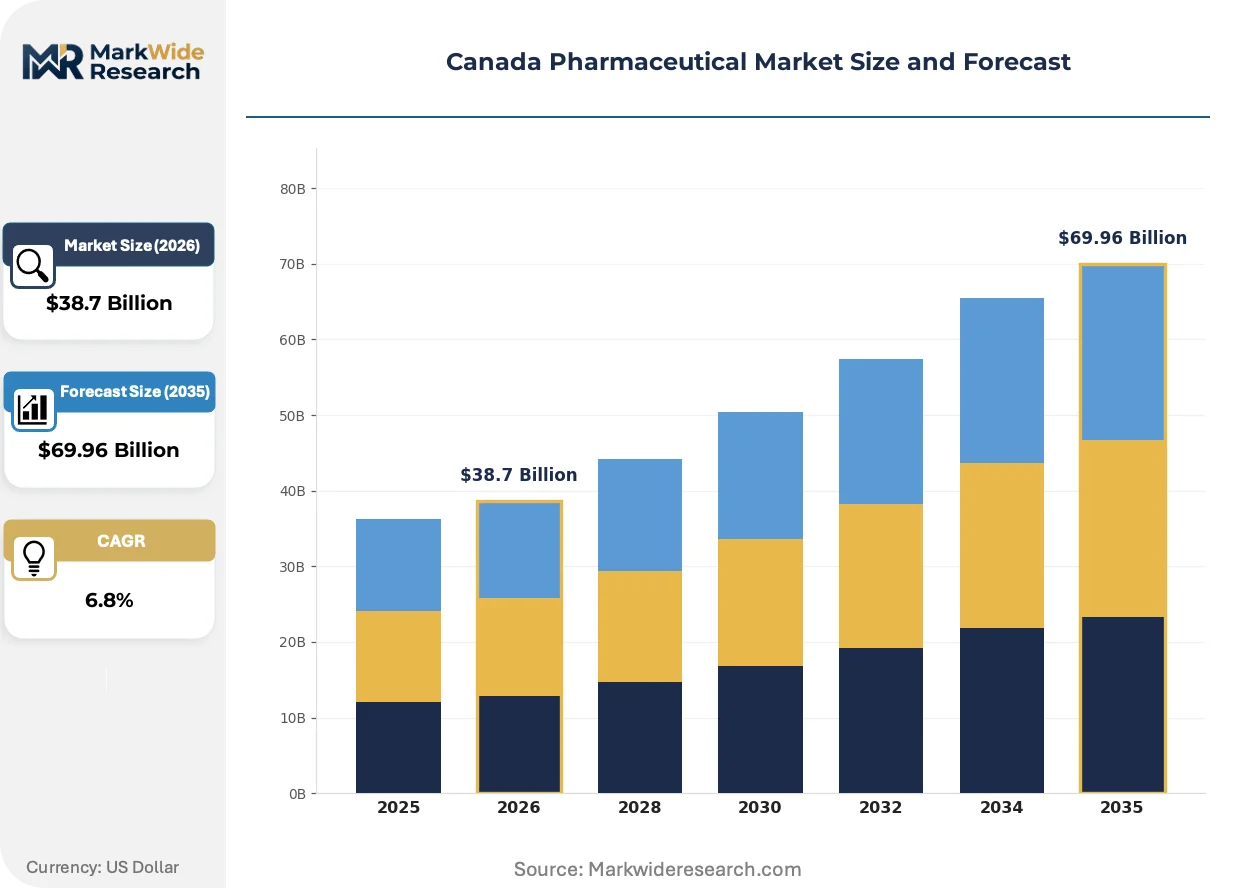
Canada's pharmaceutical sector is restructuring around provincial biosimilar switching mandates and Health Canada's accelerated approval pathways for complex generics, compressing legacy brand revenue cycles while amplifying contract manufacturing demand.
Growth Catalysts
- Health Canada ICH Q12 Implementation:Post-approval manufacturing change reporting is streamlining for established products, reducing regulatory lag for production line modifications and facility transfers.
- Ontario Cancer Agency Immunotherapy Expansion:Provincial formularies are broadening access to hospital-administered biologics, creating concentrated demand pull through Greater Toronto Area procurement consortia.
- Biologics Contract Manufacturing:Fermentation and sterile fill-finish capacity is multiplying across Quebec and British Columbia as hospital groups seek captive supply security.
Market Restraints
- API Import Concentration:Active pharmaceutical ingredient supply chains remain concentrated with offshore manufacturers, exposing domestic formulators to shipping volatility and customs delays.
- Patented Medicine Prices Review Board Pricing Compression:Federal reference pricing mechanisms are narrowing therapeutic margin bands for innovative molecules entering provincial formularies.
- Cold-Chain Infrastructure Gaps:Biologics distribution outside the Quebec-Ontario corridor faces temperature-controlled logistics limitations, constraining patient access in Atlantic provinces and Northern territories.
Strategic Opportunities
- Atlantic Canada Underpenetration:Nova Scotia and New Brunswick hospital procurement remains fragmented, creating whitespace for integrated distribution partnerships with regional health authorities.
- Digital Therapeutics Convergence:Prescription software and traditional pharmaceuticals are merging, with Health Canada establishing novel regulatory pathways for software-as-medical-device combinations.
- Provincial Bulk Purchasing Consortia:Ontario and Quebec joint procurement initiatives are consolidating buying power, rewarding manufacturers with domestic manufacturing footprints.
Industry Challenges
- Biologics Manufacturing Talent Scarcity:Fermentation science and cell-culture engineering expertise is concentrated in Montreal and Toronto, constraining capacity expansion in secondary markets.
- Legacy ERP Integration Friction:Hospital procurement systems require custom middleware for real-time inventory visibility, complicating vendor onboarding for specialty distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Pharmaceutical Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, OTC Drugs, Biologics, Generics Application: Cardiovascular, Oncology, Neurology, Infectious Disease End User: Hospitals, Pharmacies, Clinics, Research Institutions Distribution Channel: Retail, Wholesalers, Direct-to-Consumer, Online |
| Companies Covered | Cipher Pharmaceuticals, Tilray Brands, Bausch Health Companies, Satellos Bioscience, BioSyent, Knight Therapeutics, Xenon Pharmaceuticals, NurExone Biologic, HLS Therapeutics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Pharmaceutical Market Emerging Trajectories
Continuous manufacturing platforms and AI-driven formulation design are compressing development timelines, while provincial reimbursement policies are rewiring competitive positioning around local production footprints.
Continuous processing technology is collapsing batch-to-batch variability in oral solid dosage production. Generic manufacturers in Ontario are retrofitting legacy facilities with direct compression lines to reduce changeover downtime. This shift is collapsing the cost differential between high-volume and mid-scale production runs, enabling regional contract manufacturers to compete for hospital tender volumes previously reserved for multinational scale.
Health Canada's implementation of ICH Q5A(R2) viral safety guidelines is tightening raw material sourcing requirements for biologics. Plasma-derived and recombinant product manufacturers must now document supply chain provenance to the sub-tier level. Biologics sponsors with Quebec-based fractionation capacity are accelerating facility qualification to maintain formulary access under the tightened standards.
Hospital procurement groups are consolidating specialty pharmacy administration under provincial cancer agency umbrellas. Standalone oncology clinics in British Columbia and Alberta are losing direct purchasing authority as care delivery centralizes. This concentration is most visible in Ontario, where the provincial agency now controls immunotherapy allocation across fourteen academic medical centers.
Canada Pharmaceutical Market Segmentation
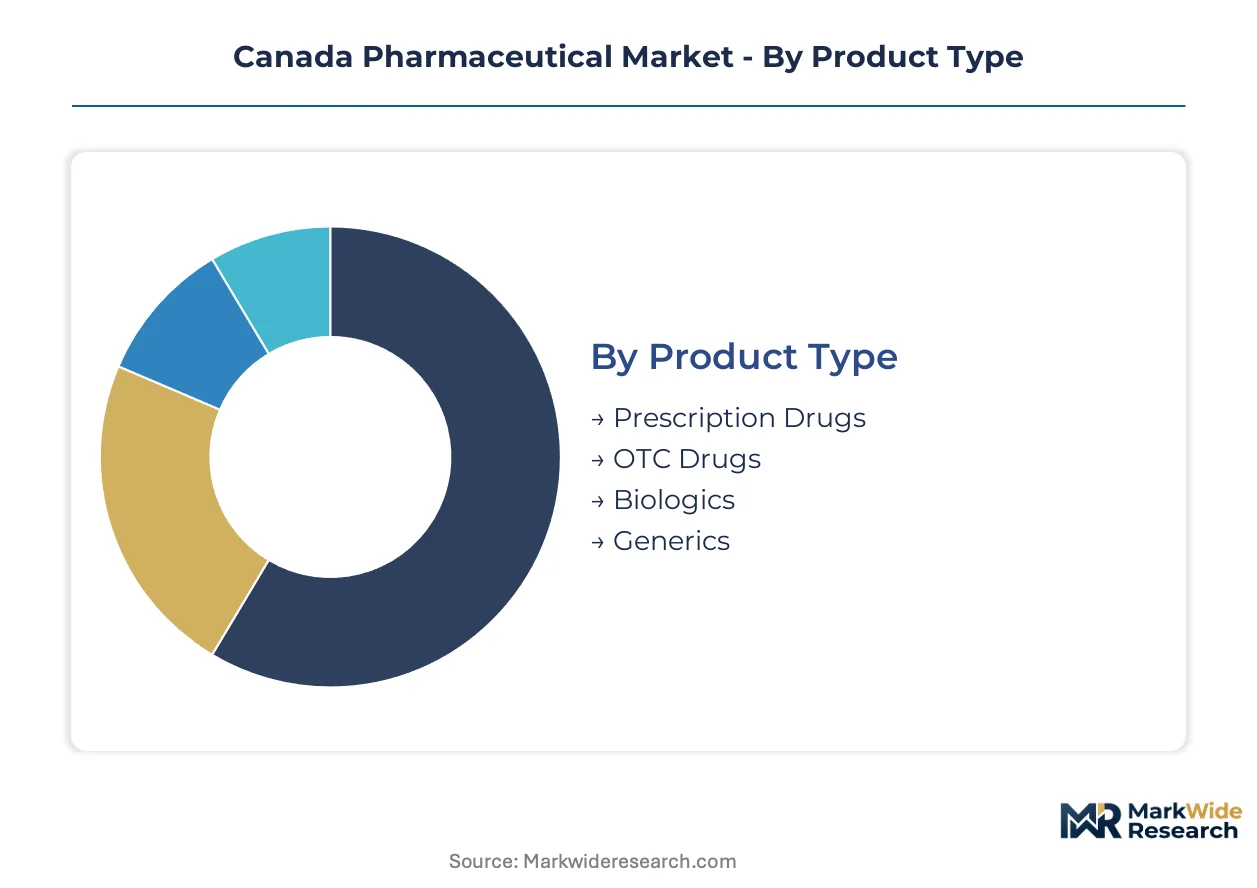
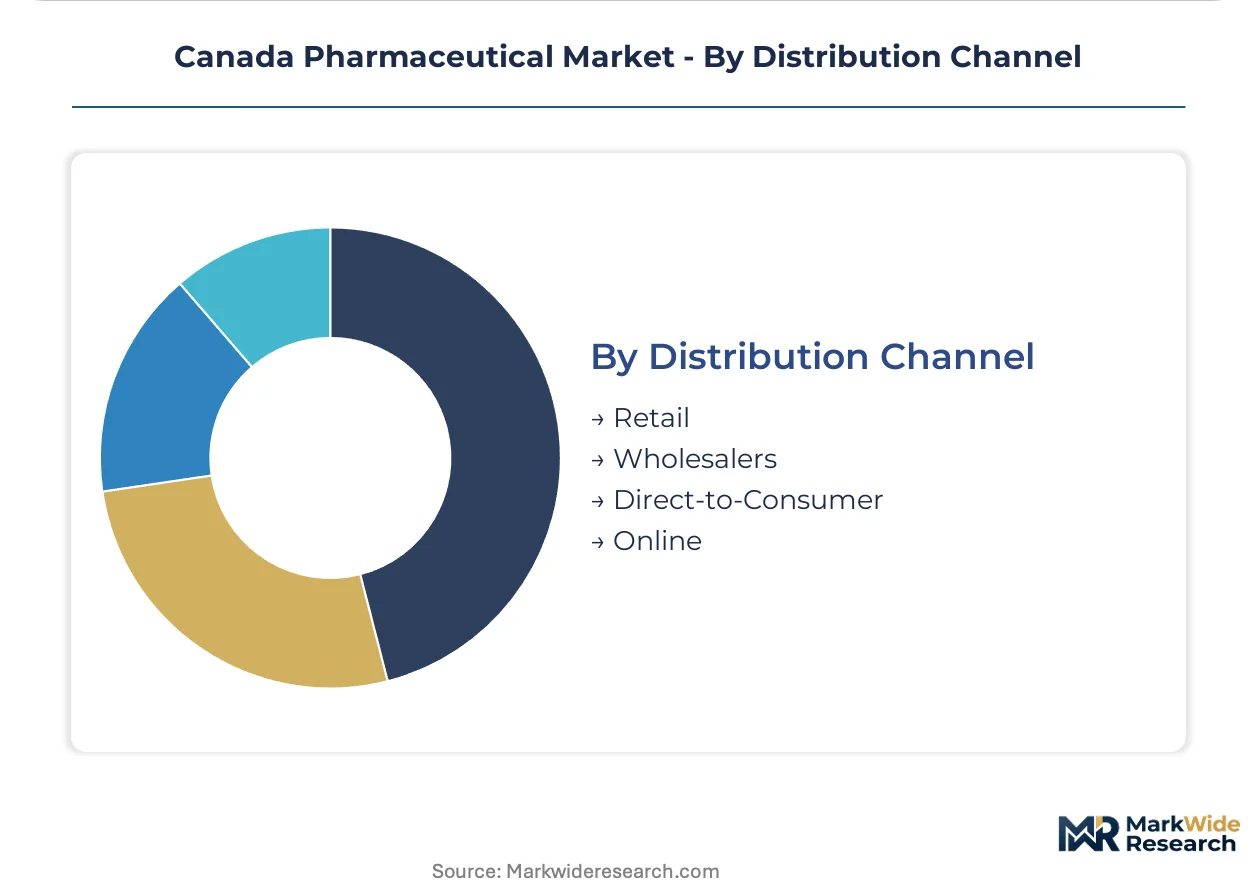
Segmentation in the Canadian pharmaceutical market reveals how provincial procurement consolidation and Health Canada regulatory pathways are rewiring competitive dynamics across product categories and distribution channels. Understanding these fault lines exposes where margin pools concentrate and where access barriers persist.
Product Type:
Mature small-molecule categories coexist with emerging biologic fermentation platforms, creating divergent investment requirements and regulatory timelines across the manufacturing base.
- Prescription Drugs:Small-molecule formulations governed by Health Canada Good Manufacturing Practice standards dominate provincial formulary reimbursement volumes. Ontario's bulk purchasing consortia concentrate demand pull for cardiovascular and diabetes therapies through centralized tendering.
- Biologics:Fermentation-derived and recombinant proteins requiring cold-chain distribution capture concentrated margin pools due to manufacturing complexity and biosimilar transition dynamics. Hospital-administered oncology biologics within Quebec and Ontario cancer agencies represent the steepest expansion trajectory among all product categories.
- OTC Drugs:Self-medication products distributed through retail pharmacy networks face margin compression from private-label substitution and direct-to-consumer digital channels.
- Generics:Complex generic entrants benefit from Health Canada's accelerated approval pathways for challenging formulations, though reference pricing mechanisms narrow therapeutic margin bands.
Prescription drugs retain volume leadership; biologics holds the steepest expansion curve.
Application:
Cost tier stratification separates hospital-administered specialty therapies from outpatient chronic disease management, with reimbursement authority fragmenting across provincial health authorities.
- Oncology:Immunotherapy and targeted therapy expansion within provincial cancer agency formularies concentrates demand in Greater Toronto Area and Montreal academic medical centers. Health Canada's ICH Q5A(R2) viral safety guidelines tighten raw material sourcing requirements for biologics sponsors.
- Cardiovascular:Generic antihypertensive and statin volumes flow through Ontario and Quebec joint procurement initiatives, rewarding manufacturers with domestic manufacturing footprints.
- Neurology:Specialty therapies for multiple sclerosis and epilepsy face restricted formulary access outside hospital neurology departments due to high-cost monitoring requirements.
- Infectious Disease:Antimicrobial stewardship programs in British Columbia and Alberta hospitals constrain broad-spectrum prescribing, shifting demand toward narrow-spectrum alternatives.
Cardiovascular commands the largest prescription volume; oncology is climbing the fastest.
End User:
Customer type concentration is accelerating as provincial cancer agencies consolidate specialty pharmacy administration under single procurement umbrellas.
- Hospitals:Academic medical centers in Ontario, Quebec, and British Columbia administer the majority of intravenous biologics and oncology therapies. Centralized allocation now controls immunotherapy distribution across fourteen Ontario centers.
- Pharmacies:Community retail networks dispense chronic disease medications under provincial drug plan formularies, with Shoppers Drug Mart and independent chains competing for prescription volume.
- Clinics:Standalone oncology clinics in Alberta and British Columbia are losing direct purchasing authority as care delivery centralizes under provincial agency umbrellas.
- Research Institutions:Clinical trial sites in Montreal and Toronto generate early-stage demand for investigational therapies prior to Health Canada approval.
Hospitals dominate biologic administration; clinics face contracting procurement autonomy.
Distribution Channel:
Supply concentration varies sharply between temperature-controlled biologics logistics and ambient small-molecule distribution, with geographic coverage gaps persisting outside the Quebec-Ontario corridor.
- Wholesalers:McKesson and AmerisourceBergen handle the majority of hospital and pharmacy deliveries, with inventory visibility requirements forcing custom middleware investments from specialty distributors.
- Retail:Brick-and-mortar pharmacy chains maintain formulary access for chronic disease medications, though front-of-store OTC categories face digital displacement.
- Online:Direct-to-consumer platforms are gaining share in OTC and wellness categories, with Health Canada establishing novel regulatory pathways for prescription software combinations.
- Direct-to-Consumer:Manufacturer-owned specialty pharmacies for rare disease therapies bypass traditional wholesale channels to maintain cold-chain integrity and patient support services.
Wholesalers retain infrastructure dominance; online channels are expanding most quickly in non-prescription categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian pharmaceutical exports flow primarily to the United States, with cross-border supply chains integrating Quebec and Ontario manufacturing clusters into American hospital procurement networks. Provincial regulatory divergence creates distinct commercial environments across domestic sub-regions.
Ontario
The Greater Toronto Area hosts the densest concentration of biologics manufacturing and hospital procurement authority. Health Canada's accelerated approval pathways for complex generics are attracting fermentation capacity investments to the corridor. Fourteen academic medical centers now coordinate immunotherapy allocation through centralized provincial cancer agency tendering.
Quebec
Montreal anchors domestic biologics production with captive fractionation and sterile fill-finish infrastructure. The province's hospital procurement groups are consolidating specialty pharmacy administration under unified umbrellas. Bausch Health Companies maintains dermatology and gastrointestinal manufacturing operations serving both provincial formularies and export markets.
British Columbia
Vancouver and the Lower Mainland are emerging as secondary biologics manufacturing nodes targeting Asia-Pacific export corridors. Cold-chain distribution limitations constrain patient access to temperature-sensitive therapies in northern and interior regions. Provincial cancer agencies are absorbing purchasing authority from standalone oncology clinics.
Alberta
Calgary and Edmonton hospital systems participate in western provincial procurement consortia for cardiovascular and diabetes therapies. Antimicrobial stewardship programs are narrowing infectious disease prescribing patterns toward narrow-spectrum alternatives. Talent scarcity in cell-culture engineering limits local biologics capacity expansion.
Atlantic Canada
Nova Scotia and New Brunswick hospital procurement remains fragmented across regional health authorities, creating whitespace for integrated distribution partnerships. Temperature-controlled logistics gaps delay biologics access outside Halifax and Moncton corridors. Knight Therapeutics leverages specialty licensing to sustain formulary presence in underserved markets.
Canada Pharmaceutical Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement environments. The vendor base clusters around three strategic archetypes: multinational manufacturers with captive Quebec infrastructure, mid-cap specialty licensors leveraging hospital relationships, and emerging biotech developers targeting orphan indications. Competitive moves center on provincial tender participation and Health Canada regulatory pathway navigation.
Within the specialty licensing tier, Knight Therapeutics and HLS Therapeutics exemplify asset-light models built on hospital-administered therapy access. Cipher Pharmaceuticals anchors the complex generic segment, while Bausch Health Companies occupies a position among integrated manufacturers with captive production infrastructure.
| Leading Market Players |
|---|
| Cipher Pharmaceuticals |
| Tilray Brands |
| Bausch Health Companies |
| Satellos Bioscience |
| BioSyent |
| Knight Therapeutics |
| Xenon Pharmaceuticals |
| NurExone Biologic |
| HLS Therapeutics |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Atlantic Canada biologics cold-chain distribution is forcing manufacturers to absorb premium logistics costs while provincial cancer agencies consolidate purchasing leverage. This utilization squeeze simultaneously erodes margin buffers for temperature-sensitive therapies and amplifies price sensitivity among hospital procurement groups negotiating formulary access.
Pricing Analysis
Generational pricing gaps separate legacy small-molecule portfolios from emerging biologic fermentation platforms and next-generation biosimilar entrants. Three-tier pricing structure across originator biologics, approved biosimilars, and complex generic alternatives dominates hospital tendering, with Health Canada ICH Q12 implementation compressing the cost differential between established and novel manufacturing processes. Price differentiation hinges on cold-chain certification grade and domestic production footprint, with Ontario bulk purchasing consortia driving cost compression in cardiovascular and diabetes categories. Reference pricing mechanisms from the Patented Medicine Prices Review Board intensify margin pressure on innovative molecules entering provincial formularies, while hospital-administered oncology therapies remain least price-sensitive due to limited therapeutic alternatives.
Supply Chain Analysis
Extended payment terms from provincial bulk purchasing consortia are squeezing working capital for specialty distributors serving hospital networks. Active pharmaceutical ingredient supply concentrates with manufacturers in India, China, and the United States, exposing domestic formulators to shipping volatility and customs delays. Fermentation equipment, chromatography resins, and single-use bioreactor components constitute critical input dependencies. Single-source vulnerability in offshore API sourcing represents the dominant structural risk, compounded by tariff exposure on Chinese-manufactured raw materials. Distribution runs through McKesson and AmerisourceBergen wholesaler networks for ambient small-molecule products, while direct-to-hospital cold-chain logistics predominate for biologics requiring temperature-controlled integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's pharmaceutical sector is approaching a platform-economics inflection as Health Canada digital therapeutics pathways merge prescription software with traditional drug reimbursement, creating interoperability demands that favor integrated data-capable suppliers over standalone manufacturers.
For Market Incumbents: Entrench formulary position through captive Quebec manufacturing infrastructure and accelerated Health Canada ICH Q5A(R2) facility qualification. Bausch Health Companies demonstrates defensive consolidation through dermatology and gastrointestinal portfolio anchoring. Prioritize vertical integration into sterile fill-finish capacity to offset biosimilar switching mandates eroding originator revenue cycles. For New Entrants and Emerging Players: Build out integrated distribution partnerships with Atlantic Canada regional health authorities, where fragmented Nova Scotia and New Brunswick procurement creates whitespace for specialty pharmacy administration. Knight Therapeutics exemplifies asset-light market penetration through hospital-administered therapy licensing. Target digital therapeutics convergence as the most penetrable segment, leveraging Health Canada novel regulatory pathways for software-as-medical-device combinations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics fermentation capacity as hospital procurement groups seek captive supply security. Long-term viability over the next decade favors manufacturers with Quebec-Ontario corridor production footprints and established provincial tender participation. Monitor Health Canada patent term restoration proposals as the critical inflection signal for margin compression timelines versus innovation incentive preservation.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada ICH Q12 Implementation | Streamlines post-approval manufacturing changes, reducing regulatory lag for production line modifications. |
| Provincial Biosimilar Switching Mandate | Accelerates formulary transition dynamics, compressing originator revenue cycles while amplifying contract manufacturing demand. |
| Atlantic Canada Distribution Partnership | Addresses cold-chain infrastructure gaps outside Quebec-Ontario corridor, capturing underserved hospital procurement volume. |
| Digital Therapeutics Regulatory Pathway | Establishes novel reimbursement frameworks for prescription software and pharmaceutical combinations. |
| Biologics Fermentation Capacity Expansion | Responds to Ontario Cancer Agency immunotherapy formulary expansion and hospital group supply security demands. |
Methodological Framework
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation. Health Canada submissions, provincial drug plan formularies, ClinicalTrials.gov records, and Patented Medicine Prices Review Board pricing decisions constituted core secondary sources. Bottom-up demand modeling across product type, application, end user, and distribution channel segments was triangulated with top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning prescription drugs, biologics, OTC, and generics by product type; oncology, cardiovascular, neurology, and infectious disease by application; and hospitals, pharmacies, clinics, and research institutions by end user. CAGRs were derived through trend extrapolation calibrated to Health Canada approval velocity and provincial reimbursement policy trajectories. Forecast inputs incorporated immunotherapy formulary expansion rates and biosimilar penetration assumptions by therapeutic category.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by multinational manufacturers or accelerated provincial bulk purchasing consolidation would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Sinus Therapeutic Drugs Market
Pharmaceuticals
Latin America Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
North America Adenomyosis Drugs Market
Pharmaceuticals
Canada Specialty Pharmacy Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Global Two Piece Empty Hard Capsule Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Vaginitis Therapeutics Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
P2X7 Receptor Antagonists Market