
 Quinoline Market | 2026-2036
Quinoline Market Size, Share, and Industry Trends Forecast 2026-2036
Quinoline Market Outlook
Multi-source procurement for quinoline intermediates is hardening among Western pharmaceutical buyers seeking supply resilience. Lonza Group AG leverages its Swiss manufacturing base to sustain high-purity quinoline output for active pharmaceutical ingredient synthesis. Merck KGaA anchors European demand through specialized reagent-grade distribution. China Sunsine Chemical Holdings Ltd. dominates bulk quinoline derivative production with integrated coal-tar feedstock access.
Quinoline is a heterocyclic aromatic compound with formula C9H7N, typically synthesized via Skraup or Friedlander condensation from aniline and glycerol, serving as a foundational scaffold for antimalarial drugs, agrochemical fungicides, and corrosion inhibitors. The 2-methylquinoline and 4-methylquinoline product grades command premium pricing due to pharmaceutical-grade purity requirements and constrained batch reactor capacity. Pharmaceutical applications absorb the largest value share, while agrochemical formulations represent the fastest volume expansion as crop protection distributors in Brazil and India broaden quinoline-based fungicide adoption.
EPA chemical safety evaluations under TSCA Section 6 are elevating testing burdens for quinoline imports into the United States, while REACH registration dossiers in Europe mandate full toxicological profiling for volume tiers above one tonne annually. China's MEE enforcement of dual carbon goals is pressuring coal-tar based quinoline producers to retrofit emissions control systems or shift to petroleum-derived feedstocks. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate which purity certifications will become mandatory for market access.
Market Dynamics
REACH registration dossiers in Europe and EPA chemical safety evaluations under TSCA Section 6 are forcing quinoline producers to rebuild purification infrastructure, diverting capital from capacity expansion into toxicological testing and emissions retrofitting.
Growth Catalysts
- Antimalarial API demand:Pharmaceutical manufacturers in India and China are scaling procurement of quinoline derivatives for artemisinin-combination therapy synthesis, tightening spot market availability.
- Agrochemical fungicide adoption:Crop protection distributors in Brazil and India are broadening quinoline-based fungicide formulations for soybean and rice disease management.
- Coal-tar feedstock integration:East China's chemical manufacturing clusters around Shanghai and Jiangsu province maintain captive access to refined naphthalene and quinoline streams.
Market Restraints
- Coal-tar input volatility:China's MEE enforcement of dual carbon goals is pressuring coal-tar based quinoline producers to retrofit emissions control systems or absorb petroleum-derived feedstock cost premiums.
- Batch reactor capacity constraints:Pharmaceutical-grade 2-methylquinoline and 4-methylquinoline production remains locked in stainless-steel batch vessels with limited throughput expansion.
- Substitution pressure from pyridine derivatives:Agrochemical formulators in select fungicide applications are trialing pyridine-based heterocycles as drop-in replacements.
Strategic Opportunities
- Underpenetrated Brazilian agrochemical channel:Quinoline-based fungicide distributors have yet to match the penetration depth achieved by triazole competitors in Mato Grosso and Paraná soybean belts.
- REACH-compliant reagent-grade positioning:European specialty chemical distributors can capture margin premiums by pre-certifying quinoline lots for ECHA-registered volume tiers above one tonne annually.
- Continuous flow reactor retrofit:Microreactor technology convergence with traditional Skraup condensation chemistry promises to compress batch cycle times and impurity profiles simultaneously.
Industry Challenges
- Process analytical chemistry skill scarcity:Real-time purity verification for pharmaceutical-grade quinoline requires trained spectroscopists familiar with USP-NF monograph compliance.
- Multi-jurisdiction certification lag:Simultaneous EPA TSCA Section 6 submissions and REACH dossier updates stretch regulatory affairs teams across 18-24 month approval windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quinoline Market |
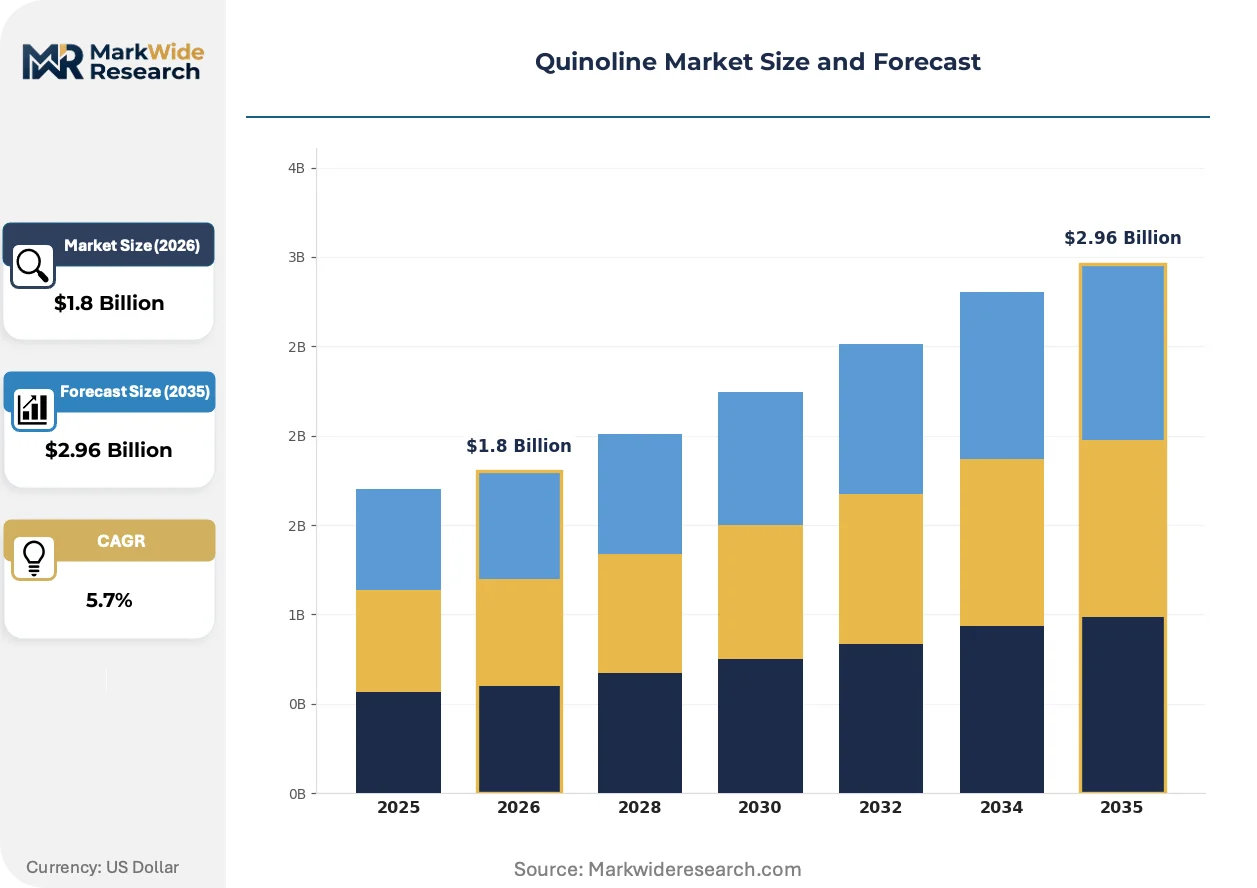
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2-Methylquinoline, 4-Methylquinoline, 6-Methylquinoline, Quinoline-3-Carboxylic Acid Application: Pharmaceuticals, Agrochemicals, Dyes, Flavors End User: Drug Manufacturers, Chemical Producers, Research Laboratories, Textile Industry Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | Lonza Group AG, Huntsman International LLC, Merck KGaA, China Sunsine Chemical Holdings Ltd., Ansteel Group Corporation, BASF SE, Jubilant Life Sciences Limited, Shanghai Xinchen Fine Chemical Co. Ltd, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quinoline Market Strategic Shifts
Continuous processing technology and real-time analytical verification are displacing traditional batch quinoline synthesis, while regulatory divergence between EPA and ECHA frameworks is fragmenting certification requirements.
Microreactor-based continuous flow synthesis is converging with traditional Skraup condensation chemistry to enable tighter temperature control and reduced impurity formation. Mid-scale pharmaceutical intermediates producers in Switzerland and Germany are piloting these systems for high-purity 2-methylquinoline output. The technology is converging with in-line NIR spectroscopy to compress quality assurance timelines from days to hours.
EPA chemical safety evaluations under TSCA Section 6 are elevating testing burdens for quinoline imports into the United States, requiring 90-day subchronic toxicity studies not previously mandated. European producers with existing REACH dossiers face lower incremental compliance costs than new market entrants. Agrochemical formulators are responding by dual-sourcing from REACH-registered and EPA-compliant suppliers to maintain cross-Atlantic supply continuity.
Western pharmaceutical buyers are consolidating vendor lists and demanding multi-year supply agreements with certified purity guarantees, displacing spot-market purchasing for critical antimalarial intermediates. Procurement teams at large API manufacturers now require quarterly audit rights and batch-level CoA documentation. This behavioral shift is most visible among Swiss and German pharmaceutical companies with vertically integrated antimalarial production pipelines.
Quinoline Market Segmentation
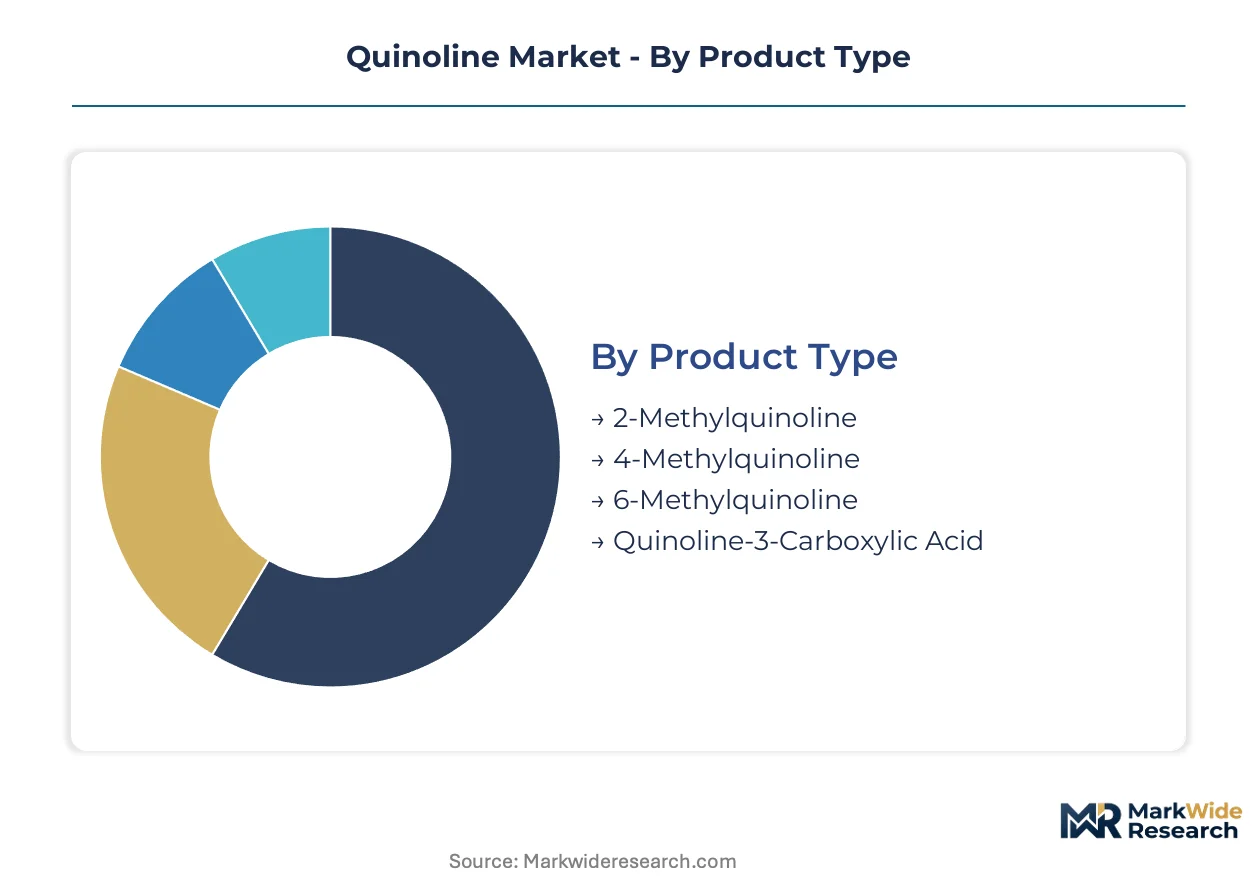
Quinoline derivatives diverge sharply in purity specifications and pricing power across pharmaceutical versus industrial grades. Segmentation reveals where batch reactor constraints and regulatory certification burdens concentrate margin capture.
Product Type:
Purchasing behavior splits between pharmaceutical buyers demanding USP-NF monograph compliance and industrial formulators prioritizing feedstock cost stability.
- 2-Methylquinoline:Pharmaceutical-grade batches require stainless-steel reactor campaigns with sub-0.1% impurity ceilings. Drug manufacturers in Switzerland and Germany contract quarterly for certified lots under multi-year agreements, locking out spot-market volatility.
- 4-Methylquinoline:Serves as the primary scaffold for antimalarial API synthesis, with demand concentrating at Indian pharmaceutical clusters around Hyderabad and Ahmedabad. ECHA-registered volume tiers above one tonne annually command 15-20% premia over unregistered material.
- 6-Methylquinoline:Industrial dye intermediate with lower purity thresholds; procurement flows through Shanghai-based distributors to textile processors in Zhejiang province.
- Quinoline-3-Carboxylic Acid:Niche reagent-grade product for research laboratory synthesis; volumes remain constrained by batch campaign economics.
Volume sits with 2-methylquinoline; growth tilts toward 4-methylquinoline.
Application:
End-use economics separate high-margin pharmaceutical contracts from commoditized industrial offtake.
- Pharmaceuticals:Antimalarial and antibiotic synthesis absorbs the largest value share. Artemisinin-combination therapy manufacturers in India scale procurement of quinoline derivatives, tightening spot availability for non-contracted buyers.
- Agrochemicals:Fungicide formulators in Brazil's Mato Grosso soybean belt are broadening quinoline-based crop protection adoption, representing the steepest expansion trajectory among all applications.
- Dyes:Textile colorant producers in China's Jiangsu province source 6-methylquinoline for azo dye coupling reactions.
- Flavors:Fragrance compound manufacturers utilize trace quinoline derivatives for bittering agents in food-grade applications.
Revenue concentrates in pharmaceuticals; volume expansion accelerates fastest in agrochemicals.
End User:
Customer scale determines whether procurement flows through audited supply agreements or spot-market distributors.
- Drug Manufacturers:Large API producers demand quarterly audit rights and batch-level CoA documentation, consolidating vendor lists to REACH-registered and EPA-compliant suppliers exclusively.
- Chemical Producers:Intermediate processors in East China's manufacturing clusters around Shanghai maintain captive coal-tar feedstock access for bulk quinoline derivative output.
- Research Laboratories:Academic and contract research organizations purchase gram-to-kilogram quantities through specialized reagent distributors.
- Textile Industry:Dye houses procure through regional chemical distributors with limited purity certification requirements.
Contract value clusters with drug manufacturers; transaction frequency peaks at research laboratories.
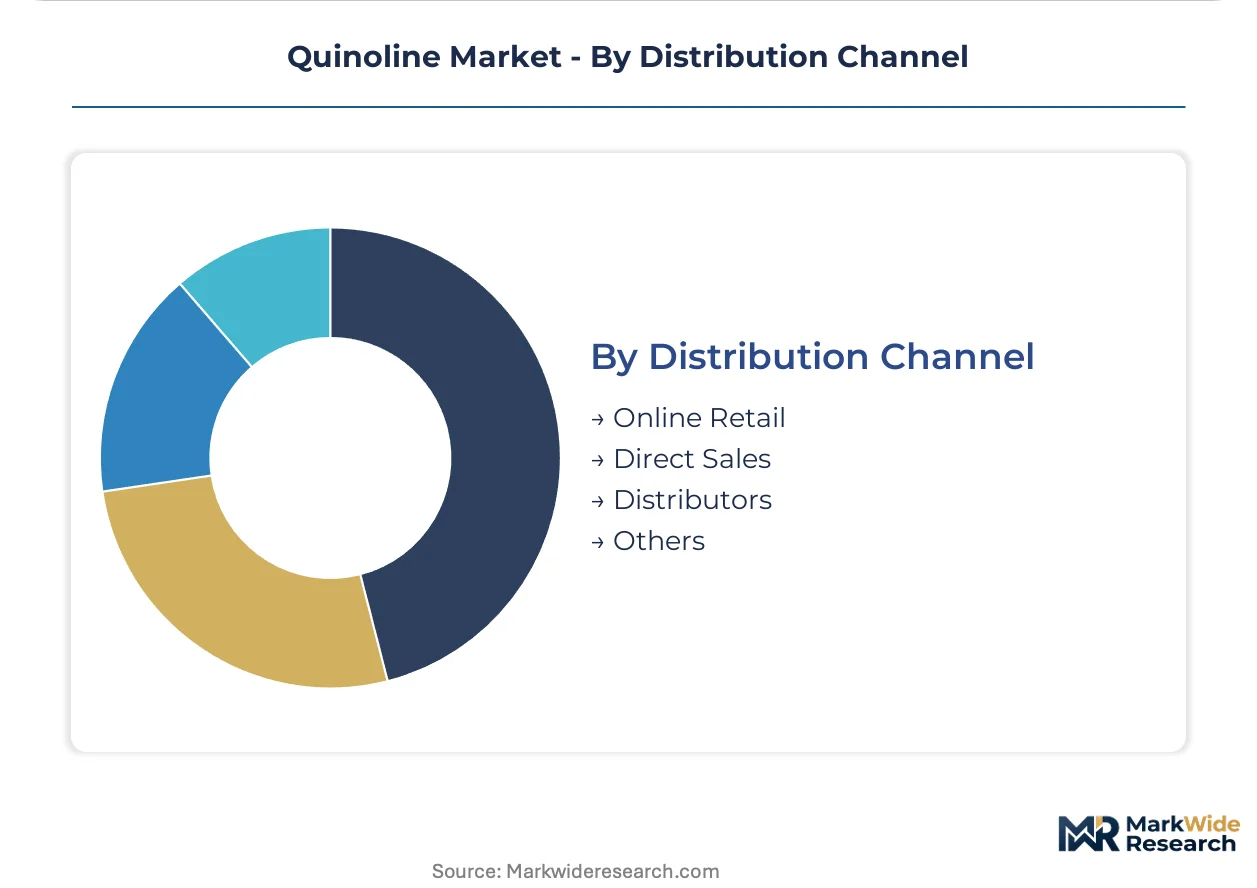
Distribution Channel:
Channel selection tracks order size, certification urgency, and geographic proximity to manufacturing clusters.
- Direct Sales:Pharmaceutical-grade 2-methylquinoline and 4-methylquinoline move through manufacturer-direct relationships with multi-year supply agreements and locked pricing.
- Distributors:Industrial-grade material flows through Shanghai-based and Rotterdam-based chemical distributors serving agrochemical and dye formulators.
- Online Retail:Research-grade quantities and reagent-catalog SKUs reach laboratories through specialized e-commerce platforms.
- Others:Remaining channels include trading houses and import-export brokers handling cross-border arbitrage.
Margin retention favors direct sales; geographic reach extends through distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coal-tar refining clusters in East China generate the dominant share of global quinoline feedstock. Procurement patterns now diverge sharply between REACH-registered European supply and EPA-compliant North American channels. Regulatory fragmentation is forcing buyers to maintain dual-qualified supplier bases.
China
Pharmaceutical-grade 4-methylquinoline demand from Indian API manufacturers is tightening spot availability for export-grade material. MEE enforcement of dual carbon goals pressures coal-tar based producers around Shanghai and Jiangsu province to retrofit emissions control systems. East China's chemical manufacturing clusters maintain captive access to refined naphthalene and quinoline streams from integrated coking operations.
India
Artemisinin-combination therapy manufacturers in Hyderabad and Ahmedabad are scaling procurement of quinoline derivatives for antimalarial synthesis. CDSCO mandates batch-level CoA documentation for imported pharmaceutical intermediates above specified purity thresholds. Gujarat's specialty chemical corridor is attracting contract manufacturing investment from European quinoline distributors seeking dual-source supply resilience.
Germany
REACH registration dossiers for volume tiers above one tonne annually command 15-20% premia over unregistered material from non-European sources. ECHA toxicological profiling requirements are diverting capital from capacity expansion into dossier maintenance and analytical infrastructure. The country's Rhineland chemical belt hosts reagent-grade distributors specializing in USP-NF monograph-compliant quinoline for pharmaceutical synthesis.
United States
EPA chemical safety evaluations under TSCA Section 6 now require 90-day subchronic toxicity studies for quinoline imports not previously mandated. Pharmaceutical manufacturers are consolidating vendor lists to EPA-compliant suppliers exclusively, displacing spot-market purchasing. Texas and Louisiana petrochemical corridors are evaluating petroleum-derived quinoline feedstocks as alternatives to coal-tar based imports.
Brazil
Agrochemical formulators in Mato Grosso and Paraná soybean belts are broadening quinoline-based fungicide adoption for crop disease management. ANVISA registration pathways for novel fungicide actives are lengthening approval timelines, favoring established quinoline derivative suppliers with existing dossiers. São Paulo-state distributors are underpenetrated relative to triazole competitors in the premium fungicide segment.
Quinoline Market Competitive Environment
Capacity expansion dominates the current landscape as producers retrofit purification infrastructure to meet divergent EPA and ECHA compliance pathways. The vendor base separates into three tiers: integrated coal-tar refiners with captive feedstock access, specialty chemical distributors with REACH-registered reagent-grade positioning, and pharmaceutical intermediates specialists with USP-NF monograph capabilities. Strategic archetypes include backward-integrated Chinese producers, Swiss-German quality-certification leaders, and Indian contract manufacturers. M&A activity and continuous flow reactor technology licensing represent the dominant competitive moves.
Within the quality-certification tier, Lonza Group AG and Merck KGaA exemplify European producers leveraging existing REACH dossiers to sustain margin premiums. China Sunsine Chemical Holdings Ltd. occupies a position among integrated coal-tar refiners with captive feedstock access in East China's manufacturing clusters. These three anchors illustrate how regulatory geography is fragmenting competitive positioning across the value chain.
| Leading Market Players |
|---|
| Lonza Group AG |
| Huntsman International LLC |
| Merck KGaA |
| China Sunsine Chemical Holdings Ltd. |
| Ansteel Group Corporation |
| BASF SE |
| Jubilant Life Sciences Limited |
| Shanghai Xinchen Fine Chemical Co. Ltd |
| Lanxess AG |
| Others |
Value Chain & Pricing Dynamics
China's MEE enforcement of dual carbon goals gates both qualified supply and premium-tier pricing access, forcing coal-tar based producers to absorb emissions retrofit costs or shift to petroleum-derived feedstocks while pharmaceutical buyers lock in multi-year contracts with certified purity guarantees.
Pricing Analysis
Certification bundling separates REACH-registered and EPA-compliant supply from unregistered spot material, with ECHA-registered volume tiers above one tonne annually commanding 15-20% premia over unregistered alternatives. Price differentiation hinges on USP-NF monograph compliance and batch-level CoA documentation, with Swiss and German pharmaceutical manufacturers least sensitive due to vertically integrated antimalarial pipelines. Cost compression in industrial-grade 6-methylquinoline intensifies because Shanghai-based distributors compete on feedstock cost stability rather than purity thresholds. Agrochemical formulators in Brazil exhibit highest price sensitivity, sourcing through Rotterdam-based distributors to arbitrage regional cost differentials.
Supply Chain Analysis
Freight cost volatility from East China's chemical manufacturing clusters to Indian pharmaceutical hubs around Hyderabad and Ahmedabad strains just-in-time procurement for artemisinin-combination therapy manufacturers. Supply concentrates in China, India, and Switzerland, with captive coal-tar feedstock access in Shanghai and Jiangsu province anchoring bulk derivative output. Raw material dependencies include refined naphthalene streams, aniline, and glycerol for Skraup condensation chemistry. Single-source vulnerability persists for pharmaceutical-grade 2-methylquinoline locked in stainless-steel batch vessels with limited throughput expansion. Distribution runs through manufacturer-direct relationships for certified grades and Shanghai-based chemical distributors for industrial offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The quinoline market operates as a vertical-integration race where upstream control over coal-tar or petroleum-derived feedstock streams determines margin capture and regulatory compliance agility.
For Market Incumbents: To counter substitution pressure from pyridine derivatives in agrochemical fungicide applications, Lonza Group AG and Merck KGaA should deepen backward integration into captive feedstock refining while pre-certifying continuous flow reactor output for both REACH and EPA compliance pathways. Capacity addition in Gujarat's specialty chemical corridor captures dual-source supply resilience demand from European pharmaceutical buyers.
For New Entrants and Emerging Players: Capture underpenetrated Brazilian agrochemical channel whitespace by targeting Mato Grosso and Paraná soybean belts with quinoline-based fungicide formulations priced below triazole competitors. A go-to-market angle through São Paulo-state distributors with existing ANVISA registration dossiers accelerates market access without lengthy novel active approval timelines.
For Investors and Strategic Acquirers: Merck KGaA's licensing of microreactor-based continuous flow synthesis technology to mid-scale Swiss-German producers is the leading indicator that batch reactor capacity constraints are unlocking acquisition premiums for technology-enabled manufacturing assets. Long-term viability over a 5-10 year window favors targets with dual EPA-ECHA certification infrastructure and pilot-scale continuous flow capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Refining | Captive coal-tar or petroleum-derived naphthalene access insulates margin from MEE emissions enforcement cost shocks. |
| Continuous Flow Reactor Retrofit | Microreactor technology convergence with Skraup condensation chemistry compresses impurity profiles and batch cycle times simultaneously. |
| Dual EPA-REACH Certification Investment | Pre-certified supply agreements lock in pharmaceutical manufacturer procurement consolidation toward compliant vendor bases exclusively. |
| Long-term Supply Agreement with Indian API Manufacturers | Hyderabad and Ahmedabad artemisinin-combination therapy producers demand quarterly audit rights and locked pricing for 4-methylquinoline offtake. |
| Joint Venture in Gujarat Specialty Chemical Corridor | European distributors partner with Indian contract manufacturers to establish dual-source supply resilience for Western pharmaceutical buyers. |
Study Parameters
Independent corroboration across plant managers at East China coal-tar refiners, procurement leads at Indian pharmaceutical API manufacturers, and distribution channel partners in Rotterdam and São Paulo underwrites the qualitative findings in this study. Primary interviews with regulatory affairs specialists navigating simultaneous EPA TSCA Section 6 submissions and REACH dossier updates combined with secondary validation from customs/trade data, ACC/Cefic chemical industry reports, and SEC 10-K filings from listed specialty chemical producers. Bottom-up demand modeling across pharmaceutical, agrochemical, and industrial dye end-uses triangulates against top-down supply capacity assessments from integrated coking operations and petroleum-derived feedstock alternatives.
Comparable-period anchoring to historical batch reactor utilization rates and coal-tar refining capacity utilization across the analysis window establishes baseline supply constraints for projection modeling. Segmentation dimensions include pharmaceutical versus industrial grade tiers, antimalarial API versus fungicide versus dye intermediate end-use industries, and regional production hub clusters in East China, Gujarat, and the Swiss-German Rhineland belt. CAGRs derive from weighted average of demand elasticity coefficients for artemisinin-combination therapy procurement and agrochemical fungicide adoption curves. Industry-specific forecast inputs incorporate MEE dual carbon enforcement timelines and ANVISA registration pathway duration assumptions for Brazilian agrochemical market penetration.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between EPA and ECHA frameworks, continuous flow reactor technology adoption rates, and pyridine derivative substitution thresholds in agrochemical formulations. Forecasts reflect assumptions about batch reactor capacity expansion constraints and coal-tar feedstock cost stability that may revise with petroleum-derived alternative economics or breakthrough process analytical chemistry automation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Europe Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Cox 2 Inhibitors Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Duloxetine API Market