
 Duloxetine API Market | 2026-2036
Duloxetine API Market Size, Share, and Industry Trends Forecast 2026-2036
Duloxetine API Market Analysis
Contract manufacturers are redrawing procurement patterns in the duloxetine API landscape, displacing traditional captive sourcing by innovator firms. Teva Pharmaceutical Industries leverages vertical integration across formulation and API to sustain margin capture in generic duloxetine supply. Sun Pharmaceutical Industries anchors its position through R&D intensity in complex generic APIs. Aurobindo Pharma specializes in high-volume duloxetine production for regulated markets.
Duloxetine API is the active pharmaceutical ingredient of the serotonin-norepinephrine reuptake inhibitor (SNRI) duloxetine hydrochloride, typically manufactured via chiral synthesis with stringent control over enantiomeric purity exceeding 99.5%. Its primary commercial purpose is supplying finished dosage form manufacturers treating major depressive disorder, generalized anxiety disorder, and diabetic peripheral neuropathic pain. Oral capsules dominate current volume consumption, reflecting entrenched prescribing habits and established bioequivalence pathways. The fibromyalgia therapy area represents a faster-growing demand pocket as off-label restrictions ease in select markets. Contract manufacturers as an end-user segment concentrate margin pools through long-term supply agreements with multinational generic sponsors.
The FDA enforces ICH Q3D elemental impurity guidelines and nitrosamine risk assessment protocols that elevate analytical burden for duloxetine API producers seeking US market access. India's CDSCO aligns with WHO prequalification standards, enabling domestic manufacturers to serve export demand while the EMA's REACH framework governs chemical substance registration for European supply. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP monographs as divergence in dissolution and related-substances specifications creates compliance complexity for multi-territory suppliers.
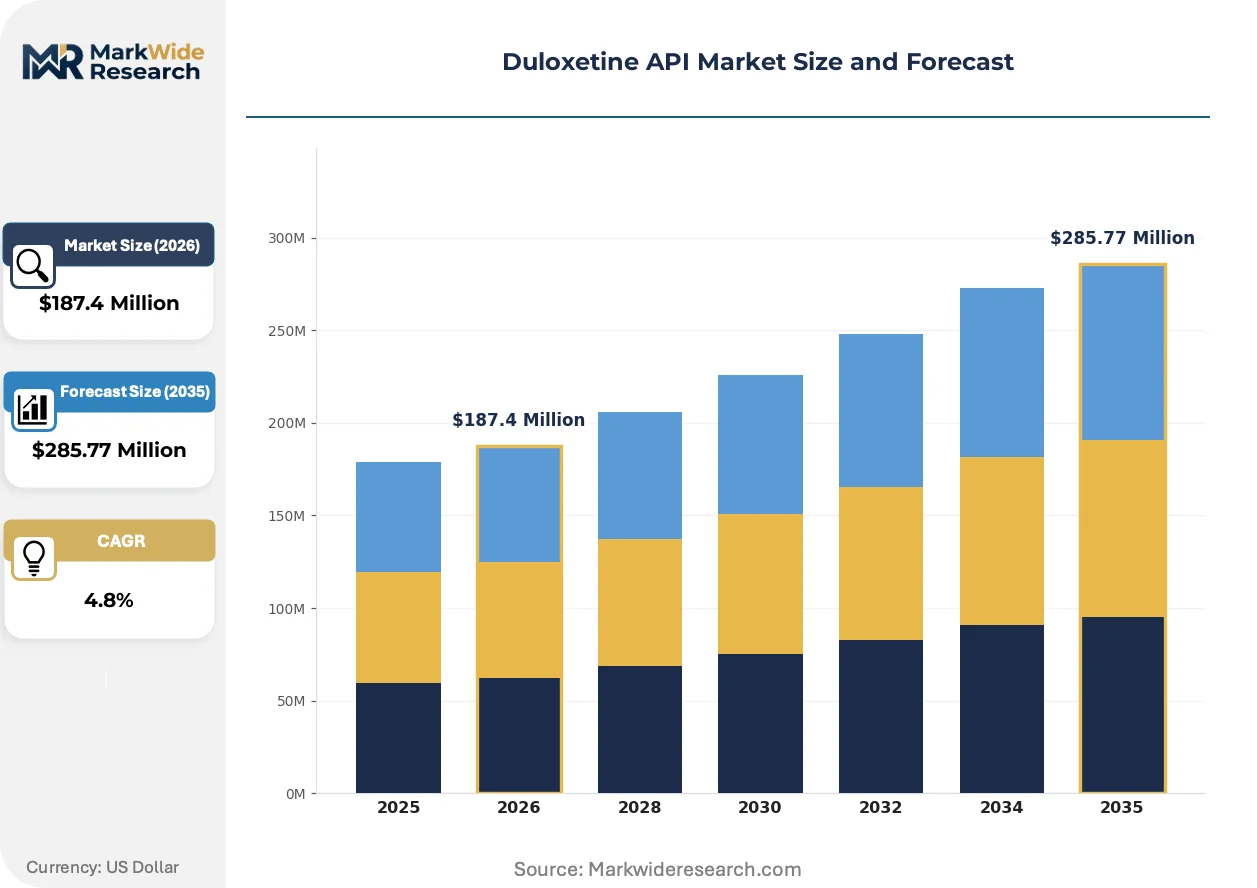
Market Dynamics
Patent expirations across major markets have dismantled innovator monopolies, triggering a wholesale reorganization of API procurement toward contract manufacturers in India who now supply generic finished dose producers across North America and Europe.
Growth Catalysts
- FDA Impurity Profiling Mandates:Tightened nitrosamine risk assessment protocols for serotonin-norepinephrine reuptake inhibitors are filtering out substandard API suppliers and consolidating volume with certified manufacturers.
- Diabetic Peripheral Neuropathy Indication Expansion:Prescriber acceptance of duloxetine for pain management in diabetes patients is broadening the addressable patient base beyond psychiatric applications.
- Chiral Synthesis Advancement:Enantiomeric purity control exceeding 99.5% has become achievable at commercial scale, enabling complex generic entrants to meet bioequivalence thresholds.
Market Restraints
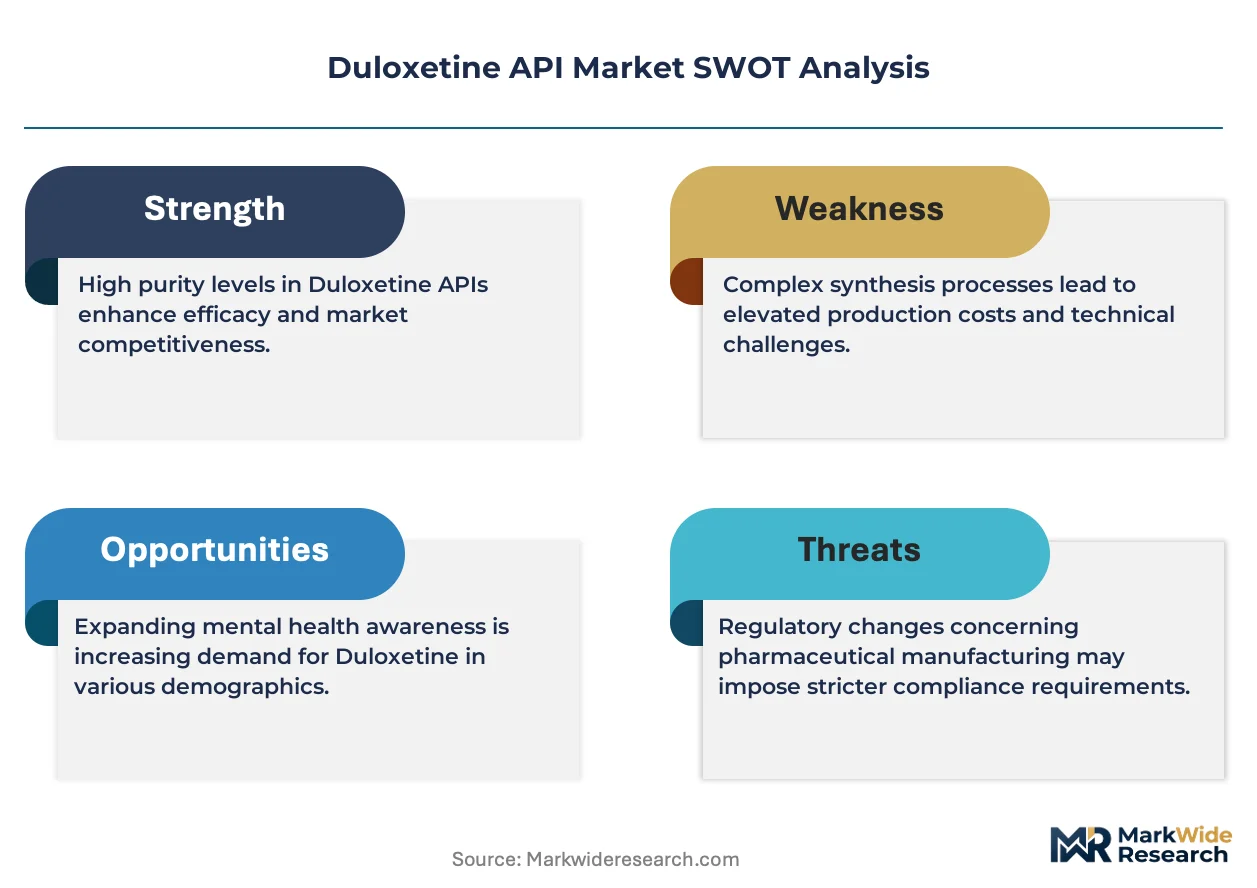
- ICH Q3D Compliance Burden:Elemental impurity testing requirements impose substantial analytical costs on smaller API producers seeking regulated market entry.
- Single-Geography Supply Concentration:India's dominance in contract manufacturing creates vulnerability to export policy shifts or logistics disruptions affecting North American and European supply security.
- Active Pharmaceutical Ingredient Input Volatility:Naphthol derivative and chiral auxiliary feedstock prices fluctuate with petrochemical cycles, compressing margin predictability for non-integrated producers.
Strategic Opportunities
- Fibromyalgia Off-Label Liberalization:Easing restrictions in select European and Latin American markets are opening new therapeutic demand pockets for duloxetine API.
- Pharmacopeial Harmonization Gaps:Divergence between USP, EP, and IP dissolution specifications creates arbitrage potential for multi-territory suppliers with flexible quality systems.
- Continuous Flow Manufacturing Adoption:Transition from batch to flow chemistry for chiral synthesis promises yield improvements and reduced solvent waste profiles.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Qualified personnel for nitrosamine and elemental impurity method development command premium compensation in competitive labor markets.
- Multi-Pharmacopeia Certification Timelines:Simultaneous USP, EP, and IP monograph compliance extends regulatory approval cycles and delays revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duloxetine API Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Capsules, Oral Solution, Injectable, Others Therapy Area: Depression, Anxiety, Fibromyalgia, Neuropathic Pain End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Hospitals Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retail Pharmacies |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Sun Pharmaceutical Industries Ltd, Aurobindo Pharma, Lupin, Eli Lilly and Company, Zydus Cadila, Hetero, Apotex Inc., Shionogi Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duloxetine API Market Emerging Trajectories
Process intensification and regulatory science are converging to redefine competitive advantage in duloxetine API supply, with manufacturers racing to align quality infrastructure with diverging pharmacopeial standards while capturing efficiency gains from manufacturing technology shifts.
Continuous flow chemistry for chiral synthesis is fragmenting the traditional batch-reactor paradigm that has dominated duloxetine API production. Mid-scale contract manufacturers in Hyderabad and Ahmedabad are piloting microreactor systems that reduce solvent volumes and improve heat transfer control. This technology is fragmenting capital allocation patterns, as established batch operators face stranded asset risk while agile entrants capture efficiency premiums.
REACH framework substance registration requirements in Europe are tightening chemical substance documentation obligations for duloxetine API exporters. The ECHA's evolving guidance on persistent, bioaccumulative, and toxic substances is forcing reformulation of synthetic routes and waste handling protocols. API suppliers serving European generic sponsors are responding by investing in lifecycle assessment capabilities and green chemistry certifications to preempt supply disqualification.
Long-term supply agreements are displacing spot-market API purchases among North American generic finished dose manufacturers. Multinational sponsors now favor 3-5 year contracts with Indian contract manufacturers who demonstrate regulatory inspection history and dedicated capacity allocation. This behavioral shift is most pronounced among companies supplying the US market, where FDA establishment inspection records have become a primary vendor selection criterion alongside price competitiveness.
Duloxetine API Market Segmentation
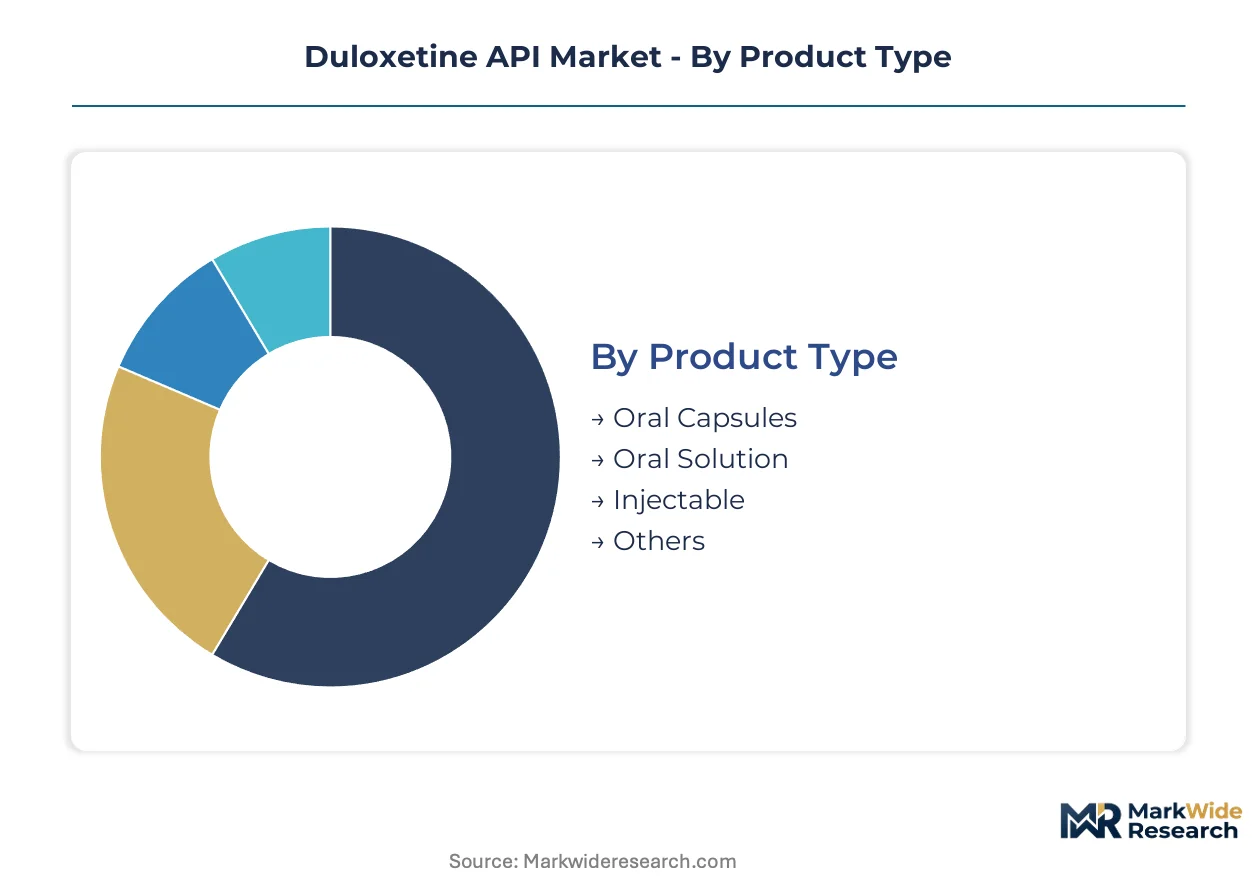
Duloxetine API demand fragments across formulation types, therapeutic applications, and procurement channels that each impose distinct quality specifications and regulatory burdens. Understanding these segment boundaries reveals where margin pools concentrate and which customer relationships lock in long-term volume.
Product Type:
Domestic consumption in regulated markets favors oral solid dosage forms, while export-led contract manufacturing increasingly supplies diverse delivery formats to emerging market sponsors.
- Oral Capsules:Hard gelatin capsules containing duloxetine hydrochloride pellets with enteric coating to protect against gastric degradation. Demand concentrates among North American generic sponsors seeking bioequivalence with reference listed drugs; FDA dissolution specification divergence between USP and IP monographs creates compliance complexity for multi-territory suppliers.
- Oral Solution:Liquid formulations with adjusted pH and stabilizing excipients for pediatric and geriatric populations with swallowing difficulties. European contract manufacturers in India are scaling capacity for this segment as EMA guidelines on excipient compatibility tighten; liquid stability testing extends development timelines.
- Injectable:Parenteral formulations requiring sterile manufacturing suites and endotoxin control below specified thresholds.
- Others:Orally disintegrating tablets and modified-release formulations in development pipelines.
Oral capsules hold the largest share; momentum sits with oral solution as pediatric labeling expansions proceed.
Therapy Area:
Psychiatric indications anchor volume consumption, while pain management applications are climbing the fastest as prescriber habits shift.
- Depression:Major depressive disorder represents the original approved indication with established reimbursement pathways. North American and European generic substitution rates exceed thresholds for psychiatric medications; prescriber familiarity sustains volume despite serotonin-specific reuptake inhibitor competition.
- Anxiety:Generalized anxiety disorder indication carries comparable dosing profiles to depression with slightly different clinical trial requirements. Contract manufacturers report steady procurement from sponsors targeting Medicare and Medicaid formularies where cost compression drives generic uptake.
- Fibromyalgia:Chronic pain syndrome with centralized sensitization mechanisms responsive to SNRI pharmacology.
- Neuropathic Pain:Diabetic peripheral neuropathy indication with specific pain scale endpoints in regulatory filings.
Depression commands the deepest volume base; fibromyalgia is expanding most quickly as off-label restrictions ease in select Latin American markets.
End User:
Procurement authority has migrated from innovator captives to specialized manufacturing intermediaries with regulatory inspection histories.
- Pharmaceutical Companies:Vertically integrated generic sponsors with in-house formulation capabilities and established FDA establishment files. Sun Pharmaceutical Industries and Teva Pharmaceutical Industries maintain captive API consumption for internal dosage form production; these players negotiate long-term supply agreements with Indian contract manufacturers for volume security.
- Contract Manufacturers:Third-party API converters serving multiple finished dose sponsors under toll manufacturing arrangements. Hyderabad and Ahmedabad clusters dominate this segment; CDSCO export certifications and WHO prequalification status determine vendor selection criteria for North American and European generic sponsors.
- Research Institutions:Academic and clinical trial material suppliers requiring small-batch GMP production.
- Hospitals:Direct procurement for institutional pharmacy compounding in select markets with regulatory exemptions.
Contract manufacturers absorb the dominant procurement share; pharmaceutical companies are regaining API integration momentum as margin compression intensifies.
Distribution Channel:
Channel structure reflects the regulatory intensity of destination markets, with direct relationships displacing intermediaries where compliance documentation requirements are most stringent.
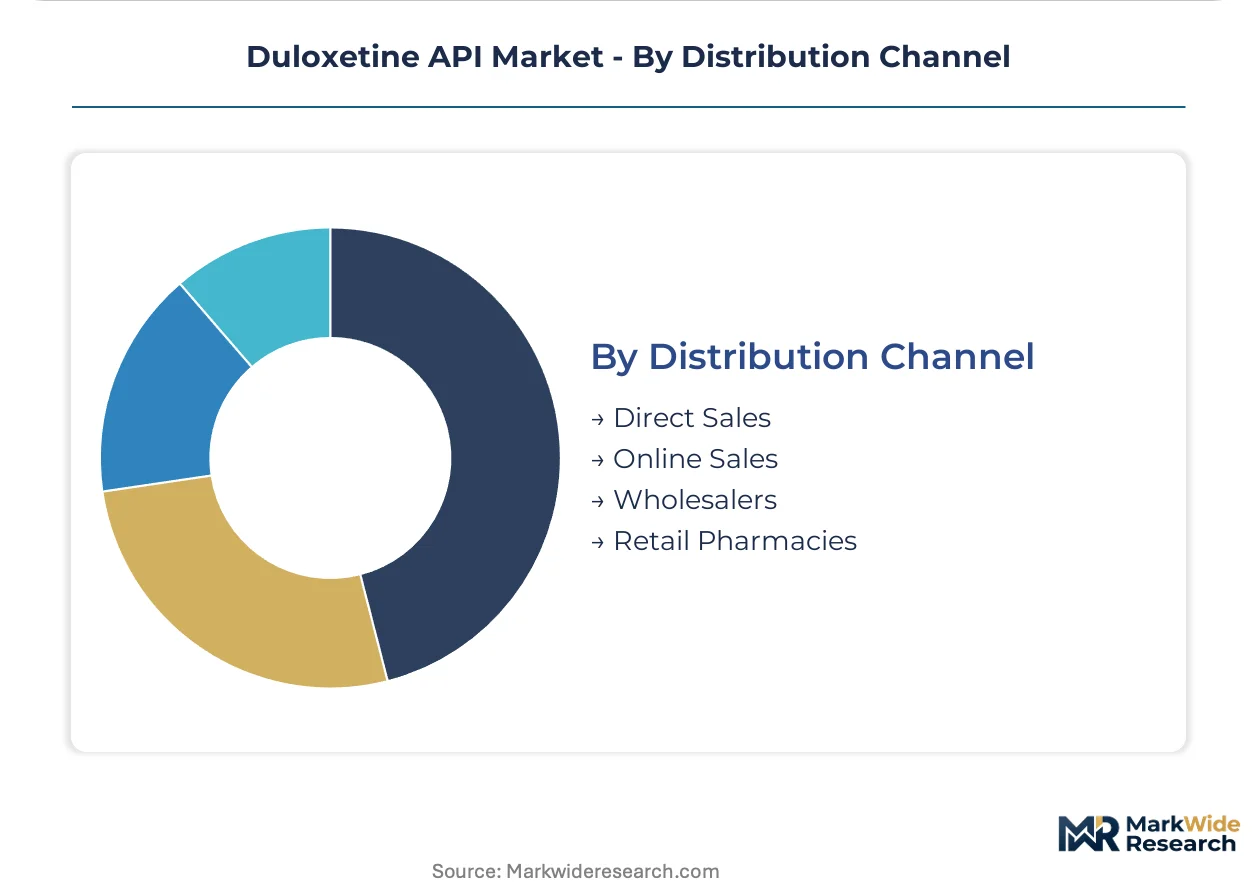
- Direct Sales:Manufacturer-to-sponsor transactions with dedicated account management and regulatory file support. North American generic sponsors favor this channel for duloxetine API to secure FDA establishment inspection records and dedicated capacity allocation; contract value typically spans three to five years with price adjustment clauses.
- Online Sales:Digital procurement platforms for standard catalog items with documented certificates of analysis. Indian API suppliers leverage this channel for research institution and smaller generic sponsor segments where transaction scale does not justify dedicated sales resources.
- Wholesalers:Inventory-carrying intermediaries with regional warehousing for time-sensitive replenishment.
- Retail Pharmacies:Limited to compounding pharmacy segments in markets with specific regulatory frameworks.
Direct sales capture the predominant value flow; online sales are gaining share fastest among mid-tier generic entrants with streamlined procurement processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports duloxetine API to North American and European generic drug sponsors under long-term supply agreements, with Hyderabad and Ahmedabad contract manufacturers serving as the primary procurement source for multinational finished dose producers.
United States
Generic substitution rates for psychiatric medications drive API procurement from Indian contract manufacturers. FDA establishment inspection records and ICH Q3D elemental impurity compliance serve as primary vendor selection criteria. New Jersey and North Carolina-based generic sponsors negotiate multi-year supply contracts with dedicated capacity allocation.
India
CDSCO export certifications and WHO prequalification status enable domestic API producers to serve regulated market demand. The PLI scheme for active pharmaceutical ingredients incentivizes capacity expansion in bulk drug manufacturing. Hyderabad and Ahmedabad clusters concentrate chiral synthesis capabilities for enantiomeric purity control.
Germany
EMA REACH framework substance registration requirements govern chemical documentation for duloxetine API imports. German generic sponsors prioritize suppliers with lifecycle assessment capabilities and green chemistry certifications. The Rhine-Ruhr pharmaceutical corridor channels API procurement toward certified Indian contract manufacturers.
United Kingdom
NHS cost compression drives generic duloxetine uptake and API demand from low-cost manufacturing jurisdictions. MHRA alignment with ICH quality guidelines maintains regulatory stringency for imported APIs. Southeast England-based generic sponsors source through direct manufacturer relationships rather than intermediaries.
Japan
PMDA quality standards for serotonin-norepinephrine reuptake inhibitors require rigorous nitrosamine risk assessment documentation. Japanese generic sponsors demonstrate conservative procurement patterns favoring established regulatory inspection histories. The Kanto region houses formulation facilities reliant on Indian API supply for cost-competitive generic production.
Duloxetine API Market Vendor Landscape
Player mix skews toward vertically integrated generic pharmaceutical sponsors and specialized contract manufacturers with regulatory inspection histories. Market structure concentrates procurement authority among Indian API producers serving North American and European finished dose sponsors. Two strategic archetypes dominate: integrated generic sponsors with captive formulation capabilities, and toll manufacturers scaling multi-sponsor production under long-term agreements. Capacity expansion and backward integration into API production represent the dominant competitive moves as margin compression intensifies.
Among Israel-based integrated generic sponsors, Teva Pharmaceutical Industries Ltd occupies a position exemplifying vertical control across formulation and active ingredient supply. Indian contract manufacturers Sun Pharmaceutical Industries Ltd and Aurobindo Pharma represent the specialized production archetype, anchoring export-oriented supply to regulated markets through CDSCO-certified facilities. These three entities collectively illustrate the bifurcation between captive integration and third-party toll manufacturing that defines competitive positioning in duloxetine API procurement.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Sun Pharmaceutical Industries Ltd |
| Aurobindo Pharma |
| Lupin |
| Eli Lilly and Company |
| Zydus Cadila |
| Hetero |
| Apotex Inc. |
| Shionogi Inc. |
| Others |
Supply Flow & Price Mechanics
FDA ICH Q3D elemental impurity certification gates both supplier qualification and price stratification in duloxetine API procurement, with certified manufacturers commanding premiums over uncertified competitors while buyers face compliance-driven vendor consolidation. This regulatory filter simultaneously restricts supply base breadth and segments pricing power across quality tiers.
Pricing Analysis
Batch-reactor versus continuous-flow manufacturing capabilities create a technology-generation pricing gap, with legacy batch operators facing margin compression against flow-chemistry entrants. Three-tier pricing structure across premium, standard, and economy levels separates FDA-inspected Indian contract manufacturers from CDSCO-certified regional suppliers and uncertified spot-market sources. Pricing pressure stems from long-term supply agreement standardization among North American generic sponsors. Research institutions and smaller emerging-market sponsors exhibit highest price sensitivity; vertically integrated pharmaceutical companies with captive formulation demand show lowest.
Supply Chain Analysis
Chiral auxiliary feedstock availability through Mumbai and Rotterdam port infrastructure constitutes a critical chokepoint for enantiomeric purity control. API production concentrates in India, China, and Israel, with naphthol derivatives, palladium catalysts, and enteric coating polymers anchoring input dependencies. Single-geography concentration in Hyderabad and Ahmedabad clusters exposes buyers to export policy volatility. Distribution runs through direct manufacturer-to-sponsor relationships with dedicated regulatory file support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward North American and European generic sponsors as procurement consolidates around long-term supply agreements with inspected Indian contract manufacturers. This concentration fragments pricing leverage among API suppliers.
For Market Incumbents: Consolidate regulatory inspection histories into dedicated capacity allocation agreements with multinational sponsors facing FDA establishment file renewal cycles. Deepen backward integration into naphthol derivative feedstocks to offset petrochemical price volatility. Capture margin defense through enantiomeric purity control technology licensing rather than volume commoditization. For New Entrants and Emerging Players: Differentiate on continuous-flow manufacturing yield advantages and reduced solvent waste profiles against incumbent batch-reactor operators. Target oral solution formulation capacity for European pediatric labeling expansions as the most penetrable segment. Pursue toll manufacturing arrangements with mid-tier generic sponsors lacking in-house API capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous-flow chemistry adoption as microreactor systems reduce fixed asset requirements. Five-to-ten year viability favors contract manufacturers with WHO prequalification status and established CDSCO export certifications. Monitor ECHA REACH substance registration timeline acceleration as inflection indicator for European supply disqualification risk.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Manufacturing Adoption | Microreactor pilot programs in Hyderabad reduce solvent volumes and improve heat transfer control. |
| Backward Integration into Feedstocks | Naphthol derivative captive supply buffers margin compression from petrochemical cycle volatility. |
| Multi-Pharmacopeia Certification Investment | Simultaneous USP, EP, and IP compliance extends vendor qualification timelines for multinational sponsors. |
| Long-term Supply Agreement Structuring | Three-to-five year contracts with price adjustment clauses lock in capacity allocation with inspected manufacturers. |
| Green Chemistry Certification Program | ECHA lifecycle assessment capabilities preempt REACH framework supply disqualification for European sponsors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA establishment inspection records, EMA REACH substance registration databases, CDSCO export certification filings, and WHO prequalification status reports. Interviews with regulatory affairs leads at contract manufacturers, procurement directors at North American generic sponsors, and analytical chemistry method development specialists informed supply-side and demand-side dynamics. Bottom-up volume estimates from API production capacity triangulate against top-down prescription volume data and generic substitution rate assumptions.
Segmentation dimensions modeled include formulation type, therapy area, end-user procurement channel, and regional regulatory cluster across the analysis window. CAGRs derive from regression analysis of historical API procurement volumes against patent expiration timelines and prescriber base expansion indicators. Forecast inputs incorporate chiral synthesis yield improvement trajectories and nitrosamine risk assessment protocol adoption curves.
Material uncertainties — regulatory inspection backlog delays, export policy shifts in India, and pharmacopeial monograph divergence — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued generic sponsor consolidation and sustained FDA ICH Q3D enforcement stringency. Practitioners should keep alternative scenarios live as REACH framework substance registration requirements and continuous-flow manufacturing adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Pharmaceutical Hot Melt Extrusion Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Piperacillin Sodium API Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market