
 Europe Plastic Caps and Closures Market | 2026-2036
Europe Plastic Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Plastic Caps and Closures Market Foresight
Multi-source procurement toward regional molders is rebalancing supply relationships across European beverage and pharmaceutical packaging networks. BERICAP GmbH and Co. KG leverages its German manufacturing base to dominate technical closure development for carbonated drinks. UNITED CAPS Luxembourg S.A. anchors premium dispensing solutions for cosmetics brands seeking differentiated user experiences. Silgan Holdings Inc. competes through scale advantages in mass-market food closures across southern Europe.
Europe plastic caps and closures are injection-molded or compression-molded thermoplastic components, typically manufactured from polypropylene or polyethylene with thread geometries precision-engineered to ISO 8317 and DIN standards, serving primarily to seal, dispense, and protect container contents across liquid and semi-solid product categories. Screw caps sustain the largest volume position due to universal compatibility with glass and PET bottles across beverage and food applications. Child-resistant caps represent the fastest-growing closure design segment as pharmaceutical packaging regulations tighten across EU member states. Polypropylene occupies the dominant material position for hot-fill and carbonated applications where thermal stability and creep resistance prove critical.
The EU Single-Use Plastics Directive, REACH chemical compliance frameworks, and EFSA food-contact material approvals collectively determine permissible resin grades, recycling content thresholds, and migration limits across European closure manufacturing. ECHA substance restrictions on intentional microplastics additives are forcing reformulation of certain slip agents and colorants used in cap production. Stakeholders must monitor pending Packaging and Packaging Waste Regulation revisions that will mandate minimum recycled content percentages and harmonize extended producer responsibility schemes across member states.
Market Dynamics
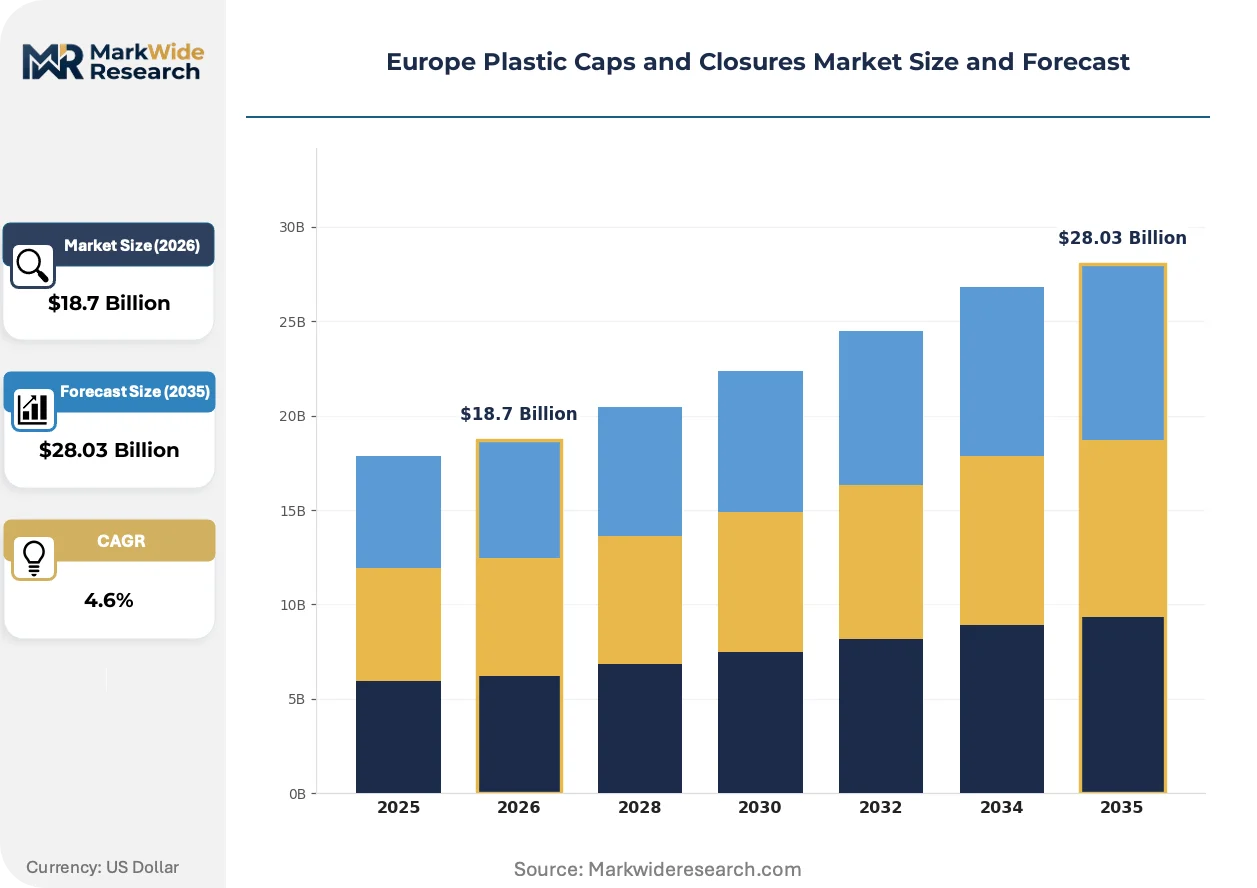
The EU Single-Use Plastics Directive and pending Packaging and Packaging Waste Regulation revisions are forcing resin reformulation and recycled content integration across European closure manufacturing networks.
Growth Catalysts
- REACH chemical compliance frameworks:Standardized migration limits and substance approvals are harmonizing cross-border trade in food-contact closures, reducing regulatory fragmentation for molders operating across Germany, France, and Italy.
- Pharmaceutical packaging regulations:Child-resistant closure mandates under ISO 8317 are accelerating technical specification upgrades across northern Italy's pharmaceutical hub and Rhineland medical packaging corridors.
- rPET integration:Brand-owner commitments to recycled content targets are pulling demand for compatible closure resins and color-matching technologies in beverage packaging lines.
Market Restraints
- Propylene feedstock volatility:Polypropylene price swings tied to naphtha cracking economics compress margin predictability for injection molders serving carbonated beverage accounts.
- German mold-making concentration:Technical closure tooling supply clusters heavily in Baden-Württemberg and Bavaria, creating single-source vulnerability for precision thread geometries.
- Aluminum substitution:Crown corks and screw caps in wine and craft spirits segments retain preference among premium positioning strategies, capping plastic penetration in alcoholic beverages.
Strategic Opportunities
- Poland and Czech Republic manufacturing expansion:Labor cost differentials and proximity to German beverage markets are attracting secondary molding capacity for mass-market food closures.
- Connected dispensing closures:NFC-enabled tamper-evident systems for cosmetics and pharmaceuticals converge electronics miniaturization with precision molding expertise concentrated in Luxembourg and Switzerland.
- Extended Producer Responsibility harmonization:Pending EU-wide EPR scheme alignment creates first-mover advantage for molders with integrated recycling partnerships and design-for-recycling capabilities.
Industry Challenges
- Tooling engineer scarcity:Multi-cavity hot-runner mold design expertise is concentrating among retiring specialists in Germany's precision engineering belt, constraining capacity expansion timelines.
- EFSA food-contact renewal cycles:Additive and pigment approvals face extended safety evaluation queues, delaying color-matched closure launches for seasonal beverage promotions.
- Legacy press integration:Compression molding equipment retrofits for lightweighting requirements demand capital outlays that mid-tier Italian molders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Plastic Caps and Closures Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screw Caps, Snap-On Caps, Dispensing Caps, Child-Resistant Caps Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Beverage Industry, Pharmaceutical Sector, Food Industry, Cosmetics Sector Closure Design: Standard Caps, Customized Caps, Tamper-Evident Caps, Easy-Open Caps |
| Companies Covered | ALPLA Werke Alwin Lehner GmbH and Co KG, Silgan Holdings Inc., Amcor plc, UNITED CAPS Luxembourg S.A., AptarGroup Inc., BERICAP GmbH and Co. KG, Berry Global Group Inc., Zeller Plastik Group, Guala Closures Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Plastic Caps and Closures Market Shifts & Advancements
Material science breakthroughs and regulatory compression are simultaneously enabling lightweighting advances and complicating compliance architectures across European closure manufacturing.
Digital thread measurement and real-time cavity pressure monitoring is decentralizing quality assurance from centralized metrology labs to production floor inline systems. Mid-sized beverage bottlers in Spain and Portugal are adopting these sensor-integrated molds faster than pharmaceutical accounts due to lower validation burdens. The shift is compressing defect detection cycles from hours to seconds while reducing scrap rates and energy-intensive reprocessing.
REACH restrictions on intentional microplastics additives are forcing reformulation of slip agents and processing aids used in high-speed capping lines. ECHA substance evaluations are eliminating certain erucamide and silicone-based lubricants from approved food-contact lists, compelling compounders to qualify bio-based alternatives. Pharmaceutical and cosmetics closure segments face the steepest retesting timelines due to stricter migration limit documentation requirements.
Beverage brand owners are consolidating supplier panels from twelve-plus regional molders to three-to-four strategic partners with pan-European quality certifications. This concentration pattern is most visible in Germany's private-label retail channel, where Aldi and Lidl procurement teams demand single-source accountability across multiple production sites. The restructuring is marginalizing smaller Italian and Portuguese molders lacking ISO 22000 and BRC packaging certifications.
Europe Plastic Caps and Closures Market Segmentation
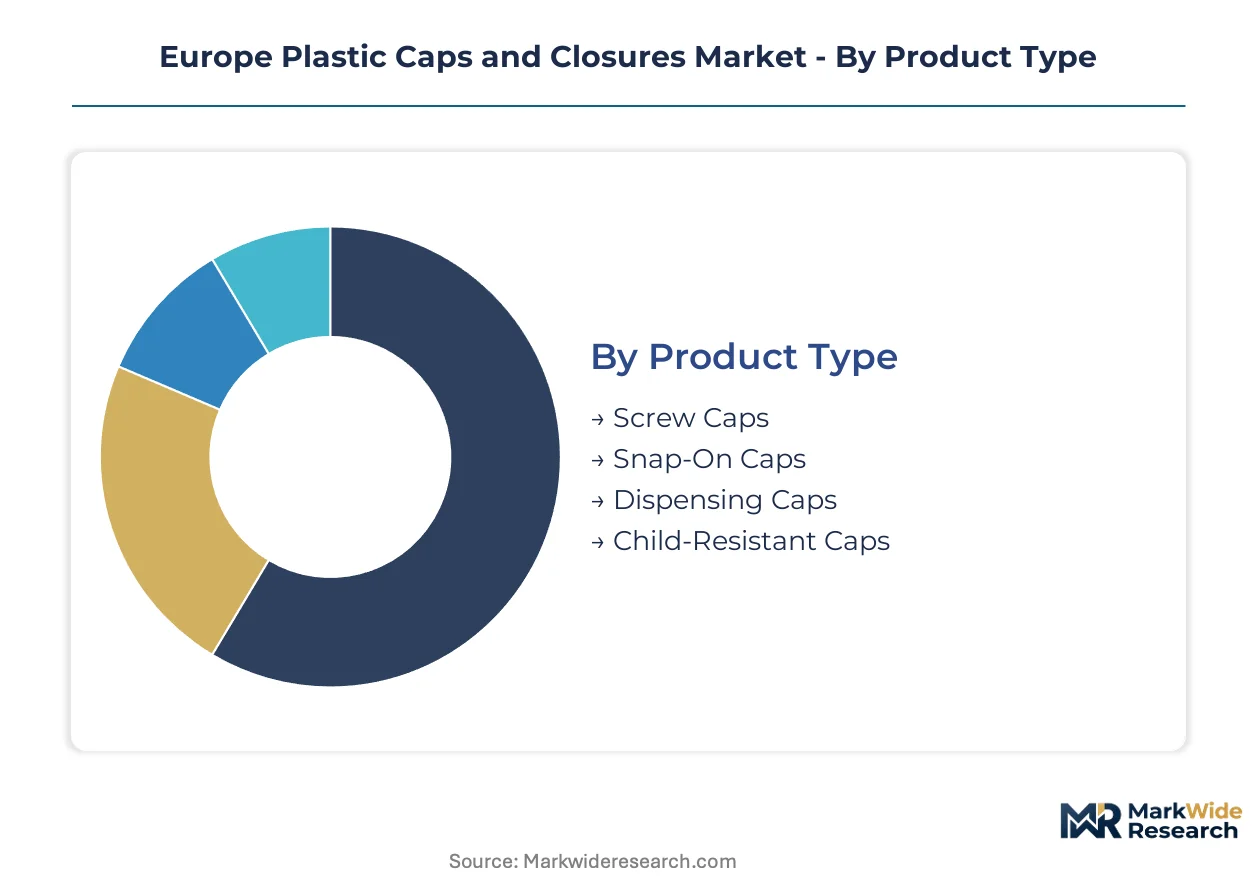
Segmentation in Europe's plastic caps and closures market reveals how technical specifications, regulatory compliance, and end-use performance requirements fragment manufacturing capabilities across distinct supplier tiers. Understanding these divisions exposes where molders can defend margin through specialization versus where scale economies dominate procurement decisions.
Product Type:
Standardization pressure from German beverage bottlers sits opposite the customization demands of pharmaceutical and cosmetics accounts across this product spectrum.
- Screw Caps:Thread geometries precision-machined to DIN and ISO 8317 standards ensure hermetic sealing across glass and PET bottle formats. Demand concentrates in Germany's Rhineland packaging cluster where carbonated beverage lines require creep-resistant polypropylene formulations for pressurized contents. REACH compliance on food-contact substances constrains lubricant selection in high-speed capping operations.
- Child-Resistant Caps:Push-and-turn or squeeze-and-turn mechanisms engineered to ISO 8317 child-safety protocols demand multi-component molding expertise. Northern Italy's pharmaceutical hub drives specification intensity as EMA packaging guidelines tighten pediatric poisoning prevention mandates. Tooling complexity limits viable supplier pools to molders with hot-runner multi-cavity capability.
- Snap-On Caps:Single-piece polyethylene designs serve mass-market food jars where cost minimization overrides dispensing sophistication.
- Dispensing Caps:Flip-top and directional pour geometries dominate cosmetics and personal care lines in France and Switzerland.
Leading the category by volume: Screw Caps. Growing fastest: Child-Resistant Caps.
Material:
Resin selection maps directly to thermal performance requirements and recycling stream compatibility across EU regulatory frameworks.
- Polypropylene:Semi-crystalline thermoplastic with superior hot-fill tolerance and carbonation pressure resistance anchors beverage closure production. Germany's mineral water and soft drink bottlers specify homopolymer grades for creep resistance under sustained load. EFSA food-contact approvals and rPET integration mandates are pulling compounders toward nucleated grades with faster cycle times.
- Polyethylene:LDPE and HDPE variants dominate snap-on food closures where flexibility and stress-crack resistance matter more than thermal ceiling. Southern European molders favor PE for cost-sensitive condiment and sauce applications. ECHA microplastics restrictions are forcing reformulation of slip agents in high-speed line applications.
- Polystyrene:Crystal and high-impact grades serve cosmetics dispensing where clarity and surface aesthetics command premium positioning.
- Polyvinyl Chloride:Specialized phthalate-free formulations persist in pharmaceutical blister lidding and certain tamper-evident bands despite sustainability headwinds.
Dominant by tonnage: Polypropylene. Expanding most quickly: Polyethylene as rPE qualification accelerates.
End User:
Customer procurement sophistication diverges sharply between consolidated beverage retail channels and fragmented pharmaceutical specification processes.
- Beverage Industry:Carbonated soft drinks, bottled water, and juice segments drive highest closure volumes with relentless lightweighting pressure. German discount retailers Aldi and Lidl consolidate supplier panels to three-to-four strategic partners demanding pan-European quality certification. rPET content mandates under EU Single-Use Plastics Directive are forcing resin color-matching investments.
- Pharmaceutical Sector:Prescription and over-the-counter packaging demands child-resistant and senior-friendly dual-functionality under ISO 8317 and EU MDR requirements. Northern Italy's Piacenza and Bologna corridors concentrate technical molding expertise for migration-controlled applications. EMA guidelines on extractables and leachables extend validation timelines for new closure launches.
- Food Industry:Condiment, sauce, and dairy applications favor cost-optimized snap-on designs with basic tamper-evidence.
- Cosmetics Sector:Premium dispensing solutions from Luxembourg and Swiss molders serve L'Oréal and Estée Lauder accounts seeking differentiated user experiences.
Highest volume concentration: Beverage Industry. Steepest specification upgrade: Pharmaceutical Sector.
Closure Design:
Design complexity stratifies supplier capabilities from commodity molders to precision engineering specialists.
- Standard Caps:Single-cavity compression-molded designs with basic thread geometries serve private-label retail channels where procurement prioritizes unit cost over innovation. Spanish and Portuguese molders compete aggressively on price for these specifications. BRC and ISO 22000 certifications are becoming minimum table stakes.
- Tamper-Evident Caps:Break-band or shrink-sleeve integrated designs protect product integrity across pharmaceutical and premium food segments. Real-time cavity pressure monitoring and digital thread measurement are migrating quality assurance from metrology labs to production floors. Sensor-integrated molds compress defect detection cycles from hours to seconds.
- Customized Caps:Brand-owner specific geometries and surface finishes command tooling investments that marginalize smaller molders.
- Easy-Open Caps:Senior-friendly torque reduction features serve aging demographics in pharmaceutical and food applications.
Widest deployment: Standard Caps. Gaining share fastest: Tamper-Evident Caps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for plastic caps and closures concentrates in Germany's Rhineland packaging corridor and northern Italy's pharmaceutical belt, with secondary growth nodes emerging in Poland and the Czech Republic as cost-optimized manufacturing expands eastward.
Germany
Carbonated beverage bottlers and discount retail chains drive closure specification intensity across the Rhineland and Bavaria. REACH chemical compliance frameworks and EFSA food-contact material approvals constrain resin formulation choices for high-speed capping lines. Baden-Württemberg's precision mold-making cluster supplies multi-cavity hot-runner tooling to beverage accounts demanding DIN-standard thread geometries.
Italy
Pharmaceutical packaging regulations under EMA guidelines accelerate child-resistant closure adoption across Piacenza and Bologna corridors. ISO 8317 compliance mandates and extractables-leachables documentation requirements extend validation timelines for new product launches. Northern Italy's technical molding hub concentrates expertise in migration-controlled applications for prescription and over-the-counter segments.
France
Premium cosmetics brands and personal care formulators pull demand for differentiated dispensing solutions from Paris and Lyon-based procurement teams. EU Single-Use Plastics Directive recycled content thresholds reshape material specifications for mass-market beverage accounts. The country's packaging innovation clusters near Strasbourg and Lille develop color-matching technologies for rPET-compatible closures.
Poland
Labor cost differentials and proximity to German beverage markets attract secondary molding capacity for standard food closures. Extended producer responsibility scheme preparations under pending EU Packaging and Packaging Waste Regulation revisions incentivize recycling partnership investments. Warsaw and Łódź industrial zones host expanding injection molding operations serving pan-European retail channels.
Switzerland
Precision engineering capabilities and pharmaceutical packaging expertise position Swiss molders for connected closure development integrating NFC-enabled tamper-evidence. Swissmedic regulatory alignment with EU MDR requirements streamlines cross-border pharmaceutical supply chains. Geneva and Basel corridors concentrate electronics miniaturization competencies converging with precision thermoplastic molding.
Europe Plastic Caps and Closures Market Competitive Landscape
Capacity expansion dominates the current landscape as molders retrofit compression equipment for lightweighting requirements and establish satellite facilities in Central European cost corridors. The supplier base stratifies into three tiers: pan-European strategic partners with integrated recycling capabilities, regional specialists in pharmaceutical or cosmetics niches, and price-competitive commodity molders serving private-label retail. M&A activity and geographic diversification represent the primary competitive vectors as procurement consolidation reduces viable supplier pools.
Among Germany-based fabricators, BERICAP GmbH and Co. KG and ALPLA Werke Alwin Lehner GmbH and Co KG exemplify scale-driven archetypes with Rhineland manufacturing footprints. UNITED CAPS Luxembourg S.A. occupies a position within the premium dispensing tier, representing specialization in differentiated user experience solutions for cosmetics and personal care segments.
| Leading Market Players |
|---|
| ALPLA Werke Alwin Lehner GmbH and Co KG |
| Silgan Holdings Inc. |
| Amcor plc |
| UNITED CAPS Luxembourg S.A. |
| AptarGroup Inc. |
| BERICAP GmbH and Co. KG |
| Berry Global Group Inc. |
| Zeller Plastik Group |
| Guala Closures Group |
| Others |
Supply & Pricing Matrix
German discount retailer consolidation toward three-to-four strategic partners per category forces secondary molders to absorb tooling amortization across longer contract horizons, compressing margin buffers for mid-tier suppliers lacking pan-European certification scale. This procurement concentration shifts pricing power toward beverage brand owners while fragmenting residual demand among price-competitive Portuguese and Spanish molders serving private-label accounts.
Pricing Analysis
High-volume beverage closures trade on razor-thin unit economics while pharmaceutical and cosmetics dispensing commands three-to-fivefold premiums for migration-controlled, multi-component designs. Three-tier pricing structure across premium, standard, and economy levels separates ISO 22000-certified strategic partners from BRC-compliant regional suppliers and uncertified commodity molders. Pricing pressure stems from propylene feedstock volatility tied to naphtha cracking spreads, forcing compounders to index contracts quarterly. Private-label retail channels exhibit highest price sensitivity, while pharmaceutical accounts prioritize validation reliability over unit cost.
Supply Chain Analysis
Precision mold-making expertise rests on Baden-Württemberg and Bavaria engineering clusters, with secondary injection capacity expanding into Poland and the Czech Republic. Polypropylene resin draws from northwest European petrochemical complexes, while colorant and additive supply hinges on Swiss and German specialty chemical producers. Single-source vulnerability concentrates in multi-cavity hot-runner tooling, where retiring German specialists constrain capacity expansion timelines. Distribution runs through pan-European logistics hubs serving consolidated beverage bottlers, with just-in-time delivery mandates compressing inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over rPET-compatible resin formulation and closed-loop recycling partnerships determines long-term procurement viability. Players securing backward integration into compounder networks or forward integration into brand-owner sustainability programs capture durable positioning.
For Market Incumbents: To counter procurement consolidation by Aldi and Lidl buying desks, BERICAP-class molders should deepen captive supply of nucleated polypropylene grades and secure EFSA pre-approvals for seasonal color launches. Anchor capacity expansion in Poland to capture labor arbitrage while maintaining German precision-tooling partnerships for pharmaceutical-grade specifications. For New Entrants and Emerging Players: Enter via Poland and Czech Republic manufacturing corridors serving mass-market food closures, where ISO 22000 certification gaps among incumbent Spanish molders create procurement openings. Target uncertified Italian mid-tiers losing private-label beverage accounts through BRC compliance failures. Lead with rPET color-matching capabilities as Aldi and Lidl enforce recycled content mandates. For Investors and Strategic Acquirers: The window for entry favors compounders with EFSA-approved additive portfolios and molders with integrated recycling partnerships ahead of EU Packaging and Packaging Waste Regulation harmonization. Watch for EPR scheme implementation timelines as the inflection signal determining which integrated players secure first-mover advantage in extended producer responsibility networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of rPET-compatible grades locks in Aldi and Lidl procurement panels ahead of recycled content mandates. |
| Poland Manufacturing Footprint Expansion | Labor cost differentials and German market proximity attract secondary capacity for mass-market food closures. |
| EFSA Pre-Approval Investment | Accelerated additive qualification timelines defend seasonal beverage launch schedules against compounder bottlenecks. |
| Closed-Loop Recycling Partnership | Design-for-recycling capabilities align with pending EU EPR harmonization and brand-owner sustainability commitments. |
| Hot-Runner Multi-Cavity Tooling Acquisition | Precision mold-making scarcity in Germany's engineering belt creates defensive moat for pharmaceutical-grade specifications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with procurement directors at German beverage bottlers, technical tooling engineers in Baden-Württemberg, and EMA regulatory affairs specialists. Cefic plastics industry reports, ECHA substance restriction databases, and SEC disclosures from listed packaging groups provided demand-side validation. Bottom-up capacity assessments across Rhineland and northern Italian molding clusters triangulated against top-down procurement spend estimates from pan-European retail channels.
Segment-level modeling tracked closure type, material grade, end-use industry, and regional manufacturing hub across the projection horizon. CAGRs derived from elasticity-adjusted volume projections responding to rPET integration timelines and EPR scheme implementation pacing. Pharmaceutical packaging growth incorporated EMA guideline revision schedules and ISO 8317 compliance upgrade cycles. Beverage segment forecasts weighted Aldi and Lidl supplier panel consolidation rates against lightweighting technical limits.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene feedstock disruption or accelerated EU Single-Use Plastics Directive enforcement. Assumptions reflect current EFSA approval queue durations and German mold-making engineer retirement trajectories. A small set of named triggers—EPR harmonization votes, REACH microplastics restriction finalization, and major retailer recycled content deadline acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Flip Top Caps and Closures Market
Caps and Closures
Cork Stoppers Market
Caps and Closures
Spain Plastic Cap and Closure Market
Caps and Closures
Bag Closure Clips Market
Caps and Closures
Lug Caps Market
Caps and Closures
Shrink Bands Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Dropper Caps Market
Caps and Closures
Global Aluminum Caps for Packaging Market
Caps and Closures
Latin America Plastic Caps and Closure Market
Caps and Closures
Molded Fiber Pulp Cap Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Metal Caps and Closures Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
Bar Top Corks Market