
 Metabolomics Market | 2026-2036
Metabolomics Market Size, Share, and Industry Trends Forecast 2026-2036
Metabolomics Market Intelligence
Platform licensing revenue is tilting toward integrated software-analytics bundles as instrument vendors seek recurring income streams. Thermo Fisher Scientific leverages its Orbitrap installed base to anchor cloud-based metabolomics data services. Bruker Corporation specializes in high-resolution mass spectrometry platforms that dominate academic core facility procurement cycles. Agilent Technologies extends its chromatography-mass spec workflow dominance into metabolomics through method standardization and cross-platform compatibility.
Metabolomics is the large-scale study of small-molecule metabolites within cells, biofluids, tissues, or organisms, typically detected through mass spectrometry platforms achieving resolution below 5 ppm mass accuracy and NMR spectroscopy operating at 600-900 MHz field strengths, serving applications from disease biomarker identification to metabolic pathway elucidation. Mass spectrometry commands the largest installed base and service revenue pool, while NMR spectroscopy retains structural elucidation advantages for complex metabolite identification. Services represent the fastest-expanding product category as pharmaceutical companies outsource bioinformatics and pathway interpretation rather than building in-house expertise.
FDA biomarker qualification programs and EMA's qualification opinion pathways shape clinical metabolomics demand by establishing evidentiary standards for regulatory acceptance of metabolic signatures. ISO 17025 accreditation requirements and CLIA laboratory certification constrain market entry for clinical service providers while reinforcing quality differentiation among established players. Stakeholders must monitor evolving regulatory frameworks for multi-omics integration in drug approval dossiers to anticipate capability investments and partnership structures.
Market Dynamics
Integrated software-analytics bundles are restructuring revenue models as instrument vendors pivot from hardware sales toward recurring service contracts, compressing traditional platform licensing economics and forcing capability consolidation across the vendor base.
Growth Catalysts
- FDA Biomarker Qualification Programs:Regulatory pathways for metabolic signature acceptance in drug approval dossiers are accelerating clinical translation demand from pharmaceutical sponsors.
- Precision Medicine Infrastructure:Research clusters in the United States, Germany, and Japan are concentrating funding for multi-omics integration, pulling metabolomics into standard biomarker discovery workflows.
- Cloud-Based Data Services:Vendors with established mass spectrometry installed bases are anchoring subscription revenue through remote bioinformatics and pathway interpretation tools.
Market Restraints
- High-Resolution Instrument Costs:Orbitrap and 900 MHz NMR platforms require capital outlays that constrain core facility procurement cycles at mid-tier academic institutions.
- ISO 17025 Accreditation Barriers:Clinical service providers face multi-year certification timelines and audit costs that reinforce quality differentiation among established players.
- Mass Spectrometry Supply Concentration:Critical ion source and detector components concentrate among specialized German and Japanese component suppliers, exposing procurement to geographic disruption.
Strategic Opportunities
- Underpenetrated Clinical Diagnostics:Japan's PMDA pathway for companion diagnostic metabolite panels remains sparsely populated relative to genomic biomarkers, creating first-mover positioning.
- AI-Accelerated Pathway Elucidation:Machine learning integration with mass spectrometry data streams is compressing interpretation timelines for complex metabolic networks.
- EMA Qualification Opinion Tailwinds:European pharmaceutical sponsors are pre-subscribing metabolic signatures for regulatory acceptance ahead of pivotal trial initiation.
Industry Challenges
- Bioinformatics Talent Scarcity:Pathway interpretation and multi-omics data integration require specialized computational biology expertise that outpaces academic training pipeline output.
- Cross-Platform Standardization Delays:Method transfer between Thermo Fisher, Bruker, and Agilent workflows creates reproducibility friction in multi-site clinical studies.
- CLIA Laboratory Certification Timelines:Clinical service expansion faces 18-24 month state-level laboratory accreditation processes that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metabolomics Market |
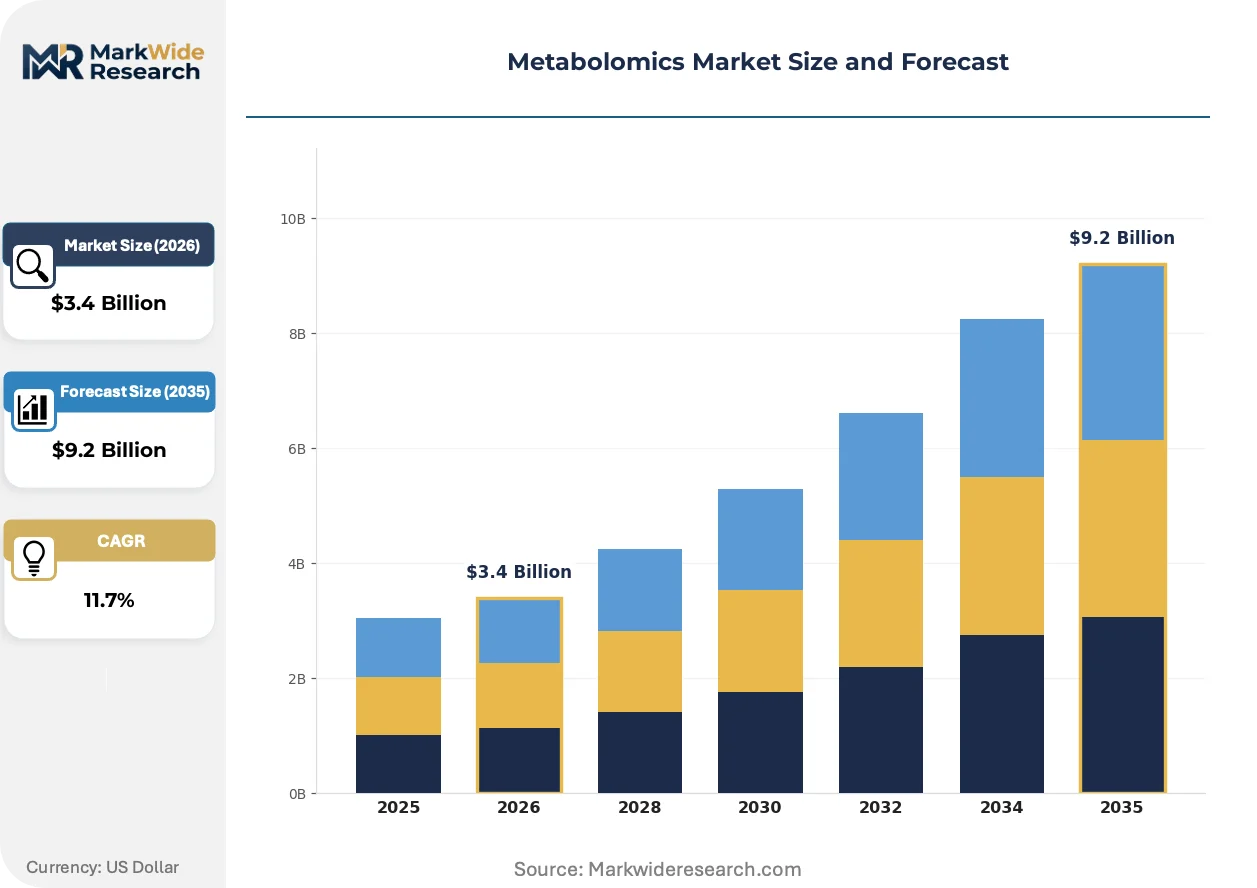
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.2 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Services Application: Biomarker Discovery, Drug Development, Personalized Medicine, Nutritional Analysis Technology: Mass Spectrometry, NMR Spectroscopy, Chromatography, Electrophoresis End User: Pharmaceutical Companies, Research Institutions, Hospitals, Academic Organizations |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, Bruker Corporation, Waters Corporation, Shimadzu Corporation, Metabolon, Human Metabolome Technologies, Danaher Corporation, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metabolomics Market Strategic Shifts & Innovations
Cloud-native metabolomics platforms are collapsing the traditional boundary between instrument control software and downstream analytics, enabling real-time pathway interpretation that restructures how pharmaceutical sponsors manage biomarker discovery workflows.
High-resolution mass spectrometry is collapsing the gap between untargeted profiling and quantitative validation, allowing pharmaceutical toxicology groups to retire separate triple-quadrupole confirmation workflows. Early adopters in large-cap sponsor organizations are compressing 12-month metabolite identification timelines into 6-week cycles. This acceleration is collapsing the economic justification for maintaining discrete discovery and development metabolomics teams.
EMA's qualification opinion pathway for novel methodologies is tightening evidentiary standards for metabolic signature submission in marketing authorization applications. Sponsors must now pre-specify analytical validation criteria before pivotal trial initiation, raising the bar for clinical metabolomics service providers. German and Swiss pharmaceutical clusters are responding by embedding metabolomics scientists directly into regulatory strategy functions.
Pharmaceutical procurement patterns are fragmenting as sponsors unbundle instrument purchase from multi-year service contracts. Biotech buyers increasingly favor pay-per-sample arrangements with ISO 17025-accredited clinical laboratories over captive analytical infrastructure. This shift concentrates contract volume among providers with demonstrated FDA biomarker qualification experience, particularly visible in Boston and San Diego biotech corridors.
Metabolomics Market Segmentation
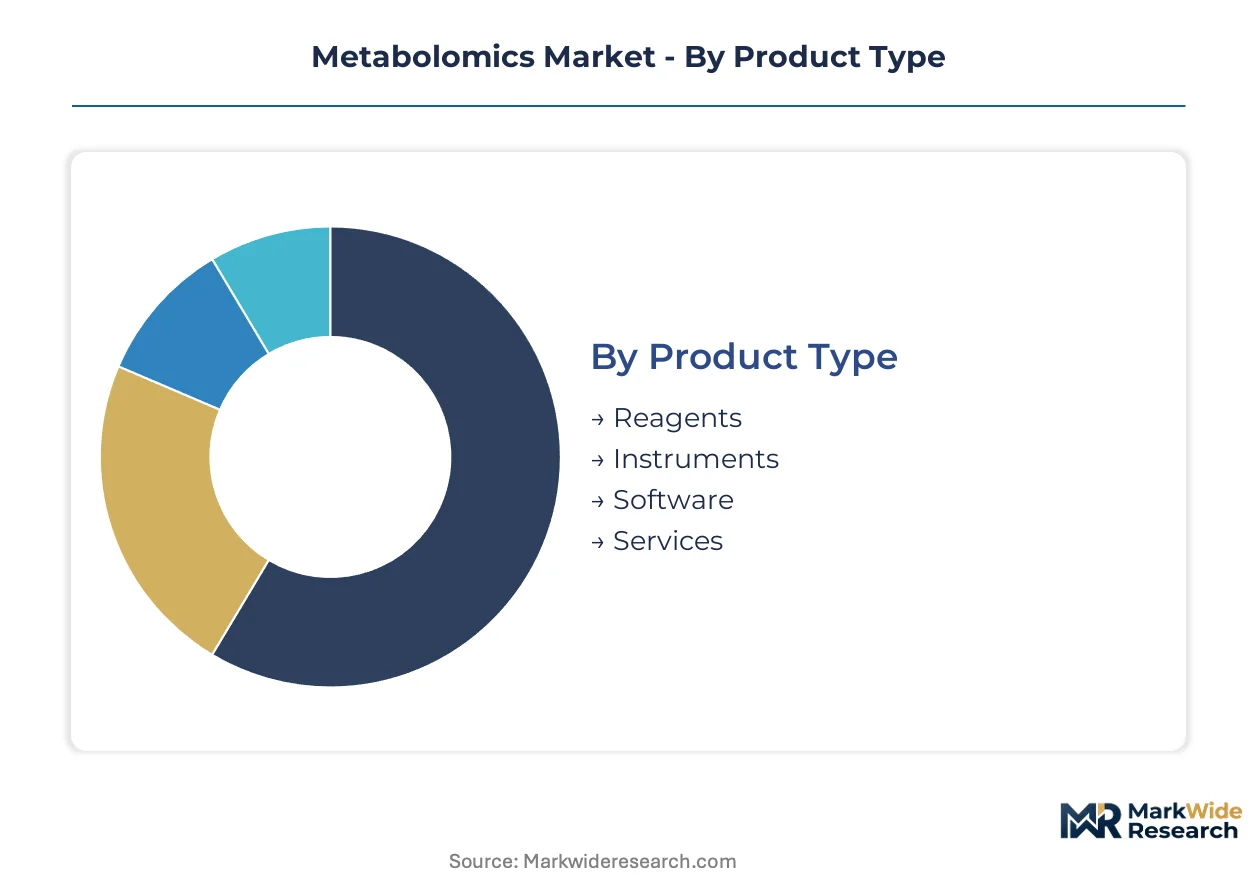
Segmentation in metabolomics reveals how technology maturity, regulatory pathways, and end-user procurement power reshape revenue allocation across hardware, consumables, and service layers. Understanding these divides exposes where vendor consolidation accelerates and where specialized providers retain pricing leverage.
Product Type:
Mature hardware segments face margin compression while emerging service bundles capture recurring revenue streams.
- Reagents:Chromatography columns, derivatization kits, and stable-isotope standards constitute the consumables backbone with 6-12 month replacement cycles. Pharmaceutical toxicology groups in the United States and Germany drive demand for certified reference materials that satisfy FDA biomarker qualification evidentiary requirements.
- Instruments:High-resolution mass spectrometry platforms achieving sub-5 ppm mass accuracy dominate capital expenditure allocation. Academic core facilities in Japan and Germany concentrate procurement of Orbitrap and 900 MHz NMR systems despite capital constraints at mid-tier institutions.
- Software:Cloud-native analytics platforms integrate instrument control with pathway interpretation tools. Vendors anchor subscription revenue through remote bioinformatics services that collapse traditional licensing economics.
- Services:ISO 17025-accredited clinical laboratories handle bioinformatics outsourcing and regulatory submission support. Biotech sponsors in Boston and San Diego corridors favor pay-per-sample arrangements over captive analytical infrastructure.
Instruments retain volume leadership; services hold the steepest expansion curve.
Application:
Cost tier stratification separates high-investment pharmaceutical pipelines from lower-budget nutritional screening programs.
- Biomarker Discovery:Untargeted metabolite profiling identifies disease-associated metabolic signatures for subsequent qualification. EMA's qualification opinion pathway tightens evidentiary standards, forcing sponsors to pre-specify validation criteria before pivotal trials.
- Drug Development:Metabolomics integrates into toxicology and pharmacokinetic workflows to characterize drug-induced metabolic perturbations. Large-cap pharmaceutical organizations compress 12-month metabolite identification timelines into 6-week cycles using high-resolution mass spectrometry.
- Personalized Medicine:Patient stratification based on metabolic phenotypes guides therapeutic selection. Japan's PMDA pathway for companion diagnostic metabolite panels remains sparsely populated relative to genomic biomarkers.
- Nutritional Analysis:Metabolic profiling assesses dietary intervention effects on human metabolism. Research institutions deploy lower-cost chromatography workflows for population-scale cohort studies.
Drug development commands the largest budget allocation; personalized medicine is gaining share fastest.
Technology:
Supply concentration among German and Japanese component suppliers shapes procurement risk profiles across detection platforms.
- Mass Spectrometry:Orbitrap and triple-quadrupole platforms achieve resolution below 5 ppm for quantitative metabolite identification. The installed base concentrates in pharmaceutical companies and academic core facilities across the United States, Germany, and Japan.
- NMR Spectroscopy:600-900 MHz field strength systems retain structural elucidation advantages for complex metabolite identification. Bruker Corporation dominates academic procurement cycles where non-destructive analysis requirements persist.
- Chromatography:Liquid and gas chromatography separations precede mass spectrometry detection in most analytical workflows. Agilent Technologies extends method standardization across multi-site clinical studies.
- Electrophoresis:Capillary electrophoresis separates charged metabolites with high efficiency for specific compound classes. Niche applications in amino acid profiling sustain limited demand.
Mass spectrometry anchors the installed base; NMR spectroscopy defends structural analysis niches.
End User:
Customer type fragmentation splits between centralized pharmaceutical procurement and distributed academic purchasing authority.
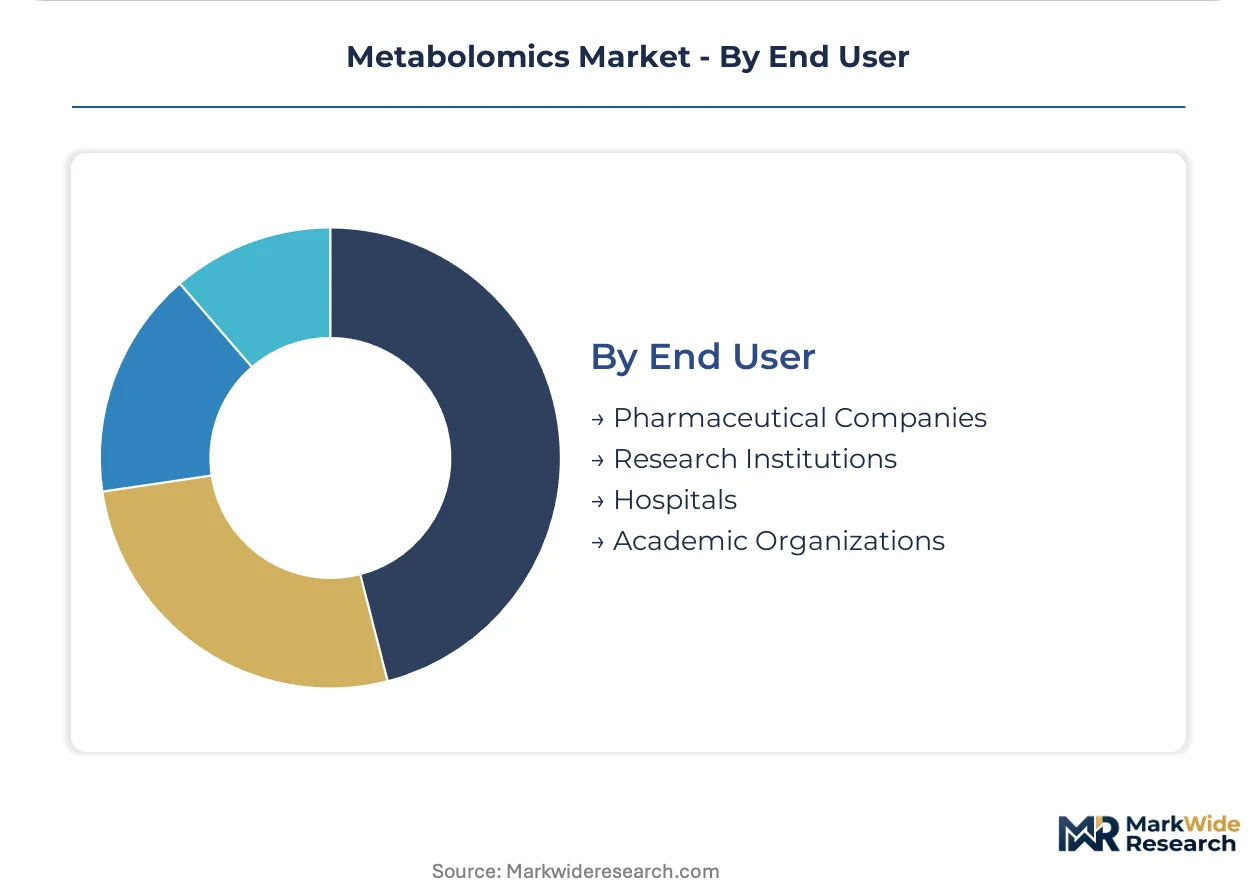
- Pharmaceutical Companies:Large-cap sponsors embed metabolomics scientists into regulatory strategy functions. EMA qualification opinion pre-subscriptions concentrate in German and Swiss pharmaceutical clusters.
- Research Institutions:Academic core facilities manage multi-user access to high-resolution instrumentation. ISO 17025 accreditation requirements constrain clinical service expansion for university-affiliated laboratories.
- Hospitals:Clinical laboratories pursue CLIA certification for metabolite panel deployment in patient care. State-level accreditation timelines extend 18-24 months, delaying revenue recognition.
- Academic Organizations:Individual research groups procure lower-cost chromatography and electrophoresis systems. Funding concentration in United States, German, and Japanese research clusters shapes regional demand patterns.
Pharmaceutical companies drive premium spending; hospitals represent the most constrained procurement tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrument manufacturing clusters in Germany, Japan, and the United States concentrate 70% of high-resolution mass spectrometry production capacity. FDA biomarker qualification programs and EMA qualification opinion pathways pull clinical metabolomics demand toward these regulatory jurisdictions. Research infrastructure investments in precision medicine create geographic anchoring effects that reinforce regional specialization.
United States
Pharmaceutical toxicology groups in Boston and San Diego corridors drive demand for ISO 17025-accredited clinical metabolomics services. FDA biomarker qualification programs establish evidentiary standards that shape global regulatory submission strategies. The National Institutes of Health funds multi-omics integration initiatives that concentrate academic core facility procurement in Maryland and Massachusetts research clusters.
Germany
Bruker Corporation anchors high-resolution mass spectrometry manufacturing in Baden-Württemberg, supplying academic core facilities worldwide. EMA qualification opinion pathways tighten pre-submission requirements for metabolic signatures in marketing authorization applications. Pharmaceutical clusters in Basel-Zurich and Rhine-Main embed metabolomics scientists directly into regulatory strategy functions.
Japan
Shimadzu Corporation and Human Metabolome Technologies concentrate instrument and service provision in Kyoto and Tokyo metropolitan areas. PMDA pathways for companion diagnostic metabolite panels remain sparsely populated relative to genomic biomarkers. METI funding for precision medicine infrastructure pulls metabolomics into standard biomarker discovery workflows at Osaka and Kobe research institutes.
Switzerland
Swissmedic regulatory frameworks align with EMA standards while offering accelerated pathways for novel analytical methodologies. Pharmaceutical sponsors in Basel and Zurich pre-subscribe metabolic signatures for regulatory acceptance ahead of pivotal trial initiation. Roche and Novartis procurement patterns fragment as sponsors unbundle instrument purchase from multi-year service contracts.
United Kingdom
Academic core facilities at Oxford and Cambridge manage multi-user access to 900 MHz NMR systems for structural metabolite elucidation. MHRA post-Brexit regulatory divergence creates uncertainty for EMA-aligned biomarker qualification strategies. London biotech corridors favor pay-per-sample arrangements with ISO 17025-accredited clinical laboratories over captive analytical infrastructure.
Metabolomics Market Key Industry Players
Full-stack platform vendors and specialized service providers split the market along hardware-versus-outsourcing fault lines. Thermo Fisher Scientific, Bruker Corporation, and Agilent Technologies anchor the consolidated instrument tier with established mass spectrometry installed bases. Cloud-native analytics entrants and ISO 17025-accredited clinical laboratories capture recurring revenue through bioinformatics outsourcing. Competitive moves concentrate on M&A for software-analytics capabilities and strategic partnerships for regulatory submission support.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify platform breadth strategies that span instrument, consumables, and service layers. Bruker Corporation occupies a position within the high-resolution mass spectrometry specialist tier, while Metabolon represents the pure-play service archetype focused on bioinformatics and pathway interpretation. Waters Corporation and Shimadzu Corporation sit within the chromatography-mass spectrometry workflow segment, competing on method standardization and cross-platform compatibility.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| Bruker Corporation |
| Waters Corporation |
| Shimadzu Corporation |
| Metabolon |
| Human Metabolome Technologies |
| Danaher Corporation |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
Baden-Württemberg's precision manufacturing cluster anchors ion source and detector component production, concentrating upstream capacity among specialized German and Japanese suppliers and feeding downstream pricing leverage to instrument vendors who bundle hardware with multi-year service contracts.
Pricing Analysis
After-sales service contracts and cloud-based analytics subscriptions now drive lifetime value, displacing transactional hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-accredited clinical laboratories from academic core facilities and mid-tier research institutions. Cost compression in consumables and reagents is intensifying because pharmaceutical sponsors unbundle instrument purchases from captive analytical infrastructure. Biotech buyers in Boston and San Diego corridors exhibit the highest price sensitivity, favoring pay-per-sample arrangements, while large-cap pharmaceutical organizations absorb premium pricing for regulatory submission support.
Supply Chain Analysis
High-purity solvents, stable-isotope labeled standards, and specialized chromatography resins feed from concentrated chemical manufacturing bases in Germany, Japan, and the United States. Critical ion source components and superconducting magnet assemblies rest on single-source vulnerability at specialized suppliers in Baden-Württemberg and Kyoto prefecture. Distribution runs through authorized dealer networks for academic procurement and direct enterprise sales teams for pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metabolomics market rewards organizations that control scarce bioinformatics talent and regulatory submission expertise, with pathway interpretation capabilities now the binding constraint on clinical translation timelines.
For Market Incumbents: Pre-empt cloud-native analytics consolidation by acquiring specialized pathway interpretation software firms before pharmaceutical sponsors internalize these capabilities. Deepen backward integration into stable-isotope standard production to defend margin position against reagent commoditization. Lock in ISO 17025-accredited clinical laboratories through exclusive multi-year service contracts that embed metabolomics scientists into sponsor regulatory strategy functions. For New Entrants and Emerging Players: Establish a beachhead in Japan's PMDA companion diagnostic metabolite panel pathway, which remains sparsely populated relative to genomic biomarkers. Target ISO 17025 accreditation for clinical service provision in Boston and San Diego biotech corridors where pharmaceutical sponsors favor outsourcing over captive infrastructure. Lead with AI-accelerated pathway elucidation tools that compress interpretation timelines for complex metabolic networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because FDA and EMA biomarker qualification pathways create durable competitive moats for service providers with demonstrated submission success. Acquisition candidates should display ISO 17025 accreditation, established pharmaceutical sponsor relationships, and embedded regulatory affairs expertise. Watch for inflection when EMA qualification opinion pre-subscriptions accelerate ahead of pivotal trial initiations in German and Swiss pharmaceutical clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Analytics Platform Launch | Thermo Fisher Scientific anchors subscription revenue through remote bioinformatics services that collapse traditional licensing economics. |
| ISO 17025 Accreditation Investment | Clinical service providers in Boston and San Diego corridors capture biotech sponsor contracts that demand regulatory submission support. |
| AI-Accelerated Pathway Elucidation Development | Machine learning integration with mass spectrometry data streams compresses 12-month metabolite identification timelines into 6-week cycles. |
| EMA Qualification Opinion Pre-Subscription | European pharmaceutical sponsors in Basel-Zurich and Rhine-Main clusters pre-specify metabolic signatures before pivotal trial initiation. |
| Backward Integration into Stable-Isotope Standards | Agilent Technologies extends chromatography-mass spec workflow dominance through certified reference materials that satisfy FDA evidentiary requirements. |
Research Approach
A standing panel of metabolomics platform directors, pharmaceutical toxicology group leaders, regulatory affairs specialists at EMA and FDA, and academic core facility managers provided ongoing calibration across the study period. Primary interviews with instrument vendor product managers and ISO 17025-accredited clinical laboratory directors combined with secondary validation against FDA biomarker qualification filings, EMA qualification opinion submissions, ClinicalTrials.gov protocol registries, and SEC 10-K disclosures from diversified life sciences conglomerates. Bottom-up segmentation modeling triangulated against top-down market sizing from installed base estimates and service revenue pools.
Scenario-bracketing framed analytical sensitivity across the projection horizon, with segmentation dimensions spanning product type, application, technology platform, and end-user procurement authority. Modeled variables included pharmaceutical sponsor outsourcing propensity, academic core facility capital expenditure cycles, and regulatory pathway adoption rates. CAGRs derived from weighted average of historical trajectory analysis and forward-looking capability diffusion curves, with explicit treatment of high-resolution instrument cost constraints and bioinformatics talent scarcity as dampening inputs.
Macroeconomic conditions sit as an overlay; deviation in NIH and METI precision medicine funding levels, or EMA regulatory timeline compression, would shift the trajectory of clinical translation demand. Cross-checking against pharmaceutical R&D outsourcing survey benchmarks and academic core facility procurement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Research
Preventive Medicine Market
Medical Research
Global Patient Derived Xenograft Models Market
Medical Research
Cancer Mouse Models Market
Medical Research
PDX Models Market
Medical Research
AAV Contract Development and Manufacturing Organizations Market
Medical Research
Forensic Medicine Market
Medical Research
Methicillin-Resistant Staphylococcus Aureus (MRSA) Drugs Market
Medical Research
FFPE Tissue Samples Market
Medical Research
Epigenomics Market
Medical Research
Global in Vitro Lung Model Market
Medical Research
Life Science R&D Infrastructure Outsourcing Market
Medical Research
Global Humanized Mouse Model Market
Medical Research
Antibody-Mediated Rejection Prevention Market
Medical Research
Organoids and Spheroids Market
Medical Research
Precision Medicine Market
Medical Research
Europe Induced Pluripotent Stem Cells (Ipscs) Market