
 Message Handling Systems Market | 2026-2036
Message Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Message Handling Systems Market Analysis
Modular deployment architectures is rebalancing procurement patterns across defense and enterprise buyers. Thales Group leverages its pan-European engineering footprint to sustain long-term service contracts with NATO-aligned ministries. Rohde & Schwarz anchors German-language market dominance through specialized hardware-software bundles for tactical communications. Boldon James competes on information assurance credentials, occupying niche positions in UK government and allied intelligence ecosystems.
Message Handling Systems comprise software and hardware platforms that route, store, and secure structured communications across military, government, and enterprise networks, typically supporting X.400 or SMTP/MIME protocols with mandatory encryption and non-repudiation features. Their primary commercial purpose centers on guaranteed message delivery with audit trails for organizations operating under strict confidentiality regimes. Cloud-Based and Hybrid service types are capturing expanding share as defense ministries relax previous on-premises-only mandates, though On-Premises deployments retain margin concentration in highest-classification environments. Multi-Channel Support features are differentiating vendor selection as buyers demand unified interfaces spanning radio, satellite, and IP networks.
FCC spectrum regulations shape VoIP system certification requirements for US government contractors, while EU NIS2 and GDPR frameworks impose breach-notification and data-localization obligations on European deployments. ISO 27001 and NATO STANAG standards function as de facto market access filters, excluding vendors without certified security engineering processes. Stakeholders must monitor evolving national encryption export controls and quantum-resistant algorithm mandates to anticipate compliance-driven replacement cycles.
Market Dynamics
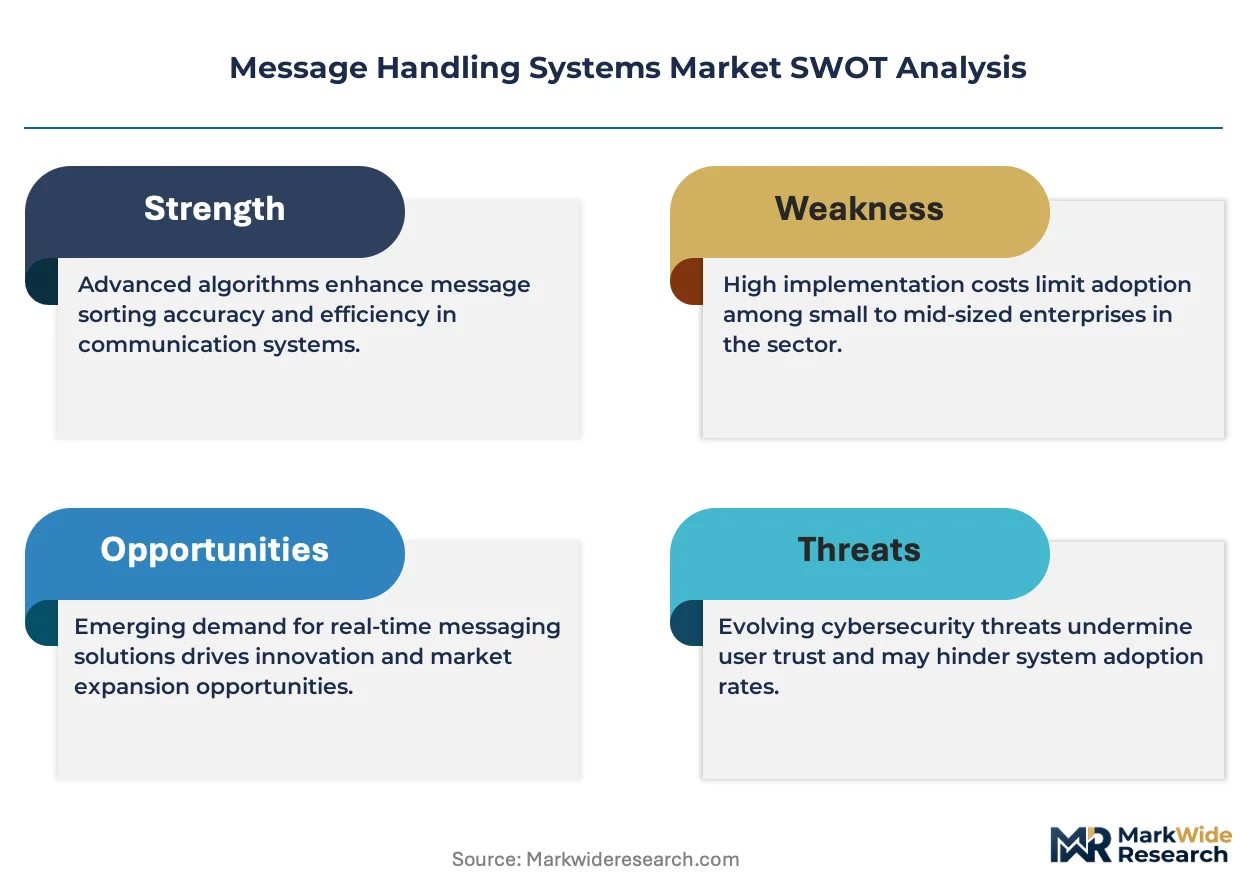
Defense ministries across NATO member states are accelerating cloud migration mandates for classified communications, forcing vendors to recertify platforms under stricter sovereignty requirements while maintaining interoperability with legacy X.400 infrastructure.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting and supply-chain security audits for critical communication operators are expanding procurement budgets for compliant message handling infrastructure.
- Tactical radio convergence:Military end-users demand unified message routing across HF, VHF, and satellite channels, driving platform upgrades with multi-channel support features.
- Quantum-resistant cryptography:National security agencies in Germany and France are mandating post-quantum algorithm migration, triggering replacement cycles for encryption modules.
Market Restraints
- Specialized hardware concentration:Fabrication of tamper-resistant security modules concentrates among a limited set of European semiconductor foundries, creating supply vulnerability.
- Prolonged certification timelines:NATO STANAG and national cryptology authority approvals extend sales cycles by 18-36 months, freezing working capital.
- Open-source messaging alternatives:Signal Protocol and Matrix implementations gain traction in non-classified government segments, pressuring proprietary platform pricing.
Strategic Opportunities
- Polish defense modernization:Warsaw's accelerated procurement of C4ISR systems creates entry points for message handling vendors with NATO interoperability credentials.
- Zero-trust architecture mandates:US federal agencies are reclassifying message handling as core zero-trust components, expanding addressable market beyond traditional defense buyers.
- API-first integration:RESTful interfaces with SIEM and SOAR platforms enable vendors to capture adjacent cybersecurity budgets through unified alerting workflows.
Industry Challenges
- Cleared personnel scarcity:Vendors struggle to recruit software engineers with both active security clearances and modern cloud-native development skills.
- Legacy protocol coexistence:Maintaining backward compatibility with X.400, SMTP, and proprietary military formats inflates engineering overhead and test matrix complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Message Handling Systems Market |
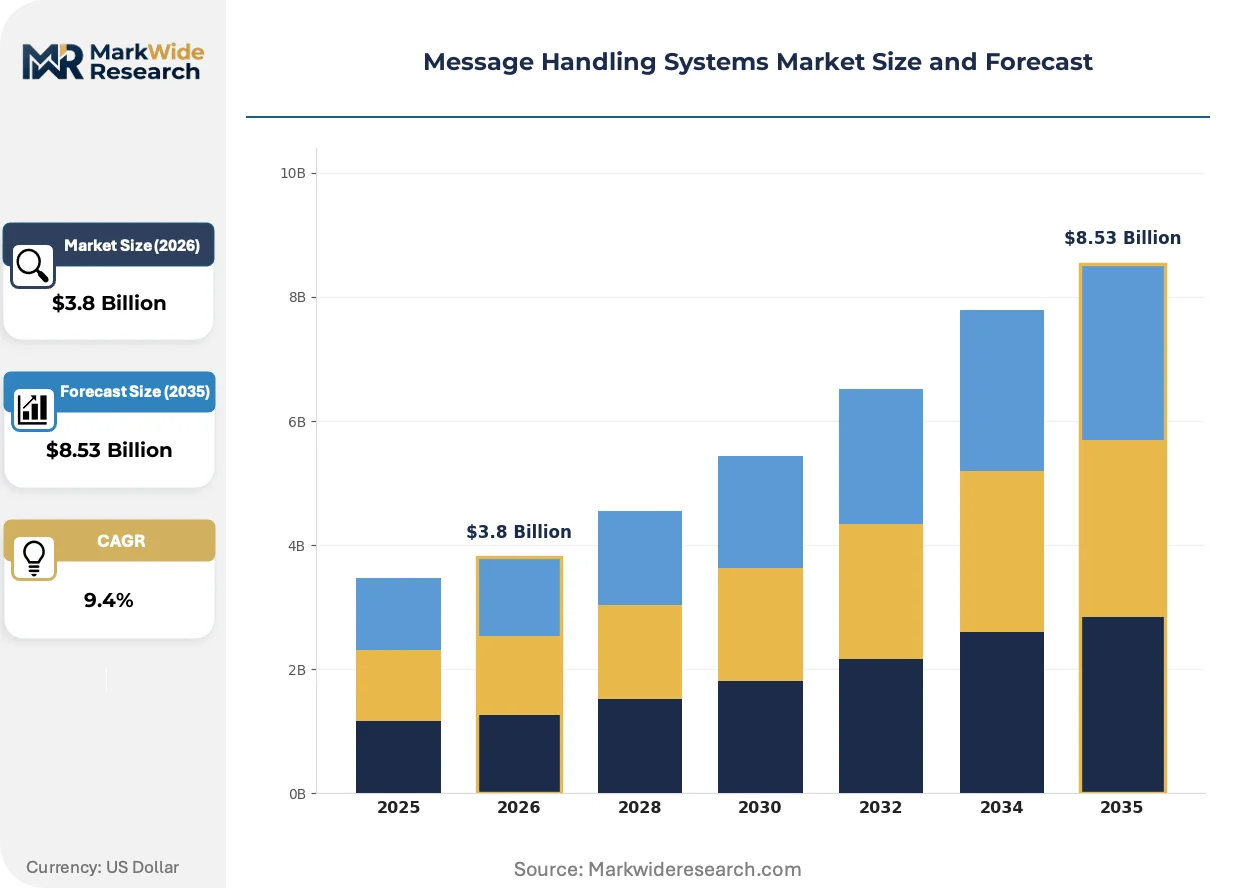
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SMS Gateway, Email Server, VoIP System, Instant Messaging App Service Type: Cloud-Based, On-Premises, Hybrid, Managed Services End User: Enterprises, Educational Institutions, Government Agencies, Financial Services Feature: Message Encryption, Real-Time Analytics, Multi-Channel Support, Automated Alerts |
| Companies Covered | Nexor Limited, Telos Corporation, Boldon James, Rohde & Schwarz, Avitech GmbH, Monitor Soft Pvt. Ltd, Ingegneria Dei Sistemi S.p.A, Thales Group, Systematic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Message Handling Systems Market Emerging Trajectories
Artificial intelligence and machine learning capabilities are embedding into message classification and threat detection workflows, transforming platforms from passive routing infrastructure into active security enforcement layers.
Containerized deployment architectures are integrating Kubernetes orchestration with hardware security module attestation, enabling defense agencies to operate classified workloads on accredited commercial cloud environments. NATO's C3B interoperability framework is accelerating adoption of these hybrid configurations among member state signal corps. This technology convergence is compressing deployment timelines from months to weeks for non-classified message domains.
EU Cybersecurity Certification Scheme for ICT products is mandating Common Criteria evaluation for message handling systems processing EU classified information, forcing vendors to restructure development processes around certified secure engineering. Germany's BSI and France's ANSSI are enforcing divergent national interpretations, fragmenting compliance pathways. Vendors with pre-existing BSI certifications are capturing early mover advantage in Bundeswehr procurement cycles.
Subscription-based platform access is displacing perpetual license models as defense ministries prioritize operational expenditure flexibility and embedded vendor support commitments. UK Strategic Command and Dutch Defense Materiel Organization have pioneered multi-year service contracts with usage-based pricing tiers. This procurement evolution is most visible in Northern European markets where budget predictability outweighs total cost of ownership considerations.
Message Handling Systems Market Segmentation
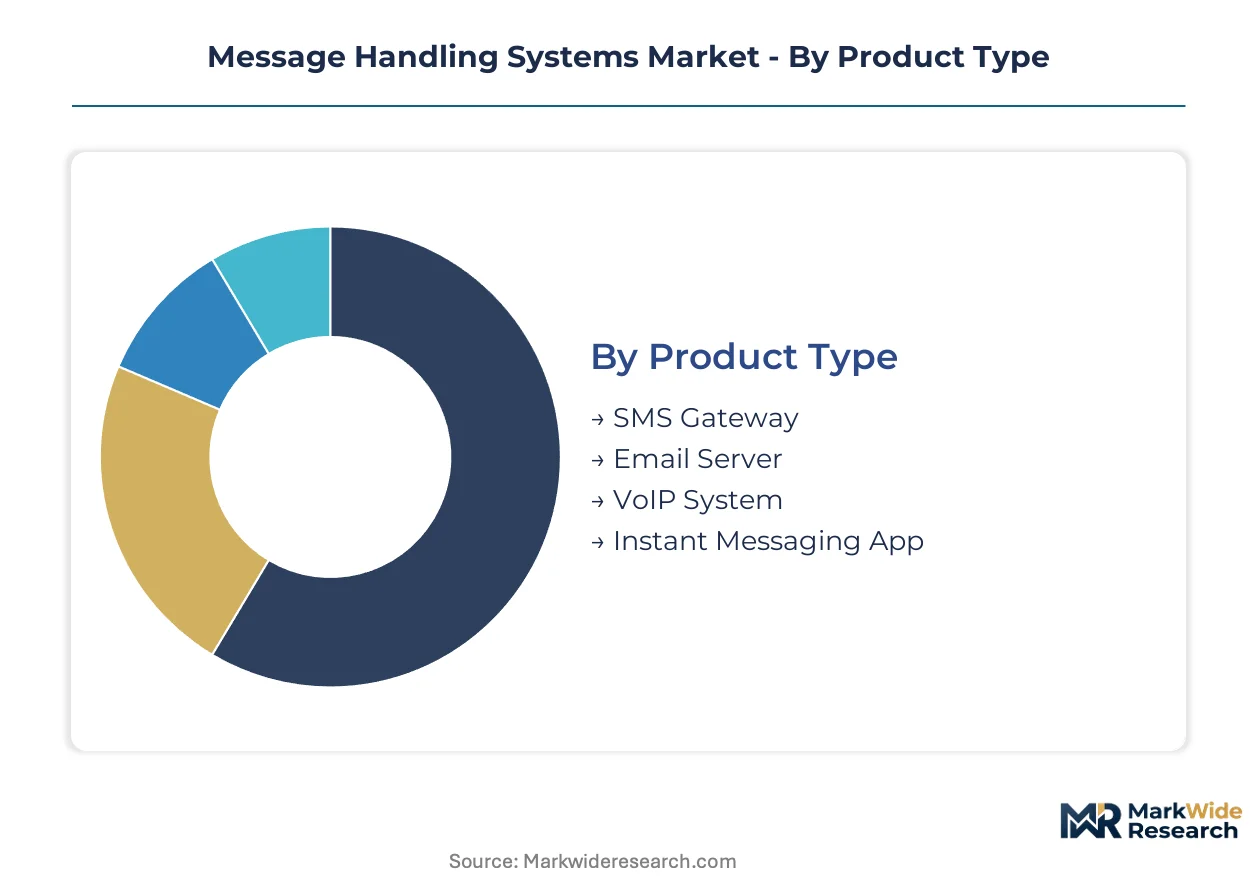
Segmentation in Message Handling Systems reveals how procurement priorities diverge between classified defense environments and commercial enterprise deployments. Buyers select configurations based on sovereignty requirements, integration complexity, and operational tempo rather than generic feature comparisons.
Product Type:
Upgrade cycles across product categories reflect divergent certification burdens and interoperability mandates from NATO signal corps and national cryptology authorities.
- Email Server:X.400-compliant servers with STANAG 4406 extensions dominate Bundeswehr and UK Strategic Command procurement. German defense ministries prioritize hardware-software bundles from BSI-certified vendors, extending replacement timelines to 7-10 years for highest-classification environments.
- VoIP System:Military-grade VoIP integrates with tactical radio networks across HF, VHF, and satellite channels. French Army C4ISR modernization programs are driving demand for quantum-resistant encryption modules in voice infrastructure, compressing procurement cycles for field-deployable units.
- SMS Gateway:Government alerting systems in Netherlands and Norway deploy carrier-grade gateways for population-wide emergency notifications.
- Instant Messaging App:NATO C3B interoperability frameworks are accelerating adoption of containerized messaging for coalition operations.
Volume placements concentrate in Email Server; the faster expansion belongs to VoIP System.
Service Type:
Cost tier differentiation separates sovereign cloud mandates from commercial flexibility requirements across European defense budgets.
- On-Premises:Air-gapped deployments with hardware security module attestation retain margin concentration in French and German facilities processing CONFIDENTIEL UE and NATO RESTRICTED traffic. ANSSI and BSI certification pathways fragment vendor qualification, favoring incumbents with pre-existing national approvals.
- Cloud-Based:UK Strategic Command and Dutch Defense Materiel Organization have pioneered accredited commercial cloud workloads through NATO's C3B framework. Kubernetes orchestration with HSM attestation enables deployment compression from months to weeks for non-classified domains.
- Hybrid:Polish defense modernization programs are adopting split architectures with classified on-premises cores and unclassified cloud extensions.
- Managed Services:Multi-year service contracts with usage-based pricing are displacing perpetual licenses in Northern European procurement.
Margin capture clusters in On-Premises; the steepest expansion trajectory belongs to Cloud-Based.
End User:
Application-specific requirements shape encryption grade, audit granularity, and integration depth across buyer categories.
- Government Agencies:Defense ministries and intelligence services mandate Common Criteria EAL4+ evaluation under EU Cybersecurity Certification Scheme. Germany's BSI interprets requirements more stringently than France's ANSSI, creating compliance fragmentation that favors vendors with pre-existing German certifications.
- Financial Services:ECB oversight and national banking regulators in Frankfurt and Paris impose breach-notification obligations aligned with NIS2 Directive. Payment infrastructure operators are upgrading message handling for real-time settlement systems with sub-second latency requirements.
- Enterprises:Critical infrastructure operators in energy and transport sectors face expanded NIS2 compliance scope.
- Educational Institutions:University research consortia handling EU-funded defense projects require interim accreditation for handling RESTRICTED information.
Budget authority concentrates in Government Agencies; the fastest share gain belongs to Financial Services.
Feature:
Maturity gradients separate baseline compliance features from advanced capabilities commanding premium positioning.
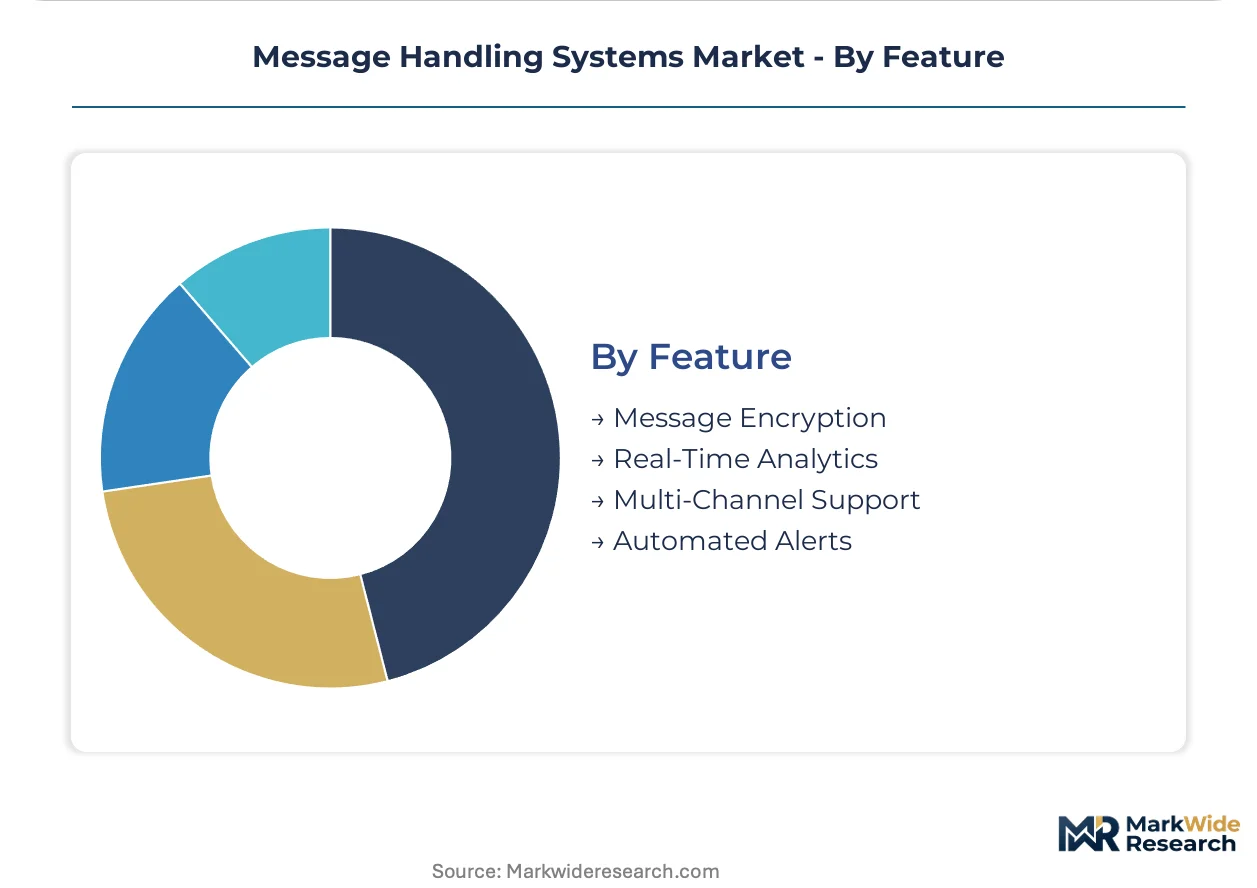
- Message Encryption:Post-quantum algorithm migration mandated by German and French national security agencies is triggering module replacement cycles. AES-256 and emerging lattice-based schemes must coexist during transition periods, inflating engineering overhead.
- Multi-Channel Support:Unified interfaces spanning radio, satellite, and IP networks differentiate vendor selection for tactical deployments. NATO signal corps demand seamless handoff between HF legacy systems and modern IP-based infrastructure.
- Real-Time Analytics:SIEM and SOAR platform integration through RESTful APIs enables vendors to capture adjacent cybersecurity budgets.
- Automated Alerts:Machine learning classification workflows are embedding threat detection into routing decisions.
Procurement priority concentrates in Message Encryption; the climbing adoption curve belongs to Multi-Channel Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of secure message handling infrastructure concentrates in Germany, France, and the United Kingdom, while consumption spreads across NATO member states with divergent certification requirements and procurement timelines.
Germany
Bundeswehr modernization and BSI certification mandates drive procurement of hardware-software bundles for classified environments. The EU NIS2 Directive tightens supply-chain security audits for critical communication operators. Engineering clusters in Munich and Stuttgart anchor Thales Group and Rohde & Schwarz manufacturing capacity for NATO STANAG-compliant platforms.
United Kingdom
UK Strategic Command pioneers multi-year service contracts with usage-based pricing for cloud-accredited workloads. The National Cyber Security Centre enforces stringent encryption standards for government messaging infrastructure. Boldon James maintains niche positions within intelligence ecosystems through information assurance credentials developed in Cheltenham and London.
France
French Army C4ISR programs accelerate demand for quantum-resistant encryption modules in voice and message infrastructure. ANSSI interprets EU Cybersecurity Certification Scheme requirements with national variations that fragment vendor qualification pathways. Thales Group leverages its domestic engineering footprint to sustain long-term contracts with defense ministries in Paris and Toulouse.
Poland
Warsaw's accelerated defense procurement creates entry points for vendors with NATO interoperability credentials. The country's national cyber defense strategy expands budgets for secure military messaging systems. C4ISR modernization programs in Warsaw and Kraków attract foreign suppliers seeking footholds in Eastern European defense markets.
Netherlands
Dutch Defense Materiel Organization adopts hybrid architectures with accredited commercial cloud extensions for non-classified domains. GDPR and NIS2 frameworks impose data-localization obligations on message handling deployments. The Hague and Eindhoven host system integration clusters serving NATO coalition operations and population-wide emergency notification systems.
Message Handling Systems Market Vendor Landscape
The competitive structure tilts toward defense-anchored conglomerates with pre-existing national security certifications. Vendor qualification fragments across BSI, ANSSI, and NATO STANAG approval pathways, creating moats for incumbents with multi-year certification investments. Two strategic archetypes dominate: pan-European engineering conglomerates with sovereign cloud credentials, and specialized information assurance boutiques with intelligence community relationships. Competitive moves concentrate on API-first platform extensions and multi-year service contract conversions from perpetual licenses.
Among European defense-anchored conglomerates, Thales Group and Rohde & Schwarz exemplify the scale-driven tier with pan-continental engineering footprints and pre-existing national cryptology authority approvals. Boldon James occupies a specialist position within UK government and allied intelligence ecosystems, representing the information assurance boutique archetype that competes on certification depth rather than geographic breadth.
| Leading Market Players |
|---|
| Nexor Limited |
| Telos Corporation |
| Boldon James |
| Rohde & Schwarz |
| Avitech GmbH |
| Monitor Soft Pvt. Ltd |
| Ingegneria Dei Sistemi S.p.A |
| Thales Group |
| Systematic |
| Others |
Supply Flow & Price Mechanics
Containerized deployment architectures with Kubernetes orchestration and hardware security module attestation are compressing deployment timelines from months to weeks, simultaneously reducing per-unit implementation costs and concentrating engineering expertise among vendors with pre-existing NATO C3B framework certifications. This dual shift reshapes procurement economics across defense and enterprise segments.
Pricing Analysis
Cost-down pressure on cloud-accredited tiers accelerates because subscription-based platform access displaces perpetual licenses in Northern European procurement. Three-tier pricing structure across premium, standard, and economy levels separates BSI-certified hardware-software bundles from cloud-native SaaS tiers and open-source protocol implementations. Certification depth and sovereign cloud credentials drive price differentiation, with German defense ministries least price-sensitive and non-classified government segments most responsive to usage-based alternatives.
Supply Chain Analysis
Dual-sourcing requirements for tamper-resistant security modules mandate multi-supplier qualification across German, French, and Dutch semiconductor foundries. Fabrication draws from specialized European foundries with NATO STANAG certification, while raw material inputs include cryptographic processors, radiation-hardened memory, and quantum-resistant algorithm IP cores. Single-source vulnerability concentrates in BSI and ANSSI-approved security module vendors. Distribution runs through defense ministry procurement offices and system integrators serving NATO signal corps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Message handling systems vendors are racing to deepen backward integration into cryptographic processor supply and downstream into managed service delivery, capturing margin pools that previously accrued to channel partners.
For Market Incumbents: Cement pan-European certification breadth by accelerating BSI and ANSSI parallel approval pathways before EU Cybersecurity Certification Scheme fragmentation hardens. Prioritize captive supply of quantum-resistant encryption modules to offset foundry concentration risk. Defend against API-first challengers by embedding RESTful SIEM integration into standard service tiers. For New Entrants and Emerging Players: Zero-trust architecture mandates for US federal agencies present a technology-first wedge into non-traditional defense buyers previously captured by legacy X.400 vendors. Polish defense modernization programs offer the most penetrable geography for NATO interoperability credentials. Lead with containerized deployment expertise and Kubernetes-native security attestation to bypass incumbent hardware-software bundle advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by defense-anchored conglomerates seeking sovereign cloud credentials and national cryptology authority approvals. Long-term viability hinges on certification moats rather than feature velocity. Watch for quantum-resistant algorithm standardization by Germany's BSI and France's ANSSI as the inflection signal triggering replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Integration | RESTful SIEM and SOAR connectivity captures adjacent cybersecurity budgets from CISOs. |
| Multi-Year Service Contract Conversion | Usage-based pricing displaces perpetual licenses in UK Strategic Command procurement. |
| Quantum-Resistant Module Certification | BSI and ANSSI post-quantum approvals trigger replacement cycles in Bundeswehr infrastructure. |
| Backward Integration into Security Modules | In-house cryptographic processor supply mitigates European foundry concentration risk. |
| Geographic Expansion into Polish Defense | Warsaw's C4ISR modernization creates NATO interoperability entry points for qualified vendors. |
Methodological Framework
Defense procurement databases, NATO STANAG documentation, and EU regulatory filings formed the secondary backbone, supplemented by primary interviews with signal corps procurement officers, CISOs at critical infrastructure operators, platform engineers at accredited cloud providers, and integration specialists serving coalition operations. Bottom-up and top-down triangulation validated segment-level estimates against ministry budget disclosures and vendor contract announcements.
Historical trendline analysis across deployment model transitions informed projection frameworks, modeling service type, product category, end-user vertical, and feature tier dimensions over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against defense budget trajectory assumptions, with quantum-resistant algorithm migration timelines and NIS2 compliance deadlines as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including classified program budgets, national encryption export control revisions, and coalition operation tempo variations. Forecasts reflect documented assumptions about certification timeline stability and foundry capacity expansion. Deviation in BSI-ANSSI regulatory divergence or NATO C3B framework adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
High Performance Message Infrastructure Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Cloud Communication Platform Market
Communication Services
Broadcasting Solutions Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Postal Services Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Mobile Messaging Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Global Communications Interface Market
Communication Services
Speech to Speech Translation Market
Communication Services
Audio Conferencing Services Market
Communication Services
Meeting Solutions Market