
 Ripening Cultures Market | 2026-2036
Ripening Cultures Market Size, Share, and Industry Trends Forecast 2026-2036
Ripening Cultures Market Analytics
Direct-to-artisan distribution is reshaping how ripening cultures reach small-scale dairy operations. Chr. Hansen Holding A/S leverages its strain library to dominate European cheese-producing regions. DSM-Firmenich anchors global supply through integrated biotechnology platforms. Lallemand competes on freeze-dried formats optimized for cold-chain logistics.
Ripening cultures comprise defined microbial consortia—bacteria, yeasts, and molds—selected for enzymatic activity, acidification kinetics, and proteolytic profiles that transform milk proteins into textured, flavored curd. Liquid cultures retain viability for seven to twenty-one days under refrigeration, while freeze-dried alternatives extend shelf stability to twenty-four months through controlled sublimation. Freeze-dried cultures command premium positioning among artisan producers seeking batch consistency without cold-chain dependency. Dairy Products applications generate the deepest margin pools due toProtected Designation of Origin requirements across European cheese categories.
EFSA evaluates novel microbial strains for Qualified Presumption of Safety status before market authorization. EU REACH governs enzymatic additives and residual metabolites in finished food matrices. France's national food safety agency enforces additional terroir-specific microbial criteria for AOP-labeled cheeses. Stakeholders must monitor strain patent expirations and evolving clean-label definitions as regulatory and consumer preference boundaries converge.
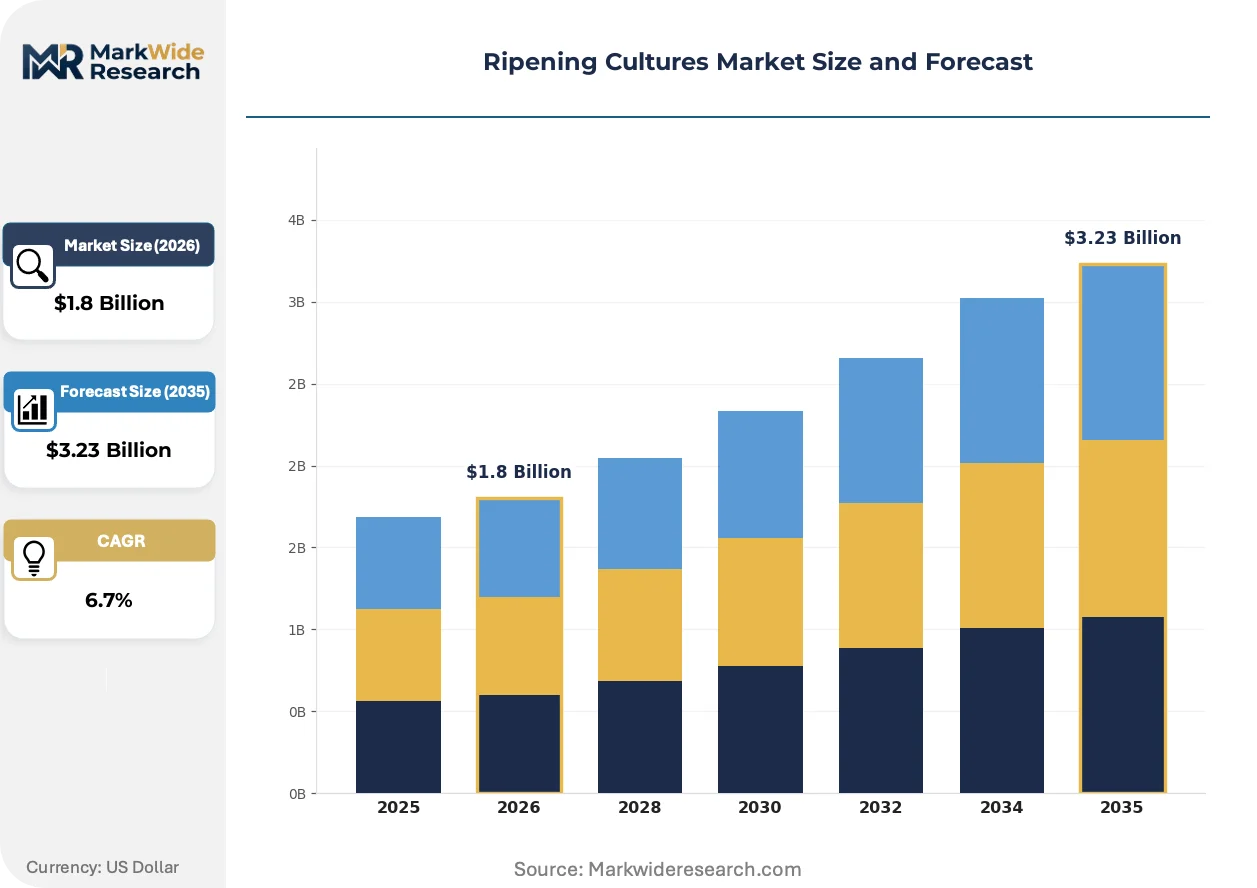
Market Dynamics
Freeze-dried culture formats are compressing cold-chain dependency among artisan producers, forcing liquid culture suppliers to defend margin positions through strain patent exclusivity and terroir-specific consortium development.
Growth Catalysts
- EFSA Qualified Presumption of Safety pathway:Streamlined microbial strain approvals accelerate novel culture commercialization for Protected Designation of Origin cheese categories across EU member states.
- Artisan dairy clustering:France's Normandy and Auvergne production zones concentrate demand for precisely characterized ripening consortia with documented enzymatic profiles.
- Controlled sublimation advances:Shelf-stable freeze-dried formats eliminate refrigeration infrastructure requirements for small-scale creameries in remote dairy regions.
Market Restraints
- Strain library concentration:Proprietary microbial collections remain concentrated among three European biotechnology suppliers, creating bottleneck risk for specialized AOP-compliant cultures.
- REACH metabolite testing costs:Residual enzymatic byproduct characterization requirements impose fixed compliance burdens disproportionately affecting small culture producers.
- Clean-label definitional drift:Evolving consumer interpretations of "natural" ripening challenge standardization of microbial additive positioning across retail cheese categories.
Strategic Opportunities
- Direct-to-artisan distribution platforms:Bypassing traditional dairy ingredient wholesalers enables culture suppliers to capture margin and provide technical support for small-batch producers.
- Convergence of genomic screening and traditional phenotyping:Combining rapid strain characterization with classical cheese-making trials compresses development timelines for region-specific culture blends.
- EU Green Deal agricultural biotechnology incentives:Funding streams for sustainable food production systems subsidize precision fermentation infrastructure for culture manufacturing.
Industry Challenges
- Qualified Presumption of Safety timeline variability:EFSA novel strain review durations create planning uncertainty for culture development pipelines targeting seasonal cheese production cycles.
- Terroir-specific microbial criteria fragmentation:France's ANSM enforces additional regional standards beyond baseline EU requirements, multiplying compliance documentation burdens for cross-border culture suppliers.
- Legacy dairy microbiology skill scarcity:Traditional curd-handling expertise required for culture efficacy validation is concentrating among retiring cheese-maker cohorts in established production clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ripening Cultures Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Cultures, Solid Cultures, Freeze-Dried Cultures, Starter Cultures Application: Dairy Products, Fermented Beverages, Plant-Based Foods, Meat Products End User: Food Manufacturers, Beverage Producers, Artisan Chefs, Research Institutions Packaging Type: Plastic Pouches, Glass Vials, Metal Cans, Bulk Containers |
| Companies Covered | Chr. Hansen Holding A/S, DSM-Firmenich, DuPont de Nemours, Lallemand, Dairy Connection, Proxis Developpement, Sacco System, Biochem SRL, CSK Food Enrichment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ripening Cultures Market Evolving Landscape
Precision strain selection tools are compressing the traditional artisan knowledge gap, enabling data-driven culture matching to specific milk compositions and aging protocols without decades of empirical apprenticeship.
Next-generation sequencing platforms are collapsing the cost barrier for microbial consortium characterization. Artisan producers in Auvergne and Normandy now access strain-level identification services previously reserved for industrial dairy R&D facilities. This compression enables batch-to-batch consistency verification for AOP-labeled cheeses without laboratory infrastructure investment.
EU REACH enforcement on enzymatic food additives is tightening metabolite disclosure requirements for finished cheese matrices. Culture suppliers must now document residual proteolytic byproducts across extended aging periods. Small-scale French producers face disproportionate analytical cost burdens relative to industrial dairy operations with captive testing facilities.
Consolidation among dairy ingredient distributors is redirecting artisan procurement toward specialized biotechnology direct channels. Traditional agricultural supply cooperatives in Normandy are losing culture volume to manufacturer-led technical service programs. This channel rotation concentrates purchasing power among producers willing to commit to minimum order quantities for freeze-dried formats.
Ripening Cultures Market Segmentation
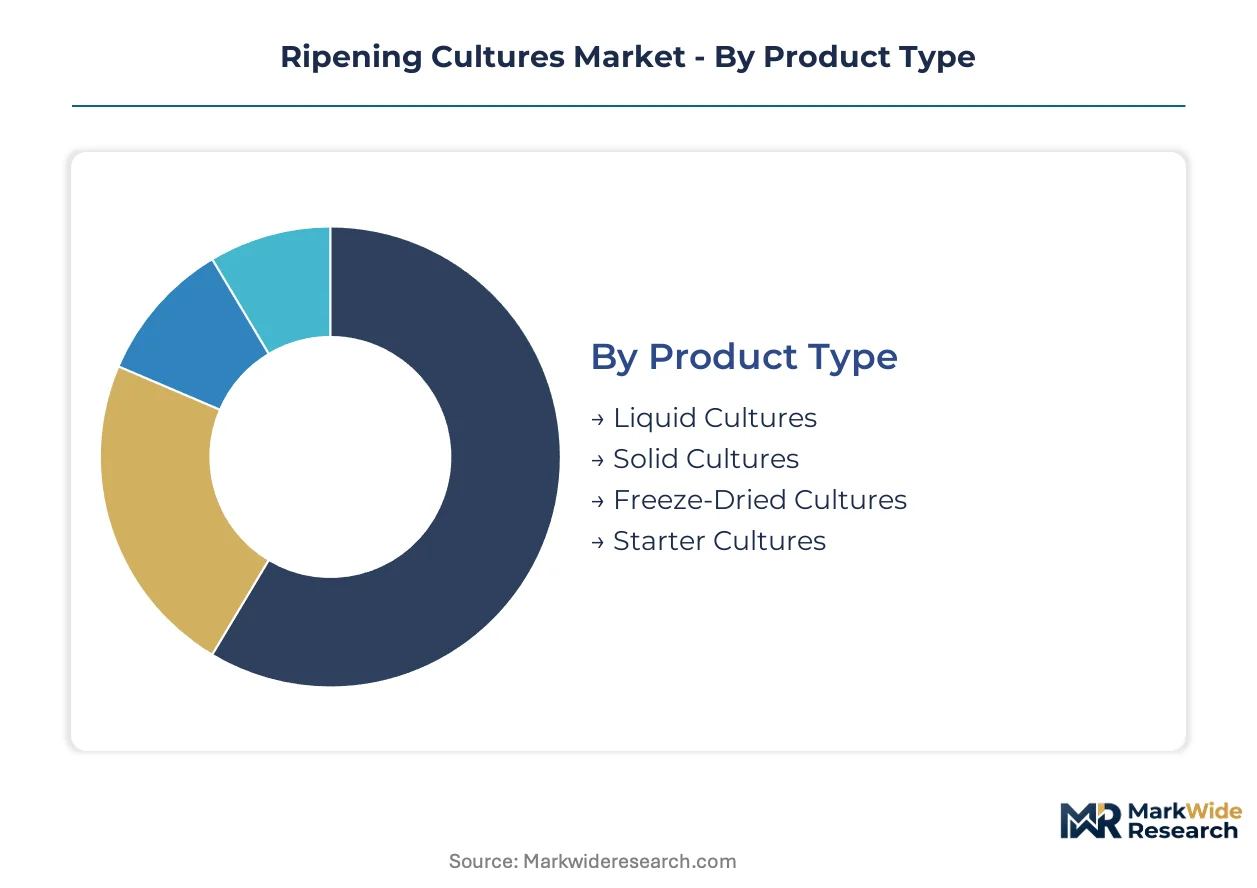
Ripening cultures segment across product formats, applications, and user profiles that each demand distinct technical support intensity. Freeze-dried formats require formulation guidance for rehydration protocols, while liquid cultures need cold-chain troubleshooting. Artisan end-users consume disproportionate service hours per unit volume compared to industrial dairy operations.
Product Type:
After-sales service intensity varies sharply across physical formats, with freeze-dried and liquid cultures demanding opposite support archetypes—technical consultation versus logistics coordination.
- Freeze-Dried Cultures:Controlled sublimation removes moisture to below 5%, yielding twenty-four-month shelf stability without refrigeration. Normandy's AOP-certified creameries drive demand for precisely titrated reconstitution protocols that preserve enzymatic activity profiles. Technical service teams visit artisan sites to calibrate hydration ratios against local water chemistry.
- Liquid Cultures:Active microbial suspensions in buffered media retain viability for seven to twenty-one days under strict 2-8°C cold-chain maintenance. Auvergne's remote mountain dairies struggle with refrigeration infrastructure gaps, compressing addressable market for this format in peripheral production zones. Service burden concentrates on temperature excursion recovery protocols.
- Solid Cultures:Agar-based or freeze-concentrated preparations for specialized terroir-specific consortium propagation.
- Starter Cultures:Defined-strain inoculants for initial acidification prior to secondary ripening microbiota introduction.
Freeze-Dried Cultures holds the largest share; momentum sits with Starter Cultures as precision fermentation enables custom consortium design for emerging plant-based matrices.
Application:
Application segmentation tracks margin architecture, with Protected Designation of Origin compliance requirements creating tiered pricing power across end-use categories.
- Dairy Products:Cheese, yogurt, and fermented milk matrices dominate value capture due to EFSA QPS documentation requirements and AOP microbial specification rigor. France's terroir enforcement agencies mandate strain-level provenance verification for Roquefort, Comté, and Reblochon labeling, embedding culture suppliers deeply into compliance workflows. Technical documentation burdens scale with aging duration.
- Plant-Based Foods:Oat, coconut, and cashew matrices require novel microbial consortia adapted to non-dairy protein substrates lacking casein micelle structures. Clean-label positioning pressures drive demand for undefined, traditionally sourced cultures rather than genetically characterized alternatives. Service intensity concentrates on flavor development timelines that compress versus dairy equivalents.
- Fermented Beverages:Kefir, kombucha, and traditional fermented drinks utilize mixed-culture inoculants with less stringent strain documentation.
- Meat Products:Dry-cured and fermented sausage applications employ specialized mold and yeast cultures for surface ripening.
Dairy Products commands the deepest margin pools; Plant-Based Foods gains share fastest as oat-cheese and coconut-yogurt R&D pipelines accelerate.
End User:
Customer type segmentation reveals inverse relationships between volume scale and technical service consumption per kilogram of culture delivered.
- Artisan Chefs:Small-batch producers in France's designated cheese clusters generate disproportionate support tickets for strain selection, batch troubleshooting, and AOP documentation. Direct-to-artisan distribution models capture this service premium through technical advisory subscriptions rather than commodity markups. Individual producers may consume ten to twenty hours of microbiologist consultation annually.
- Food Manufacturers:Industrial dairy operations with captive R&D facilities internalize most technical support, reducing per-unit service cost for culture suppliers. Volume commitments enable custom consortium development for proprietary cheese lines. Relationship management concentrates on supply security and strain exclusivity negotiations.
- Beverage Producers:Kombucha and kefir operations span craft-to-industrial scale with variable documentation requirements.
- Research Institutions:Academic and government laboratories source reference strains for phenotypic and genomic characterization studies.
Food Manufacturers represents the largest volume segment; Artisan Chefs climbs fastest as direct distribution platforms proliferate.
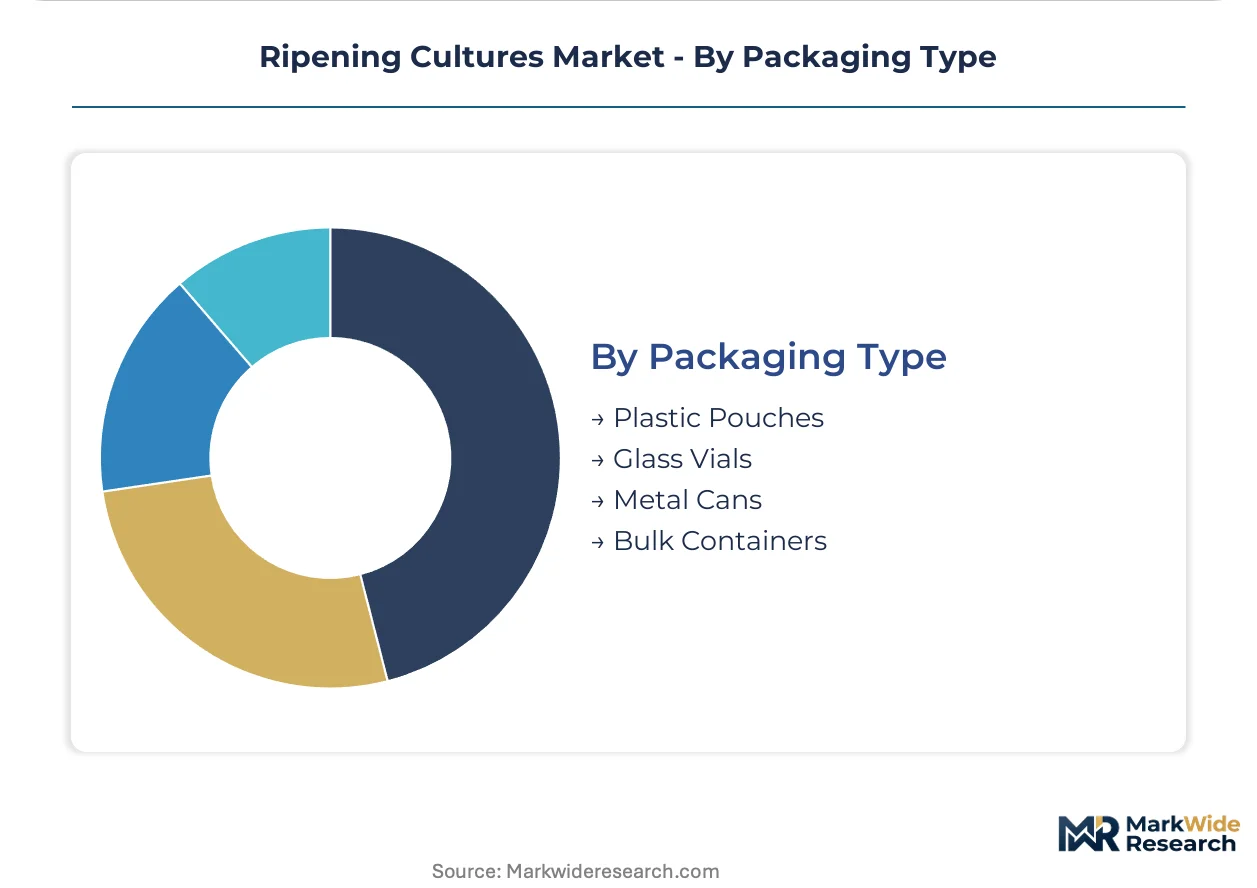
Packaging Type:
Packaging segmentation maps to logistics infrastructure and contamination risk profiles across the cold-chain-to-shelf-stable spectrum.
- Glass Vials:Inert borosilicate containers with septum seals preserve anaerobic culture integrity for high-value, low-volume specialty strains. Premium positioning targets AOP-labeled cheese producers requiring documented batch traceability. Breakage risk elevates freight insurance costs for remote artisan deliveries.
- Plastic Pouches:Multi-layer metallized films with nitrogen flushing dominate freeze-dried culture formats for weight and shatter resistance. Normandy's agricultural supply cooperatives historically distributed through this format, though manufacturer-direct channels now displace wholesale procurement. Shelf appeal limitations constrain retail-facing positioning.
- Metal Cans:Tinplate or aluminum containers for bulk liquid culture shipments with extended shelf-life requirements.
- Bulk Containers:Stainless steel totes and drums for industrial-scale dairy inoculant delivery with integrated temperature monitoring.
Plastic Pouches holds the largest installed base; Glass Vials expands most quickly as terroir-specific strain premiumization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal agricultural biotechnology incentives are redirecting precision fermentation investment toward cheese-producing territories. France's ANSM enforces terroir-specific microbial criteria beyond baseline EFSA requirements. Germany's ECHA REACH framework imposes metabolite disclosure burdens on enzymatic additive suppliers.
France
Normandy and Auvergne cheese clusters concentrate demand for AOP-compliant culture consortia with documented enzymatic profiles. ANSM enforces additional regional microbial standards for Roquefort, Comté, and Reblochon labeling. Artisan producers in these zones consume disproportionate technical service hours for strain selection and batch troubleshooting.
Germany
ECHA REACH mandates residual enzymatic byproduct characterization across extended cheese aging periods. Baden-Württemberg and Bavaria host industrial dairy operations with captive R&D facilities that internalize technical support. These facilities negotiate custom consortium development for proprietary cheese lines.
Italy
Emilia-Romagna and Lombardy maintain traditional Parmigiano-Reggiano and Grana Padano production requiring defined-strain acidification protocols. EFSA QPS documentation requirements embed culture suppliers into compliance workflows. Regional consortia enforce strict microbial provenance verification for Protected Designation of Origin status.
United States
FDA oversight of microbial food additives parallels EFSA frameworks with less stringent strain-level documentation. Wisconsin and Vermont artisan creameries drive adoption of freeze-dried formats for cold-chain independence. Direct-to-artisan distribution platforms bypass traditional agricultural supply cooperatives in these states.
Switzerland
Swissmedic and federal food safety agencies enforce dual compliance with EU REACH and domestic purity standards for cheese exports. Gruyère and Emmental production zones in Fribourg and Vaud require precisely characterized thermophilic starter cultures. Mountain dairies prioritize shelf-stable formats to overcome remote logistics constraints.
Ripening Cultures Market Competitive Landscape
On the supply side, the industry is concentrated among European biotechnology specialists with proprietary strain libraries. Three dominant suppliers anchor global availability through integrated fermentation platforms and freeze-dried formulation expertise. Strategic archetypes include strain library custodians, precision fermentation platform operators, and technical service-intensive direct distributors. Competitive moves center on terroir-specific consortium development and direct-to-artisan channel expansion.
Within the integrated biotechnology tier, Chr. Hansen Holding A/S and DSM-Firmenich exemplify platform-scale players with extensive strain collections and regulatory navigation capabilities. Lallemand occupies a position emphasizing freeze-dried format optimization for logistics-constrained artisan producers. These three anchors represent the dominant supply-side concentration shaping availability and pricing architecture across European cheese-producing regions and export markets.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| DSM-Firmenich |
| DuPont de Nemours |
| Lallemand |
| Dairy Connection |
| Proxis Developpement |
| Sacco System |
| Biochem SRL |
| CSK Food Enrichment |
| Others |
Value Network & Pricing Analysis
Normandy's AOP-certified creamery clusters concentrate freeze-dried culture manufacturing capacity, embedding pricing power with suppliers who control strain library access and terroir-specific consortium documentation. This geographic concentration enables premium capture for EFSA QPS-compliant cultures serving Protected Designation of Origin cheese categories.
Pricing Analysis
Certification level creates the primary spread across EFSA QPS-documented, REACH-registered, and baseline food-grade tiers. Three-tier pricing structure across premium, standard, and economy levels tracks enzymatic specificity, with artisan producers in France's designated cheese zones absorbing the steepest premiums for AOP-compliant strain provenance. Cost compression in liquid culture formats is intensifying because freeze-dried alternatives eliminate cold-chain infrastructure requirements, forcing traditional suppliers to bundle technical advisory services into per-unit pricing. Food manufacturers with captive R&D facilities exhibit lowest price sensitivity due to volume commitments and internalized compliance costs.
Supply Chain Analysis
EU dual-use export controls on precision fermentation technology limit strain transfer protocols and bioreactor equipment flows to non-member states, constraining capacity expansion outside established European biotechnology hubs. Supply concentrates in Denmark, the Netherlands, and France, where integrated fermentation platforms draw from proprietary microbial collections, specialized growth media formulations, and lyophilization equipment. Single-source vulnerability concentrates in thermophilic starter culture lines for Gruyère and Emmental production. Distribution runs through manufacturer-direct technical service programs that displace traditional agricultural supply cooperatives in artisan cheese clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens as direct-to-artisan distribution dissolves wholesale channel control, creating niches for specialized culture suppliers who bundle genomic screening with traditional phenotyping support.
For Market Incumbents: Insulate strain library exclusivity through accelerated patent filings on novel microbial consortia and terroir-specific enzymatic profiles. Consolidate position by acquiring regional culture distributors in Auvergne and Lombardy to lock in AOP compliance workflows. Vertical integration into precision fermentation infrastructure captures EU Green Deal biotechnology subsidies and reduces dependency on external bioreactor capacity. For New Entrants and Emerging Players: Plant-based cheese R&D pipelines in oat and coconut matrices represent the most penetrable entry point, as established dairy culture suppliers lack optimized consortia for non-casein protein substrates. Remote mountain dairies in Switzerland and peripheral French production zones offer addressable white space for shelf-stable freeze-dried formats with embedded rehydration guidance. Go-to-market execution should lead with technical advisory subscriptions rather than commodity culture pricing. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because EFSA QPS documentation requirements and ANSM terroir enforcement create durable moats around approved strain collections. Acquisition targets should display proprietary microbial libraries with multi-jurisdiction regulatory filings and direct-to-artisan channel infrastructure. Signal to monitor is EFSA novel strain review timeline compression, which would accelerate pipeline velocity for culture developers.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA QPS Documentation Investment | Accelerates market authorization for novel microbial strains targeting AOP cheese categories. |
| Direct-to-Artisan Channel Expansion | Bypasses agricultural supply cooperatives in Normandy to capture margin and service premiums. |
| Precision Fermentation Infrastructure Buildout | Secures EU Green Deal biotechnology incentives for controlled sublimation capacity. |
| Terroir-Specific Consortium Development | Locks in compliance workflows with ANSM and regional AOP enforcement agencies. |
| Genomic Screening Platform Integration | Compresses strain characterization timelines for artisan producers lacking laboratory infrastructure. |
Research Methodology
Operator-level perspectives from culture production microbiologists, AOP cheese consortium technical directors, dairy ingredient procurement managers, and artisan creamery owners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EFSA QPS registry filings, REACH enzymatic additive registrations, ANSM terroir enforcement documentation, and EU Green Deal agricultural biotechnology funding disclosures. Bottom-up strain-level demand modeling triangulated against top-down fermentation capacity assessments across European biotechnology hubs.
Scenario bracketing around EFSA novel strain approval timelines, REACH metabolite testing cost trajectories, and clean-label definitional evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include physical format, application matrix, end-user scale, and regional regulatory cluster. CAGRs derived from installed base growth rates, replacement demand cycles, and penetration assumptions for freeze-dried formats in cold-chain-constrained production zones. Industry-specific inputs incorporated AOP cheese production volume trends and plant-based dairy R&D pipeline acceleration.
Macroeconomic conditions sit as an overlay; deviation in EU agricultural subsidy allocation, biotechnology equipment import tariffs, or artisan dairy labor availability would shift the trajectory. Forecasts reflect documented assumptions on EFSA review duration stability and REACH enforcement consistency. Material shifts in clean-label regulatory interpretation or precision fermentation technology export controls would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Cultured Dextrose Market