
 Antibiotic Resistance Market | 2026-2036
Antibiotic Resistance Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotic Resistance Market Analysis
Project finance partnerships between biotech innovators and institutional investors is rewriting competitive access in the antibiotic resistance space. Pfizer leverages its manufacturing scale to supply broad-spectrum therapies across integrated delivery networks. Merck & Co. sustains one of the industry's deepest late-stage pipelines for carbapenem-resistant pathogens. Melinta Therapeutics anchors its position through specialized commercial infrastructure for hospital-administered anti-infectives.
Antibiotic resistance encompasses the biological capacity of bacterial pathogens to survive therapeutic concentrations of antimicrobial agents, measured clinically through minimum inhibitory concentration thresholds and resistance gene profiling via PCR-based diagnostics. The phenomenon threatens standard-of-care treatments across surgery, oncology, and transplantation medicine, elevating mortality risk and extending hospital stays. Broad-spectrum antibiotics dominate current revenue pools due to empiric prescribing protocols in sepsis management, while narrow-spectrum alternatives capture fastest-growing demand as diagnostic-guided stewardship programs expand. Intravenous administration generates the majority of hospital-based value, though oral formulations gain traction in step-down therapy and outpatient parenteral antimicrobial programs.
The FDA's Qualified Infectious Disease Product designation and EMA's PRIME pathway for antibacterial therapies reshape clinical trial incentives and accelerated market access for novel mechanisms. The CDC's National Healthcare Safety Network mandates public reporting of resistant infection rates, directly tying reimbursement to stewardship performance. Stakeholders must monitor how diagnostic-adjacent reimbursement reforms alter prescribing economics and whether pull-incentive legislation stabilizes commercial returns for new antibiotic classes.
Market Dynamics
Diagnostic-guided antimicrobial stewardship programs are compressing empiric prescribing windows and forcing hospitals to integrate rapid molecular testing into sepsis protocols, reshaping how resistance-mitigating therapies reach patients.
Growth Catalysts
- CMS antimicrobial stewardship mandates:Medicare reimbursement reforms tie hospital payments to documented compliance with CDC stewardship protocols, accelerating procurement of resistance-tracking infrastructure.
- Carbapenem-resistant Enterobacteriaceae spread:ICU and transplant units face rising mortality from CRE bloodstream infections, intensifying demand for novel beta-lactamase inhibitor combinations.
- Point-of-care PCR diagnostics:Cepheid and BioFire platforms now deliver resistance gene detection within 90 minutes, enabling same-day targeted therapy selection.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India control over 80% of generic antibiotic raw material supply, exposing formulators to export restriction risks and quality variability.
- Clinical trial recruitment barriers:FDA Qualified Infectious Disease Product pathways require documented treatment failures against standard-of-care, slowing enrollment in carbapenem-resistant pathogen studies.
- Oral bioavailability limitations:Gram-negative outer membrane permeability barriers restrict development of outpatient-compatible formulations for resistant Pseudomonas infections.
Strategic Opportunities
- Japan's AMR countermeasure legislation:METI and PMDA coordinated pull incentives guarantee minimum revenue thresholds for novel antibiotic classes entering the national formulary.
- Phage therapy convergence:Combination regimens pairing engineered bacteriophages with conventional antibiotics address biofilm-associated device infections in orthopedic and cardiac surgery.
- Subscription-based procurement pilots:NHS England's subscription model for antimicrobials decouples hospital payments from volume prescribed, stabilizing commercial returns for narrow-spectrum developers.
Industry Challenges
- Microbiology laboratory staffing shortages:Clinical laboratory scientist vacancies exceed 20% in US hospital systems, delaying susceptibility testing turnaround and stewardship program effectiveness.
- Legacy EHR integration complexity:Antibiotic decision support tools require custom HL7 FHIR mapping to Epic and Cerner installations, extending implementation timelines and IT capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotic Resistance Market |
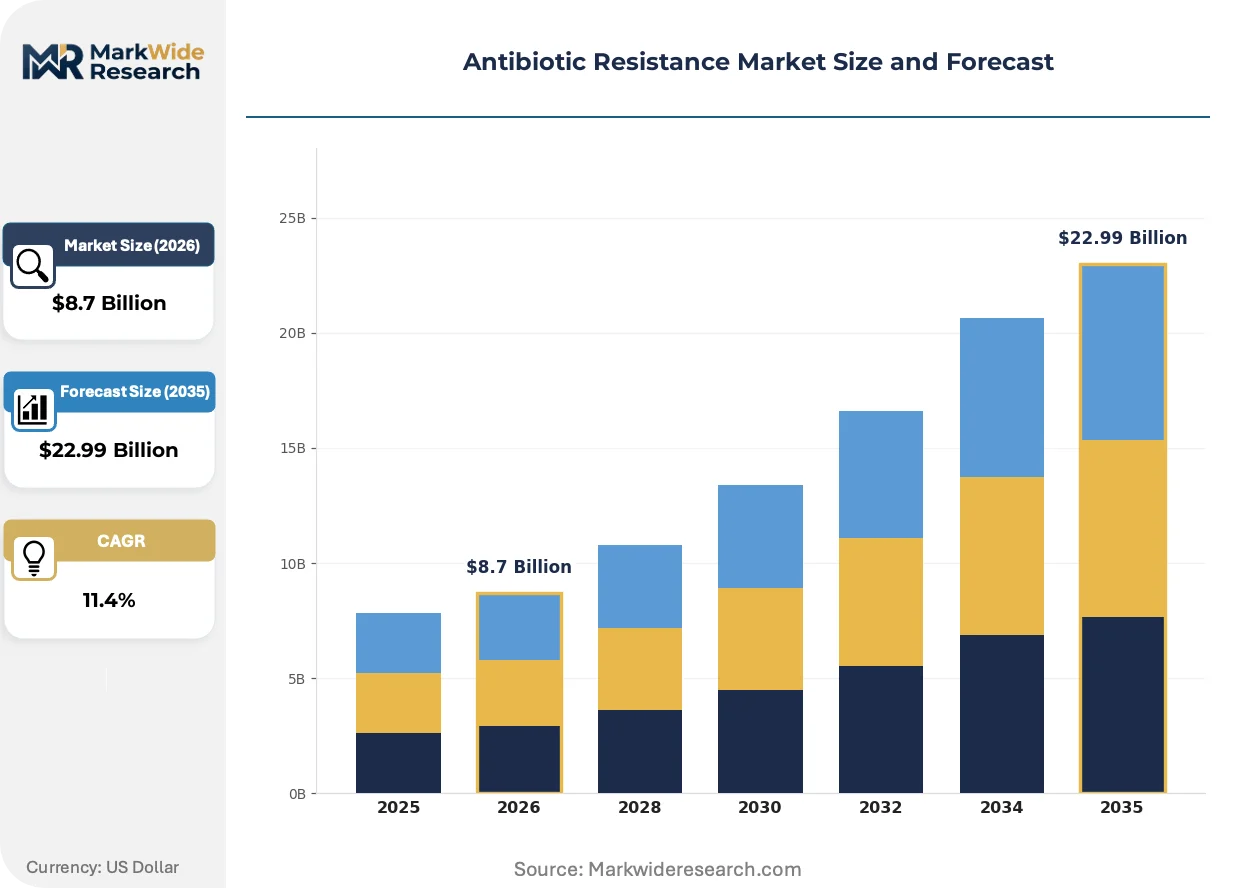
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broad-Spectrum Antibiotics, Narrow-Spectrum Antibiotics, Beta-Lactams, Glycopeptides End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutions Route of Administration: Oral, Intravenous, Topical, Inhalation Application: Infections, Surgical Prophylaxis, Cancer Treatment, Veterinary Use |
| Companies Covered | Pfizer, Merck & Co., AbbVie, Novartis, Johnson & Johnson, AstraZeneca, Melinta Therapeutics, Basilea Pharmaceutica, Theravance Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotic Resistance Market Emerging Trajectories
Artificial intelligence is compressing antibiotic discovery timelines by predicting resistance mutation pathways before clinical exposure occurs, while regulatory pull incentives and diagnostic-stewardship integration reshape commercialization models.
AI-driven resistance prediction platforms are virtualizing traditional high-throughput screening by modeling bacterial efflux pump evolution and target site modification before compound synthesis. Biotech discovery teams at institutions like MIT and Insitro deploy these tools to deprioritize candidates with elevated resistance potential. The approach collapses preclinical development cycles and redirects R&D expenditure toward mechanism-diverse chemical scaffolds.
REACH antimicrobial resistance environmental monitoring requirements in Europe now mandate pharmaceutical manufacturers to quantify manufacturing discharge into wastewater treatment systems. ECHA enforcement actions against Indian API suppliers have triggered supply chain audits and on-site effluent testing protocols. Formulators sourcing from European facilities face accelerated compliance timelines compared to Asian import-dependent competitors.
Hospital purchasing cooperatives are consolidating antibiotic procurement across integrated delivery networks, displacing individual facility contracting with multi-year enterprise agreements. Premier and Vizient now negotiate exclusive formulary placement for novel anti-infectives across 3,000+ member hospitals. This concentration is most pronounced in the United States, where IDN consolidation has reduced the number of independent procurement decision points by 40% since 2018.
Antibiotic Resistance Market Segmentation
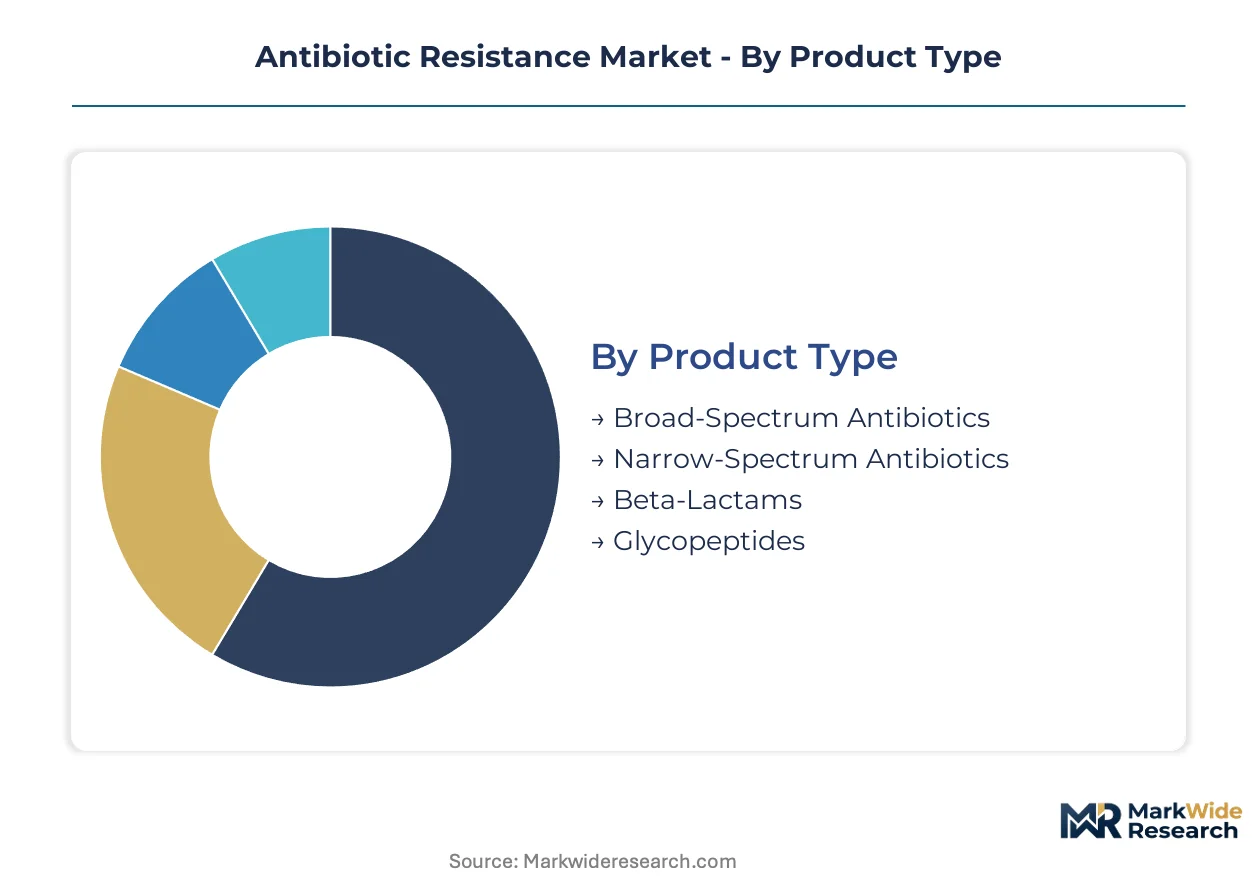
Antibiotic resistance markets fragment across therapeutic specificity, care setting, and delivery mechanism, with each axis determining reimbursement pathways, regulatory scrutiny, and commercial access. Understanding these divides reveals where diagnostic-stewardship integration concentrates procurement budgets and where novel mechanisms face adoption barriers.
Product Type:
Mature empiric therapies dominate hospital formularies while emerging targeted agents capture stewardship-driven substitution demand.
- Broad-Spectrum Antibiotics:Carbapenems, fluoroquinolones, and advanced-generation cephalosporins deliver empiric coverage against polymicrobial sepsis before susceptibility results return. US hospital systems allocate the largest procurement volumes here, though Medicare reimbursement reforms now penalize prolonged empiric prescribing without documented de-escalation.
- Narrow-Spectrum Antibiotics:Pathogen-specific agents including novel beta-lactamase inhibitor combinations and lipoglycopeptides target confirmed resistant infections. Demand concentrates in academic medical centers with rapid PCR diagnostic capabilities, where FDA Qualified Infectious Disease Product incentives accelerate formulary placement.
- Beta-Lactams:Penicillin derivatives and cephalosporins remain foundational for community-acquired infections with established susceptibility patterns.
- Glycopeptides:Vancomycin and teicoplanin analogs serve MRSA and enterococcal coverage in surgical prophylaxis and bloodstream infection protocols.
Broad-spectrum agents handle the majority of throughput; narrow-spectrum alternatives are expanding most quickly as diagnostic-guided protocols displace empiric paradigms.
End User:
Procurement authority concentrates in integrated delivery networks while decentralized settings face capital constraints for resistance-tracking infrastructure.
- Hospitals:Inpatient facilities command the largest antibiotic procurement volumes, with IDN consolidation reducing independent purchasing decision points. CMS antimicrobial stewardship mandates tie reimbursement directly to documented CDC protocol compliance, forcing capital allocation toward susceptibility testing infrastructure.
- Diagnostic Laboratories:Clinical and reference laboratories anchor resistance surveillance through molecular diagnostics and susceptibility testing services. US hospital systems face microbiologist staffing vacancies exceeding 20%, creating demand for automated platforms from Cepheid and BioFire.
- Clinics:Outpatient settings manage uncomplicated infections with oral formulations, constrained by limited on-site susceptibility testing.
- Research Institutions:Academic centers and contract research organizations drive early-phase resistance mechanism studies and novel scaffold evaluation.
Hospitals retain the majority of procurement authority; diagnostic laboratories are gaining share fastest as stewardship programs outsource resistance surveillance.
Route of Administration:
Delivery mode determines care setting economics, with intravenous protocols dominating inpatient reimbursement and oral alternatives enabling cost-saving step-down therapy.
- Intravenous:Hospital-administered formulations generate premium reimbursement under Medicare severity-adjusted diagnosis-related groups. Beta-lactamase inhibitor combinations and novel lipopeptides require IV delivery for Gram-negative coverage, anchoring value in ICU and transplant units.
- Oral:Bioavailable agents including fluoroquinolones and oxazolidinones enable outpatient parenteral antimicrobial therapy programs and early discharge protocols. Oral bioavailability limitations for resistant Pseudomonas coverage constrain development pipelines.
- Topical:Skin and soft tissue infection formulations serve wound care and surgical site prophylaxis in ambulatory settings.
- Inhalation:Aerosolized delivery targets respiratory pathogens in cystic fibrosis and ventilator-associated pneumonia protocols.
Intravenous administration captures the majority of hospital-based value; oral formulations are climbing the fastest as step-down therapy protocols expand.
Application:
Clinical use cases span curative treatment, preventive intervention, and adjuvant oncology support, each with distinct regulatory and reimbursement profiles.
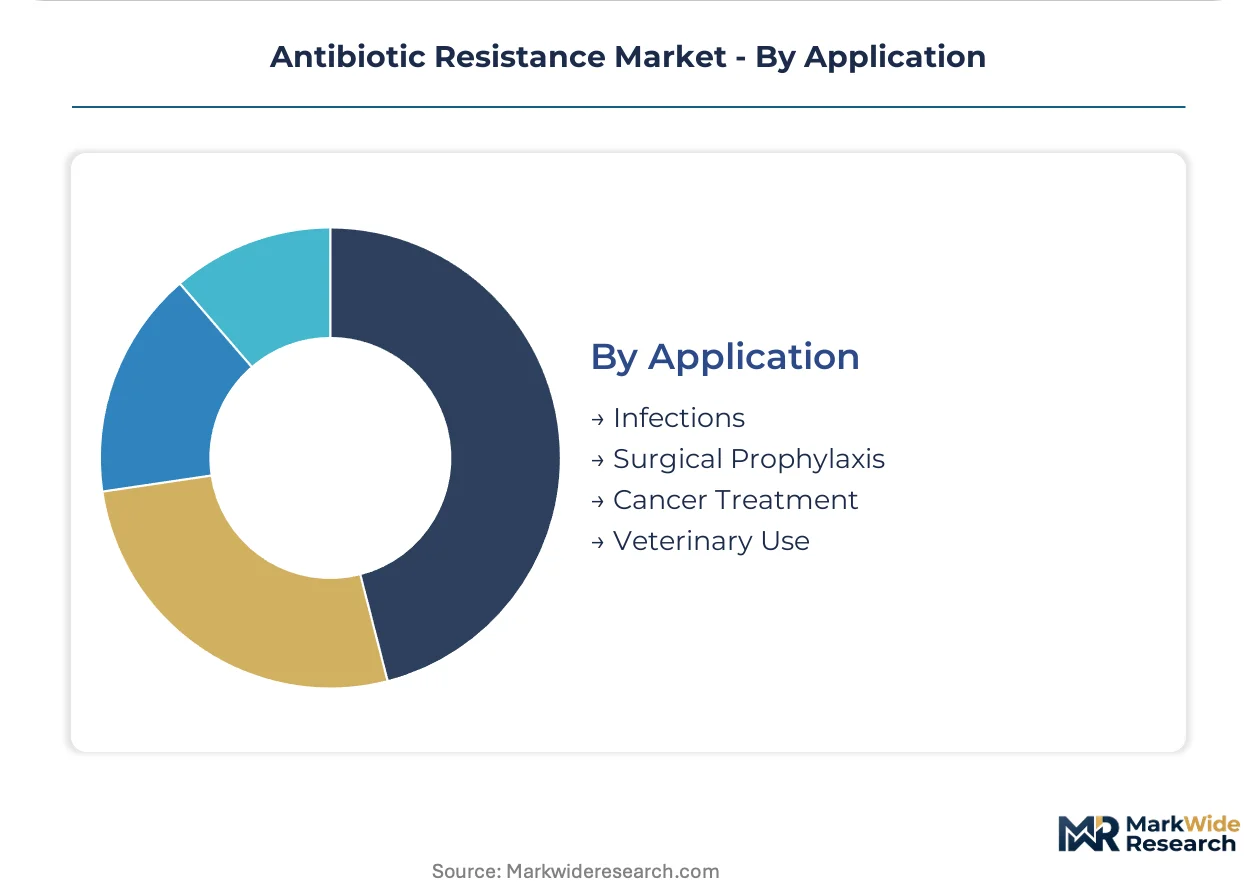
- Infections:Curative therapy for confirmed resistant pathogens including CRE bloodstream infections, complicated intra-abdominal infections, and hospital-acquired pneumonia. Carbapenem-resistant Enterobacteriaceae mortality pressures drive demand for novel beta-lactamase inhibitors in US academic medical centers.
- Surgical Prophylaxis:Preoperative and perioperative dosing protocols prevent surgical site infections in orthopedic, cardiac, and transplant procedures. Joint Commission accreditation standards mandate documented prophylaxis compliance.
- Cancer Treatment:Febrile neutropenia prophylaxis and treatment in myelosuppressed oncology patients, where resistant gram-negative infections elevate mortality risk.
- Veterinary Use:Agricultural and companion animal applications face distinct FDA and EMA regulatory pathways for resistance monitoring.
Infection treatment commands the majority of therapeutic volume; surgical prophylaxis is gaining share fastest as bundled payment models intensify SSI prevention incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's AMR countermeasure legislation guarantees minimum revenue thresholds for novel antibiotics entering the national formulary, establishing a template for pull-incentive programs worldwide. Germany's EMA-coordinated access pathways and stewardship mandates reshape procurement economics across European hospital networks. India's API manufacturing concentration exposes supply chains to regulatory enforcement actions under REACH environmental monitoring requirements.
United States
CMS antimicrobial stewardship mandates tie Medicare reimbursement directly to documented CDC protocol compliance, forcing hospital systems toward rapid diagnostic integration. The FDA's Qualified Infectious Disease Product designation accelerates novel beta-lactamase inhibitor approvals through priority review vouchers. Boston's academic medical corridor anchors carbapenem-resistant pathogen research, with Massachusetts General and Brigham and Women's driving stewardship program standardization.
Germany
EMA's PRIME pathway for antibacterial therapies compresses market access timelines for mechanism-diverse candidates targeting resistant Gram-negative infections. Germany's national antibiotic resistance strategy mandates hospital-level resistance surveillance reporting through the Robert Koch Institute. The Rhine-Main biotech cluster around Frankfurt hosts late-stage developers specializing in hospital-administered anti-infectives for ICU and transplant units.
Japan
METI-coordinated pull incentives guarantee minimum revenue thresholds for novel antibiotic classes, stabilizing commercial returns for narrow-spectrum developers. PMDA's Sakigake designation accelerates regulatory review for breakthrough antibacterial mechanisms addressing carbapenem-resistant Enterobacteriaceae. Tokyo's pharmaceutical corridor concentrates domestic stewardship program implementation, with Keio University Hospital serving as a national reference center for resistance surveillance.
India
Domestic API manufacturing dominance exposes formulators to ECHA enforcement actions against effluent discharge from antibiotic production facilities. CDSCO's tightening environmental compliance timelines force supply chain audits for European-sourced finished dosage forms. Hyderabad's bulk drug manufacturing belt faces accelerated wastewater testing protocols, with regional suppliers investing in zero-liquid discharge infrastructure to maintain export eligibility.
Switzerland
Swissmedic's streamlined antibacterial approval pathways attract developers seeking concurrent European market access for novel resistance-mitigating therapies. The country's pharmaceutical manufacturing base specializes in high-potency anti-infective production for global hospital supply. Basel's industrial cluster anchors beta-lactamase inhibitor combination manufacturing, with facilities serving integrated delivery networks across German-speaking European markets.
Antibiotic Resistance Market Vendor Landscape
On the supply side, the industry is consolidating around three structural tiers: multinational pharmaceutical conglomerates with manufacturing scale, specialized anti-infective developers with hospital-focused commercial infrastructure, and biotech innovators with late-stage resistance-targeting pipelines. Strategic archetypes include empiric therapy suppliers stewarding broad-spectrum formularies, narrow-spectrum specialists capturing diagnostic-guided substitution demand, and platform technology holders engineering novel beta-lactamase inhibitor combinations. Dominant competitive moves encompass subscription-based procurement pilots decoupling revenue from volume prescribed, and backward integration into active pharmaceutical ingredient production securing supply chain resilience against Asian export restrictions.
Within the multinational tier, Pfizer leverages manufacturing scale to supply broad-spectrum therapies across integrated delivery networks, while Merck & Co. sustains one of the industry's deepest late-stage pipelines for carbapenem-resistant pathogens. Melinta Therapeutics anchors the specialized commercial infrastructure archetype through dedicated hospital-administered anti-infective capabilities. These three represent distinct strategic positions: scale-driven empiric coverage, pipeline depth in resistant Gram-negatives, and focused commercial execution in institutional settings.
| Leading Market Players |
|---|
| Pfizer |
| Merck & Co. |
| AbbVie |
| Novartis |
| Johnson & Johnson |
| AstraZeneca |
| Melinta Therapeutics |
| Basilea Pharmaceutica |
| Theravance Biopharma |
| Others |
Supply Flow & Price Mechanics
China and India control over 80% of generic antibiotic active pharmaceutical ingredient output, anchoring margin capture upstream while finished dosage formulators in the United States and Europe compete on regulatory certification and stewardship compliance.
Pricing Analysis
Certification level creates the primary spread between FDA Qualified Infectious Disease Product-designated therapies and commodity generics. Subscription-based procurement pilots decouple hospital payments from volume prescribed, compressing transactional pricing for empiric broad-spectrum agents while stabilizing returns for narrow-spectrum innovators. Cost compression in the generic API tier intensifies as REACH environmental enforcement triggers supply chain audits. Academic medical centers with rapid PCR diagnostic capabilities show the least price sensitivity; community hospitals facing Medicare stewardship penalties exhibit the highest.
Supply Chain Analysis
Upstream fermentation feedstocks for beta-lactam and macrolide production concentrate in Shandong Province and the Hyderabad bulk drug belt. Key intermediate dependencies include 7-ACA for cephalosporins and 6-APA for penicillin derivatives, with purification reagents sourced from German and Swiss chemical specialists. Single-source vulnerability runs through Chinese export licensing protocols for fermentation capacity. Distribution runs through hospital purchasing cooperatives consolidating procurement across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antibiotic resistance markets are approaching a platform-economics inflection where diagnostic-stewardship integration creates interoperability standards that determine formulary access and reimbursement eligibility.
For Market Incumbents: Harden manufacturing scale advantages through backward integration into API production, securing captive supply against Indian and Chinese export restriction risks. Deepen hospital purchasing cooperative relationships to defend formulary placement as Premier and Vizient consolidate procurement authority across integrated delivery networks. FDA Qualified Infectious Disease Product certification investment remains the priority lever for pricing power preservation. For New Entrants and Emerging Players: Mid-tier community hospital systems in the United States represent the most penetrable entry point, as Medicare stewardship mandates force capital allocation toward rapid diagnostic platforms without established narrow-spectrum formularies. Japan's METI-coordinated pull incentive program offers guaranteed revenue thresholds for novel antibiotic classes entering the national formulary. A go-to-market angle pairing engineered bacteriophage combination regimens with conventional antibiotics addresses biofilm-associated device infections in orthopedic surgery. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across late-stage beta-lactamase inhibitor combination development, as FDA treatment failure documentation requirements extend clinical trial timelines and enrollment costs. Acquisition targets should prioritize specialized anti-infective developers with dedicated hospital-administered commercial infrastructure and existing formulary relationships. The signal to watch is NHS England subscription model expansion, which would validate decoupled-revenue commercialization at scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Production | Reduces exposure to Chinese export licensing volatility for fermentation capacity. |
| Diagnostic-Stewardship Platform Integration | Positions therapies for same-day targeted selection via Cepheid and BioFire PCR systems. |
| Subscription-Based Procurement Pilot Expansion | Validates decoupled revenue models through NHS England and Japan METI pull incentives. |
| Phage Therapy Combination Development | Addresses biofilm-associated orthopedic and cardiac device infections resistant to standard protocols. |
| Hospital Purchasing Cooperative Consolidation | Captures formulary placement across 3,000+ member hospitals through Premier and Vizient agreements. |
Methodological Framework
A standing panel of hospital formulary directors, antimicrobial stewardship program leads, infectious disease clinicians, and GPO contracts managers provided ongoing calibration against secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Primary interviews with regulatory affairs specialists at biotech innovators and procurement executives at integrated delivery networks were triangulated with bottom-up segment sizing and top-down market reconciliation.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning therapeutic specificity, route of administration, care setting, and regional regulatory cluster. CAGRs were derived from modeled adoption curves for diagnostic-guided stewardship programs and pull-incentive policy implementation. Forecast inputs incorporated CMS antimicrobial stewardship mandate compliance rates and PMDA Sakigake designation timelines.
Practitioners should monitor FDA Qualified Infectious Disease Product approval velocity and REACH enforcement actions against Indian API suppliers for early signals of supply constraint or regulatory acceleration. Quarterly review of hospital microbiology laboratory staffing vacancy rates and rapid diagnostic platform installation timelines is advised to detect inflection in stewardship program effectiveness and narrow-spectrum substitution demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
Microbial Rennet Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Eubiotics Market