
 Menopause Treatment Market | 2026-2036
Menopause Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Menopause Treatment Market Outlook
Aftermarket service revenue from patient monitoring and adherence programs is fragmenting across competing platforms. AbbVie Inc. leverages its established endocrinology infrastructure to sustain pharmacy-led distribution networks. Pfizer Inc. anchors its position through manufacturing scale in hormonal active pharmaceutical ingredients. TherapeuticsMD, Inc. specializes in novel delivery formulations that differentiate its portfolio from conventional oral therapies.
Menopause treatment encompasses pharmacological and non-pharmacological interventions designed to alleviate vasomotor symptoms, genitourinary syndrome, and metabolic changes associated with ovarian hormone decline, with hormone replacement therapy typically combining estrogen and progestin at standardized dosages adjusted to patient risk profiles. The primary commercial purpose centers on symptom management and long-term bone and cardiovascular health maintenance in perimenopausal and postmenopausal populations. Hormone replacement therapy occupies the largest revenue pool due to decades of clinical validation and prescriber familiarity, while non-hormonal treatments represent the fastest-expanding category as breast cancer survivors and contraindicated patients seek alternatives. Homecare settings are gaining share as self-administered patches and topical creams reduce dependency on clinical visits.
The FDA oversees hormone therapy safety labeling and post-market surveillance, while the EMA's Pharmacovigilance Risk Assessment Committee monitors thromboembolic signals across European markets, and the WHO maintains menopause management guidelines that influence national formulary inclusion in emerging markets. These frameworks elevate documentation burdens for new entrants but also create compliance-based moats for established manufacturers with robust pharmacovigilance systems. Stakeholders must weigh investment timing between next-generation bioidentical formulations and digital therapeutics platforms as reimbursement pathways for non-pharmaceutical interventions crystallize.
Market Dynamics
Telehealth platforms are fragmenting patient acquisition channels and compressing the traditional clinic-pharmacy-patient pathway into direct digital fulfillment models. This structural shift forces incumbents to rebuild distribution architectures around consumer-facing interfaces rather than prescriber networks.
Growth Catalysts
- FDA Labeling Modernization:The FDA's updated hormone therapy safety guidance reduces prescriber liability concerns and accelerates new formulation approvals for bioidentical combinations.
- Telehealth Infrastructure:Direct-to-consumer platforms bypass geographic access barriers and capture patient cohorts previously underserved by gynecology clinic density gaps in rural United States counties.
- Breast Cancer Survivor Demand:Non-hormonal therapeutic categories expand as oncologists refer contraindicated patients to specialized menopause management protocols.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Hormonal API manufacturing clusters in China and India create supply vulnerability to export licensing disruptions and geopolitical friction.
- EMA Pharmacovigilance Burden:The EMA's Pharmacovigilance Risk Assessment Committee mandates costly thromboembolic signal monitoring that elevates post-market surveillance expenses for European market entrants.
- Compounding Pharmacy Substitution:Customized bioidentical hormone preparations from 503A facilities capture price-sensitive patients seeking alternatives to manufactured dosage forms.
Strategic Opportunities
- Digital Therapeutics Reimbursement:United States payers are piloting coverage for cognitive behavioral therapy apps targeting vasomotor symptom management, creating a pharmaceutical-adjacent revenue pool.
- Genitourinary Syndrome Undertreatment:Vaginal estrogen and laser therapy penetration remains below twenty percent among symptomatic postmenopausal populations in Germany and France.
- Homecare Delivery Convergence:Self-administered transdermal patches and topical formulations reduce clinical visit dependency and align with Medicare Advantage remote monitoring incentives.
Industry Challenges
- Menopause-Specific Clinical Trial Design:Regulatory agencies lack standardized endpoints for non-hormonal vasomotor symptom therapies, prolonging Phase III protocol negotiations.
- Pharmacovigilance System Integration:Legacy adverse event reporting infrastructure requires expensive retrofitting to capture real-world evidence from wearable biosensors and patient-reported outcome platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menopause Treatment Market |
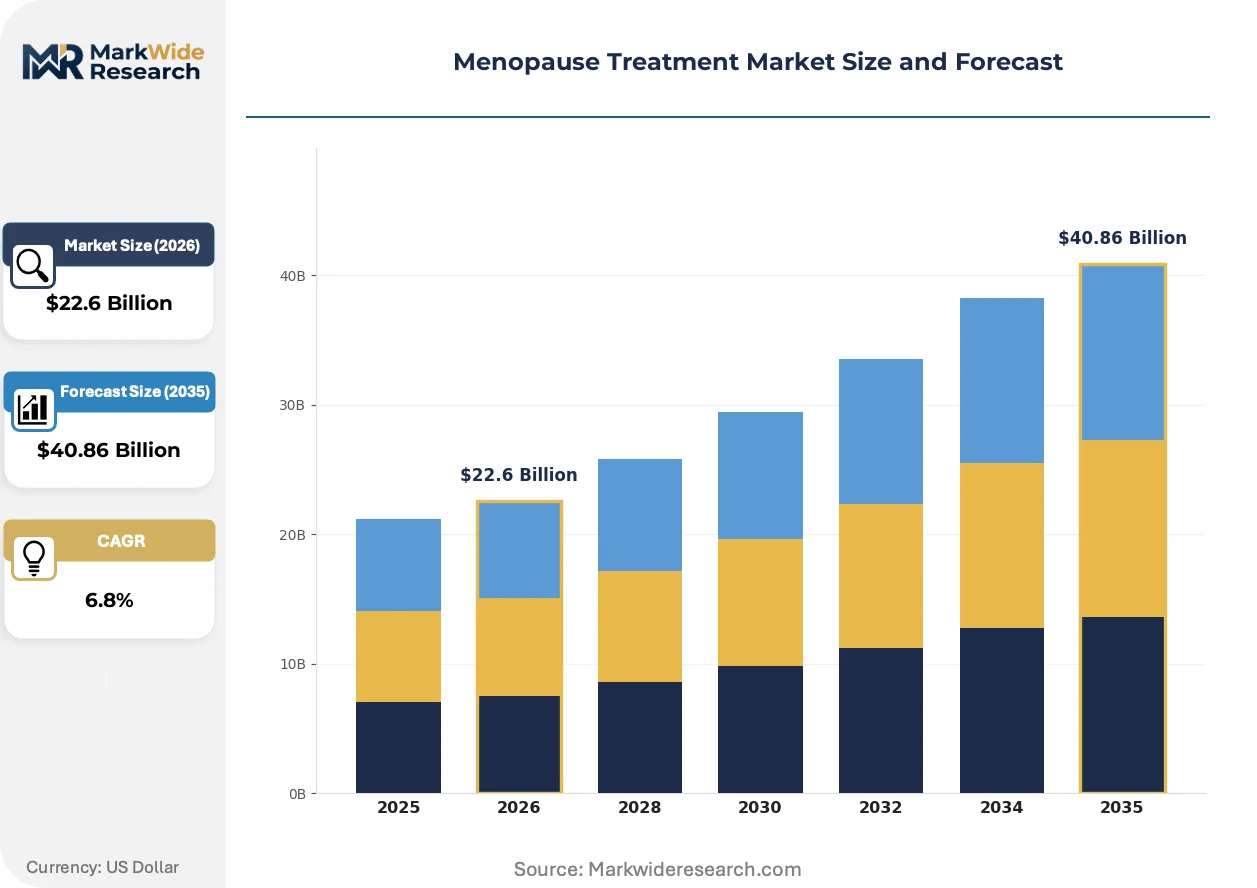
| Market Size in 2026 | $22.6 Billion |
| Market Size in 2035 | $40.86 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Replacement Therapy, Non-Hormonal Treatments, Herbal Supplements, Lifestyle Products Delivery Mode: Oral Tablets, Patches, Injections, Topical Creams End User: Hospitals, Clinics, Homecare Settings, Pharmacies Age Group: 40-45 Years, 46-50 Years, 51-55 Years, 56+ Years |
| Companies Covered | AbbVie Inc., Astellas Pharma Inc., Bayer AG, Pfizer Inc., Novartis AG, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Eli Lilly and Company, TherapeuticsMD, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menopause Treatment Market Strategic Shifts
Bioidentical hormone formulations are converging with digital adherence monitoring to create closed-loop therapeutic ecosystems. This convergence redefines competitive advantage around data capture rather than molecular innovation alone.
Transdermal delivery systems are hybridizing estrogen absorption kinetics with connected patch technologies that transmit dosing confirmation to prescriber dashboards. Gynecology clinics in the United States are piloting these platforms to reduce follow-up visit volume. The technology is compressing reimbursement models toward episode-based payment structures that reward adherence outcomes over prescription volume.
REACH regulatory updates in Europe are tightening purity specifications for hormonal active pharmaceutical ingredients, forcing API suppliers to retool solvent recovery systems. Manufacturers serving EMA-regulated markets face eighteen-month compliance timelines that favor established players with dedicated regulatory affairs infrastructure. Bioidentical formulation specialists are responding by consolidating European manufacturing footprints to reduce cross-border certification complexity.
Patient acquisition through employer-sponsored benefits platforms is displacing traditional pharmacy benefit manager channels for menopause management services. Large self-insured employers in the United States are contracting directly with telehealth providers to reduce specialty pharmacy spend. This behavioral shift concentrates volume with platforms capable of integrating medical and pharmacy claims data for population health reporting.
Menopause Treatment Market Segmentation
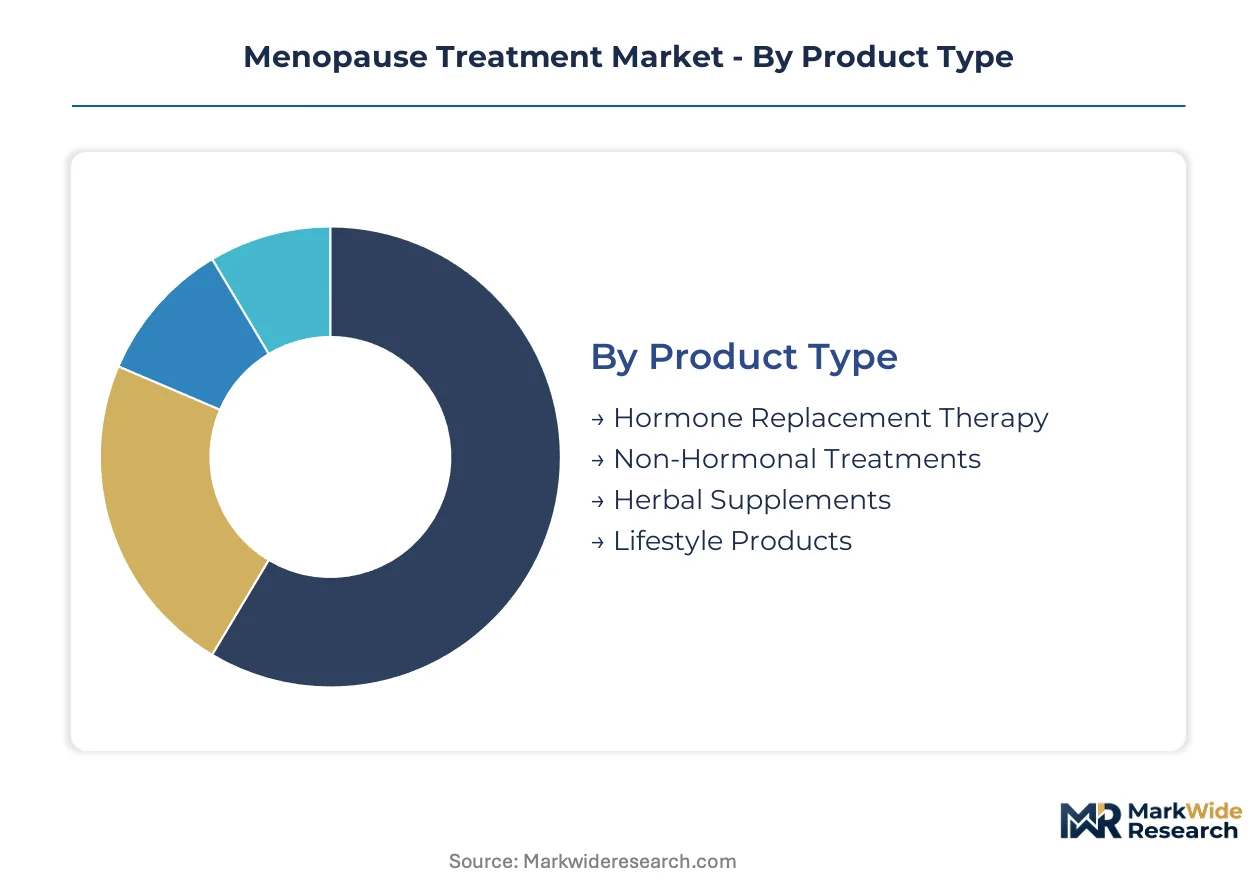
Menopause treatment segmentation reveals divergent commercial rhythms across product categories. Prescription hormonal therapies cycle through patent cliffs and biosimilar entry, while digital adherence platforms and homecare delivery systems are compressing traditional replenishment timelines.
Product Type:
Hormone Replacement Therapy turns inventory fastest through established pharmacy channels, whereas Herbal Supplements move slowest due to consumer trial cycles and regulatory ambiguity.
- Hormone Replacement Therapy:Synthetic and bioidentical estrogen-progestin combinations administered in standardized or personalized dosing protocols. United States gynecology clinics drive volume through insured prescription pathways, though FDA labeling updates are accelerating prescriber re-education requirements.
- Non-Hormonal Treatments:Selective serotonin reuptake inhibitors, gabapentinoids, and novel neurokinin-3 receptor antagonists targeting vasomotor symptoms without hormonal exposure. Breast cancer survivor populations in Germany and France are expanding this segment fastest as oncologist referrals multiply.
- Herbal Supplements:Phytoestrogen compounds and botanical preparations including black cohosh and red clover extracts. European markets show regulatory fragmentation as EFSA health claim evaluations lag commercial innovation.
- Lifestyle Products:Cooling devices, moisture-wicking textiles, and sleep optimization systems addressing symptom management without pharmacological intervention. Direct-to-consumer telehealth platforms in the United States are bundling these with subscription care models.
Hormone Replacement Therapy dominates installed base. Non-Hormonal Treatments are where expansion concentrates.
Delivery Mode:
Cost tiering separates premium connected patches from economy oral generics, with reimbursement differentials widening the pricing spread.
- Oral Tablets:First-line systemic hormone delivery in fixed-dose and variable-dose formulations. Medicare Advantage plans in the United States favor this modality for formulary simplicity, though first-pass hepatic metabolism elevates thromboembolic risk profiles.
- Patches:Transdermal estrogen absorption systems enabling steady-state plasma levels with reduced hepatic impact. Homecare adoption is climbing fastest as self-administration protocols align with remote monitoring incentives.
- Injections:Depot formulations providing extended-release hormone delivery for compliance-challenged patients. Clinical administration requirements limit this segment to hospital and specialty clinic settings.
- Topical Creams:Localized estrogen delivery for genitourinary syndrome with minimal systemic absorption. French and German markets show underpenetration below symptomatic population prevalence.
Oral Tablets dominate installed base. Patches are climbing the fastest.
End User:
Patient acquisition costs vary threefold across settings, with telehealth-enabled homecare compressing traditional clinic economics.
- Hospitals:Acute care and surgical menopause management requiring intravenous or monitored hormone protocols. United States health systems are consolidating these services into dedicated women's health pavilions.
- Clinics:Gynecology and endocrinology practices providing longitudinal menopause management. Rural United States counties face access gaps that telehealth platforms are exploiting.
- Homecare Settings:Self-administered therapies with remote prescriber oversight through connected devices. Medicare Advantage remote monitoring incentives are accelerating this channel's volume capture.
- Pharmacies:Dispensing nodes for prescription therapies with adherence counseling. Independent 503A compounding pharmacies are siphoning price-sensitive patients from manufactured dosage forms.
Clinics dominate installed base. Homecare Settings are gaining share fastest.
Age Group:
Symptom severity and treatment persistence create margin differentiation across life-stage cohorts.
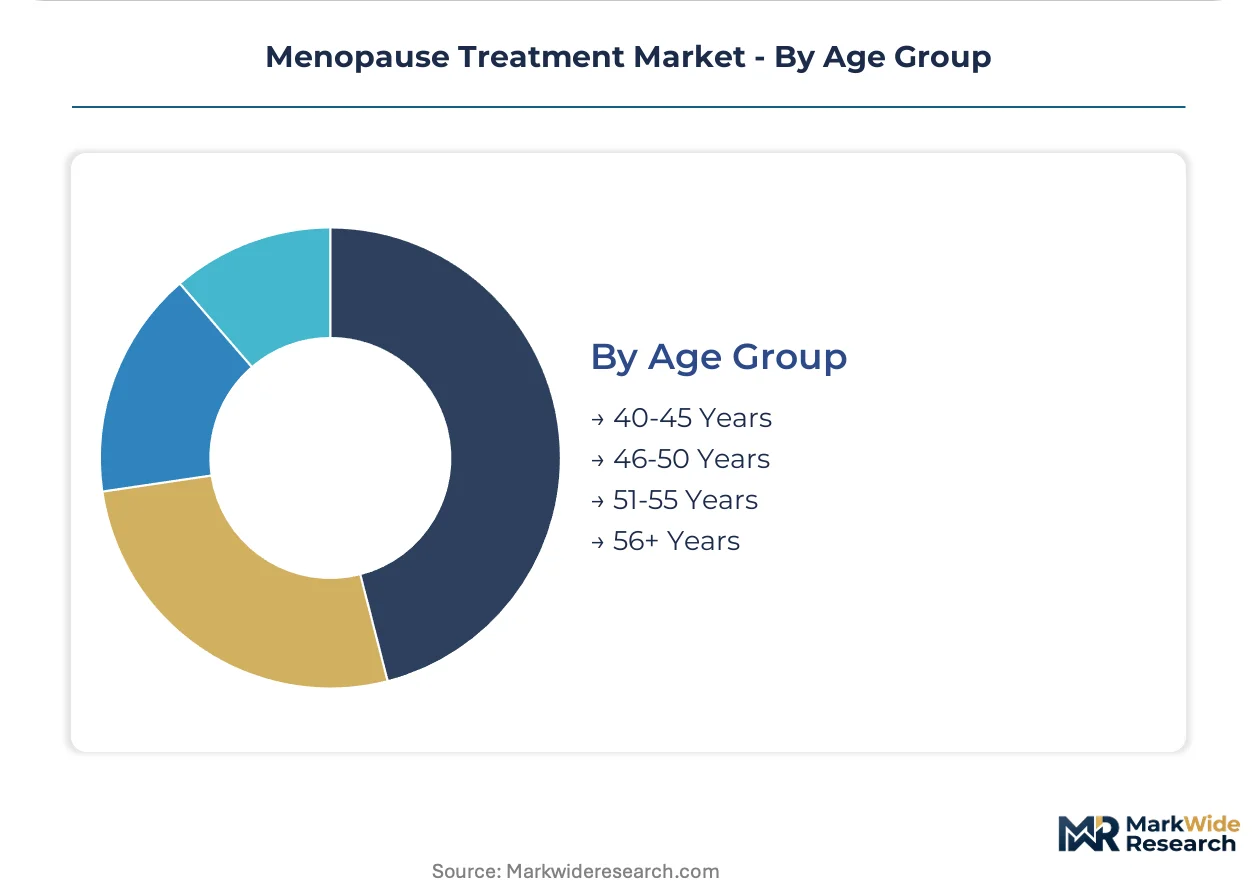
- 40-45 Years:Perimenopausal onset with irregular cycling and early vasomotor symptoms. United States employer-sponsored benefits platforms are targeting this cohort for early intervention programs.
- 46-50 Years:Peak symptom burden with amenorrhea transition and metabolic shifts. This cohort shows highest treatment persistence and pharmaceutical spending intensity.
- 51-55 Years:Established postmenopausal status with genitourinary syndrome emergence. German and French markets show undertreatment of vaginal estrogen indications in this bracket.
- 56+ Years:Long-term bone and cardiovascular health maintenance with reduced acute symptom management. Medicare reimbursement frameworks dominate purchasing decisions in the United States.
46-50 Years dominates installed base. 40-45 Years is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with the United States favoring telehealth-enabled direct fulfillment while European markets retain clinic-centric prescribing traditions and Asian markets show accelerating uptake of non-hormonal alternatives.
United States
Telehealth platforms and employer-sponsored benefits are compressing patient acquisition timelines, while Medicare Advantage remote monitoring incentives accelerate homecare adoption. FDA labeling modernization for hormone therapy reduces prescriber liability barriers. Boston and San Francisco clusters host digital therapeutics pilots integrating wearable biosensors with adherence programs.
Germany
Genitourinary syndrome undertreatment persists despite high symptomatic prevalence, creating expansion headroom for localized estrogen therapies. EMA Pharmacovigilance Risk Assessment Committee mandates elevate post-market surveillance costs for new entrants. The Rhine-Ruhr metropolitan region concentrates gynecology clinic networks piloting connected patch technologies.
France
Breast cancer survivor populations drive non-hormonal treatment demand through oncologist referral pathways. ANSM vigilance requirements for thromboembolic signal monitoring shape product development priorities. Paris and Lyon host specialized menopause management centers consolidating regional referral volumes.
United Kingdom
NHS formulary negotiations constrain pricing for novel bioidentical formulations, favoring established manufacturers with pharmacoeconomic evidence packages. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for digital therapeutics. London's Harley Street medical district concentrates private menopause specialist practices.
Japan
Aging demographics and cultural stigma reduction expand addressable patient pools beyond traditional urban centers. PMDA guidelines for hormone therapy safety labeling align with international standards while maintaining domestic specificity. Tokyo and Osaka clusters concentrate pharmaceutical R&D partnerships targeting neurokinin-3 receptor antagonists.
Menopause Treatment Market Competitive Environment
Capability concentration sits with formulation specialists possessing novel delivery technologies; scale advantage sits with diversified pharmaceutical conglomerates commanding API manufacturing and distribution infrastructure. The market structures around three tiers: integrated multinationals with endocrinology portfolios, mid-cap bioidentical specialists, and emerging digital therapeutics platforms. Dominant competitive moves include vertical integration into hormonal API supply and strategic partnerships with telehealth fulfillment networks.
Within the multinational tier, AbbVie Inc., Pfizer Inc., and TherapeuticsMD, Inc. occupy distinct positioning archetypes. AbbVie leverages established pharmacy-led distribution networks sustained through endocrinology infrastructure depth. Pfizer anchors manufacturing scale in hormonal active pharmaceutical ingredients. TherapeuticsMD exemplifies the formulation-specialist archetype through novel delivery system differentiation from conventional oral therapies.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Astellas Pharma Inc. |
| Bayer AG |
| Pfizer Inc. |
| Novartis AG |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Eli Lilly and Company |
| TherapeuticsMD, Inc. |
| Others |
Value Chain & Pricing Dynamics
Shanghai-to-Rotterdam container freight corridors transmit cost volatility from hormonal API manufacturing clusters to downstream price differentiation between bioidentical formulations and synthetic alternatives. This logistics dynamic concentrates margin pressure on mid-tier manufacturers while rewarding established players with captive supply arrangements and regulatory certification depth.
Pricing Analysis
Long-term offtake contracts dominate hormone replacement therapy procurement between API manufacturers and finished dosage form producers, though spot purchasing persists for specialized bioidentical ingredients. Three-tier pricing structure across premium connected patches, standard transdermal systems, and economy oral generics reflects FDA certification tier and manufacturing scale. Cost compression in the oral generic segment is intensifying because 503A compounding pharmacies capture price-sensitive patients with customized formulations. Employer-sponsored benefits platforms show lowest price sensitivity due to integrated medical-pharmacy claims bundling, while uninsured direct-to-consumer purchasers drive hardest bargain negotiations.
Supply Chain Analysis
Contract manufacturing concentration for hormonal APIs sits with specialized producers in China, India, and select European facilities certified for EMA-regulated markets. Estrogen and progestin active pharmaceutical ingredients draw from steroid precursor feedstocks sourced through concentrated chemical synthesis clusters. Single-source vulnerability from export licensing disruptions in key manufacturing jurisdictions poses structural risk to formulation continuity. Distribution runs through pharmacy-led networks for prescription therapies, though telehealth platforms are fragmenting fulfillment pathways toward direct-to-patient models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Menopause treatment markets reward defensive positioning through regulatory entrenchment, where FDA and EMA pharmacovigilance compliance creates compliance-based moats that new entrants cannot rapidly replicate.
For Market Incumbents: Harden market position through backward integration into hormonal API supply and consolidation of European manufacturing footprints to reduce cross-border certification complexity. Compounding pharmacy substitution threatens manufactured dosage form volumes, requiring channel control investments in telehealth platform partnerships. Certification depth in EMA Pharmacovigilance Risk Assessment Committee compliance serves as the priority defensive lever. For New Entrants and Emerging Players: Pursue white-space expansion in genitourinary syndrome undertreatment across Germany and France, where vaginal estrogen penetration remains below symptomatic population prevalence. Non-hormonal therapeutic categories offer most penetrable entry path through oncologist referral networks serving breast cancer survivor populations. Direct-to-consumer telehealth bundling with lifestyle products provides differentiated go-to-market angle against established pharmacy channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core women's health assets with underutilized endocrinology infrastructure. Five-to-ten year viability favors formulation specialists possessing novel delivery technologies and established pharmacovigilance systems. Signal to watch is reimbursement pathway crystallization for digital therapeutics platforms targeting vasomotor symptom management.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA labeling modernization for bioidentical combinations accelerates prescriber re-education and formulary access. |
| Manufacturing Scale-Up | REACH regulatory updates in Europe force eighteen-month API purity compliance timelines favoring established players. |
| Strategic Partnership | Telehealth platform alliances compress traditional clinic-pharmacy-patient pathways into direct digital fulfillment models. |
| Pipeline Diversification | Neurokinin-3 receptor antagonist development targets non-hormonal vasomotor symptom management for contraindicated patients. |
| Geographic Expansion | Medicare Advantage remote monitoring incentives accelerate homecare adoption in United States rural counties. |
Study Parameters
Operator-level perspectives from gynecology clinic administrators, formulary directors at United States payers, regulatory affairs leads at hormonal API manufacturers, and telehealth platform executives anchored the qualitative base. Primary interviews combined with secondary validation from FDA filings, EMA Pharmacovigilance Risk Assessment Committee reports, ClinicalTrials.gov protocols, and Medicare Advantage plan documents. Bottom-up prescription volume modeling and top-down pharmaceutical spending triangulation cross-verified segment estimates.
Scenario-bracketing framed demand projections across the analysis window through sensitivity testing of telehealth adoption rates and reimbursement pathway evolution. Segmentation dimensions modeled include product type, delivery mode, end-user setting, and age cohort with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of historical prescription patterns adjusted for demographic shift projections and regulatory event impacts. Forecast inputs incorporated FDA labeling update implementation timelines and EMA compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, employer-sponsored benefits spending, or pharmaceutical trade policy would shift the trajectory. Forecasts reflect documented assumptions regarding telehealth platform penetration and digital therapeutics reimbursement crystallization. Quarterly review of FDA adverse event reporting system signals and EMA pharmacovigilance database entries is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Lung Cancer Surgery Market
Medical Treatment
Inguinal Hernia Market
Medical Treatment
House Dust Mite Allergy Treatment Market
Medical Treatment
Myasthenia Gravis Treatment Market
Medical Treatment
Babesiosis Treatment Market
Medical Treatment
Prion Disease Treatment Market
Medical Treatment
Nose Reconstruction Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Global Rotator Cuff Treatment Market
Medical Treatment
Severe Asthma Treatment Market
Medical Treatment
Nasal Allergy Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Ventral Hernia Treatment Market