
 US AI in Fintech Market | 2026-2036
US AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
US AI in Fintech Market Insights
Buyer concentration among US financial institutions is broadening beyond money-center banks to encompass regional lenders and neobanks. JPMorgan Chase leverages massive proprietary datasets to train fraud-detection models that sustain operational cost advantages. Goldman Sachs anchors its Marcus platform with machine learning-driven personalization, while Upstart Holdings competes using alternative-data credit scoring that differentiates approval rates from FICO-dependent rivals.
US AI in Fintech deploys computational systems—encompassing supervised learning pipelines, natural language processing engines, and robotic process automation bots—to automate decisions, detect anomalies, and personalize financial services at scale. These systems process structured transactional data and unstructured customer communications to reduce latency in credit adjudication and compliance monitoring. Fraud Detection applications dominate current deployment volumes across banking institutions, while Predictive Analytics solutions capture expanding margin pools as investment firms demand real-time portfolio risk signals. Machine Learning technology leads implementation spend, though Natural Language Processing is accelerating fastest as chatbot and voice-interface adoption spreads among payment processors.
The SEC scrutinizes AI-driven investment advice under fiduciary standards, while the CFPB enforces fair-lending protocols that shape model explainability requirements for credit decisions. State regulators in New York and California layer supplementary algorithmic-audit obligations onto federally chartered institutions. Stakeholders must monitor evolving supervisory guidance on third-party AI vendor risk as banking agencies finalize interagency framework expectations.
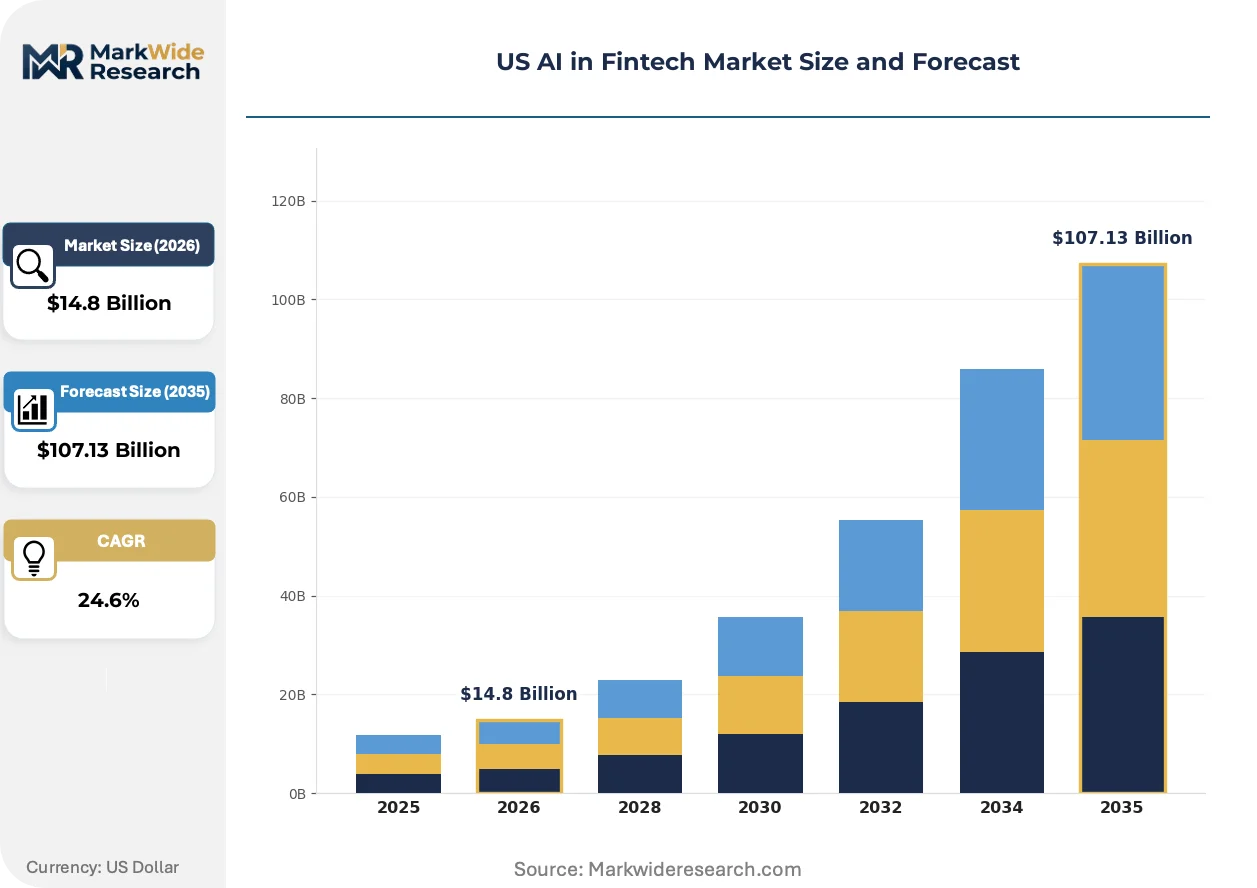
Market Dynamics
The CFPB's fair-lending enforcement is compressing deployment timelines for explainable AI models across US credit underwriting, forcing institutions to retrofit black-box algorithms with interpretable decision pathways before regulatory examination cycles.
Growth Catalysts
- Cloud-based AI tooling:Lower infrastructure barriers enable community banks and credit unions to deploy fraud-detection systems previously accessible only to money-center institutions.
- SEC fiduciary scrutiny:Heightened oversight of robo-advisory algorithms accelerates demand for compliant, auditable investment recommendation engines.
- Alternative data integration:Cash-flow analytics and employment-verification APIs expand addressable borrower pools beyond FICO-dependent scoring models.
Market Restraints
- GPU supply concentration:Training infrastructure dependence on Taiwan-based semiconductor fabrication creates procurement bottlenecks for model development pipelines.
- State regulatory fragmentation:California's algorithmic-audit obligations layer atop federal CFPB requirements, multiplying compliance engineering costs for multi-state lenders.
- Legacy core system lock-in:Mainframe-dependent regional banks face integration friction that slows real-time inference deployment.
Strategic Opportunities
- Midwestern community bank penetration:Nebraska, Iowa, and Kansas credit unions remain underserved by AI-native vendors despite rising fraud losses.
- Voice-interface payment authorization:NLP-driven biometric authentication is converging with contactless point-of-sale terminals to reduce card-not-present fraud.
- IRA green-lending incentives:Tax credits for residential energy-efficiency financing create demand for automated collateral valuation models.
Industry Challenges
- ML engineering talent scarcity:Model-risk-management expertise sufficient for regulatory defense remains concentrated among coastal financial centers.
- Third-party vendor oversight:Banking agencies' pending interagency framework on AI vendor risk forces institutions to renegotiate liability terms with cloud providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US AI in Fintech Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $107.13 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Risk Management, Customer Insights, Personal Finance Technology: Machine Learning, Natural Language Processing, Robotic Process Automation, Blockchain Solution: Predictive Analytics, Chatbots, Credit Scoring Models, Wealth Management Tools End User: Banking Institutions, Investment Firms, Insurance Companies, Payment Processors |
| Companies Covered | JPMorgan Chase, Bank of America, Goldman Sachs, Wells Fargo, American Express, PayPal, Visa, Mastercard, Upstart Holdings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US AI in Fintech Market Trends and Innovations
Generative AI architectures are rewriting customer-interaction economics across US financial services, compressing call-center cost structures while introducing new model-governance obligations.
Large language models specialized for financial document parsing are converging with robotic process automation to extract unstructured data from loan applications and KYC documentation. Regional lenders in Texas and Florida are piloting these systems to compress underwriting cycle times from weeks to hours. The structural consequence is a compression of operational cost advantages previously held by institutions with massive back-office workforces.
The CFPB's circular on adverse-action notice requirements for AI credit decisions is forcing lenders to deploy counterfactual explanation engines that identify which input variables drove denials. Banks must now maintain model-documentation standards that satisfy both supervisory examination and private litigation defense. The consumer-lending segment is responding by shifting procurement toward vendors with pre-built regulatory compliance modules.
Neobank customers are demanding real-time, conversational money-management interfaces that displace static dashboard experiences. Payment processors are unbundling traditional bundled service contracts to offer API-first, usage-priced AI capabilities. This behavioral shift is most visible among digitally native consumers in New York and California metro corridors, where switching costs between fintech providers approach zero.
US AI in Fintech Market Segmentation
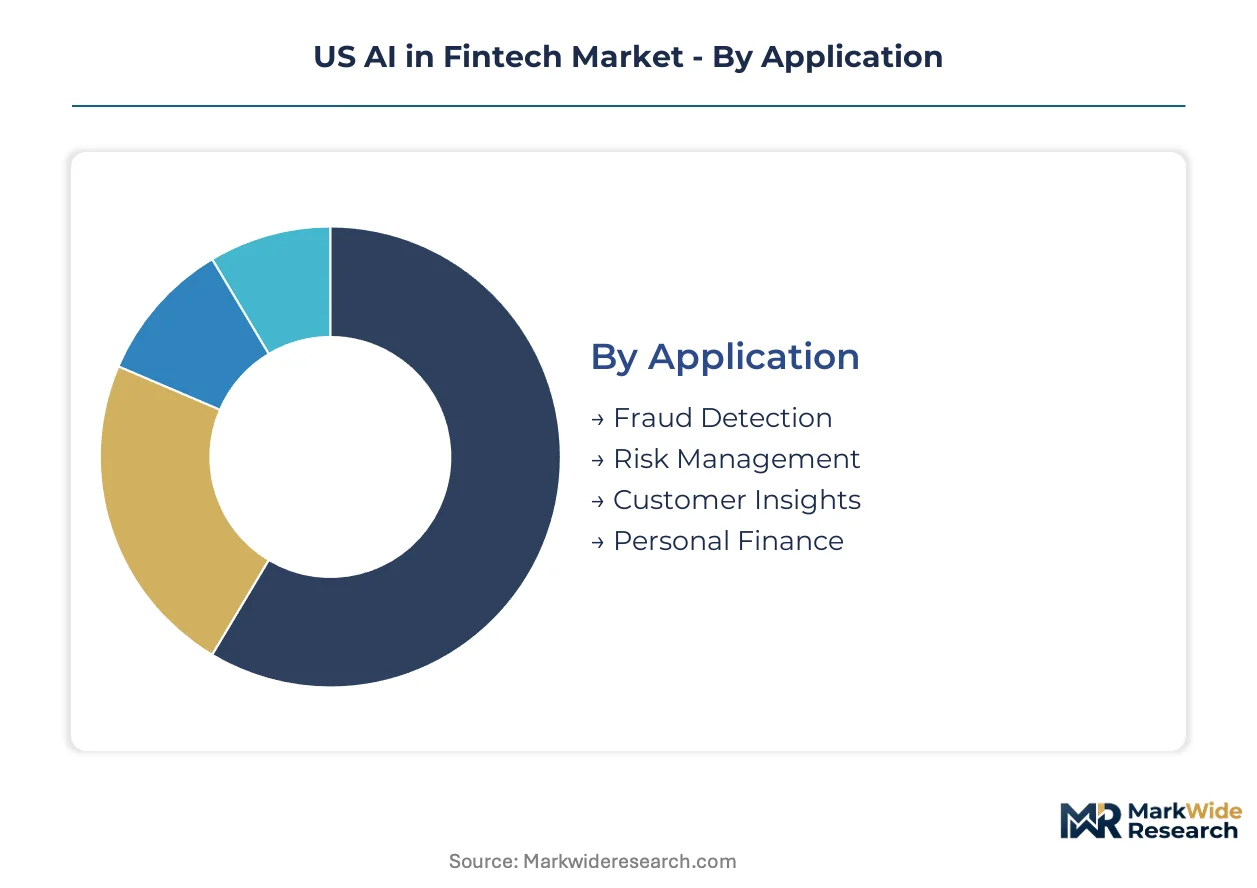
Segmentation reveals how AI deployment patterns diverge across technical architectures, use cases, and institutional buyer profiles. Understanding these divides exposes where procurement budgets concentrate and which solution categories face regulatory pressure.
Application:
Supply concentration in fraud-detection tooling dominates current procurement cycles as banks prioritize loss-prevention ROI over experimental deployments.
- Fraud Detection:Real-time transaction monitoring systems deploy supervised learning pipelines to flag anomalous payment patterns. JPMorgan Chase and regional banks in California cluster procurement here, driven by card-not-present loss escalation and CFPB scrutiny of inadequate controls.
- Risk Management:Portfolio stress-testing engines process macroeconomic scenarios to recalculate exposure concentrations. Investment firms in New York demand these systems as SEC fiduciary rules tighten on robo-advisory risk disclosures.
- Customer Insights:Behavioral segmentation models parse transaction histories to predict product propensity.
- Personal Finance:Automated budgeting engines aggregate cash-flow data across accounts to generate savings recommendations.
Today's leader: Fraud Detection. Tomorrow's challenger: Risk Management.
Technology:
Cost tiering separates mature machine-learning infrastructure from emerging natural-language-processing deployments requiring specialized GPU allocations.
- Machine Learning:Supervised and unsupervised algorithms power credit scoring, fraud detection, and portfolio optimization. Banking institutions absorb the majority of implementation spend here, though talent scarcity in model-risk management constrains rollout velocity.
- Natural Language Processing:Transformer architectures parse customer service transcripts and KYC documentation to extract structured data. Payment processors in Texas and Florida pilot voice-interface authentication, climbing the fastest as contactless biometric adoption accelerates.
- Robotic Process Automation:Software bots execute repetitive back-office workflows in loan origination and compliance reporting.
- Blockchain:Distributed-ledger smart contracts automate settlement and identity verification in cross-border payments.
Today's leader: Machine Learning. Tomorrow's challenger: Natural Language Processing.
Solution:
Volume concentration flows toward predictive analytics as investment firms demand real-time risk signals, while chatbot deployments expand among payment processors seeking cost compression.
- Predictive Analytics:Time-series forecasting engines project borrower default probabilities and market volatility regimes. Investment firms anchor procurement here, driven by margin pressure on active management fees.
- Chatbots:Conversational interfaces handle balance inquiries and payment disputes without human intervention. Neobanks in California and New York deploy these aggressively, gaining share fastest as switching costs between providers approach zero.
- Credit Scoring Models:Alternative-data algorithms incorporate cash-flow analytics and employment-verification APIs beyond FICO.
- Wealth Management Tools:Automated rebalancing engines adjust portfolio allocations based on risk-tolerance questionnaires.
Today's leader: Predictive Analytics. Tomorrow's challenger: Chatbots.
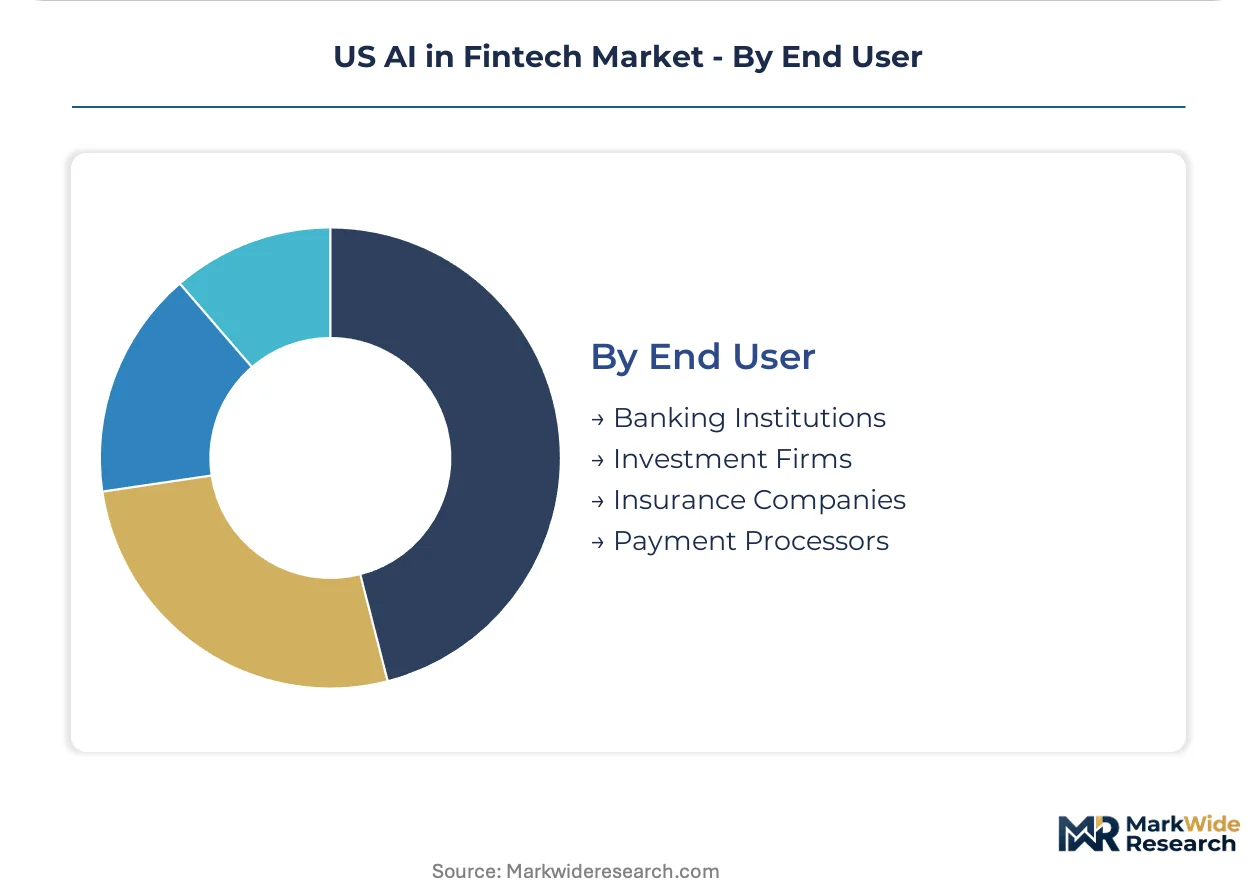
End User:
Customer-type maturity separates banking institutions with legacy core-system constraints from neobanks deploying cloud-native inference without technical debt.
- Banking Institutions:Money-center and regional banks deploy fraud detection and credit scoring at scale. Institutions in California and New York concentrate procurement, though Midwestern community banks in Nebraska and Iowa remain underserved.
- Investment Firms:Asset managers and broker-dealers demand predictive analytics for portfolio construction. SEC fiduciary enforcement accelerates adoption of auditable recommendation engines here.
- Insurance Companies:Underwriting automation and claims-fraud detection drive AI procurement.
- Payment Processors:Transaction networks deploy NLP-driven voice authentication and real-time risk scoring.
Today's leader: Banking Institutions. Tomorrow's challenger: Payment Processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's fintech AI adoption lags the United States by roughly three years, while Mexico's regulatory sandbox experiments attract venture capital that bypasses traditional banking infrastructure entirely. This divergence shapes procurement patterns across North American financial centers.
California
Venture funding density and neobank proliferation drive cloud-native AI deployment at scale. The CFPB's algorithmic-audit obligations for credit decisions force San Francisco-based lenders to maintain explainable model-documentation standards. Los Angeles payment processors pilot voice-interface authentication systems that reduce card-not-present fraud losses.
New York Metro
Money-center banks anchor fraud-detection procurement volumes while SEC fiduciary scrutiny accelerates robo-advisory compliance spending. The state's Department of Financial Services layers supplementary algorithmic-audit requirements atop federal mandates. Manhattan investment firms demand predictive analytics for real-time portfolio risk signals.
Texas
Regional lenders pilot generative AI document-parsing systems to compress underwriting cycle times from weeks to hours. The state's business-friendly regulatory environment attracts fintech relocations from California. Dallas-Fort Worth credit unions represent underserved demand for AI-native vendor solutions.
Florida
Retirement-wealth concentration fuels demand for automated rebalancing engines and conversational money-management interfaces. State banking regulators emphasize third-party vendor oversight as AI adoption accelerates among community institutions. Miami's emerging fintech cluster attracts payment processors seeking Latin American market access.
Midwest (Illinois/Ohio/Michigan)
Legacy core-system constraints slow real-time inference deployment at regional banks dependent on mainframe infrastructure. The CFPB's fair-lending enforcement compresses timelines for retrofitting black-box algorithms with interpretable pathways. Chicago anchors procurement for risk-management solutions serving agricultural lending portfolios.
US AI in Fintech Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across fragmented procurement channels. Money-center banks leverage proprietary datasets to sustain operational cost advantages in fraud detection, while neobanks and payment processors outsource AI capabilities through API-first vendor relationships. Three archetypes dominate: vertically integrated financial institutions with captive data assets, cloud-native fintech platforms with alternative-data scoring models, and infrastructure providers offering tokenized AI capabilities. Competitive intensity concentrates on M&A targeting specialized engineering teams and strategic partnerships securing exclusive data-access arrangements.
Within the vertically integrated tier, JPMorgan Chase and Goldman Sachs exemplify institutions deploying massive proprietary datasets for model training advantages. Upstart Holdings occupies a position representing the alternative-data specialist archetype, competing against FICO-dependent scoring incumbents through cash-flow analytics integration. These three entities anchor competitive dynamics across credit adjudication and fraud-prevention segments.
| Leading Market Players |
|---|
| JPMorgan Chase |
| Bank of America |
| Goldman Sachs |
| Wells Fargo |
| American Express |
| PayPal |
| Visa |
| Mastercard |
| Upstart Holdings |
| Others |
Pricing and Supply Chain Analysis
GPU cloud compute costs cascade through AI fintech pricing tiers, with Taiwan-sourced semiconductor fabrication feeding infrastructure-as-a-service premiums that concentrate among money-center banks while community institutions absorb SaaS markups from vendor intermediation.
Pricing Analysis
Capacity additions in hyperscaler data centers are reshaping price floors for inference-as-a-service offerings. Three-tier pricing structure across premium, standard, and economy levels separates JPMorgan-scale proprietary deployments from regional bank API subscriptions and credit union off-the-shelf bundles. Price differentiation rests on model customization depth and CFPB audit-readiness certification. Pricing pressure stems from open-source foundation model commoditization eroding vendor margins. Community banks exhibit highest price sensitivity; money-center institutions prioritize performance latency over unit economics.
Supply Chain Analysis
Freight costs for specialized AI hardware from Taiwan and South Korea amplify total cost of ownership for on-premise deployments. Raw material dependencies center on advanced node semiconductors, high-bandwidth memory modules, and liquid cooling infrastructure. Supply chain risk concentrates in single-source vulnerability for sub-5nm GPU fabrication. Distribution runs through cloud provider marketplaces and direct OEM relationships with NVIDIA and AMD.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud infrastructure cost compression and explainable AI premium tiering create margin expansion vectors for stakeholders who align procurement with regulatory audit cycles.
For Market Incumbents: Extend proprietary dataset advantages into adjacent fraud-detection verticals before alternative-data specialists achieve scale. Backward integration into cloud infrastructure insulates against hyperscaler pricing power. Invest in model-risk-management certification programs to defend against CFPB examination exposure. Lock in multi-year enterprise agreements with community banks before API-first competitors erode installed base. For New Entrants and Emerging Players: Voice-interface biometric authentication offers the most penetrable wedge for payment processors seeking card-not-present fraud reduction. Target Nebraska and Iowa credit unions with turnkey explainable credit scoring bundles that satisfy fair-lending documentation requirements. Pursue channel partnerships with core banking system vendors to bypass direct enterprise sales cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where model-risk-management talent scarcity constrains rollout velocity at regional lenders. Long-term viability favors acquirers of specialized compliance-engineering teams over pure algorithm plays. Watch CFPB algorithmic-audit enforcement intensity as inflection indicator for explainable AI vendor valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Explainable AI Compliance Module Development | Pre-built CFPB audit documentation reduces sales friction with multi-state lenders. |
| Alternative Data API Integration | Cash-flow analytics partnerships expand addressable borrower pools beyond FICO-dependent scoring. |
| Voice Biometric Authentication Deployment | NLP-driven contactless verification captures payment processor demand for card-not-present fraud reduction. |
| Midwestern Community Bank Channel Partnership | Core system vendor alliances unlock underserved Nebraska and Iowa credit union procurement. |
| Model Risk Management Talent Acquisition | Regulatory defense expertise concentration in coastal centers creates scarcity premium for qualified engineering teams. |
Research Methodology
Direct dialogue with chief risk officers, AI product managers at neobanks, CFPB examination specialists, and cloud infrastructure procurement leads grounded qualitative findings. Secondary validation drew from SEC filings of publicly traded fintech vendors, FFIEC call report data, venture funding databases, and CFPB supervisory guidance releases. Bottom-up deployment estimates triangulated against top-down banking IT spending benchmarks.
Segmentation outputs across application, technology, solution, and end-user dimensions anchored the analytical framework over the projection horizon. CAGRs derived from S-curve adoption modeling weighted by regulatory enforcement intensity and cloud infrastructure cost trajectories. Forecast inputs incorporated GPU supply constraints and state-level algorithmic-audit obligation diffusion patterns.
The model holds under stable CFPB enforcement posture and continued hyperscaler capex expansion; deviation in SEC fiduciary rulemaking or Taiwan semiconductor supply disruption would shift deployment timelines. Forecasts reflect documented assumptions about regulatory compliance cost pass-through and community bank cloud migration velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Spain AI in Fintech Market
FinTech
Latin America AI in Fintech Market
FinTech
Middle East AI in Fintech Market
FinTech
France AI in Fintech Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
Robo Advisory Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
AI in Fintech Market
FinTech
Wealthtech Solutions Market
FinTech
Finance Cloud Market
FinTech
Hand Account Software Market
FinTech
Europe Embedded Finance Market
FinTech
Europe Financial Analytics Market
FinTech
Fintech Lending Market
FinTech
Financial Consolidation Software Market
FinTech
Cyber Security in Fintech Market