
 Indonesia E-Services Market | 2026-2036
Indonesia E-Services Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia E-Services Market Insights
Buyer concentration across Indonesia's MSME base is decoupling from traditional Jakarta-centric procurement patterns as regional entrepreneurs adopt cloud-based service suites. Tokopedia anchors seller-side digital infrastructure through its hyperlocal fulfillment network. Shopee competes via aggressive live-streaming commerce integration and same-day delivery guarantees in tier-two urban clusters.
Indonesia E-Services encompass digitally delivered commercial and financial transactions conducted through internet-connected platforms, typically requiring API interoperability, SSL encryption protocols, and real-time payment settlement rails to function. These systems enable remote commerce, education access, and financial inclusion without physical infrastructure dependency. E-Commerce and Digital Payment segments currently dominate transaction volume, while Travel Booking retains higher per-transaction margins amid post-pandemic normalization. The Mobile App platform channel leads user acquisition, though Web Portal interfaces sustain enterprise-grade contract flows with superior average order values.
Bappebti, Bank Indonesia, and the Ministry of Communication and Informatics enforce licensing frameworks for fintech operators, e-money issuers, and content platforms respectively, creating segmented compliance obligations that favor capitalized incumbents. The Personal Data Protection Law mandates localized data storage for certain service categories, directly shaping infrastructure investment decisions. Stakeholders must monitor regulatory harmonization between central bank payment rules and sector-specific ministry decrees to anticipate licensing bottlenecks before market entry.
Market Dynamics
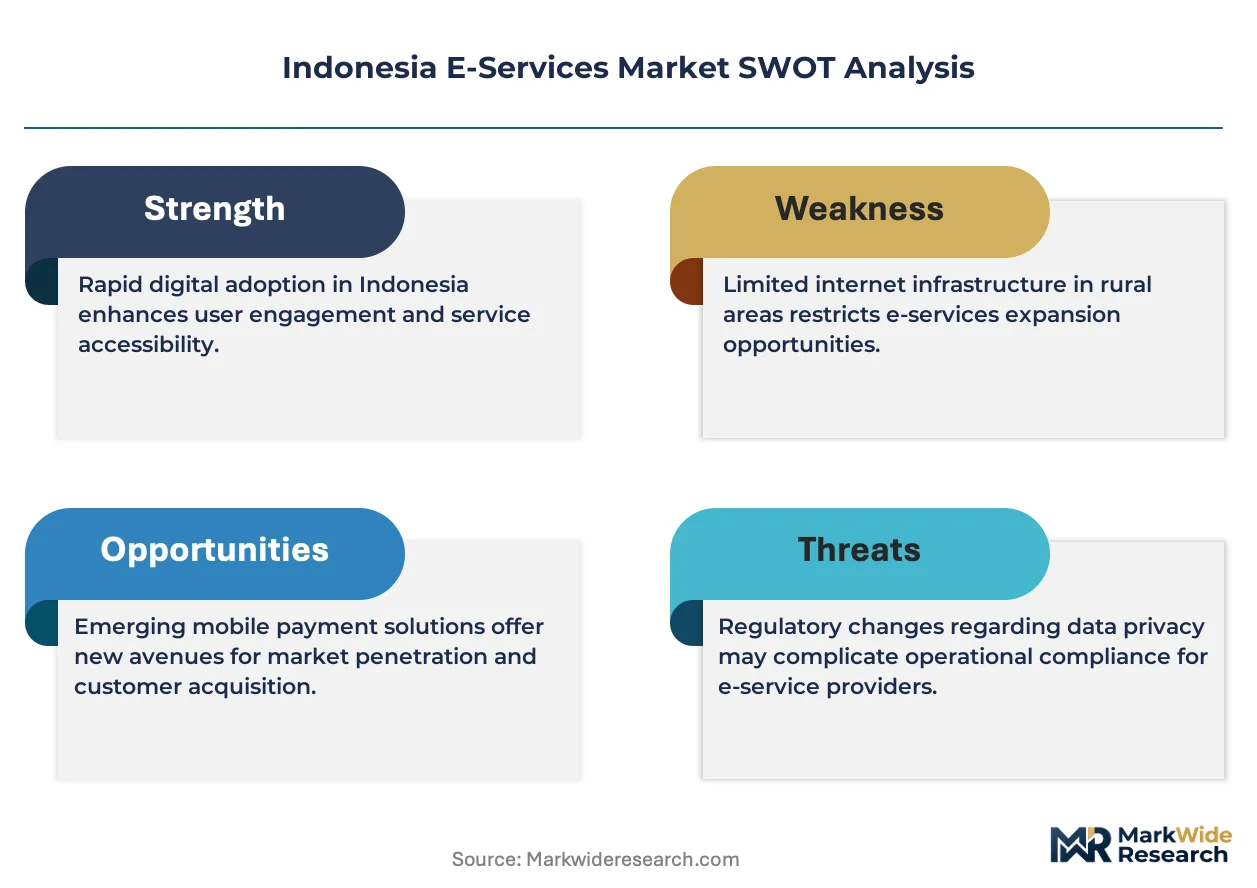
Indonesia's E-Services sector is restructuring around the Personal Data Protection Law's localization mandates, which force infrastructure investment decisions and reshape competitive entry barriers for foreign platform operators.
Growth Catalysts
- Bank Indonesia QRIS interoperability:Unified QR code standards eliminate payment fragmentation across digital wallets and banking apps, accelerating merchant onboarding in Surabaya and Makassar corridors.
- MSME cloud migration:Micro-enterprises in second-tier cities adopt SaaS-based accounting and inventory tools as mobile penetration crosses critical mass thresholds.
- Live-streaming commerce integration:Real-time video selling formats reduce customer acquisition costs for fashion and electronics sellers while compressing purchase decision cycles.
Market Restraints
- Data center concentration risk:Over 70 percent of certified Tier III facilities cluster in Greater Jakarta, creating single-point-of-failure exposure for national service continuity.
- Cross-border data friction:UU PDP's adequacy determination delays block Indonesian fintech operators from seamless ASEAN expansion until bilateral agreements finalize.
- Digital literacy variance:Eastern Indonesia provinces exhibit sub-40 percent formal financial account penetration, limiting addressable market depth for sophisticated e-service bundles.
Strategic Opportunities
- Halal certification digitization:BPJPH's online halal registration platform creates adjacent service demand for compliance software targeting food and cosmetics exporters.
- Logistics corridor decentralization:East Java and South Sulawesi port upgrades enable fulfillment network expansion beyond Java-centric distribution models.
- API banking convergence:Open finance regulations from the Financial Services Authority permit non-bank platforms to embed lending and insurance products directly into e-commerce checkouts.
Industry Challenges
- DevSecOps talent scarcity:Shortage of engineers combining cloud architecture skills with UU PDP compliance expertise extends platform security audit timelines.
- Legacy ERP integration friction:Established distributors in Surabaya and Bandung resist API-based inventory synchronization, forcing hybrid middleware investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia E-Services Market |
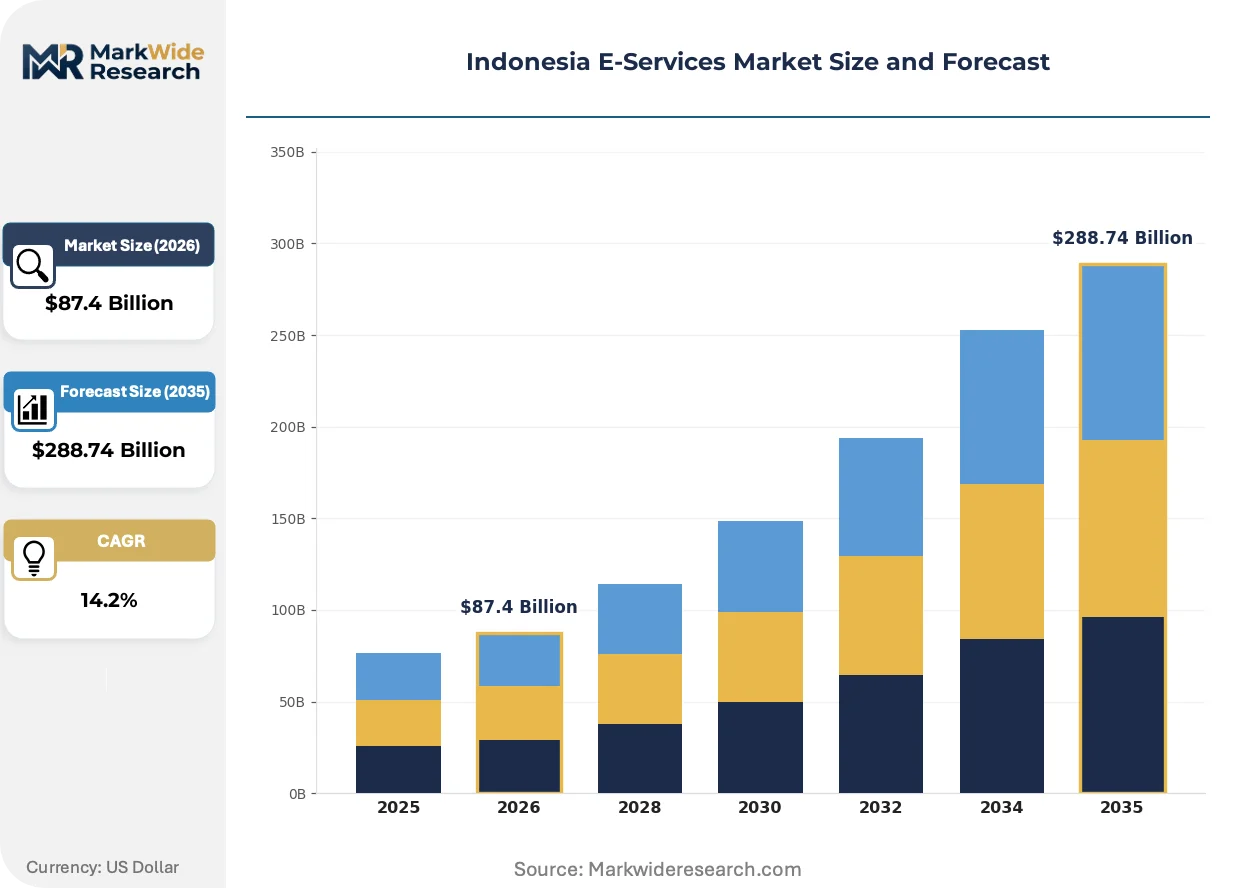
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $288.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Online Banking, E-Commerce, Travel Booking, Digital Payment Consumer Segment: Millennials, Businesses, Students, Seniors Platform: Mobile App, Web Portal, Social Media, Aggregators Usage Frequency: Daily, Weekly, Monthly, Occasional |
| Companies Covered | Shopee, Tokopedia, Blibli, Lazada, Ruangguru, HarukaEdu, Tinder, Bumble, TikTok Shop, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia E-Services Market Trends and Innovations
Platform economics in Indonesia are compressing around embedded finance capabilities and hyperlocal fulfillment density, with regulatory technology emerging as a distinct competitive layer separating compliant operators from marginal entrants.
Artificial intelligence-powered fraud detection is converging with real-time transaction monitoring systems deployed by payment gateways. MSME lenders and e-money issuers adopt machine-learning risk scoring to replace manual KYC document review. This convergence is collapsing underwriting timelines from days to minutes while expanding credit access to thin-file borrowers in Makassar and Medan urban clusters.
Bank Indonesia's Payment System Roadmap 2025 mandates real-time gross settlement integration for all licensed e-money operators. The regulation forces infrastructure standardization across previously siloed wallet ecosystems. Fintech platforms serving cross-border remittance corridors face the steepest compliance costs as they rearchitect settlement rails to meet central bank specifications.
Merchant procurement of logistics services is fragmenting across multiple last-mile providers rather than consolidating with single-platform solutions. Tokopedia and Shopee sellers increasingly split inventory between hyperlocal fulfillment centers and third-party courier networks to optimize delivery speed against cost. This pattern is most pronounced in Surabaya's electronics wholesale districts where same-day delivery guarantees determine vendor selection.
Indonesia E-Services Market Segmentation
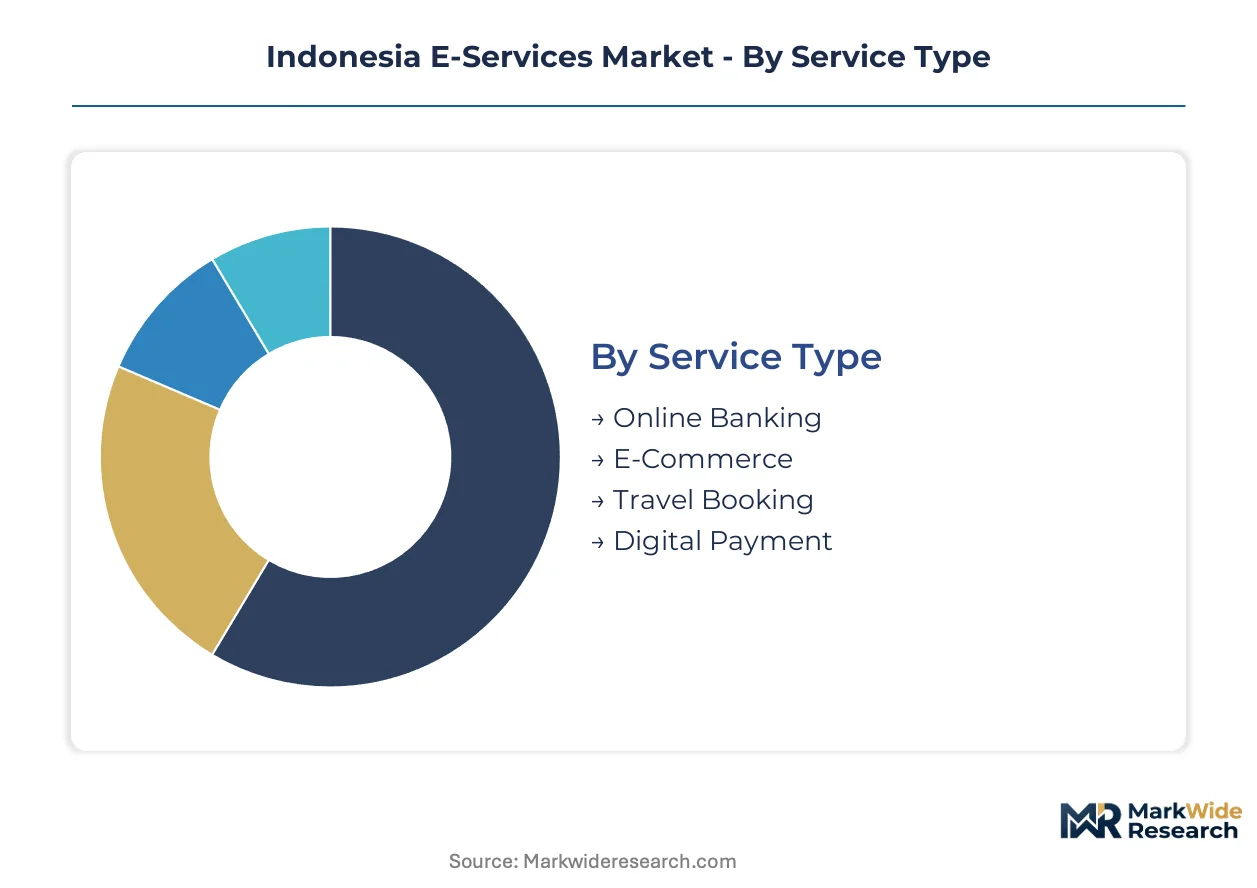
Segmentation in Indonesia's E-Services Market reveals how infrastructure investment and regulatory pressure distribute opportunity unevenly across service categories and user bases. Distinct buyer behaviors emerge between Java-centric commercial corridors and emerging second-tier urban clusters.
Service Type:
Buyers differentiate primarily by transaction velocity requirements and compliance exposure under Bank Indonesia and Bappebti licensing frameworks.
- E-Commerce:Platforms enable product discovery, inventory synchronization, and payment settlement through API-connected merchant dashboards. Demand concentrates in Surabaya electronics wholesale districts and Jakarta's fashion verticals, driven by live-streaming commerce adoption and same-day delivery guarantees.
- Digital Payment:Systems process QRIS-standardized transactions across interoperable wallet and banking applications. Merchant onboarding accelerates in Makassar and Bandung corridors where QR code penetration crosses critical mass for street-level commerce.
- Online Banking:Services deliver account management, fund transfers, and credit origination through encrypted web and mobile interfaces. Regional banks in East Java prioritize these platforms to capture MSME deposit bases.
- Travel Booking:Platforms aggregate transportation, accommodation, and experience inventory with post-pandemic margin recovery. Per-transaction yields exceed other service types despite lower absolute volume.
Volume sits with E-Commerce; growth tilts toward Digital Payment.
Consumer Segment:
Adoption patterns split sharply by digital literacy gradients and formal financial account penetration across Indonesia's archipelago.
- Millennials:Users aged 25-40 drive platform-native behaviors including embedded finance product adoption and social commerce engagement. This cohort dominates transaction frequency in Jakarta and Surabaya urban cores where smartphone penetration exceeds 85 percent.
- Businesses:MSME operators procure SaaS-based accounting, inventory, and payment acceptance tools. Cloud migration accelerates among second-tier city entrepreneurs seeking to bypass legacy ERP constraints.
- Students:Learners access educational content, device financing, and peer-to-peer payment services through campus-centered platform partnerships.
- Seniors:Late adopters require simplified interfaces and assisted onboarding, limiting addressable market depth in Eastern Indonesia provinces with sub-40 percent formal financial inclusion.
Businesses generate the steepest expansion trajectory; Millennials anchor current revenue concentration.
Platform:
Channel selection determines compliance architecture and average order value profiles for service providers.
- Mobile App:Native applications dominate user acquisition through push-notification engagement and biometric authentication. Tokopedia and Shopee anchor this channel with hyperlocal fulfillment network integration.
- Web Portal:Browser-based interfaces sustain enterprise-grade contract flows with superior average order values and multi-user permission structures. Corporate procurement in Bandung and Semarang favors this channel for B2B service bundles.
- Social Media:Messaging and content platforms enable conversational commerce and influencer-mediated transactions. Live-streaming integration compresses purchase decision cycles for fashion and cosmetics verticals.
- Aggregators:Comparison and bundling platforms reduce search costs across fragmented service providers. Travel and financial product distribution relies on this channel for customer acquisition in price-sensitive segments.
Mobile App captures transaction volume; Web Portal secures margin contribution.
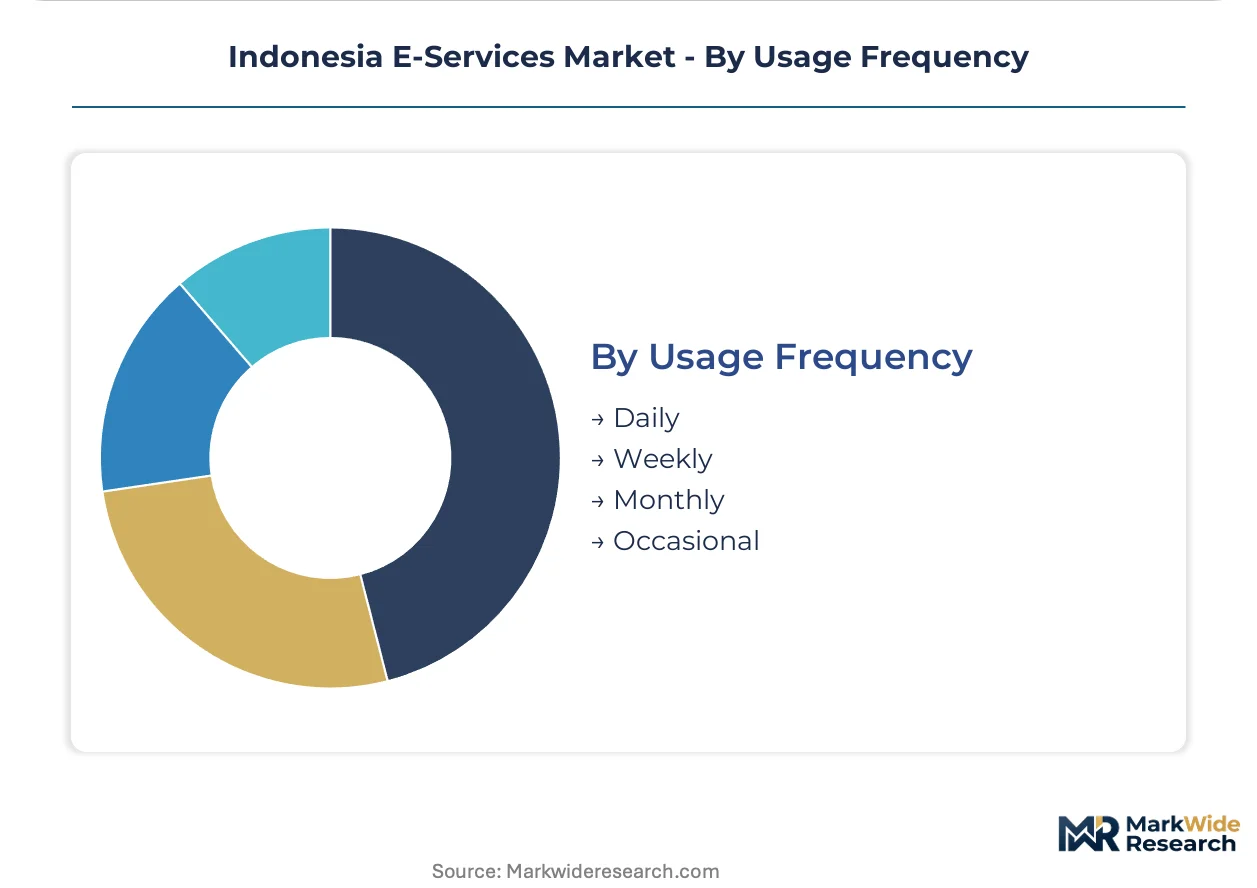
Usage Frequency:
Engagement intensity correlates with platform infrastructure investment and real-time settlement capability requirements.
- Daily:High-frequency users demand instant payment confirmation and fraud monitoring through AI-powered transaction scoring. QRIS interoperability and e-money wallet saturation enable this behavior in Java-based logistics corridors.
- Weekly:Regular engagement patterns characterize utility bill payment and grocery commerce with predictable replenishment cycles. Subscription management tools target this cadence in emerging urban clusters.
- Monthly:Periodic users concentrate in salary-cyclical financial services and travel planning with lower infrastructure dependency.
- Occasional:Episodic engagement limits platform monetization efficiency and increases per-transaction acquisition costs for specialized service categories.
Daily usage dominates infrastructure load; Weekly engagement expands most quickly as second-tier cities mature digitally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Java-based logistics corridors concentrate Indonesia's e-services demand, though Surabaya and Makassar emerge as secondary growth poles as digital onboarding accelerates beyond Jakarta-centric procurement patterns.
Greater Jakarta
Bank Indonesia's QRIS interoperability mandates drive merchant onboarding velocity across Jakarta's dense commercial corridors. The Personal Data Protection Law forces Tier III data center localization investments in Bogor and Tangerang satellite zones. Fintech operators cluster in South Jakarta's central business district to access real-time gross settlement infrastructure.
East Java
Surabaya's electronics wholesale districts generate concentrated e-commerce transaction volume through live-streaming commerce adoption. The Ministry of Communication and Informatics enforces content platform licensing for regional streaming services based in Malang. Port infrastructure upgrades at Tanjung Perak enable fulfillment network decentralization beyond Java-centric distribution models.
South Sulawesi
Makassar anchors eastern Indonesia's digital payment penetration as QR code acceptance crosses critical mass for street-level commerce. Bappebti's licensing framework for e-money issuers shapes local fintech operator compliance architecture. The city's logistics corridor expansion attracts third-party courier network investments from national platform operators.
West Java
Bandung's established distributor base resists API-based inventory synchronization, forcing hybrid middleware investments among SaaS providers. Regional banks prioritize online banking platform deployment to capture MSME deposit bases across Cimahi and Bekasi industrial zones. Cloud migration accelerates among textile sector entrepreneurs seeking legacy ERP bypass.
Bali and Nusa Tenggara
Travel booking platforms concentrate in Denpasar and Lombok as post-pandemic margin recovery drives per-transaction yield optimization. Digital literacy variance limits addressable market depth for sophisticated e-service bundles in eastern provinces with sub-40 percent formal financial inclusion. The central bank's payment system roadmap forces infrastructure standardization for regional remittance corridor operators.
Indonesia E-Services Market Competitive Landscape
Jakarta-based platform operators anchor the consolidated tier; Singapore-headquartered regional specialists hold secondary positions through cross-border marketplace integration. The vendor structure concentrates around integrated commerce-finance ecosystems with hyperlocal fulfillment density as the primary differentiation vector. Three archetypes dominate: horizontal marketplace operators, vertical education specialists, and social-commerce hybrids. Competitive moves center on live-streaming commerce integration and API banking convergence to embed lending products directly into checkout flows.
Within the horizontal marketplace tier, Shopee and Tokopedia occupy positions defined by fulfillment network density and merchant dashboard sophistication. Blibli represents the domestic incumbent archetype with established logistics partnerships. These three entities exemplify the capital requirements for Bank Indonesia licensing compliance and UU PDP-mandated data localization infrastructure.
| Leading Market Players |
|---|
| Shopee |
| Tokopedia |
| Blibli |
| Lazada |
| Ruangguru |
| HarukaEdu |
| Tinder |
| Bumble |
| TikTok Shop |
| Others |
Pricing and Supply Chain Analysis
Cloud DevSecOps engineers concentrated in Greater Jakarta command wage premiums that widen pricing spreads between enterprise-grade and basic-tier e-service bundles. Labor-cost differentials between certified compliance specialists and generalist developers directly determine margin structures across Bank Indonesia-licensed payment platforms and unlicensed SaaS tools.
Pricing Analysis
Volume concentrates in QRIS-standardized payment processing with compressed per-transaction margins, while travel booking and embedded finance products retain superior yield profiles. Three-tier pricing structure across premium API-integrated suites, mid-market SaaS subscriptions, and economy self-service portals reflects compliance certification levels and data localization guarantees. Pricing pressure stems from QRIS interoperability mandates eliminating wallet-specific premiums. MSME operators in Surabaya and Makassar corridors exhibit highest price sensitivity; enterprise procurement in Jakarta tolerates premium tiers for UU PDP audit documentation.
Supply Chain Analysis
Regional distribution centers in Bogor and Tangerang satellite zones anchor hub-and-spoke fulfillment patterns serving Java-based logistics corridors. Tier III data center capacity concentrates in Greater Jakarta, with secondary hub development in Surabaya and Makassar port zones. Critical inputs include submarine cable landing stations, GPU clusters for AI fraud detection, and localized server racks meeting UU PDP mandates. Single-source vulnerability runs through Jakarta-centric data center concentration exceeding 70 percent of certified national capacity. Distribution runs through hyperlocal fulfillment networks integrated with third-party courier partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's e-services sector functions as a vertical-integration race where control over hyperlocal fulfillment density and embedded finance APIs determines competitive durability. Players are pursuing backward integration into Tier III data center assets to satisfy UU PDP localization mandates.
For Market Incumbents: Acquire certified Tier III data center capacity in East Java and South Sulawesi to decentralize infrastructure risk beyond Greater Jakarta concentration. Consolidate API banking partnerships before OJK open finance regulations fully commoditize lending product distribution. Shopee and Tokopedia's live-streaming commerce integration represents the substitute technology threat; counter via proprietary merchant dashboard sophistication and inventory synchronization tools.
For New Entrants and Emerging Players: Launch via halal certification digitization services targeting BPJPH compliance workflows for food and cosmetics exporters in Bandung and Semarang. White-space opportunity sits with SaaS-based accounting tools for textile sector MSMEs in West Java seeking legacy ERP bypass. Most penetrable segment: second-tier city entrepreneurs in Makassar and Medan with sub-40 percent formal financial inclusion but accelerating smartphone penetration.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mid-cap specialists controlling both merchant-facing platforms and last-mile courier networks given logistics corridor decentralization catalysts. Long-term viability favors operators with UU PDP-compliant infrastructure and Bank Indonesia e-money licenses. Signal to watch: bilateral adequacy agreements enabling cross-border ASEAN expansion for Indonesian fintech operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Hyperlocal Fulfillment Network Expansion | East Java and South Sulawesi port upgrades enable same-day delivery guarantees in Surabaya electronics districts. |
| Embedded Finance Product Integration | OJK open finance regulations permit lending and insurance embedding directly into Tokopedia and Shopee checkouts. |
| Regulatory Technology Platform Development | UU PDP compliance automation separates capitalized incumbents from marginal entrants facing audit timeline extensions. |
| Tier III Data Center Localization | Bank Indonesia and Ministry of Communication licensing mandates force infrastructure investment in Bogor-Tangerang satellite zones. |
| Live-Streaming Commerce Capability Buildout | Real-time video selling formats reduce customer acquisition costs for fashion verticals in Jakarta and Surabaya urban cores. |
Research Methodology
Document review covered Bank Indonesia payment system circulars, Bappebti fintech licensing frameworks, and UU PDP implementation decrees, complemented by interviews with platform engineering leads, e-money issuer compliance officers, and MSME merchant acquisition managers. Secondary validation drew from Ministry of Communication and Informatics content platform licensing databases, QRIS interoperability technical specifications, and regional port authority infrastructure disclosure filings. Bottom-up transaction volume modeling triangulated against top-down GDP digital economy contribution estimates.
Cross-reference between historical QRIS adoption velocity and expert panel input on live-streaming commerce penetration shaped projection parameters across the analysis window. Segmentation dimensions modeled include service type, consumer segment, platform channel, and usage frequency, with additional weighting for Java versus eastern Indonesia digital literacy gradients. CAGRs derived from logistic diffusion curves fitted to mobile penetration thresholds and cloud migration S-cycles. Industry-specific inputs incorporated Bank Indonesia Payment System Roadmap 2025 infrastructure standardization timelines and BPJPH halal certification digitization platform rollout scope.
Regulatory harmonization delays between central bank rules and sector-specific ministry decrees, cross-border data adequacy agreement timing, and DevSecOps talent supply constraints are the dominant revision risks warranting forecast sensitivity testing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
UK Ecommerce Market
E-Commerce Solutions
Digital Coupons Market
E-Commerce Solutions
Global Ecommerce Platform Market
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
Egypt E-Commerce Market
E-Commerce Solutions
North America E-Commerce Market
E-Commerce Solutions
Brazil E-Commerce Market
E-Commerce Solutions
Courier Express and Parcel (CEP) Market
E-Commerce Solutions
Europe E-Commerce Logistics Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
Live Commerce Platforms Market
E-Commerce Solutions
Asia Pacific Same Day Delivery Market
E-Commerce Solutions
China Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Switzerland E-Commerce Market
E-Commerce Solutions
Indonesia Alcohol E-Commerce Market
E-Commerce Solutions
Africa E-Commerce Market