
 Japan Digital Transformation Market | 2026-2036
Japan Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Digital Transformation Market Insights
Mid-market manufacturers is collapsing as the fastest-growing buyer archetype in Japan's digital transformation landscape, overtaking traditional large-enterprise dominance. Fujitsu Japan Limited leverages its domestic manufacturing heritage to anchor hybrid cloud deployments for industrial clients. NEC Corporation competes through cybersecurity-integrated infrastructure stacks. Hitachi Consulting specializes in operational-technology convergence for legacy plant modernization.
Digital transformation encompasses the systematic integration of cloud computing, artificial intelligence, and Internet-of-Things architectures into enterprise workflows to replace analog processes with data-driven decision systems. Its primary purpose is to compress operational latency and generate predictive intelligence from previously siloed information streams. Cloud Services and AI Solutions command the largest current revenue pools, while IoT Platforms represents the fastest-expanding segment as factory-floor sensor networks proliferate. Manufacturing end users sustain the deepest deployment intensity, though Financial Services generates superior per-account margins due to compliance-driven system complexity.
METI's Society 5.0 roadmap, JIS standards for data interoperability, and the Personal Information Protection Commission's cross-border data rules collectively shape vendor product architecture and client procurement criteria. METI specifically mandates open API frameworks for public-sector digitization, forcing solution providers to abandon proprietary lock-in strategies. Stakeholders must monitor whether Japan's forthcoming AI governance guidelines replicate EU-level compliance burdens or preserve lighter-touch innovation incentives.
Market Dynamics
Japan's digital transformation market is compressing around METI's Society 5.0 mandate, which forces vendors to abandon proprietary architectures for open API frameworks while mid-market manufacturers accelerate cloud migration ahead of regulatory deadlines.
Growth Catalysts
- Society 5.0 Policy Framework:METI's roadmap mandates open data interoperability standards across public-sector digitization, compelling enterprise software vendors to rearchitect solutions for cross-platform integration.
- Manufacturing Cloud Migration:Factory-floor sensor deployment and predictive maintenance systems are pulling industrial IoT platform spending as mid-market producers modernize legacy operational technology stacks.
- Financial Services Automation:Tokyo's banking and insurance corridors deploy AI-driven process automation at scale to compress compliance-driven system complexity into real-time risk monitoring infrastructure.
Market Restraints
- Cross-Border Data Friction:The Personal Information Protection Commission's strict localization requirements create architectural constraints for multinational cloud providers seeking unified Asia-Pacific infrastructure.
- Legacy System Entrenchment:Decades-old mainframe architectures in Japan's industrial base impose integration costs that slow hybrid cloud adoption timelines beyond initial procurement cycles.
- Domestic Vendor Concentration:Heavy reliance on established systems integrators with deep keiretsu relationships limits price competition and extends procurement negotiations for emerging technology categories.
Strategic Opportunities
- Kansai Industrial Belt Penetration:Osaka-Kyoto manufacturing clusters remain underdigitized relative to Tokyo, creating whitespace for operational technology convergence specialists targeting SME modernization.
- AI Governance Tailwind:Forthcoming national AI guidelines will clarify compliance boundaries, reducing procurement uncertainty for financial services buyers evaluating automated decision systems.
- Edge-to-Cloud Convergence:Factory-floor edge computing paired with centralized analytics platforms enables real-time quality control applications previously constrained by latency-bound architectures.
Industry Challenges
- Scarce Cloud-Native Engineering Talent:Japanese universities produce insufficient DevOps and Kubernetes-certified professionals to meet deployment velocity demands from accelerating enterprise migrations.
- Interoperability Certification Delays:JIS standards for data exchange protocols remain in draft for several verticals, freezing procurement decisions for buyers requiring guaranteed future compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Digital Transformation Market |
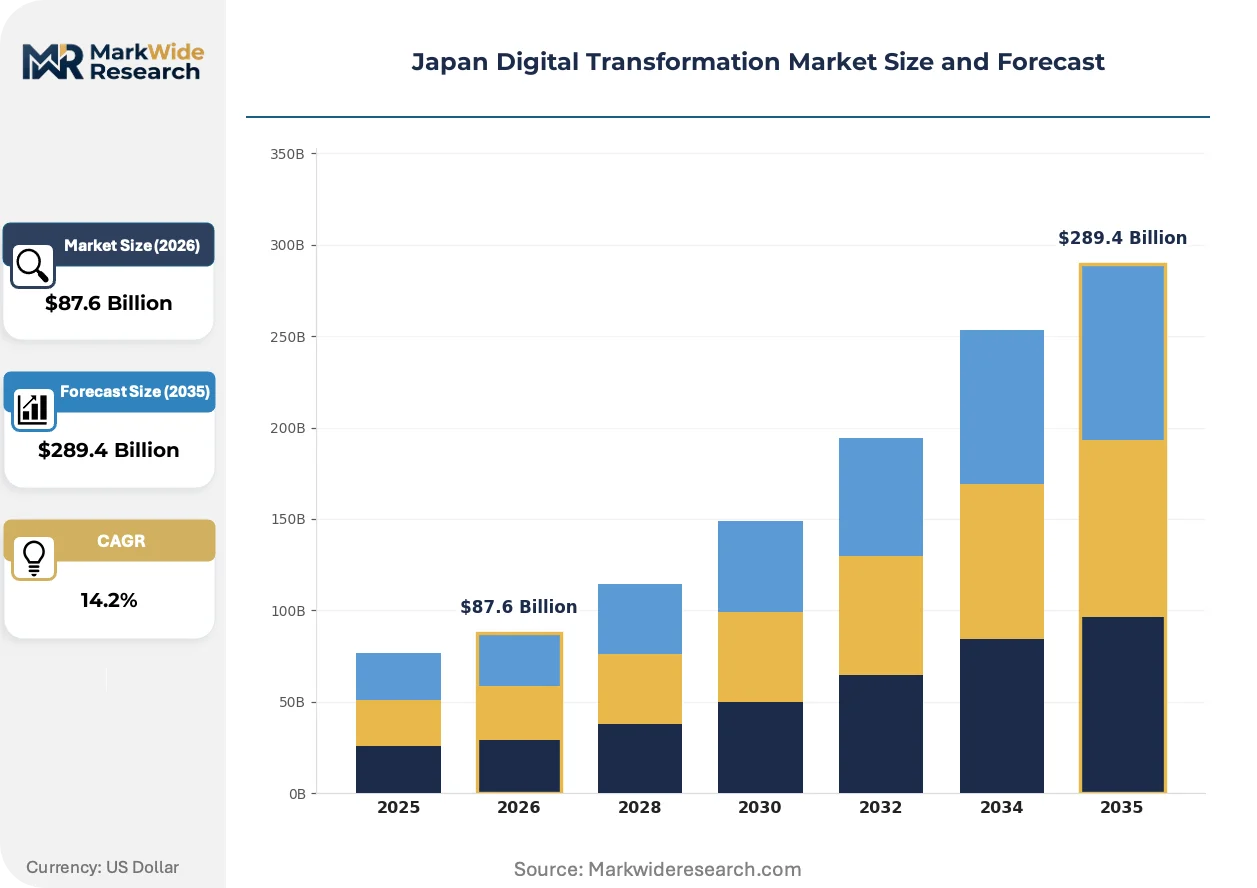
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $289.4 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Cloud Services, AI Solutions, Data Analytics, IoT Platforms End User: Manufacturing, Retail, Healthcare, Financial Services Technology: Big Data, Blockchain, Machine Learning, Cybersecurity Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | Fujitsu Japan Limited, NEC Corporation, NTT DATA Group, Accenture PLC, IBM Corporation, Siemens AG, Hitachi Consulting, Deloitte Japan, TIS Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Digital Transformation Market Trends and Innovations
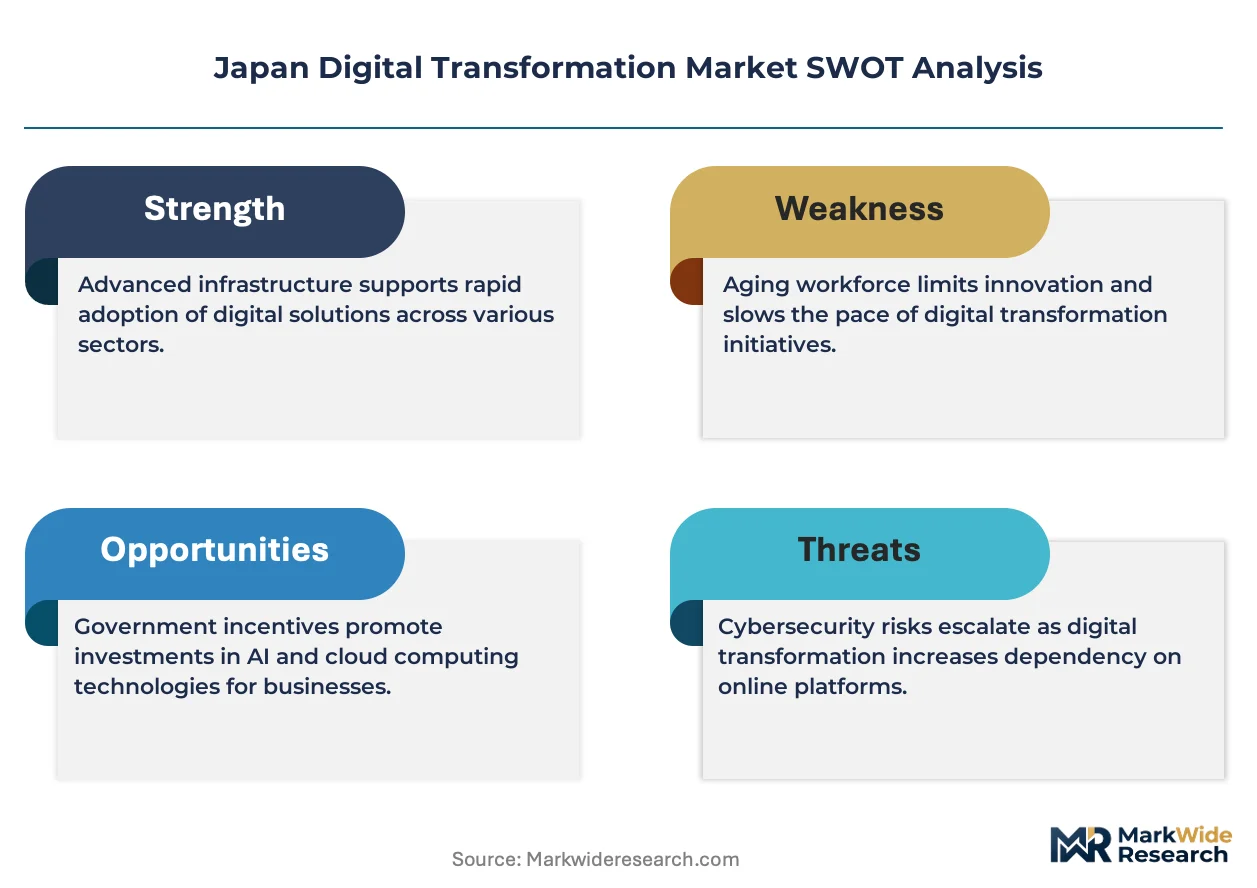
Japan's digital transformation trajectory is fragmenting across three vectors: technology architecture choices, regulatory compliance architectures, and procurement model reinvention. Each vector carries distinct implications for vendor positioning and buyer investment priorities.
Hybrid cloud infrastructure is bifurcating between hyperscale public deployments for non-sensitive workloads and sovereign-private stacks for regulated data. Financial services firms in Tokyo's enterprise corridor are adopting this dual-mode architecture fastest, driven by PIPC localization mandates. The structural consequence is compressing vendor margins as buyers demand seamless orchestration across incompatible environments rather than single-platform solutions.
METI's open API mandate for public-sector systems is forcing proprietary software vendors to expose core functionality through standardized interfaces. Industrial software providers must rearchitect decades-old monolithic products into modular microservices to retain government contract eligibility. Manufacturing end users benefit from reduced switching costs, though implementation complexity rises during transition periods.
Mid-market manufacturers are consolidating vendor relationships from fragmented point solutions to integrated platform contracts spanning infrastructure through application layers. Systems integrators with domestic operational technology heritage capture this consolidation by bundling legacy modernization with cloud migration services. The Kansai and Chubu industrial regions exhibit this pattern most visibly as SME buyers prioritize single-accountability over best-of-breed component sourcing.
Japan Digital Transformation Market Segmentation
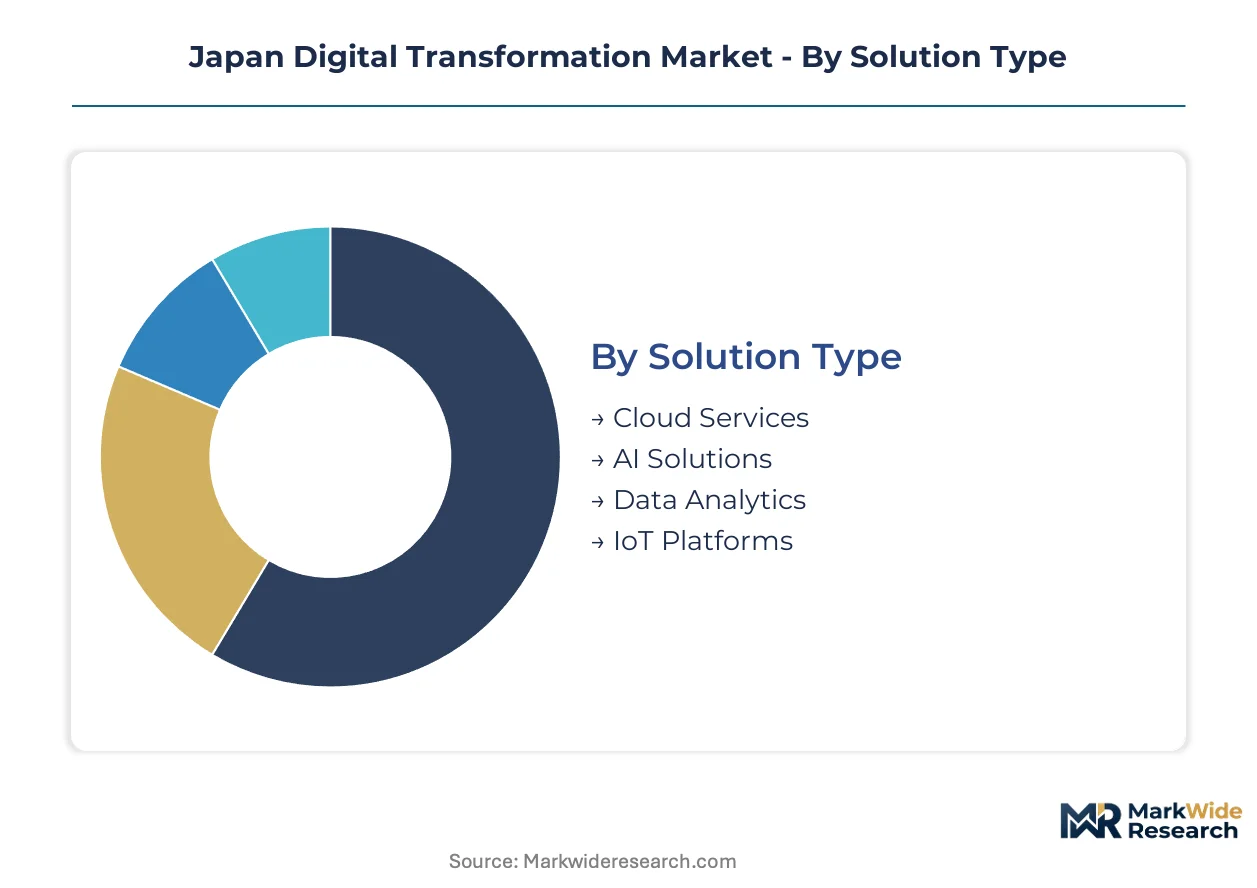
Japan's digital transformation market fragments across four critical dimensions that determine vendor positioning and procurement patterns. Solution type and deployment model choices reflect METI's Society 5.0 interoperability mandates, while end-user and technology segmentation reveals where capital deployment concentrates across Tokyo's enterprise corridor and regional industrial belts.
Solution Type:
Domestic demand dominates Cloud Services and AI Solutions as Tokyo financial institutions and manufacturers prioritize sovereign data architectures, while IoT Platforms draw export-linked investment from automotive and electronics supply chains serving Southeast Asian assembly networks.
- Cloud Services:Hyperscale infrastructure deployments supporting enterprise workload migration from legacy mainframes. Tokyo banking clusters and Osaka manufacturing hubs drive procurement volume under PIPC localization requirements.
- AI Solutions:Machine learning platforms for process automation and predictive analytics. Financial services buyers in Tokyo's enterprise corridor deploy compliance-driven risk monitoring systems at scale.
- Data Analytics:Business intelligence tools converting operational data streams into decision support.
- IoT Platforms:Factory-floor sensor networks and predictive maintenance systems. Expanding most quickly as mid-market manufacturers modernize legacy operational technology stacks in Aichi and Shizuoka prefectures.
Cloud Services holds the largest share; momentum sits with IoT Platforms.
End User:
Cost tier segmentation separates premium compliance-driven deployments from efficiency-focused mid-market modernization, with Financial Services and Manufacturing occupying opposite poles of this procurement spectrum.
- Manufacturing:Operational technology convergence for legacy plant modernization spanning automotive, electronics, and precision machinery sectors. Toyota City and Hamamatsu industrial clusters sustain deepest deployment intensity for sensor networks and edge computing.
- Financial Services:AI-driven process automation and real-time risk infrastructure. Tokyo banking and insurance corridors generate superior per-account margins due to regulatory complexity and system integration demands.
- Retail:Customer analytics and supply chain digitization for omnichannel operations.
- Healthcare:Electronic medical records and telemedicine platforms facing PMDA data governance requirements.
Manufacturing commands volume leadership; Financial Services delivers margin concentration.
Technology:
Application maturity varies sharply across this category, with established Big Data architectures contrasting against emerging Blockchain deployments still seeking production-scale validation in Japanese enterprise environments.
- Big Data:Distributed storage and processing frameworks for enterprise data lake construction. Manufacturing quality control and financial transaction monitoring represent primary consumption vectors.
- Machine Learning:Supervised and unsupervised learning models for pattern recognition and predictive forecasting. Deployment concentrates in Tokyo financial services for credit risk and fraud detection applications.
- Cybersecurity:Zero-trust architectures and threat detection systems mandated by critical infrastructure protection guidelines.
- Blockchain:Distributed ledger pilots for supply chain traceability and trade finance documentation.
Big Data maintains installed base dominance; Machine Learning exhibits steepest expansion trajectory.
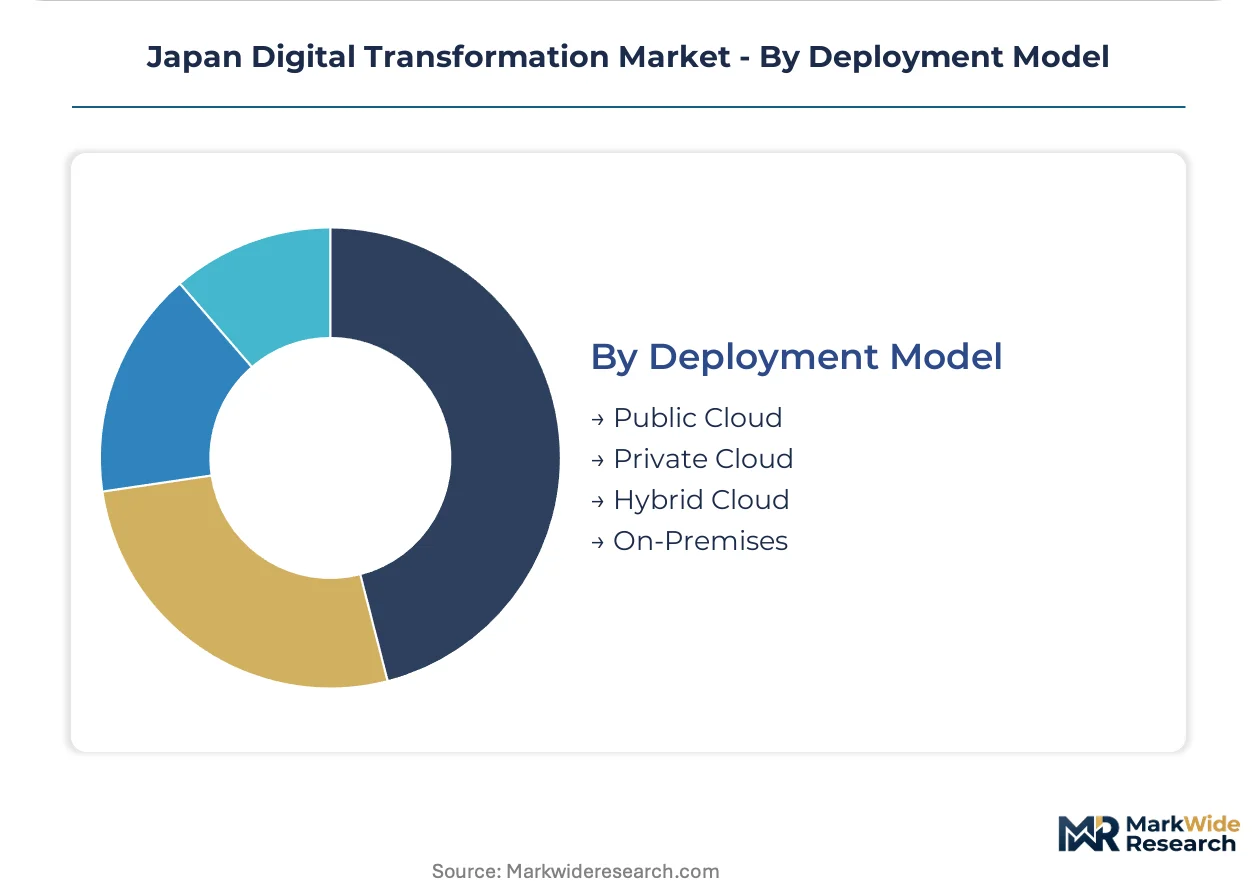
Deployment Model:
Customer type segmentation distinguishes between regulated entities requiring sovereign data control and unregulated buyers optimizing for cost and scalability through shared infrastructure.
- Public Cloud:Shared infrastructure for non-sensitive workloads and development environments. Mid-market manufacturers in regional industrial belts adopt this model for cost containment during initial digitization phases.
- Hybrid Cloud:Orchestrated workloads spanning on-premises and cloud environments. Financial services firms in Tokyo deploy dual-mode architectures fastest to satisfy PIPC localization mandates while retaining scalability.
- Private Cloud:Dedicated infrastructure for regulated data and critical systems.
- On-Premises:Legacy data center retention for mainframe-dependent operations and air-gapped security requirements.
Hybrid Cloud captures investment momentum; On-Premises retains substantial legacy footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan exports digital transformation solutions through Southeast Asian supply chains while importing cloud infrastructure services from US hyperscalers. This bilateral technology flow shapes procurement patterns across Tokyo's enterprise corridor and regional industrial belts. Domestic vendors anchor hybrid deployments while foreign providers capture platform-layer contracts.
Kanto/Tokyo
Financial services automation and sovereign cloud deployments dominate enterprise spending in the capital region. METI's open API mandate forces vendors serving government clients to rearchitect proprietary systems for interoperability. Tokyo's banking corridor drives AI-driven risk monitoring adoption at scale under PIPC localization requirements.
Kansai/Osaka
Manufacturing modernization accelerates as mid-market producers consolidate fragmented operational technology stacks. JIS standards for data interoperability guide procurement decisions among automotive and electronics suppliers. Osaka-Kyoto industrial clusters remain underdigitized relative to Tokyo, creating whitespace for operational technology convergence specialists.
Chubu/Nagoya
Toyota City and Hamamatsu industrial zones sustain Japan's deepest factory-floor sensor network deployment intensity. METI's Society 5.0 framework mandates predictive maintenance system adoption among tier-one automotive suppliers. Aichi and Shizuoka prefectures lead IoT platform expansion as legacy plant modernization timelines compress.
Kyushu
Semiconductor and automotive component manufacturing anchors digital investment in southern Japan. Regional suppliers face keiretsu procurement constraints that extend vendor selection cycles for emerging technology categories. Fukuoka's emerging tech corridor attracts edge computing deployments serving export-linked assembly networks.
Japan Digital Transformation Market Competitive Landscape
Player mix skews toward domestic systems integrators with deep keiretsu relationships, creating a tiered structure where established Japanese vendors capture infrastructure contracts while foreign specialists penetrate application layers. Three archetypes dominate: manufacturing-heritage conglomerates leveraging operational technology credibility, hyperscale cloud platforms offering sovereign-compliant architectures, and global consultancies delivering financial services automation. Competitive moves concentrate on hybrid cloud partnership structures and vertical-specific AI solution bundling.
Within the domestic infrastructure tier, Fujitsu Japan Limited, NEC Corporation, and Hitachi Consulting exemplify the manufacturing-heritage archetype that anchors industrial client relationships through legacy system integration capabilities. These vendors occupy positions where keiretsu networks and JIS certification histories create defensive moats against foreign platform entrants. Their collective presence shapes procurement timelines and technical standards across Japan's enterprise corridor.
| Leading Market Players |
|---|
| Fujitsu Japan Limited |
| NEC Corporation |
| NTT DATA Group |
| Accenture PLC |
| IBM Corporation |
| Siemens AG |
| Hitachi Consulting |
| Deloitte Japan |
| TIS Inc. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud infrastructure economics in Japan compress unit costs for compute and storage services while keiretsu procurement networks preserve premium pricing tiers for domestic systems integrators. This dual structure concentrates pricing power among established vendors serving regulated sectors while mid-market buyers extract volume discounts from foreign platform providers.
Pricing Analysis
Legacy mainframe-to-cloud migration pricing gaps separate incumbent vendor premiums from next-generation SaaS-native alternatives, with hybrid orchestration layers commanding intermediate rates. Three-tier pricing structure across sovereign-compliant, standard enterprise, and developer-economy levels stratifies buyer segments. Cost compression in mid-market manufacturing tiers intensifies as foreign hyperscalers compete on per-workload economics. Financial services buyers exhibit lowest price sensitivity due to PIPC localization mandates that override cost considerations.
Supply Chain Analysis
United States and Ireland anchor hyperscale cloud platform engineering and data center infrastructure supply for Japanese enterprise deployments. Taiwan and South Korea feed semiconductor components for edge computing hardware deployed across Aichi and Shizuoka factory floors. Supply chain risk centers on single-source dependency for advanced GPU accelerators constrained by export control classifications. Distribution runs through domestic systems integrators with keiretsu relationships that filter foreign technology access to end-user accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's digital transformation market represents a high-growth disruption as METI's Society 5.0 interoperability mandates force proprietary vendor rearchitectures and accelerate mid-market cloud migration timelines.
For Market Incumbents: Shield manufacturing-heritage client relationships through JIS-certified hybrid cloud bundles that embed legacy operational technology integration capabilities. Deepen keiretsu channel control against foreign hyperscaler direct-sales encroachment by co-developing sovereign-private stack architectures with PIPC-compliant data localization. Prioritize DevOps certification programs to address scarce cloud-native engineering talent constraints. For New Entrants and Emerging Players: Lead with AI governance readiness consulting to capture financial services procurement uncertainty ahead of forthcoming national guidelines. Target Kansai industrial belt SME modernization whitespace through operational technology convergence offerings priced below Fujitsu-NEC incumbent tiers. Position through regional systems integrator partnerships rather than direct enterprise sales to bypass keiretsu relationship barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operational technology specialists with manufacturing domain expertise and existing JIS certification histories. Long-term viability hinges on hybrid cloud orchestration capabilities spanning sovereign-private and hyperscale public environments. Monitor METI AI governance guideline publication as signal for financial services automation procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Platform Integration | Enables PIPC-compliant data localization for Tokyo financial services workloads. |
| Operational Technology Convergence | Captures Kansai SME modernization demand through legacy plant sensor deployment. |
| Strategic Partnership with Domestic SI | Accelerates keiretsu channel access for foreign hyperscaler platform penetration. |
| Acquisition of Edge Computing Specialist | Consolidates Chubu automotive supplier real-time quality control capabilities. |
| AI Governance Compliance Certification | Reduces procurement friction for automated decision system sales to insurers. |
Research Methodology
Operator-level perspectives from cloud platform engineers, IT procurement officers at financial institutions, manufacturing plant managers, systems integrator account executives, and METI policy officials anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of listed hyperscalers, Japanese government digitization white papers, JIS standards documentation, and industrial IoT deployment case studies. Bottom-up segment sizing triangulated against top-down macroeconomic absorption capacity estimates.
Sensitivity analysis across deployment model adoption curves, regulatory compliance cost scenarios, and talent supply constraints shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include solution type, end-user industry vertical, technology maturity tier, and geographic adoption cluster. CAGRs derived from installed base growth rates, replacement cycle compression, and net new workload creation across the analysis window. Forecast inputs incorporated PIPC enforcement intensity scenarios and METI open API mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained Society 5.0 policy continuity or abrupt AI governance restriction would require recalibration. Forecasts reflect documented assumptions regarding cross-border data friction persistence and legacy system integration cost trajectories. Recalibration cycles align with material shifts in METI regulatory publication schedules and hyperscaler sovereign cloud certification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Germany Digital Transformation Market
Digital Transformation
Digital Platform Scale Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
China Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Global Design Thinking Market