
 Brazil Digital Transformation Market | 2026-2036
Brazil Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Digital Transformation Market Insights
Cloud-native architecture is reshaping how Brazilian enterprises deliver software and manage infrastructure. CI&T Inc leverages its São Paulo engineering base to anchor large-scale digital product development for domestic clients. Stefanini Group competes through its managed services footprint across Latin America while sustaining deep integration partnerships with global hyperscalers. TOTVS S.A. dominates the ERP modernization segment, where its vertical-specific modules control renewal cycles in manufacturing and agribusiness.
Brazil digital transformation encompasses the systematic replacement of legacy operational models with digitally integrated processes, spanning cloud infrastructure, data analytics pipelines, and automated decision systems. The technical stack typically involves API-first microservices architectures, container orchestration platforms, and real-time data lakes processing terabyte-scale operational feeds for predictive maintenance and customer personalization. Among deployment models, hybrid cloud configurations capture expanding margin pools as enterprises balance latency-sensitive workloads against regulatory data residency requirements. Within industry verticals, finance and manufacturing lead current spending, while retail accelerates fastest as omnichannel fulfillment pressures intensify.
ANVISA imposes stringent data integrity standards on healthcare technology implementations, compelling vendors to validate audit trails and access controls. The LGPD privacy framework, enforced by the national data protection authority, shapes cross-border data flows and cloud contract negotiations. BIS-equivalent telecommunications standards under ANATEL govern IoT device certification for industrial deployments. Stakeholders must monitor how evolving central bank digital currency infrastructure and open banking mandates will redistribute platform requirements across financial services supply chains.
Market Dynamics
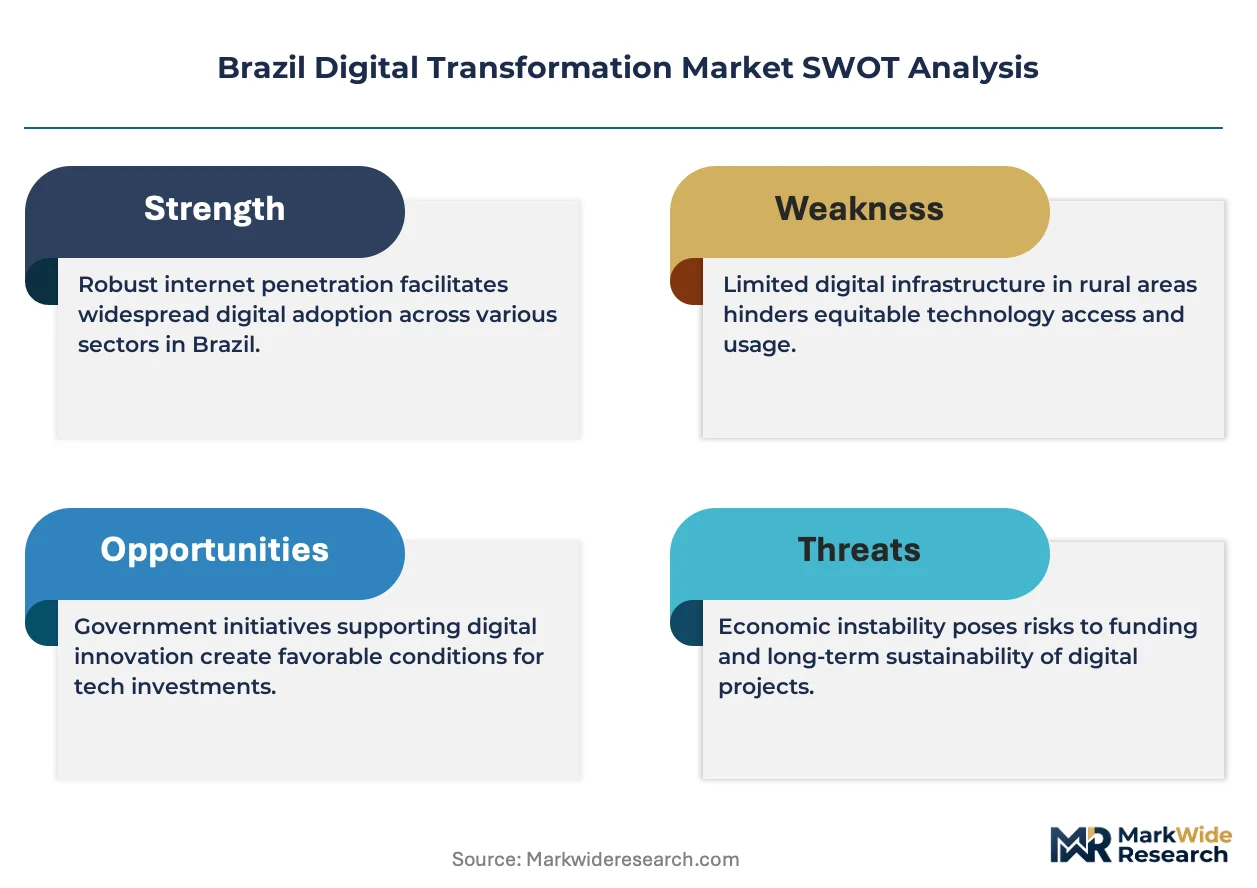
LGPD enforcement and ANVISA data governance mandates are compressing vendor compliance timelines while São Paulo's enterprise corridor concentrates procurement decisions among manufacturing and financial services conglomerates.
Growth Catalysts
- Cloud Migration Mandates:Brazilian financial institutions accelerate off-premises infrastructure deployment to meet central bank operational resilience requirements.
- LGPD Compliance Deadlines:The national data protection authority's enforcement actions compel enterprises to replace legacy data architectures with privacy-by-design systems.
- São Paulo Enterprise Corridor:Manufacturing and retail conglomerates anchor procurement volumes, creating demand density for systems integrators.
Market Restraints
- Legacy System Entrenchment:Decades-old ERP installations in agribusiness and manufacturing create technical debt that slows cloud-native replacement cycles.
- Specialized Talent Scarcity:Domestic supply of DevOps engineers and data governance specialists falls short of enterprise hiring requirements.
- ANATEL Certification Friction:IoT device approval timelines for industrial deployments extend implementation schedules by quarters.
Strategic Opportunities
- Northeast Brazil Digital Hubs:Recife and Fortaleza emerge as secondary engineering centers with lower talent acquisition costs than São Paulo.
- Open Banking Infrastructure:Central Bank of Brazil mandates for API standardization create platform requirements across credit and payments supply chains.
- Edge-Cloud Convergence:Latency-sensitive manufacturing workloads drive hybrid architectures combining on-premise edge nodes with hyperscaler backbones.
Industry Challenges
- Cross-Functional Skill Gaps:Enterprises struggle to hire professionals fluent in both domain operations and cloud architecture.
- Integration Complexity:API-first microservices must coexist with monolithic legacy systems, multiplying deployment risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Digital Transformation Market |
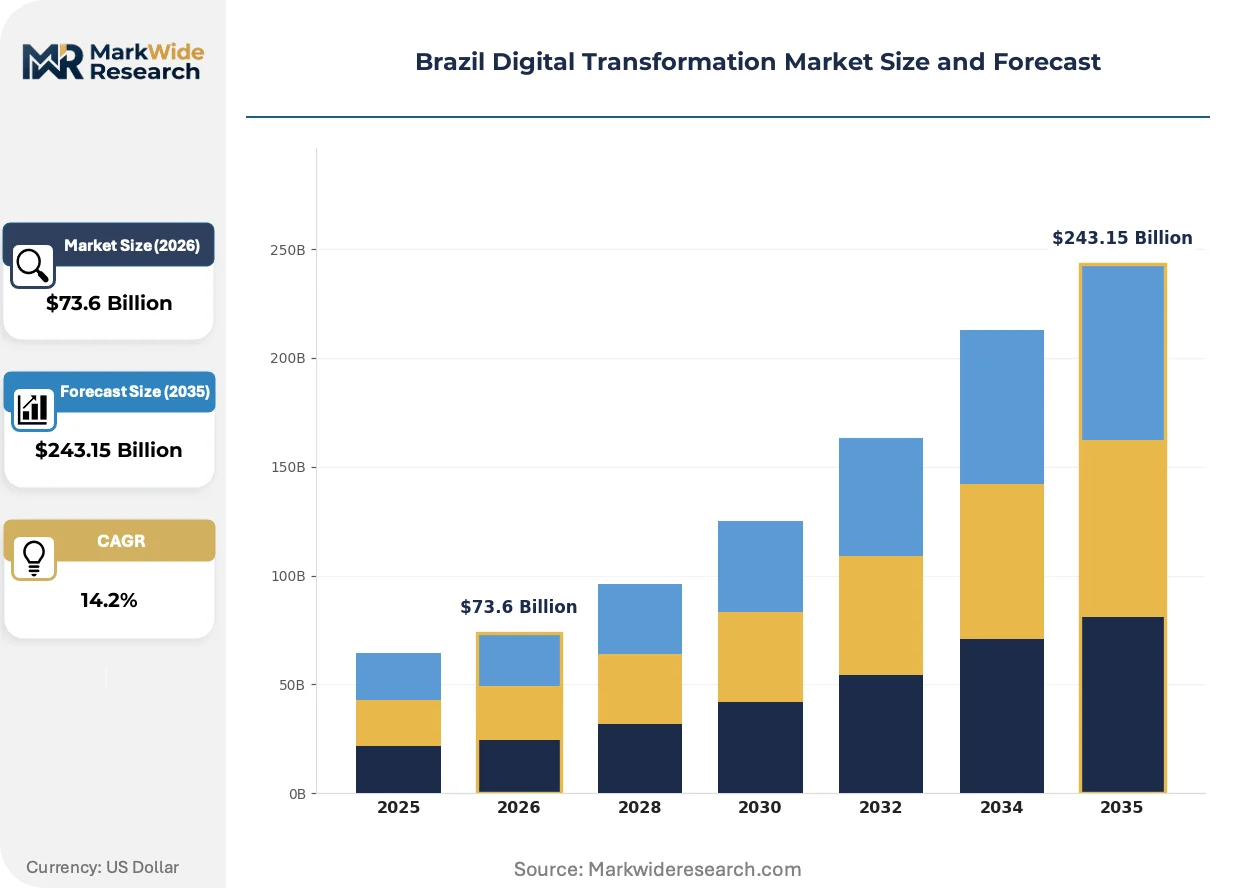
| Market Size in 2026 | $73.6 Billion |
| Market Size in 2035 | $243.15 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: Consulting, Integration, Managed Services, Support Industry Vertical: Finance, Healthcare, Retail, Manufacturing Technology: Artificial Intelligence, IoT, Blockchain, Big Data |
| Companies Covered | CI&T Inc, Stefanini Group, Concrete Solutions, Luby Software LLC, BIX Technology, Tempest Security Intelligence, Neurotech Information Technology, Siena Company, TOTVS S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Digital Transformation Market Trends and Innovations
Artificial intelligence deployment patterns and regulatory data localization requirements are reconfiguring how Brazilian enterprises architect their technology stacks.
Hybrid cloud infrastructure is hybridizing operational technology environments across Brazilian manufacturing. Container orchestration platforms now coordinate workloads between on-premise edge nodes and hyperscaler regions. Petrobras and Vale anchor early deployments, compressing supplier qualification timelines for industrial-grade Kubernetes distributions.
ANVISA's data integrity standards for healthcare technology implementations are tightening audit trail requirements. Vendors must validate access controls and lineage documentation before production deployment. Pharmaceutical distributors and hospital networks in São Paulo and Rio de Janeiro face the steepest compliance ramps.
Subscription-based software procurement is displacing perpetual license models across mid-market enterprises. Channel partners are restructuring compensation around recurring revenue rather than upfront fees. This pattern concentrates most visibly among retail and logistics operators in the Southeast region.
Brazil Digital Transformation Market Segmentation
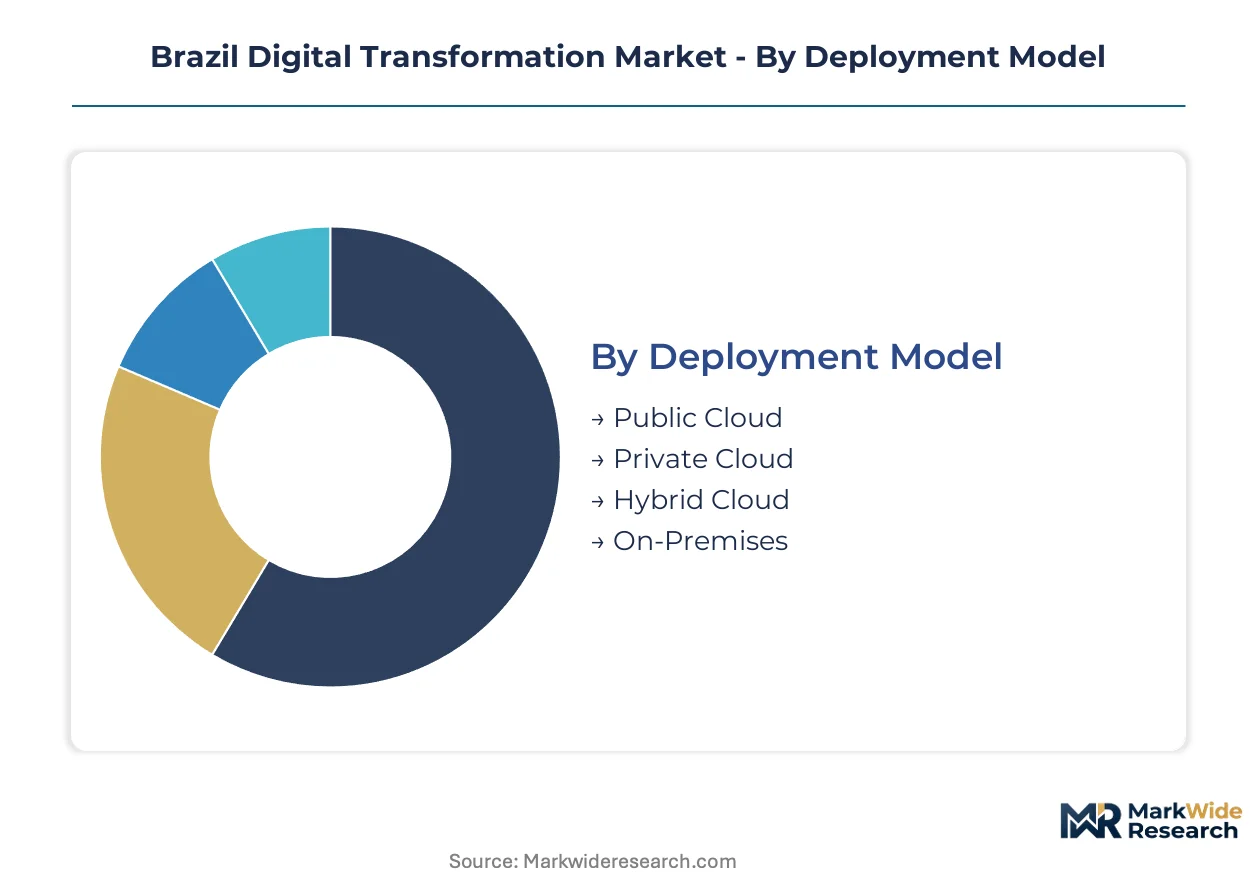
Segmentation in Brazil's digital transformation market reveals how regulatory pressure and infrastructure maturity reshape procurement patterns across enterprise tiers. Deployment choices reflect ANVISA data residency mandates and LGPD cross-border restrictions, while service mix varies with internal technical capabilities.
Deployment Model:
Mature hyperscaler regions coexist with emerging sovereign cloud alternatives as enterprises navigate latency and compliance trade-offs.
- Public Cloud:Hyperscaler regions in São Paulo and Rio de Janeiro host latency-sensitive financial services workloads. Central Bank operational resilience directives accelerate migration among tier-one banks.
- Hybrid Cloud:Container orchestration spans on-premise edge nodes and hyperscaler backbones for manufacturing predictive maintenance. Petrobras and Vale deployments compress supplier qualification timelines for industrial Kubernetes distributions.
- Private Cloud:ANVISA-mandated audit trails drive healthcare and pharmaceutical implementations with dedicated infrastructure stacks.
- On-Premises:Legacy ERP entrenchment in agribusiness maintains substantial installed base despite cloud migration pressure.
Hybrid Cloud handles the majority of new throughput; Public Cloud is the fastest mover on share.
Service Type:
Cost tier differentiation separates advisory engagements from recurring operational contracts across the enterprise maturity spectrum.
- Managed Services:Multi-year operational contracts dominate financial services and retail conglomerates seeking to offset DevOps talent scarcity. Channel partners restructure compensation around recurring revenue rather than upfront fees.
- Integration:API-first microservices deployment for open banking infrastructure and legacy ERP coexistence commands premium billing rates.
- Consulting:LGPD readiness assessments and ANVISA compliance roadmaps anchor mid-market engagements in São Paulo.
- Support:Maintenance contracts for TOTVS S.A. and Stefanini Group installed bases provide predictable revenue streams.
Managed Services captures the largest contract value; Integration is climbing the fastest as open banking mandates proliferate.
Industry Vertical:
Application intensity varies with regulatory exposure and omnichannel operational pressure across Brazilian enterprise corridors.
- Finance:Open banking API standardization and central bank digital currency infrastructure drive platform replacement cycles. Cloud migration mandates from Banco Central do Brasil accelerate off-premises deployment.
- Manufacturing:Edge-cloud convergence for predictive maintenance and supply chain visibility anchors Industry 4.0 capital allocation.
- Retail:Omnichannel fulfillment pressures in Southeast region accelerate subscription-based software procurement.
- Healthcare:ANVISA data integrity standards tighten audit trail requirements for hospital networks and pharmaceutical distributors.
Finance commands the deepest technology stacks; Retail is expanding most quickly as digital commerce penetration deepens.
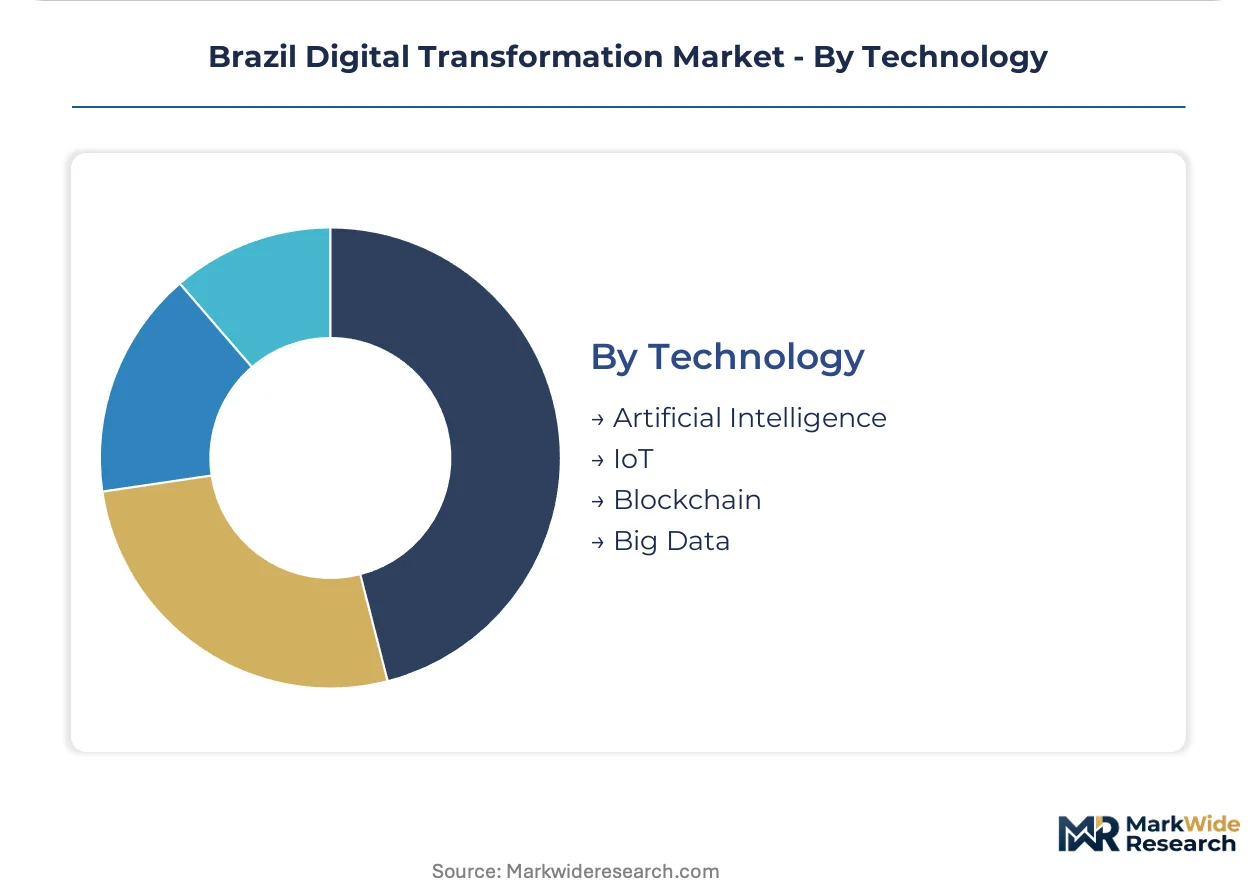
Technology:
Customer type maturity separates proof-of-concept experimentation from production-scale deployment across enterprise segments.
- Artificial Intelligence:Credit scoring automation and customer personalization engines process terabyte-scale operational feeds in tier-one financial institutions.
- Big Data:Real-time data lakes aggregate operational feeds for predictive maintenance and supply chain optimization.
- IoT:ANATEL certification friction extends industrial device approval timelines by quarters for manufacturing and agribusiness sensor networks.
- Blockchain:Trade finance and supply chain traceability pilots concentrate among export-oriented commodity traders.
Big Data underpins the broadest deployment base; Artificial Intelligence is gaining share fastest as model operationalization matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian digital transformation vendors export implementation services across Latin America, with Colombian and Mexican financial institutions absorbing São Paulo-engineered cloud migration frameworks.
São Paulo
Banco Central do Brasil's operational resilience directives drive hyperscaler region expansion for tier-one banks. ANVISA data integrity standards tighten audit trails for pharmaceutical distributors headquartered in the metropolitan corridor. The São Paulo enterprise corridor concentrates procurement decisions among manufacturing conglomerates and retail operators migrating to subscription-based software models.
Rio de Janeiro
State-controlled energy majors anchor edge-cloud convergence deployments for predictive maintenance workloads. LGPD enforcement actions by the national data protection authority accelerate privacy-by-design system replacements in hospital networks. Petrobras compresses supplier qualification timelines for industrial Kubernetes distributions across the metropolitan industrial belt.
Minas Gerais
Agribusiness ERP entrenchment maintains substantial legacy installed base despite cloud migration pressure from TOTVS S.A. renewal cycles. ANATEL certification friction extends IoT sensor network approval timelines for mining and agricultural operations. Belo Horizonte's technology park hosts secondary engineering centers with lower talent acquisition costs than the southeastern megalopolises.
Rio Grande do Sul
Manufacturing predictive maintenance workloads drive hybrid architectures combining on-premise edge nodes with hyperscaler backbones. Open banking API standardization creates platform requirements for regional credit cooperatives and payment processors. Porto Alegre anchors industrial IoT pilot programs for export-oriented machinery producers.
Bahia
Northeast Brazil digital hubs emerge with lower DevOps engineer hiring costs than São Paulo, attracting systems integrator expansion. Central bank digital currency infrastructure pilots redistribute platform requirements across regional financial services supply chains. Salvador's technology corridor concentrates mid-market LGPD readiness assessments and compliance roadmap engagements.
Brazil Digital Transformation Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where no single participant commands dominant share. Systems integrators with multi-year managed services contracts anchor financial services relationships, while ERP specialists control vertical-specific renewal cycles. Two strategic archetypes dominate: hyperscaler-aligned implementation partners and vertical software incumbents with captive maintenance revenue. Competitive moves concentrate on geographic expansion into secondary engineering hubs and portfolio diversification through AI/ML capability acquisition.
Within the São Paulo-based engineering tier, CI&T Inc and Stefanini Group exemplify channel-controlling archetypes with Latin American service footprints. TOTVS S.A. occupies a distinct position as a vertical software incumbent with manufacturing and agribusiness module dominance. These three anchors illustrate how domestic players balance hyperscaler partnerships against proprietary IP development in a market where LGPD compliance and ANVISA validation requirements create switching costs for enterprise clients.
| Leading Market Players |
|---|
| CI&T Inc |
| Stefanini Group |
| Concrete Solutions |
| Luby Software LLC |
| BIX Technology |
| Tempest Security Intelligence |
| Neurotech Information Technology |
| Siena Company |
| TOTVS S.A. |
| Others |
Pricing and Supply Chain Analysis
Hyperscaler cloud infrastructure concentration in São Paulo and Rio de Janeiro anchors margin pools in managed services and integration tiers, with proximity to enterprise corridors determining delivery cost premiums for systems integrators competing for financial services contracts.
Pricing Analysis
Legacy ERP maintenance contracts trade at substantial discounts to cloud-native transformation engagements, while next-generation AI-enabled implementations command premium billing multiples. Three-tier pricing structure across premium, standard, and economy levels separates hyperscaler-certified implementation partners from regional systems integrators and commodity staffing providers. Price differentiation rests on LGPD compliance certification depth and vertical-specific module expertise. Cost compression in mid-market consulting tiers is intensifying because talent scarcity in DevOps and data governance disciplines constrains supply expansion. Retail conglomerates in the Southeast region exhibit highest price sensitivity, while Banco Central do Brasil-mandated resilience programs render tier-one banks least sensitive to implementation premiums.
Supply Chain Analysis
Stefanini Group, CI&T Inc, and TOTVS S.A. anchor domestic implementation capacity, with delivery networks concentrated in São Paulo, Recife, and Belo Horizonte. Engineering talent pools draw from Brazil's southeastern megalopolises and emerging Northeast digital hubs, while hyperscaler backbone infrastructure sources from AWS, Microsoft Azure, and Google Cloud regional deployments. Supply chain risk centers on single-source vulnerability for ANVISA-validated healthcare technology implementations, where approved vendor lists compress qualification pathways. Distribution runs through multi-year managed services contracts with financial services conglomerates, channel partner networks, and direct enterprise sales teams serving manufacturing and agribusiness verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's digital transformation market functions as a defensive-moat arena where LGPD compliance entrenchment and ANVISA validation requirements create substantial switching costs for enterprise clients, cementing incumbent positions.
For Market Incumbents: Harden compliance certification depth as the primary defensive perimeter against emerging cloud-native specialists. Invest in backward integration into proprietary AI/ML capability development to reduce dependency on hyperscaler platform roadmaps. Expand delivery capacity in Recife and Fortaleza to capture cost arbitrage against São Paulo talent inflation. Prioritize multi-year managed services contract renewals with manufacturing conglomerates before open banking infrastructure mandates proliferate integration complexity. For New Entrants and Emerging Players: Pursue white-space penetration in Northeast Brazil digital hubs, where lower DevOps engineer acquisition costs enable competitive rate positioning against southeastern incumbents. Target mid-market LGPD readiness assessment engagements in Salvador and Fortaleza as the most penetrable entry vector. Anchor go-to-market strategy through partnership with hyperscaler field organizations seeking localized implementation capacity for central bank digital currency infrastructure pilots. For Investors and Strategic Acquirers: Capital is best deployed toward vertical software incumbents with captive maintenance revenue streams and ANVISA-validated healthcare technology footprints, where regulatory entrenchment sustains renewal predictability across multi-year horizons. Acquisition priority rests on firms combining ERP module dominance with nascent AI/ML service capabilities. Monitor central bank open banking mandate enforcement cadence as the critical inflection signal for platform replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI/ML Capability Acquisition | CI&T Inc and Stefanini Group compete for data science talent to anchor predictive maintenance offerings for Petrobras. |
| Geographic Expansion | Systems integrators establish delivery centers in Recife and Fortaleza to capture 30-40% cost arbitrage on engineering talent. |
| Regulatory Certification Investment | ANVISA validation timelines compress competitive qualification for pharmaceutical distributor and hospital network contracts. |
| Hyperscaler Partnership Deepening | AWS, Azure, and Google Cloud field organizations channel enterprise contracts toward certified implementation partners. |
| Vertical Software Module Development | TOTVS S.A. renewal cycles in agribusiness and manufacturing sustain predictable revenue despite cloud migration pressure. |
Research Methodology
The analysis maps cloud infrastructure deployment, managed services procurement, ERP modernization, and AI/ML implementation sub-sectors, each validated through CTOs, IT procurement officers, platform engineers, and channel partners at financial institutions, manufacturing conglomerates, and retail operators. Primary interview findings triangulate against ANVISA regulatory filings, Banco Central do Brasil policy directives, SEC filings from CI&T Inc and TOTVS S.A., hyperscaler regional capex disclosures, and LGPD enforcement action records. Bottom-up contract value aggregation and top-down macroeconomic scaling cross-validate segment sizing.
Assumptions held fixed include current LGPD enforcement intensity, ANVISA validation timeline structures, and central bank operational resilience directive implementation schedules across the projection horizon. Variables include open banking API standardization adoption velocity, central bank digital currency infrastructure deployment pace, and edge-cloud convergence penetration in manufacturing. Segmentation dimensions modeled span deployment model, service type, industry vertical, technology category, and enterprise size tier. CAGRs derive from regression analysis of historical procurement patterns against regulatory mandate timelines and talent supply elasticity.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rate volatility, domestic interest rate trajectories, or federal technology investment appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding hyperscaler regional expansion schedules and ANATEL IoT certification process efficiency. Quarterly review of Banco Central do Brasil policy communications, ANVISA guidance updates, and São Paulo technology labor market indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Telco Transformation Market
Digital Transformation
Qatar Digital Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
France Digital Transformation Market
Digital Transformation
South East Asia Digital Transformation Market
Digital Transformation
South Korea Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Workspace Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
APAC Digital Transformation Market
Digital Transformation
UAE Digital Transformation Market
Digital Transformation
Canada Digital Transformation Market