
 Italy Digital Transformation Market | 2026-2036
Italy Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Digital Transformation Market Insights
Modular service bundling is realigning how Italian enterprises procure digital infrastructure. Microsoft Corporation leverages its cloud-native productivity stack to anchor hybrid deployment contracts across mid-market manufacturers. SAP SE specializes in vertical ERP modules that integrate shop-floor IoT with financial planning, sustaining renewal rates in the automotive supply base. Amazon Web Services competes on compute pricing and edge locations, extending its Milan region footprint to capture latency-sensitive workloads from Lombardy-based industrials.
Italy digital transformation encompasses the integration of cloud computing, artificial intelligence, Internet of Things sensors, and advanced data analytics into enterprise operations, typically delivered through API-connected platforms that orchestrate real-time information flows across production, distribution, and customer touchpoints. Its primary purpose is to replace fragmented legacy IT with interoperable systems that reduce operational friction and enable predictive decision-making. Cloud Computing and AI together attract the largest share of enterprise IT budgets as manufacturers seek elastic infrastructure for machine-learning model training. Within End User segmentation, Manufacturing and BFSI represent the deepest margin pools, reflecting stringent compliance requirements and high transaction volumes that justify premium platform spending.
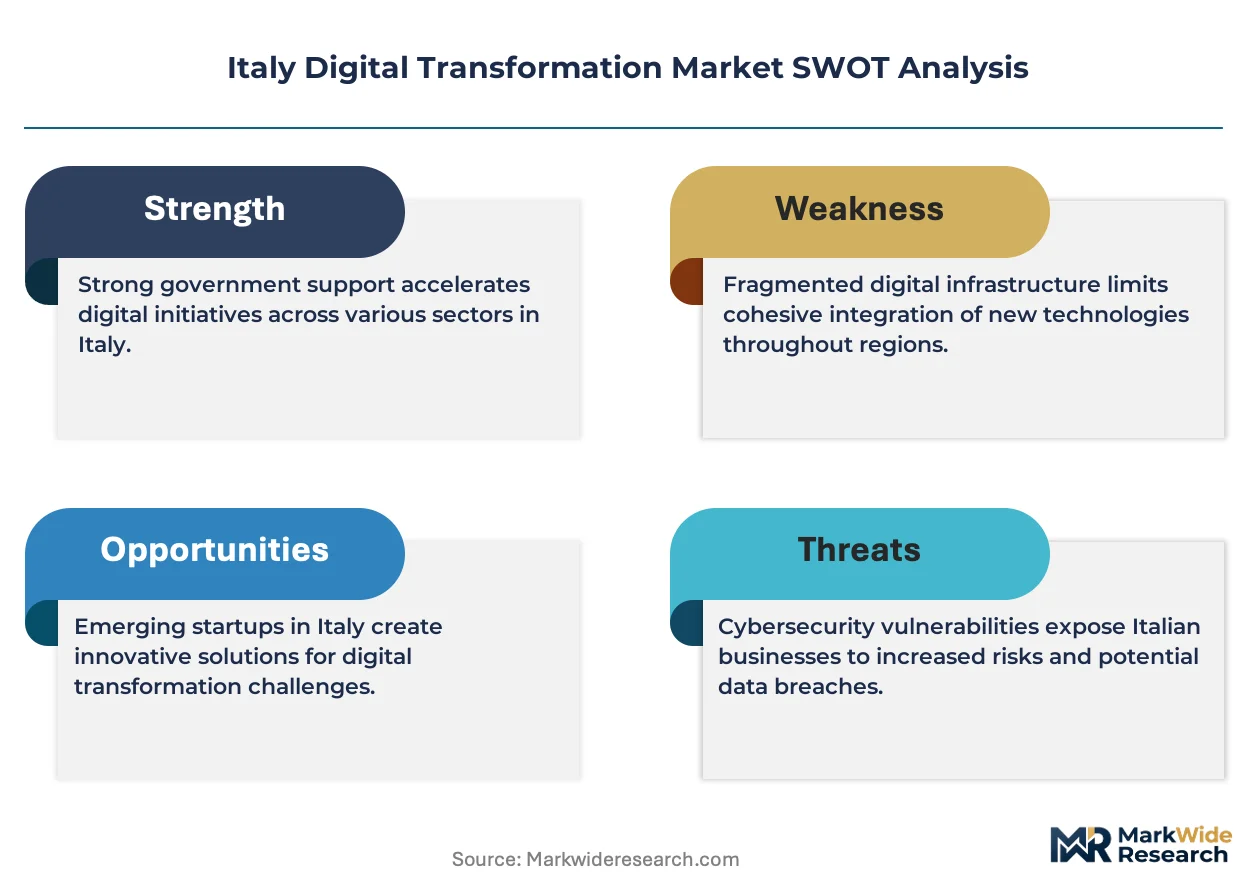
Italy's digital transformation agenda operates under overlapping oversight from the EU AI Act, which imposes risk-tiered obligations on automated decision systems, and the national Agency for Digital Italy (AgID), which enforces interoperability standards and cloud migration protocols for public-sector contractors. The EU Green Deal further shapes demand by mandating emissions traceability that requires IoT-enabled monitoring and blockchain-verified reporting across supply chains. Stakeholders must weigh compliance investment against platform lock-in as regulatory granularity intensifies and procurement rules favor vendors with certified sovereign data architectures.
Market Dynamics
Italy's digital transformation market is being reshaped by the collision between EU-mandated compliance timelines and fragmented legacy infrastructure that resists cloud-native orchestration. The National Recovery and Resilience Plan is forcing public and private capital into synchronized modernization cycles.
Growth Catalysts
- EU AI Act compliance deadlines:Risk-tiered obligations on automated systems are compelling manufacturers to upgrade decision-support platforms, creating immediate procurement pull through 2026.
- Automotive supply base:Tier-1 suppliers around Turin are deploying IoT-enabled predictive maintenance to meet OEM traceability requirements under the EU Green Deal.
- Cloud migration protocols:AgID mandates for public-sector contractors are channeling sovereign-architecture spending toward certified domestic providers.
Market Restraints
- Legacy system debt:Decades of on-premise ERP installations in Lombardy manufacturing create integration friction that slows platform replacement cycles.
- Specialized talent scarcity:DevOps and MLOps expertise concentrates in Milan, leaving central and southern regions dependent on costly external contracting.
- Input cost volatility:Semiconductor and energy price instability compresses IT budget elasticity for mid-market manufacturers.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily exhibit sub-20 percent cloud adoption among SMEs, creating whitespace for region-specific service bundles.
- Edge-AI convergence:Latency-sensitive quality-control applications in Emilia-Romagna food processing are driving demand for on-premise inference hardware.
- CSRD reporting mandates:Emissions traceability requirements are opening consulting and platform markets for sustainability data orchestration.
Industry Challenges
- Interoperability certification delays:AgID approval timelines for cloud service providers extend procurement cycles by 6-12 months.
- Shop-floor integration complexity:OT-IT convergence projects in Piedmont automotive plants face downtime risks that deter aggressive migration schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Digital Transformation Market |
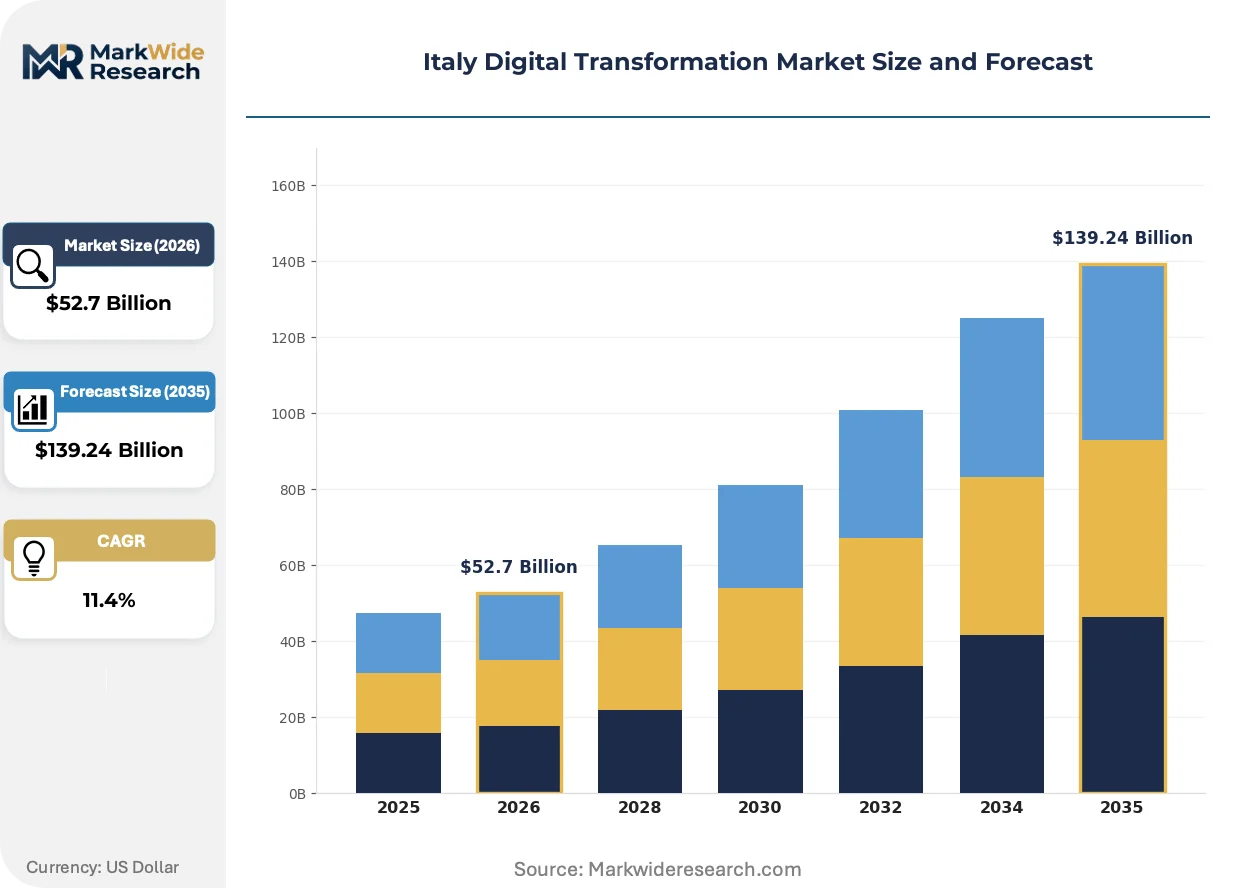
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $139.24 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud Computing, AI, IoT, Big Data End User: Manufacturing, Retail, Healthcare, BFSI Application: Customer Engagement, Operational Efficiency, Supply Chain Management, Data Analytics Deployment: On-Premise, Hybrid, SaaS, PaaS |
| Companies Covered | Accenture PLC, Google LLC, Microsoft Corporation, IBM Corporation, SAP SE, Oracle Corporation, Hewlett Packard Enterprise, Siemens AG, Amazon Web Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Digital Transformation Market Trends and Innovations
Platform consolidation is compressing vendor diversity as enterprises prioritize integrated stacks over best-of-breed point solutions. Regulatory complexity is simultaneously elevating compliance-automation tools and sovereign-cloud architectures.
API-orchestrated microservices are consolidating middleware layers across Italian manufacturing ERP environments. Mid-market metalworking and machinery producers in Veneto are migrating from on-premise monoliths to containerized deployments. This consolidation is compressing the addressable market for standalone integration vendors while expanding contract values for full-stack platform providers.
The EU AI Act's risk-classification framework is mandating algorithmic audit trails for high-stakes automated decisions. Automotive and medical device manufacturers face documentation burdens that favor pre-certified AI platforms. Northern Italian industrials are responding by embedding compliance tooling directly into MLOps pipelines rather than retrofitting governance post-deployment.
Subscription-based platform economics are displacing perpetual-license procurement in BFSI and manufacturing verticals. Procurement teams now prioritize total-cost-of-ownership metrics over upfront capital expenditure. This shift is most visible among Milan-headquartered financial institutions consolidating vendor relationships under multi-year enterprise agreements with built-in upgrade cycles.
Italy Digital Transformation Market Segmentation
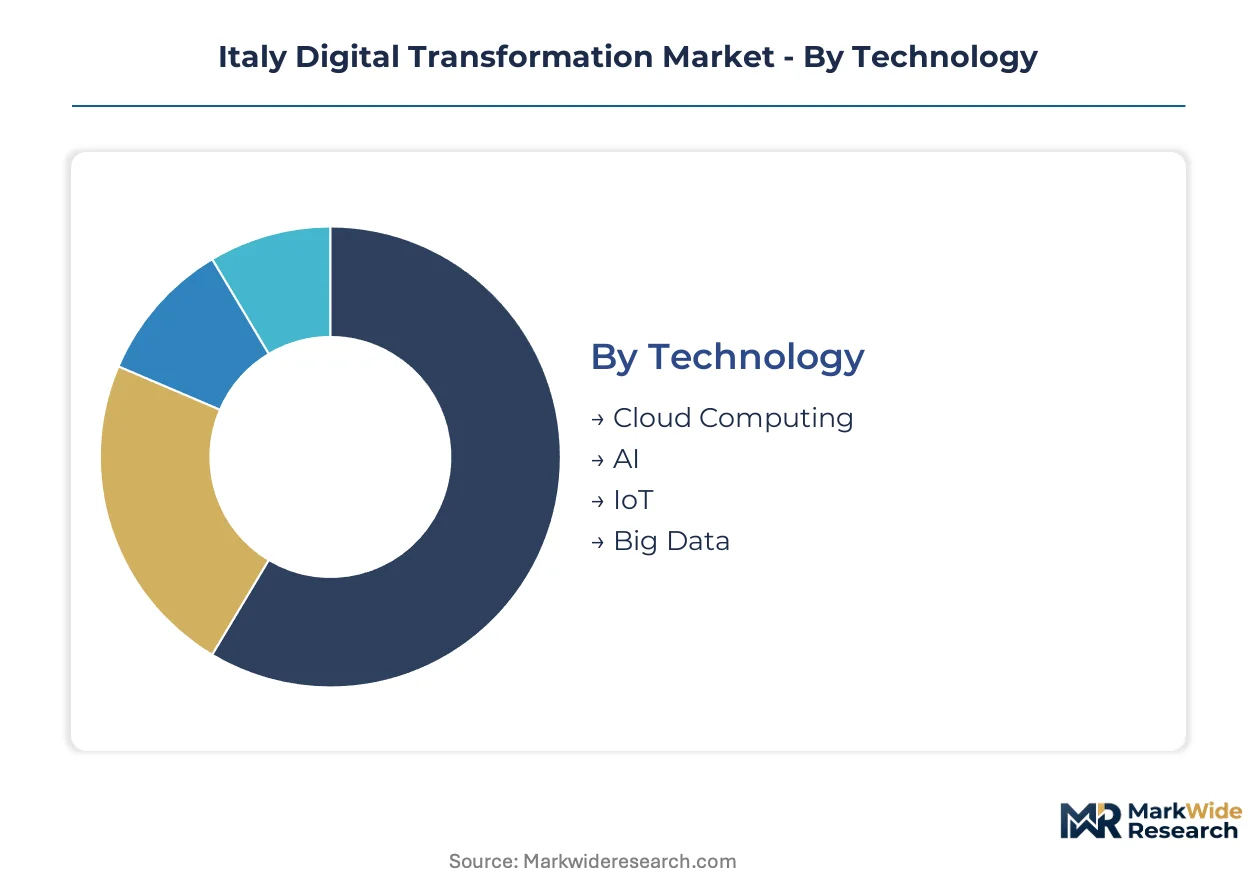
Italian enterprises allocate technology budgets across distinct capability layers, with procurement patterns diverging sharply between compliance-driven public contractors and margin-focused private manufacturers. Understanding these segment boundaries reveals where platform vendors can anchor multi-year contracts versus where point solutions still command premium pricing.
Technology:
Investment intensity varies by infrastructure maturity, with northern industrial clusters favoring integrated stacks while southern SMEs pursue modular entry points.
- Cloud Computing:Elastic infrastructure services dominate enterprise IT spending as Lombardy manufacturers migrate production workloads to sovereign-certified environments. AgID procurement rules channel public-sector demand toward domestic cloud providers with certified data architectures.
- AI:Machine-learning platforms face risk-tiered compliance obligations under the EU AI Act, compelling automotive and medical device producers to embed audit trails directly into MLOps pipelines. High-stakes automated decision systems in Turin supply chains drive premium spending on pre-certified solutions.
- IoT:Sensor networks enable emissions traceability mandated by the EU Green Deal, with Tier-1 suppliers deploying predictive maintenance at scale.
- Big Data:Analytics platforms consolidate fragmented ERP data across Veneto metalworking clusters.
Volume sits with Cloud Computing; growth tilts toward AI as compliance deadlines harden.
End User:
Vertical buying power concentrates where regulatory density and transaction velocity justify platform consolidation.
- Manufacturing:Shop-floor IoT integration and predictive maintenance dominate capital allocation, with Piedmont automotive plants pursuing OT-IT convergence despite downtime risks. Metalworking and machinery producers in Veneto drive containerized ERP replacement cycles.
- BFSI:Milan-headquartered financial institutions prioritize subscription economics and built-in upgrade cycles, consolidating vendor relationships under multi-year enterprise agreements. Compliance automation and real-time risk analytics command premium platform spending.
- Healthcare:Medical device manufacturers face EU AI Act documentation burdens for automated diagnostic systems.
- Retail:Customer data platforms and omnichannel orchestration attract mid-market investment in northern urban centers.
Manufacturing captures the deepest contract values; BFSI is climbing the fastest on regulatory automation demand.
Application:
Use-case prioritization reflects whether enterprises seek revenue expansion or cost containment.
- Operational Efficiency:Process automation and workflow optimization anchor manufacturing budgets, with Emilia-Romagna food processors deploying edge-AI for latency-sensitive quality control. Real-time production monitoring reduces waste and energy consumption under EU Green Deal pressures.
- Supply Chain Management:Blockchain-verified emissions reporting and IoT-enabled traceability dominate procurement for export-oriented industrials. CSRD mandates open consulting and platform markets for sustainability data orchestration across Lombardy-based supply networks.
- Customer Engagement:Personalization engines and omnichannel platforms serve retail and BFSI verticals.
- Data Analytics:Predictive decision-support tools consolidate fragmented legacy data across public-sector contractors.
Operational Efficiency holds installed base dominance; Supply Chain Management gains share fastest on sustainability mandates.
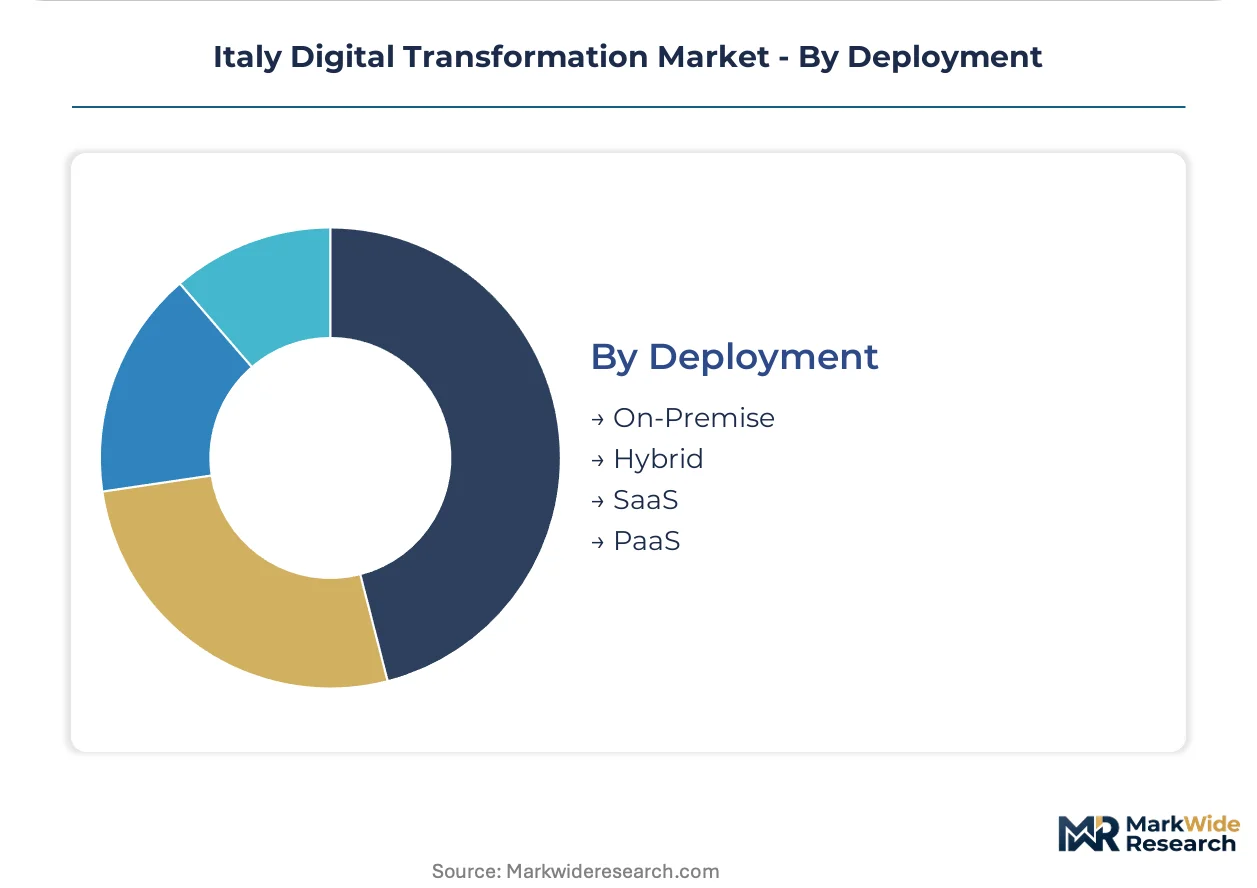
Deployment:
Architecture choices split between latency constraints, data sovereignty requirements, and legacy integration debt.
- Hybrid:Mixed on-premise and cloud workloads dominate northern manufacturing, balancing shop-floor latency requirements with elastic compute for model training. Microsoft anchors multi-year contracts through cloud-native productivity stacks integrated with residual on-premise systems.
- SaaS:Subscription-based platform economics displace perpetual licenses in BFSI and mid-market manufacturing, with procurement teams prioritizing total-cost-of-ownership metrics over upfront capital expenditure.
- On-Premise:Residual deployments persist where legacy ERP debt and integration friction slow migration timelines.
- PaaS:Developer-centric environments attract DevOps-scarce regions dependent on external contracting.
Hybrid deployments command current volume leadership; SaaS is expanding most quickly as subscription economics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lombardy's tax-advantaged industrial zones concentrate digital infrastructure investment, drawing cloud providers and systems integrators into Milan's orbit. The National Recovery and Resilience Plan channels €191 billion through regional development corridors, accelerating procurement cycles in northern manufacturing clusters.
Lombardy
Enterprise cloud migration and AI model training dominate IT spending as manufacturers replace legacy ERP with sovereign-certified platforms. AgID interoperability standards govern public-sector contractor procurement, favoring vendors with certified data architectures. Milan anchors hybrid deployment contracts, with Microsoft and Amazon Web Services competing for latency-sensitive workloads from metalworking and machinery producers.
Piedmont
Tier-1 automotive suppliers deploy IoT-enabled predictive maintenance to meet OEM traceability requirements under the EU Green Deal. EU AI Act risk-tiered obligations compel upgrade cycles for automated decision-support platforms. Turin's engineering talent density sustains complex OT-IT convergence projects despite downtime risks that slow migration timelines.
Veneto
Mid-market metalworking producers pursue containerized ERP replacement, migrating from on-premise monoliths to API-orchestrated microservices. CSRD emissions reporting mandates open consulting markets for sustainability data orchestration. Vicenza and Verona clusters drive subscription-based platform economics, prioritizing total-cost-of-ownership metrics over perpetual licenses.
Emilia-Romagna
Food processors deploy edge-AI for latency-sensitive quality control, creating demand for on-premise inference hardware. EU Green Deal energy consumption pressures accelerate real-time production monitoring investments. Bologna's packaging machinery specialists integrate sensor networks to reduce waste and enable predictive maintenance.
Lazio
Public-sector digitalization concentrates in Rome's administrative core, where AgID cloud migration protocols channel sovereign-architecture spending. Healthcare providers face EU AI Act documentation burdens for automated diagnostic systems. The capital's BFSI institutions consolidate vendor relationships under multi-year enterprise agreements with built-in compliance tooling.
Italy Digital Transformation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Italy's digital transformation market. Global systems integrators anchor large-scale manufacturing contracts, while vertical ERP vendors sustain renewal rates through shop-floor IoT integration. Three archetypes dominate: full-stack cloud hyperscalers, specialized enterprise software providers, and IT services conglomerates. Competitive positioning hardens through strategic partnerships with domestic system integrators and portfolio diversification into sovereign-cloud architectures.
Within the full-stack cloud tier, Microsoft Corporation and Amazon Web Services exemplify divergent market approaches. Microsoft leverages cloud-native productivity stacks to anchor hybrid deployment contracts across mid-market manufacturers, while Amazon Web Services competes on compute pricing and edge location density. SAP SE occupies a distinct position among specialized enterprise software providers, with vertical ERP modules that integrate shop-floor IoT with financial planning. IBM Corporation represents the IT services conglomerate archetype, drawing on decades of public-sector relationships to capture AgID-mandated modernization contracts.
| Leading Market Players |
|---|
| Accenture PLC |
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| Siemens AG |
| Amazon Web Services |
| Others |
Pricing and Supply Chain Analysis
AgID cloud migration protocols are compelling public-sector contractors to prioritize sovereign-certified architectures, forcing vendors to absorb compliance certification costs and compressing margins on standard-tier offerings while enabling premium pricing for pre-certified platforms.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations as Lombardy manufacturers facing EU AI Act deadlines pay 15-25 percent markups for rapid deployment of compliant MLOps pipelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales integration depth. Cost compression in the standard tier is intensifying because hyperscalers are matching domestic providers on sovereign-cloud pricing. Mid-market metalworking producers in Veneto exhibit highest price sensitivity, while Turin-based automotive Tier-1s prioritize compliance speed over unit economics.
Supply Chain Analysis
Italy's National Recovery and Resilience Plan local-content provisions are reshaping sourcing patterns for edge-AI hardware, mandating domestic assembly quotas that extend procurement cycles. Semiconductor supply draws from Taiwan, South Korea, and the Netherlands, while sovereign-cloud infrastructure rests on German and French data center equipment. Single-source vulnerability concentrates in advanced GPU allocations for model training workloads. Distribution runs through Milan-headquartered systems integrators with AgID certification, channeling public-sector contracts toward approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Containerized microservices are displacing monolithic ERP installations across Italian manufacturing, marking a definitive infrastructure transition phase that rewards vendors with hybrid deployment expertise.
For Market Incumbents: To counter margin erosion from hyperscaler price-matching, anchor renewal rates through embedded compliance tooling and backward integration into sovereign-cloud infrastructure. Deepen vertical control over MLOps pipeline certification to lock in automotive supply base contracts. Prioritize capacity addition in Lombardy and Piedmont to capture latency-sensitive edge-AI workloads. For New Entrants and Emerging Players: Edge-AI inference hardware for Emilia-Romagna food processors offers the most penetrable white-space target, given latency requirements that hyperscalers struggle to meet. Campania and Sicily SMEs present underpenetrated cloud adoption below 20 percent, creating region-specific service bundle opportunities. Lead with compliance-automation tooling as the primary go-to-market angle, embedding EU AI Act documentation directly into platform offerings. For Investors and Strategic Acquirers: The window for entry favors specialized compliance-automation vendors with pre-certified AI platforms and established AgID relationships. Long-term viability hinges on regulatory complexity deepening rather than simplifying, rewarding vertical expertise over horizontal scale. Monitor AgID interoperability certification queue lengths as the critical inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign-Cloud Certification Investment | AgID approval unlocks public-sector procurement pipelines worth billions in National Recovery and Resilience Plan allocations. |
| Edge-AI Hardware Partnership | Latency-sensitive quality control in Emilia-Romagna food processing creates captive demand for on-premise inference infrastructure. |
| Compliance-Automation Platform Launch | EU AI Act documentation burdens favor pre-certified MLOps pipelines with embedded audit trail capabilities. |
| Regional Systems Integrator Acquisition | Milan and Turin channel relationships accelerate sovereign-cloud deployment across Lombardy manufacturing clusters. |
| Containerized ERP Integration | API-orchestrated microservices consolidate fragmented Veneto metalworking environments into multi-year subscription contracts. |
Research Methodology
Document review covered AgID procurement guidelines, EU AI Act implementation timelines, and National Recovery and Resilience Plan disbursement records, complemented by interviews with platform engineers, IT procurement officers at Lombardy manufacturers, compliance leads at automotive Tier-1 suppliers, and channel partners in Milan's systems integration ecosystem. Secondary validation drew from hyperscaler capex disclosures, SEC filings of listed enterprise software vendors, and Italian trade association cloud adoption surveys. Bottom-up spending estimates across technology segments were triangulated against top-down GDP-linked IT investment projections.
Historical spending patterns were cross-referenced against panel input from regional CIOs to anchor growth assumptions across the projection horizon. The analytical framework modeled deployment architecture, organization size, vertical industry, integration complexity, and regional adoption pattern as primary segmentation dimensions. CAGRs were derived from slope analysis of technology penetration curves adjusted for regulatory deadline effects. Forecast inputs incorporated AgID certification queue dynamics and EU Green Deal emissions reporting mandate timelines.
Several conditions sit outside the modeled scope, including geopolitical disruptions to semiconductor supply chains and potential EU AI Act enforcement variations across member states. Forecasts reflect documented assumptions about sovereign-cloud migration pace and mid-market ERP replacement cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
ASEAN Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Oman Digital Transformation Market
Digital Transformation
Automotive Digital Transformation Market
Digital Transformation
Telco Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Global Application Transformation Market
Digital Transformation
Brazil Digital Transformation Market
Digital Transformation
Enterprise 2.0 Technologies Market
Digital Transformation
Colombia Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
Innovation Management Market
Digital Transformation
SQL Server Transformation Market
Digital Transformation
Qatar Digital Transformation Market