
 Nonwoven Flanging Market | 2026-2036
Nonwoven Flanging Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Flanging Market Intelligence
Buyer consolidation among Tier 1 hygiene and medical product manufacturers is realigning procurement leverage across the supply base. Ahlstrom leverages its European manufacturing footprint to sustain long-term contracts with institutional healthcare buyers. Freudenberg Performance Materials anchors its position through backward integration into polymer staple fiber production. Berry Global Inc. competes on scale across North American converting operations, while DuPont differentiates via proprietary spunbond-meltblown-spunbond composite technologies.
Nonwoven flanging denotes edge-finished strips or bindings fabricated from bonded, entangled, or melt-extruded fibrous webs, typically calendered to densities between 0.05 and 0.30 g/cm³ for seam reinforcement and dimensional stability in finished goods. The process serves primarily to prevent fraying, enable heat-sealing, and provide structural integrity in disposable and durable applications across hygiene, medical, and industrial end uses. Spunbond flanging dominates volume due to its tensile strength and cost efficiency in high-speed converting lines, while meltblown variants command premium positioning in filtration and barrier applications where micron-level pore structure determines performance. Needle punch flanging occupies a mature niche in geotextile and construction reinforcement, with polyester and polypropylene material grades splitting demand based on chemical resistance and thermal bonding requirements.
EPA regulations on volatile organic compound emissions from thermal bonding ovens constrain plant siting and capital deployment in the United States. FDA device and textile requirements for medical-grade flanging mandate biocompatibility testing and lot traceability, elevating compliance costs for entrants. China's SAMR enforces GB standards for automotive interior nonwovens, including flammability and fogging specifications that shape product development priorities. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America, as these will determine recyclability mandates and material substitution pathways for polypropylene-dominant supply chains.
Market Dynamics
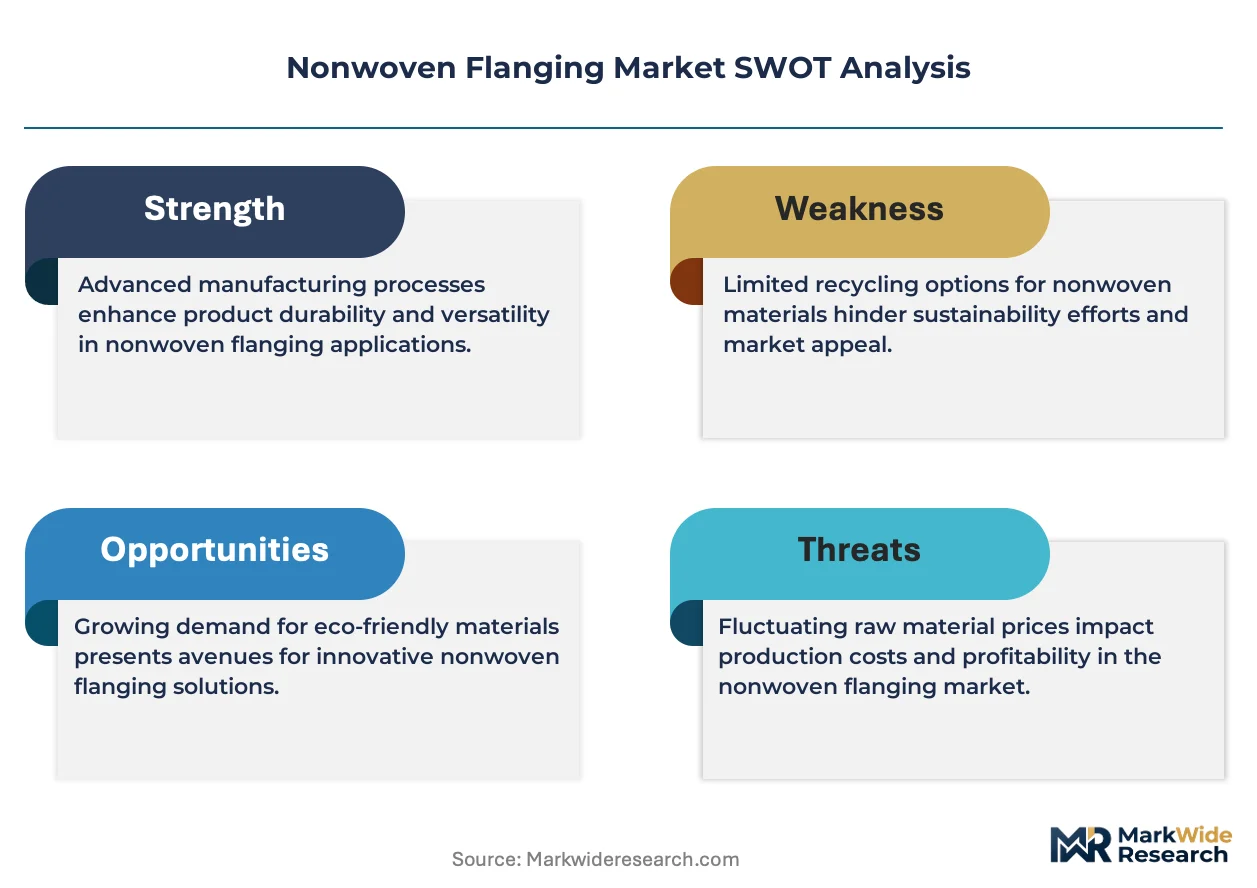
Buyer consolidation among Tier 1 hygiene and medical product manufacturers is compressing supplier margins and forcing flanging producers to defend position through dedicated capacity contracts and technical service bundling rather than commodity pricing alone.
Growth Catalysts
- EPA emission controls on thermal bonding:Stricter volatile organic compound limits are accelerating capital turnover toward electric and infrared curing systems, creating replacement demand for compliant flanging equipment and substrates.
- Medical protective apparel procurement:United States healthcare systems are expanding stockpiles of isolation-grade spunbond-meltblown-spunbond composites, directly lifting specification-grade flanging volumes for seam sealing applications.
- China's GB standards enforcement:SAMR mandates for automotive interior nonwovens, including fogging and flammability specifications, are redirecting domestic production toward certified flanging suppliers capable of lot traceability.
Market Restraints
- Polypropylene feedstock volatility:Propylene monomer price swings tied to naphtha-cracking economics compress margin predictability for spunbond flanging producers lacking long-term offtake agreements with polymer suppliers.
- East Asian supply concentration:Meltblown substrate capacity clusters in Zhejiang and Jiangsu provinces expose downstream converters to single-source risk during regional power rationing or environmental compliance shutdowns.
- Biodegradable substitute threat:PLA and PHA nonwoven alternatives in European hygiene applications are displacing conventional polypropylene flanging in premium disposable segments where compostability certification commands buyer preference.
Strategic Opportunities
- India's hygiene market underpenetration:Rural diaper and feminine hygiene adoption rates below 35 percent create whitespace for cost-optimized needle punch flanging in economy-tier products distributed through kirana networks.
- EU Green Deal recyclability mandates: Extended producer responsibility frameworks for single-use medical textiles are incentivizing mono-material PP flanging designs compatible with mechanical recycling streams.
- Digital printing convergence:Inline inkjet decoration of nonwoven substrates is creating demand for surface-modified flanging with controlled surface energy for adhesion, opening technical differentiation for compounders.
Industry Challenges
- Multiaxis calendering skill scarcity:Precision gap control for sub-0.10 g/cm³ density targets requires operators trained in thermal-rheological fiber behavior, a competency gap acute in North American converting operations.
- FDA 510(k) timeline compression:Medical-grade flanging submissions for novel barrier applications face 180-day review cycles that mismatch quarterly procurement calendars of hospital group purchasing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Flanging Market |
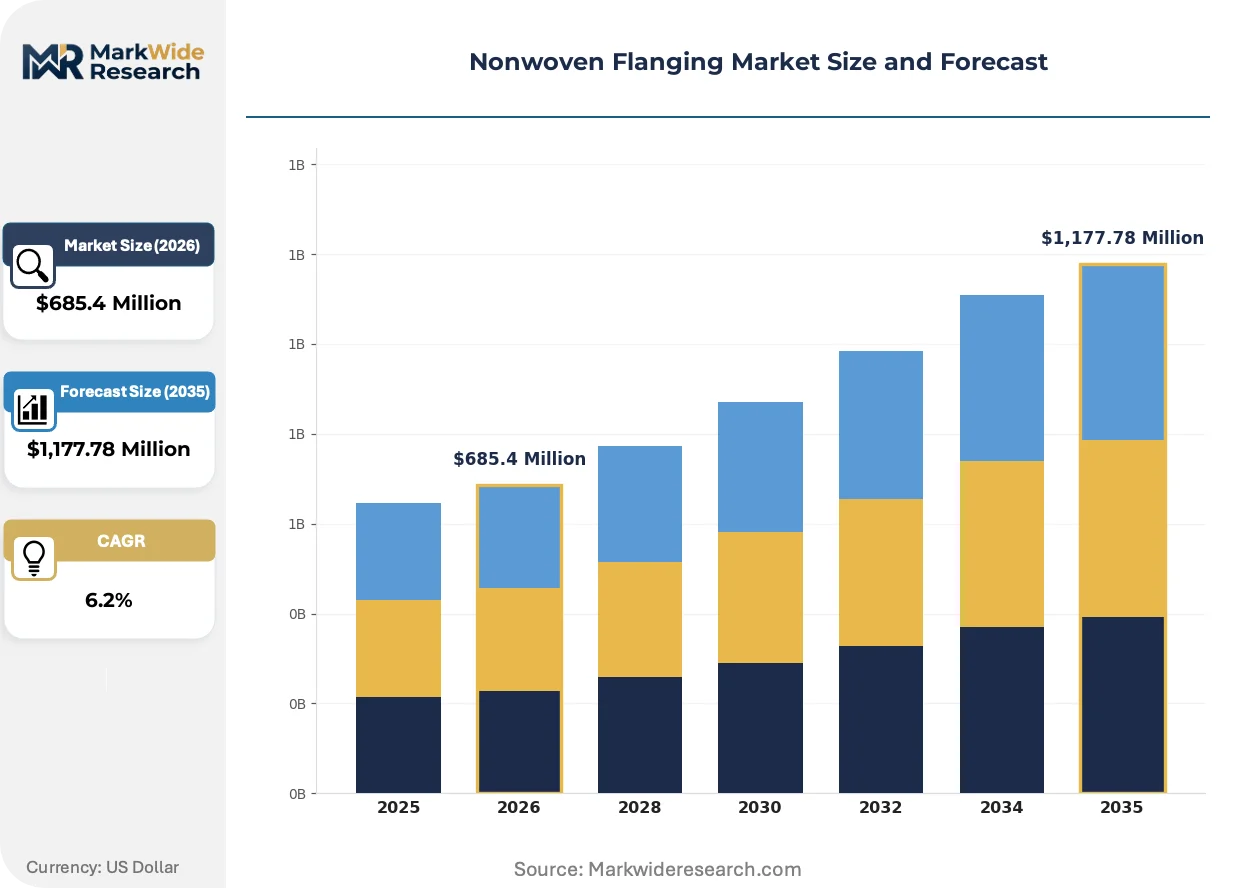
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Bonded, Spunbond, Meltblown, Needle Punch End Use Industry: Medical, Automotive, Construction, Hygiene Material: Polypropylene, Polyester, Rayon, Biodegradable Application: Filtration, Isolation Gowns, Geotextiles, Packaging |
| Companies Covered | Ahlstrom, Johns Manville, Berry Global Inc., Suominen, DuPont, Freudenberg Performance Materials, Fitesa, Toray Industries, Inc., Kimberly-Clark Worldwide, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Flanging Market Strategic Shifts & Innovations
Active material science and process control advances are redefining performance thresholds across hygiene, medical, and industrial end uses, with functional surface engineering and regulatory compliance emerging as the primary axes of supplier differentiation.
Spunbond-meltblown nanofiber lamination is converging with ultrasonic bonding equipment to enable sub-micron filtration flanging without chemical binders. Automotive cabin air filter manufacturers in Germany and Japan are qualifying these composite structures for ISO 5011 dust retention standards. The elimination of thermal bonding ovens reduces EPA compliance burdens for US-based converters while compressing energy costs per linear meter.
China's MEE enforcement of dual carbon goals is tightening energy intensity benchmarks for melt-extrusion lines, forcing domestic producers toward electrified spinneret packs and closed-loop quench air systems. Zhejiang-based suppliers are retrofitting existing assets to avoid production suspensions during regional carbon quota audits. The policy cascade is elevating capital requirements for new market entrants while consolidating output among state-supported industrial groups.
Hospital procurement departments are consolidating vendor lists around suppliers offering lot-level biocompatibility documentation and sterilization validation. Group purchasing organizations in the United States are displacing spot-market sourcing with multi-year master service agreements that bundle flanging supply with technical support and regulatory filing assistance. This contractual shift favors incumbent producers with captive testing laboratories and FDA submission experience over regional converters competing on unit price alone.
Nonwoven Flanging Market Segmentation
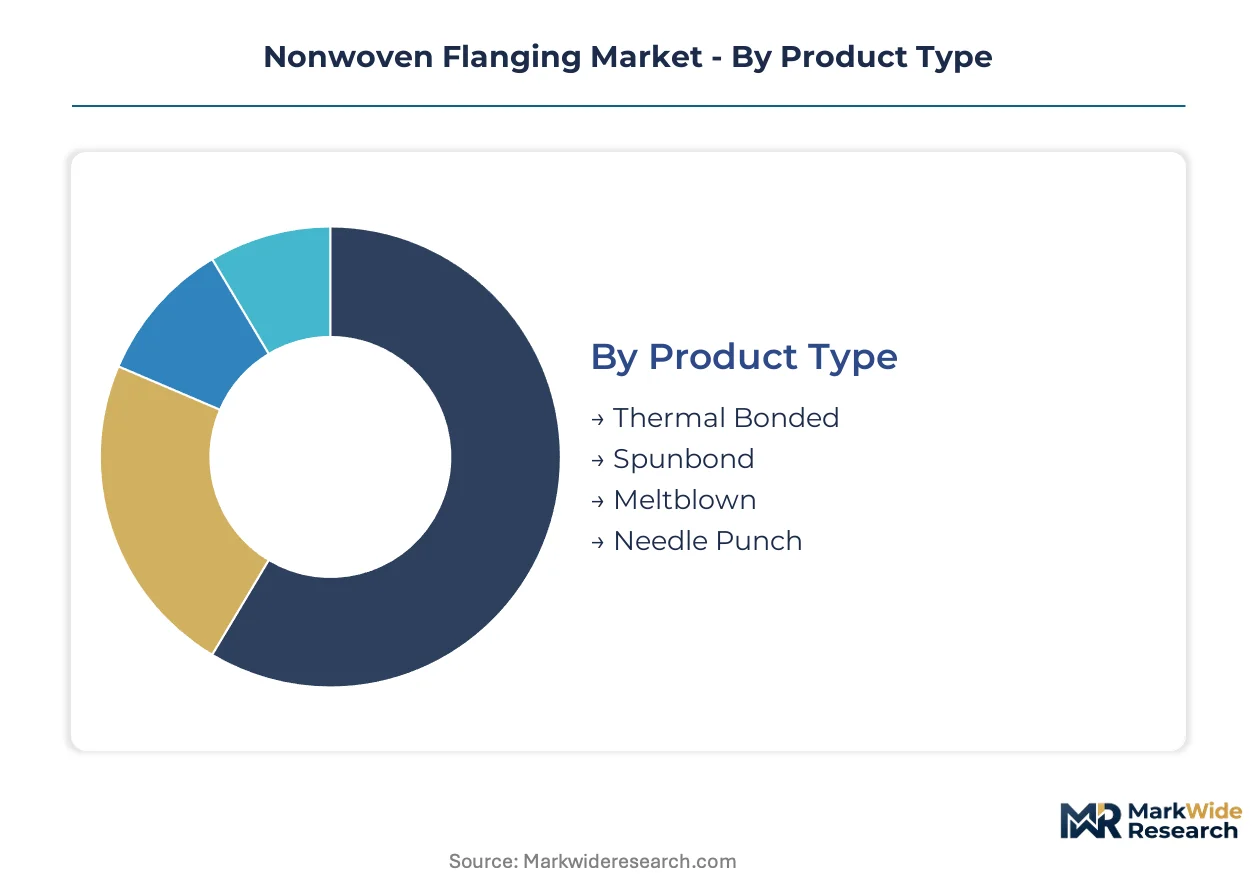
Nonwoven flanging procurement decisions hinge on balancing performance specifications against converting economics and regulatory compliance. Material composition and bonding technology determine seam integrity, while end-use certification requirements fragment supplier capabilities across medical, automotive, and industrial verticals.
Product Type:
Standardization dominates high-volume hygiene and packaging applications, whereas medical and filtration segments demand customized calendering profiles and density gradients.
- Spunbond:Continuous filament webs calendered to 0.05–0.15 g/cm³ deliver tensile strength for high-speed converting lines. US hospital group purchasing organizations specify spunbond flanging for isolation gown seams under FDA textile device requirements. Cost efficiency and line speed compatibility anchor volume leadership.
- Meltblown:Microfiber structures with sub-micron pore distributions enable barrier performance without laminate complexity. German automotive cabin air filter manufacturers qualify meltblown flanging for ISO 5011 dust retention under KBA type approval protocols. Premium positioning reflects energy-intensive extrusion and quench air precision.
- Thermal Bonded:Point-bonded webs using calendar roller patterns achieve dimensional stability for packaging edge reinforcement.
- Needle Punch:Mechanical entanglement of staple fibers produces density ranges suitable for geotextile anchoring and construction mat edging.
Most installed capacity flows through Spunbond. Expansion is steepest in Meltblown.
End Use Industry:
Margin structures diverge sharply between regulated medical applications and price-sensitive hygiene volumes, with automotive and construction occupying intermediate positions on the specification-to-commodity spectrum.
- Medical:Biocompatibility testing and lot traceability elevate compliance costs for seam-sealing applications in surgical drapes and isolation apparel. FDA 510(k) submission requirements favor incumbent suppliers with captive testing laboratories.
- Hygiene:Diaper and feminine product manufacturers procure flanging on annual contracts tied to resin index pricing. China's SAMR hygiene product standards shape export qualification protocols for domestic converters.
- Automotive:Interior trim applications demand fogging and flammability compliance under GB standards enforced by SAMR in China and KBA protocols in Germany.
- Construction:Geotextile reinforcement applications prioritize UV stability and tensile retention in civil engineering deployments.
Volume concentrates in Hygiene. Value expansion is most rapid in Medical.
Material:
Feedstock selection determines thermal bonding behavior, chemical resistance profiles, and end-of-life pathways under emerging extended producer responsibility frameworks.
- Polypropylene:Dominant feedstock for spunbond and meltblown variants, offering melt-flow compatibility with high-speed extrusion lines. Propylene monomer volatility tied to naphtha-cracking economics compresses margin predictability for converters lacking long-term offtake agreements.
- Polyester:Higher melting points and hydrolytic stability suit automotive interior applications with thermal cycling requirements. PET staple fiber availability anchors needle punch production for construction geotextiles.
- Rayon:Cellulosic base provides moisture management and softness in premium hygiene product edging.
- Biodegradable:PLA and PHA alternatives gain traction in European hygiene segments where compostability certification commands buyer preference.
Polypropylene commands the majority of installed extrusion capacity. Biodegradable alternatives are climbing the fastest as EU Green Deal recyclability mandates reshape material substitution pathways.
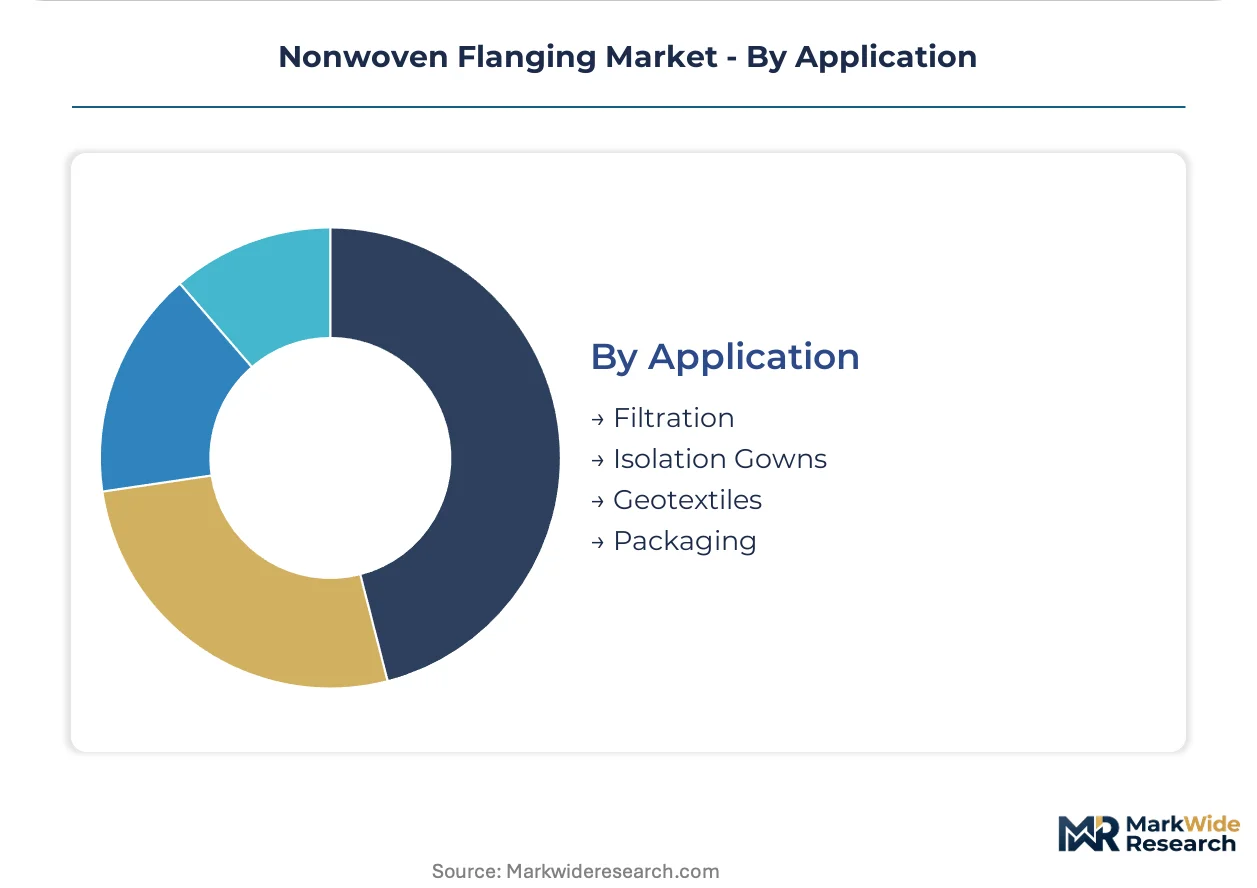
Application:
Performance requirements stratify from structural reinforcement in civil engineering to micron-level barrier integrity in medical filtration.
- Filtration:Composite flanging structures combine spunbond support layers with meltblown barrier media for HVAC and medical device applications. EPA emission controls on thermal bonding ovens accelerate qualification of ultrasonic-bonded alternatives.
- Isolation Gowns:Seam-sealing flanging for AAMI Level 2-4 protective apparel requires biocompatibility documentation and sterilization validation. US hospital procurement consolidation favors suppliers bundling technical support with regulatory filing assistance.
- Geotextiles:Civil engineering applications deploy high-tenacity needle punch flanging for erosion control mat anchoring and drainage system edging.
- Packaging:Edge reinforcement for flexible medical and consumer packaging emphasizes heat-seal compatibility and print surface adhesion.
Filtration absorbs the largest share of specification-grade capacity. Isolation gown applications are gaining share fastest as US healthcare systems expand protective apparel stockpiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer engineering talent clusters in Germany's Rhine-Ruhr corridor and China's Yangtze River Delta anchor nonwoven flanging innovation. These workforce concentrations shape regional specialization patterns.
United States
Hospital group purchasing organizations consolidate vendor lists around FDA-compliant flanging suppliers. EPA emission controls on thermal bonding ovens constrain plant siting in Texas and the Southeast. Charlotte, North Carolina hosts converting operations serving medical apparel manufacturers with isolation-grade seam-sealing products.
Germany
Automotive cabin air filter manufacturers demand ISO 5011-certified flanging under KBA type approval protocols. EU Green Deal recyclability mandates accelerate mono-material PP designs compatible with mechanical recycling. The Stuttgart-Karlsruhe corridor concentrates precision calendering operations for filtration applications.
China
SAMR enforcement of GB standards for automotive interior nonwovens redirects production toward certified suppliers. MEE dual carbon goals tighten energy intensity benchmarks for melt-extrusion lines. Zhejiang and Jiangsu provinces cluster meltblown substrate capacity exposed to regional power rationing risks.
India
Rural diaper and feminine hygiene adoption below 35 percent creates whitespace for cost-optimized needle punch flanging. BIS hygiene product standards shape export qualification protocols for domestic converters. Gujarat and Maharashtra host staple fiber processing hubs supplying economy-tier product manufacturers.
Japan
METI industrial standards for high-performance filtration materials drive specification-grade meltblown development. PMDA medical device requirements elevate documentation burdens for seam-sealing applications. The Chubu region around Nagoya anchors automotive supply chain integration for interior trim flanging.
Nonwoven Flanging Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across material grades and end-use certifications. The vendor base fragments across three tiers: multinational polymer science leaders with captive R&D, regional converters serving single industries, and emerging Asian fabricators competing on unit economics. Two strategic archetypes dominate—backward-integrated fiber producers controlling resin-to-web conversion, and technology licensors monetizing proprietary bonding equipment. Capacity expansion and dedicated long-term supply contracts constitute the primary competitive moves.
Among diversified materials conglomerates, Ahlstrom and DuPont exemplify the premium-tier archetype through proprietary spunbond-meltblown-spunbond composite positioning. Freudenberg Performance Materials occupies a distinct position as a German GmbH-structured specialist with upstream fiber production integration. Berry Global Inc. represents the North American scale-driven model competing across high-volume converting operations.
| Leading Market Players |
|---|
| Ahlstrom |
| Johns Manville |
| Berry Global Inc. |
| Suominen |
| DuPont |
| Freudenberg Performance Materials |
| Fitesa |
| Toray Industries, Inc. |
| Kimberly-Clark Worldwide, Inc. |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between FDA 510(k) medical flanging and commodity hygiene grades manifests in dual supply chain architectures: biocompatibility-validated production anchors in Germany and the United States with captive testing laboratories, while cost-optimized spunbond capacity clusters in Zhejiang and Gujarat feeding price-indexed annual contracts.
Pricing Analysis
Capacity additions in Zhejiang and Jiangsu provinces are reshaping price floors for standard-grade spunbond flanging, compressing margins for regional converters lacking polymer offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified medical grades from SAMR-compliant automotive specifications and unbranded hygiene volumes. Pricing pressure stems from propylene monomer volatility tied to naphtha-cracking economics. Hospital group purchasing organizations exhibit lowest price sensitivity due to bundled technical service requirements, while rural Indian hygiene distributors operate at highest sensitivity.
Supply Chain Analysis
ISO 13485 and FDA 510(k) qualification gating restricts medical-grade supply to incumbent producers with captive testing infrastructure, fragmenting vendor pools. Geographic concentration centers on China for meltblown substrates, Germany for precision calendering equipment, and India for staple fiber processing. Raw material dependencies draw from propylene monomer, PET staple fiber, and PLA biopolymer feedstocks. Single-source vulnerability runs through Zhejiang meltblown capacity exposed to MEE carbon quota enforcement. Distribution runs through Tier 1 hygiene and medical product manufacturers consolidating vendor lists around multi-year master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EPA emission controls and FDA compliance burdens elevate US production costs for thermal-bonded grades, while China's MEE dual carbon goals tighten energy intensity benchmarks, widening cost differentials for converters with electrified assets in Southeast Asia.
For Market Incumbents: Hedge against biodegradable substitute displacement by securing backward integration into polymer staple fiber production and qualifying mono-material PP designs for EU Green Deal mechanical recycling streams. Defend margin position through dedicated capacity contracts with hospital group purchasing organizations that bundle regulatory filing assistance with technical support, neutralizing spot-market competitors. For New Entrants and Emerging Players: Regional distributors in India's kirana networks offer the most penetrable channel partner type for cost-optimized needle punch flanging targeting rural diaper and feminine hygiene segments below 35 percent adoption. White-space targets include economy-tier hygiene products and automotive interior trim serving domestic OEMs under SAMR GB standards. A go-to-market angle anchored to BIS export qualification protocols enables access to international buyers sourcing from Gujarat processing hubs. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing captive meltblown extrusion lines and FDA submission experience, as hospital procurement consolidation favors incumbent technical service bundling over unit price competition. Long-term viability hinges on electrification capex positioning ahead of MEE carbon quota tightening and EPA thermal bonding oven constraints. The signal to watch is regional power rationing frequency in Zhejiang and Jiangsu provinces as an indicator of supply disruption risk and margin expansion opportunity for alternative capacity holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Staple Fiber | Freudenberg Performance Materials anchors margin control through captive fiber production upstream of web formation. |
| Electrified Melt-Extrusion Retrofit | Zhejiang-based suppliers avoid MEE production suspensions by retrofitting spinneret packs and closed-loop quench air systems. |
| FDA 510(k) Bundle with Technical Service | Incumbent producers displace spot-market sourcing by offering hospital GPOs regulatory filing assistance alongside seam-sealing supply. |
| Mono-Material PP Design Certification | EU Green Deal recyclability mandates reward mechanical recycling-compatible flanging with extended producer responsibility compliance. |
| Ultrasonic Bonding Equipment Qualification | German automotive cabin air filter manufacturers adopt sub-micron filtration flanging without EPA-regulated thermal bonding ovens. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with nonwoven plant managers, procurement leads at Tier 1 hygiene manufacturers, FDA regulatory affairs specialists, and automotive interior trim engineers with secondary validation against customs trade data, EPA emission filings, SAMR GB standard publications, and SEC 10-K disclosures from diversified materials conglomerates. Bottom-up capacity assessments across Zhejiang, Jiangsu, and Gujarat production zones were triangulated against top-down demand modeling from hospital group purchasing organization contract databases.
Historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-stockpiling normalization trajectories across the projection horizon. Segmentation dimensions modeled include bonding technology, end-use certification tier, material composition, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating propylene monomer price volatility indices and electrification capex cycle timing. Industry-specific inputs encompassed MEE dual carbon goal enforcement schedules and FDA 510(k) review cycle compression effects on procurement calendars.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biodegradable polymer substitution rates in European hygiene segments and regional power rationing severity in China's Yangtze River Delta. Forecasts reflect documented assumptions regarding SAMR enforcement consistency and EPA thermal bonding oven regulatory stability. A model refresh is warranted upon material change in EU Green Deal extended producer responsibility implementation timelines or PLA biopolymer cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Airlaid Textile Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
Barrier Nonwoven Fiber for Breathable Surgical Gowns Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Dust Cover Market