
 Hygienic Non-Woven Fabrics Market | 2026-2036
Hygienic Non-Woven Fabrics Market Size, Share, and Industry Trends Forecast 2026-2036
Hygienic Non-Woven Fabrics Market Intelligence
Medical-grade bacterial filtration efficiency is unwinding legacy commodity supply chains as buyers demand certified barrier performance. Berry Global Inc. leverages its spunbond-meltblown-spunbond composite capacity to anchor North American hospital supply contracts. Kimberly-Clark sustains R&D intensity in hydroentangled wipe substrates for sensitive-skin personal care segments. Ahlstrom differentiates through European-centric sustainability certifications that dominate premium surgical gown procurement.
Hygienic non-woven fabrics are engineered sheet structures composed of synthetic or natural fibers bonded through mechanical, thermal, or chemical means, typically achieving basis weights of 10–150 gsm and bacterial filtration efficiencies exceeding 95 percent for medical grades. These materials function primarily as disposable barriers against pathogens, fluids, and particulates across healthcare, personal care, and food safety environments. Spunbond technology leads in volume throughput for diaper and bed liner backsheet applications, while meltblown occupies the critical margin pool in face mask and surgical gown filtration layers where barrier precision commands price premiums. Hydroentangled fabrics are gaining share in premium wipe applications as softness and lint-free performance become non-negotiable specifications for cosmetic and infant care brands.
The FDA governs surgical gown and face mask performance through 21 CFR medical device classifications that mandate fluid resistance and bacterial filtration validation for market access. EMA-aligned CE marking under the EU Medical Device Regulation enforces biocompatibility and sterilization compatibility standards that shape European product development cycles. China's NMPA implements GB standards for disposable medical textiles that determine import eligibility for foreign manufacturers. Stakeholders must monitor how divergent filtration efficiency test methods across these regulators create compliance fragmentation that favors regionally certified producers over global generalists.
Market Dynamics
Medical-grade bacterial filtration efficiency mandates are unwinding legacy commodity supply chains as hospital procurement teams demand certified barrier performance rather than generic non-woven substrates.
Growth Catalysts
- Adult Incontinence Demand:Aging demographics in Germany and Japan are expanding orders for superabsorbent core wraps and acquisition distribution layers that require hydroentangled softness.
- FDA Device Reclassification:Tighter 21 CFR standards for surgical gowns and face masks are forcing manufacturers to upgrade meltblown capacity, creating pull-through for high-efficiency filtration media.
- Spunbond-Meltblown-Spunbond Composites:This multi-layer architecture now dominates premium diaper backsheet and surgical barrier applications where fluid resistance and breathability must coexist.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer price swings directly compress margins for spunbond producers serving commodity hygiene segments.
- Chinese Meltblown Concentration:Over half of global fine-fiber capacity sits in Zhejiang and Jiangsu provinces, exposing buyers to single-country supply disruption risks.
- Biodegradability Trade-offs:PLA and other bio-based polymers still fail to match polypropylene's thermal bonding efficiency and cost structure at commercial scale.
Strategic Opportunities
- Indian Hygiene Penetration:Low per-capita consumption of disposable diapers and sanitary pads in rural Maharashtra and Uttar Pradesh offers volume expansion potential as urbanization accelerates.
- EU Green Deal Procurement:Public hospital tenders in France and Italy now award points for recycled-content and carbon-footprint disclosures, favoring certified sustainable suppliers.
- Hydroentangled Wipe Premiumization:Cosmetic brands in South Korea are specifying lint-free, ultra-soft substrates for facial cleansing applications that command 40-60% price premiums over airlaid alternatives.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Securing simultaneous FDA 510(k), CE-MDR, and NMPA approvals for surgical textiles extends product launch cycles by 18-24 months.
- Skilled Meltblown Technician Scarcity:Fine-die maintenance and air-quantity calibration for sub-micron fiber production require specialized expertise that outpaces vocational training output in North America and Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hygienic Non-Woven Fabrics Market |
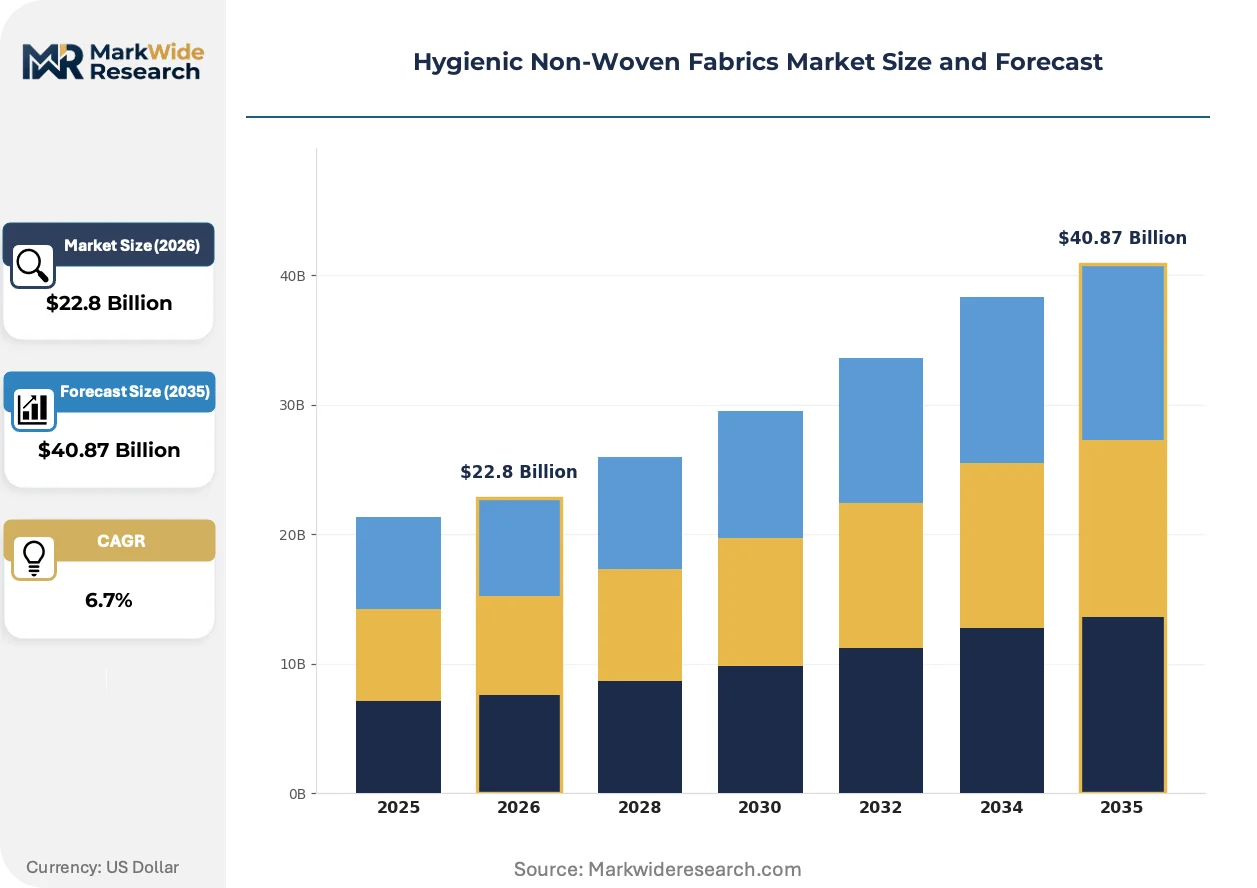
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $40.87 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria Filtration, Fluid Resistance, Surgical Gowns, Face Masks End Use Industry: Healthcare, Personal Care, Cleaning, Food Safety Technology: Spunbond, Meltblown, Needle Punch, Hydroentangled Application: Wipes, Bed Liners, Diapers, Protective Apparel |
| Companies Covered | Berry Global Inc., Ahlstrom, Kimberly-Clark, Avgol Industries, DuPont de Nemours Inc., Fitesa, Freudenberg Group, Kingsafe Group, Suominen Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hygienic Non-Woven Fabrics Market Strategic Shifts & Innovations
Barrier performance certification is displacing commodity specifications across healthcare procurement, while sustainability metrics and softness engineering reshape consumer-facing segments.
Bicomponent spunbond technology is decomposing the traditional trade-off between strength and softness in diaper topsheet applications. Premium infant care brands in Germany and the Netherlands now specify sheath-core polyethylene-polypropylene fibers that deliver cotton-like hand feel without sacrificing tensile integrity. This fiber architecture is compressing demand for carded thermal-bond alternatives in the premium tier.
The EU Medical Device Regulation's expanded biocompatibility testing requirements for surgical textiles are extending product development timelines and favoring incumbent producers with established notified body relationships. Manufacturers serving European hospital systems must now validate cytotoxicity and sensitization endpoints beyond prior CE-marking standards. German procurement offices are leveraging these requirements to pre-qualify only domestic and near-shore suppliers with proven sterilization compatibility.
Direct contracting between non-woven converters and retail pharmacy chains is disintermediating traditional distribution layers for face mask and wipe categories. CVS and Walgreens in the United States now source private-label hygiene products through dedicated supply agreements that specify lot-level traceability and quarterly sustainability reporting. This channel consolidation concentrates volume with converters capable of integrated packaging and regulatory documentation.
Hygienic Non-Woven Fabrics Market Segmentation
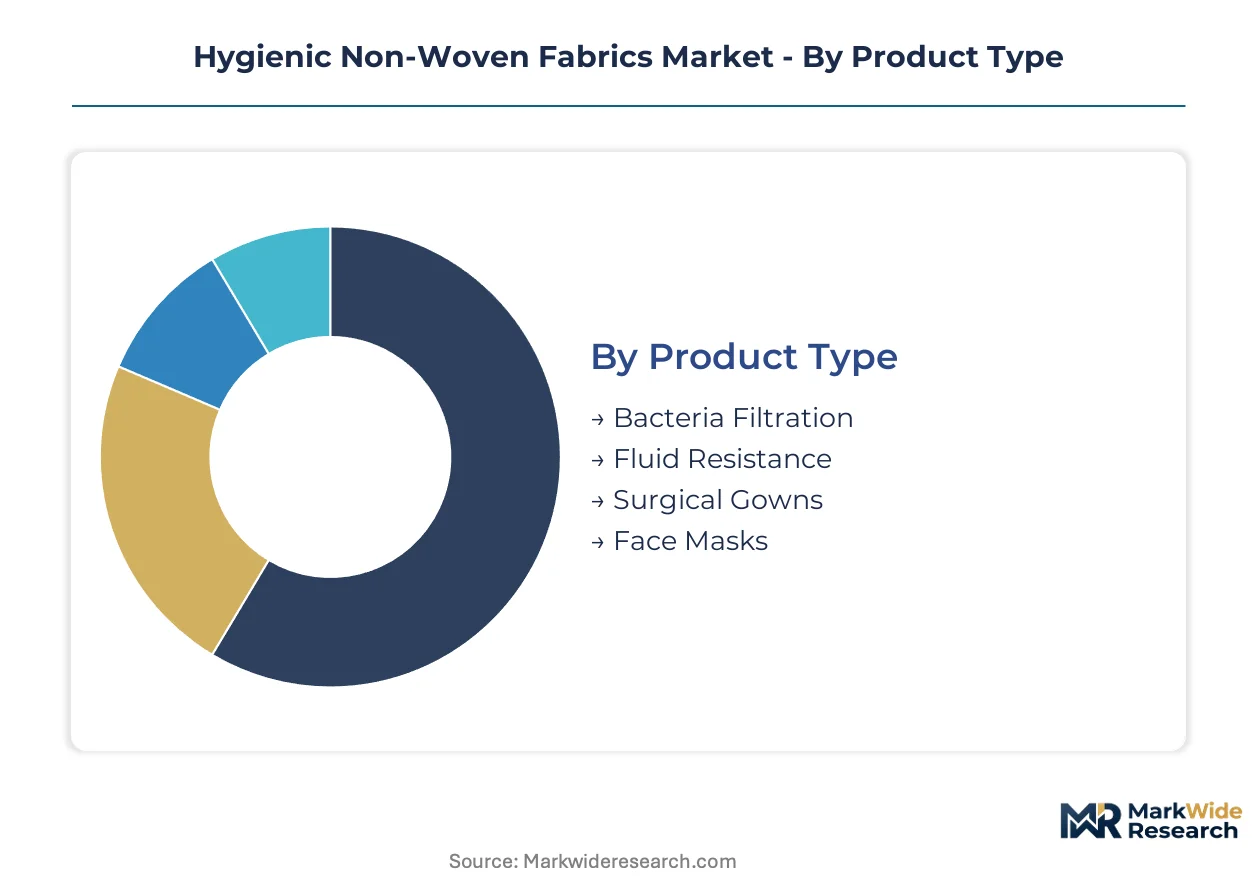
Hygienic non-woven fabrics serve divergent performance requirements across medical barriers and consumer disposables. Segmentation reveals how technology choices and end-use specifications create distinct margin pools and geographic demand concentrations.
Product Type:
Domestic hospital procurement in Germany and Japan drives premium specifications, while export markets absorb standardized commodity grades from Chinese and Indian converters.
- Bacteria Filtration:Meltblown microfiber layers achieve sub-micron particle capture exceeding medical device thresholds. German hospital tenders now mandate validated bacterial filtration efficiency documentation from domestic notified body partnerships.
- Fluid Resistance:Spunbond-meltblown-spunbond laminates block synthetic blood penetration under ASTM F1670 testing protocols. US surgical gown contracts specify hydrostatic head pressure minimums that disqualify single-layer alternatives.
- Surgical Gowns:AAMI Level 3 and Level 4 classifications govern critical zone reinforcement requirements.
- Face Masks:ASTM F2100 and EN 14683 type ratings determine filtration and breathability trade-offs.
Bacteria Filtration holds the largest share; momentum sits with Fluid Resistance as FDA device reclassification tightens.
End Use Industry:
Cost tiers separate premium certified medical grades from economy hygiene disposables, with regulatory burden driving margin stratification.
- Healthcare:Surgical textiles and sterilization wraps demand validated biocompatibility under EU MDR and FDA 21 CFR frameworks. German procurement offices pre-qualify suppliers with established notified body relationships, compressing vendor pools.
- Personal Care:Diaper and feminine hygiene components prioritize hydroentangled softness and thermal bonding efficiency. Japanese aging demographics expand adult incontinence orders for superabsorbent core wraps.
- Cleaning:Industrial wipes and surface disinfection substrates balance solvent resistance with disposability economics.
- Food Safety:Hairnets, sleeve covers, and processing aprons require metal-detectable fiber options for contamination control.
Healthcare commands the highest price realization; Personal Care delivers volume scale with expanding fastest.
Technology:
Production volume concentrates in spunbond commodity lines, while meltblown capacity scarcity creates supply bottlenecks for medical filtration.
- Spunbond:Continuous filament extrusion achieves 10-150 gsm basis weights for diaper backsheet and geotextile applications. Indian converters leverage polypropylene cost advantages to supply African and Southeast Asian hygiene markets.
- Meltblown:Fine-die extrusion produces 1-10 micron fibers for face mask and surgical gown filtration layers. Zhejiang and Jiangsu provinces host over half of global fine-fiber capacity, concentrating supply disruption exposure.
- Needle Punch:Mechanical entanglement suits durable industrial wipes and filtration pre-layers where surface integrity matters.
- Hydroentangled:High-pressure water jet bonding delivers lint-free, cotton-like hand feel for cosmetic and infant wipe premium tiers.
Spunbond dominates throughput tonnage; hydroentangled substrates climb fastest on softness premiumization.
Application:
Customer type stratification separates institutional hospital contracts from retail consumer purchasing patterns.
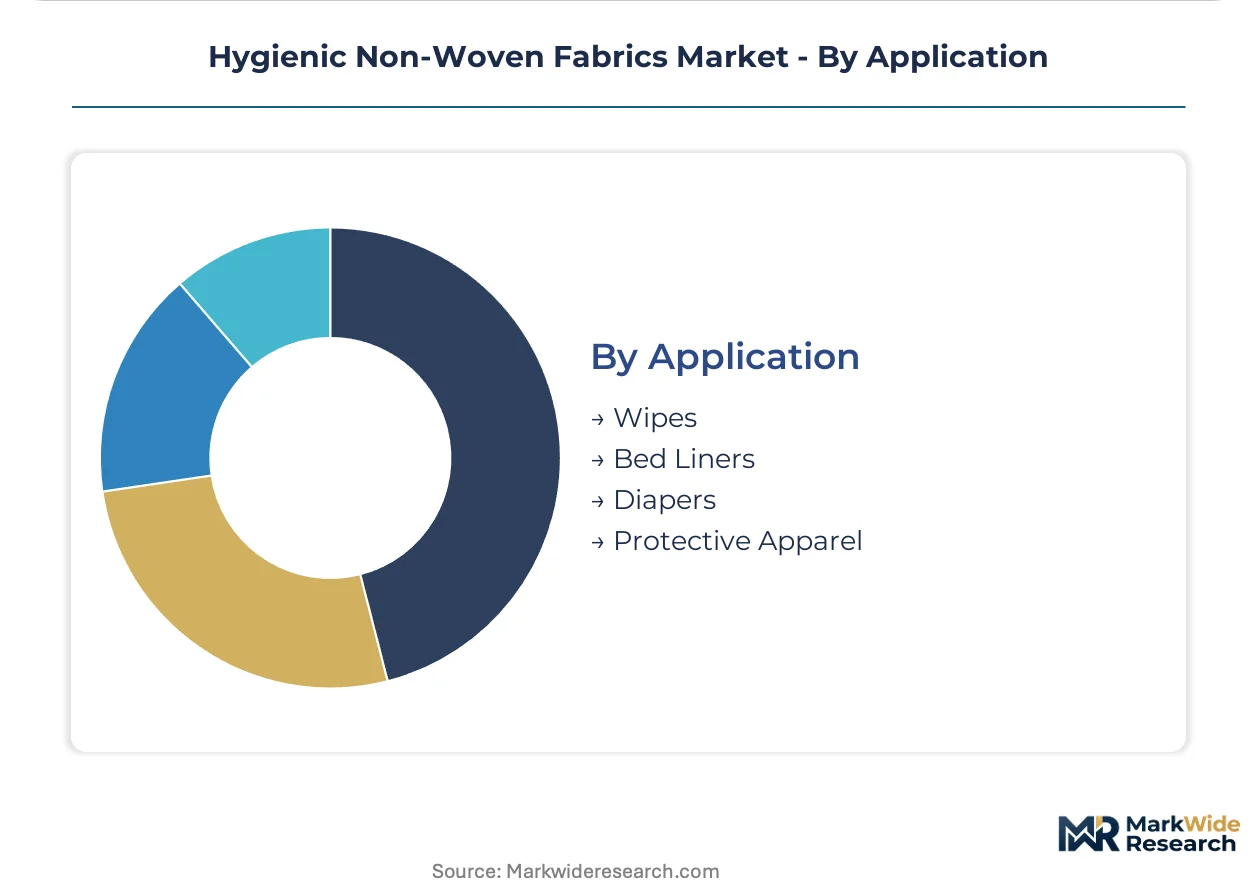
- Wipes:Cosmetic brands in South Korea specify ultra-soft hydroentangled substrates for facial cleansing applications. CVS and Walgreens private-label agreements now mandate lot-level traceability and quarterly sustainability reporting.
- Bed Liners:Spunbond backsheet films combine fluid resistance with breathability for healthcare and hospitality segments. German nursing home chains source acquisition distribution layers requiring hydroentangled acquisition speed.
- Diapers:Bicomponent sheath-core fibers decompose the strength-softness trade-off in premium infant care topsheets.
- Protective Apparel:Coveralls and isolation gowns balance particulate barrier performance with wearer comfort duration.
Wipes capture the steepest expansion trajectory; bed liners anchor steady replacement demand from institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German hospital procurement teams prioritize certified bacterial filtration efficiency regardless of cost, while Indian rural distributors compete primarily on per-unit pricing for basic hygiene disposables.
Germany
Adult incontinence product orders are expanding as the population ages, particularly for superabsorbent core wraps requiring hydroentangled softness. Hospital procurement offices now mandate validated bacterial filtration efficiency documentation under EU MDR frameworks. The North Rhine-Westphalia industrial corridor hosts concentrated meltblown capacity serving domestic surgical textile demand.
China
Domestic diaper consumption is rising with urban middle-class expansion, though export markets still absorb standardized commodity grades. NMPA implements GB standards for disposable medical textiles that determine import eligibility for foreign manufacturers. Zhejiang and Jiangsu provinces contain over half of global fine-fiber meltblown capacity, creating single-country supply concentration risks.
United States
CVS and Walgreens now source private-label hygiene products through direct contracting agreements specifying lot-level traceability. FDA 21 CFR medical device classifications mandate fluid resistance and bacterial filtration validation for surgical gown and face mask market access. Southeastern converters near Atlanta and Charlotte are expanding spunbond-meltblown-spunbond composite lines for hospital supply contracts.
India
Low per-capita consumption of disposable diapers and sanitary pads in rural Maharashtra and Uttar Pradesh offers volume expansion potential as urbanization accelerates. BIS certification requirements shape product specifications for domestic market entry. Gujarat-based polypropylene converters leverage feedstock cost advantages to supply African and Southeast Asian hygiene markets.
Japan
Aging demographics are driving adult incontinence orders for acquisition distribution layers requiring premium softness specifications. METI industrial standards influence product development cycles for medical-grade applications. The Kansai region around Osaka maintains specialized hydroentangled capacity serving cosmetic and infant care brands.
Hygienic Non-Woven Fabrics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Spunbond commodity throughput concentrates among scale-driven producers with polypropylene feedstock advantages, while meltblown filtration specialists command premium positioning through barrier precision. Three archetypes dominate: integrated resin-to-fabric converters, dedicated medical-grade filtration specialists, and regional hygiene substrate suppliers. Competitive moves center on backward integration into polymer supply and geographic expansion into underpenetrated hygiene markets.
Among North American integrated producers, Berry Global Inc. and Kimberly-Clark exemplify the scale-plus-certification archetype, leveraging established regulatory relationships to anchor hospital supply contracts. Ahlstrom occupies a position within the European sustainability-focused tier, where EU Green Deal procurement criteria favor certified suppliers with carbon-footprint disclosure capabilities. These three represent distinct strategic positioning vectors—continental scale, regulatory integration, and sustainability certification—rather than direct product competition.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Ahlstrom |
| Kimberly-Clark |
| Avgol Industries |
| DuPont de Nemours Inc. |
| Fitesa |
| Freudenberg Group |
| Kingsafe Group |
| Suominen Corporation |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day meltblown filtration media lead times concentrate pricing power with Zhejiang and Jiangsu province converters, while hospital procurement teams in Germany and the United States absorb premium markups for validated bacterial filtration efficiency documentation. Polypropylene feedstock volatility transmits directly into spunbond commodity tier margins, compressing returns for Indian and Chinese producers serving African and Southeast Asian hygiene markets.
Pricing Analysis
After-sales certification maintenance and revalidation service contracts capture lifetime value in medical-grade tiers, where FDA 510(k) and CE-MDR documentation renewal generates recurring revenue streams. Three-tier pricing structure across premium certified medical, standard industrial hygiene, and economy commodity disposables separates AAMI Level 4 surgical gown suppliers from basic diaper backsheet producers. Cost compression in spunbond commodity tiers intensifies because Indian converters leverage polypropylene feedstock advantages to undercut Southeast Asian competitors. Rural Indian distributors exhibit highest price sensitivity per unit, while German hospital procurement offices prioritize bacterial filtration efficiency validation regardless of per-meter cost.
Supply Chain Analysis
Strategic stockpiling of polypropylene resin and meltblown filtration media dominates procurement behavior among US and European hospital supply contractors, contrasting with just-in-time inventory practices in Indian and Southeast Asian hygiene converters. Manufacturing concentration in China, India, and Germany shapes global availability, with Zhejiang province hosting critical fine-fiber capacity for face mask and surgical gown applications. Raw material dependencies center on propylene monomer, specialized meltblown die components, and hydroentangled water-jet systems. Single-country supply vulnerability in Chinese meltblown concentration exposes buyers to disruption risks from regional energy rationing or export licensing shifts. Distribution runs through direct contracting between converters and retail pharmacy chains in North America, layered distributor networks in India, and domestic mill relationships in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized meltblown technician expertise and validated notified body relationships constitute scarce capabilities that constrain expansion timelines for new filtration capacity. Qualified fine-die maintenance engineers and air-quantity calibration specialists outpace vocational training output across North America and Europe, compressing the vendor pool for premium medical-grade supply contracts.
For Market Incumbents: Fortify barrier performance certification moats by deepening backward integration into polypropylene resin supply and expanding hydroentangled capacity in the Kansai region around Osaka. Emerging Chinese converters with state-supported capacity additions threaten commodity tier margins, making FDA and CE-MDR documentation renewal services the priority defensive lever for hospital supply contracts. For New Entrants and Emerging Players: Lead with sustainability-certified hydroentangled substrates for South Korean cosmetic brands and EU Green Deal-compliant surgical textiles for French and Italian public hospital tenders. Rural Maharashtra and Uttar Pradesh present the most penetrable volume opportunity as urbanization accelerates disposable diaper and sanitary pad adoption. Direct-to-retail-pharmacy private-label agreements bypass traditional distribution layers and concentrate volume with converters capable of integrated packaging and regulatory documentation. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized meltblown or spunbond capacity lacking medical-grade certification infrastructure. Long-term viability hinges on securing validated notified body relationships and specialized technician training pipelines rather than commodity scale alone. The signal to watch is FDA device reclassification enforcement intensity, which determines upgrade investment requirements and consolidation pressure on uncertified producers.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Certification Investment | EU Medical Device Regulation compliance opens German and French hospital procurement channels previously closed to uncertified suppliers. |
| Backward Integration into Polypropylene | Captive resin supply insulates spunbond producers from propylene monomer price volatility compressing Indian commodity tier margins. |
| Hydroentangled Capacity Expansion | Ultra-soft lint-free substrates capture 40-60% price premiums from South Korean cosmetic brands and Japanese adult incontinence orders. |
| Direct Pharmacy Chain Contracting | CVS and Walgreens private-label agreements mandate lot-level traceability that filters out distributors lacking integrated packaging capabilities. |
| Meltblown Fine-Fiber Technology Licensing | Sub-micron fiber production expertise transfers to Southeast Asian converters seeking medical-grade filtration tier entry. |
Research Approach
A spread of perspectives from meltblown production engineers, hospital procurement managers at German and US health systems, regulatory affairs specialists navigating FDA 510(k) pathways, and polypropylene procurement leads at Indian converters converged on the working assumptions. Secondary validation drew from FDA 510(k) filings, EMA notified body documentation, NMPA GB standard registrations, customs trade data on polypropylene resin flows, and SEC filings from integrated resin-to-fabric producers. Bottom-up capacity assessments and top-down demand modeling triangulated volume and value estimates.
Segmentation dimensions modeled include product type across bacteria filtration, fluid resistance, surgical gowns, and face masks; technology across spunbond, meltblown, needle punch, and hydroentangled processes; end-use industry across healthcare, personal care, cleaning, and food safety; and application across wipes, bed liners, diapers, and protective apparel. CAGRs were derived from regression analysis against demographic drivers, regulatory enforcement intensity indices, and feedstock cost trajectories across the analysis window. Forecast inputs incorporated aging population projections for adult incontinence demand and EU Green Deal procurement weighting schemes for sustainability-certified suppliers.
Underlying assumptions cover polypropylene price stability, continued FDA device classification enforcement, and Chinese export licensing continuity, with deviation risk concentrated in propylene monomer supply disruptions and multi-jurisdiction certification timeline extensions. Revision becomes warranted when FDA 510(k) backlog clearance rates or EU MDR notified body capacity constraints cross thresholds that materially alter product launch cycle assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Nonwoven Fabric Production Line Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Nonwoven Furniture Construction Sheeting Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market