
 Nonwoven Sponges Market | 2026-2036
Nonwoven Sponges Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Sponges Market Intelligence
The capital-intensity divergence between automated meltblown lines and conventional carded web operations is unwinding competitive dynamics across the nonwoven sponges landscape. Cardinal Health leverages its distribution scale to sustain hospital system contracts across North America. Medline Industries anchors its position through in-house sterilization infrastructure that reduces third-party dependency. Mölnlycke Health Care differentiates via specialized surgical sponges with integrated X-ray detectable elements.
Nonwoven sponges are engineered fibrous webs manufactured through thermal, chemical, or mechanical bonding of synthetic or natural fibers, typically achieving basis weights between 30–100 gsm for medical grades; these structures provide controlled absorbency, low linting, and biocompatibility for wound management and surgical site preparation. The disposable sponges segment dominates hospital procurement due to infection control protocols that mandate single-patient use, while antimicrobial sponges represent the fastest-expanding category as chlorhexidine-impregnated variants gain formulary acceptance. Polyester and rayon blends command premium positioning in surgical applications where fiber purity and absorbency consistency determine clinical outcomes.
The FDA enforces Quality System Regulation requirements for medical-grade nonwoven sponges, while the EPA oversees antimicrobial additive claims under FIFRA; together these frameworks elevate compliance costs but also create barriers against unvalidated imports. ISO 10993 biocompatibility testing further shapes product development timelines and material selection decisions. Stakeholders must monitor evolving sterilization validation requirements and ambulatory care site expansion patterns to align capacity with shifting point-of-care demand.
Market Dynamics
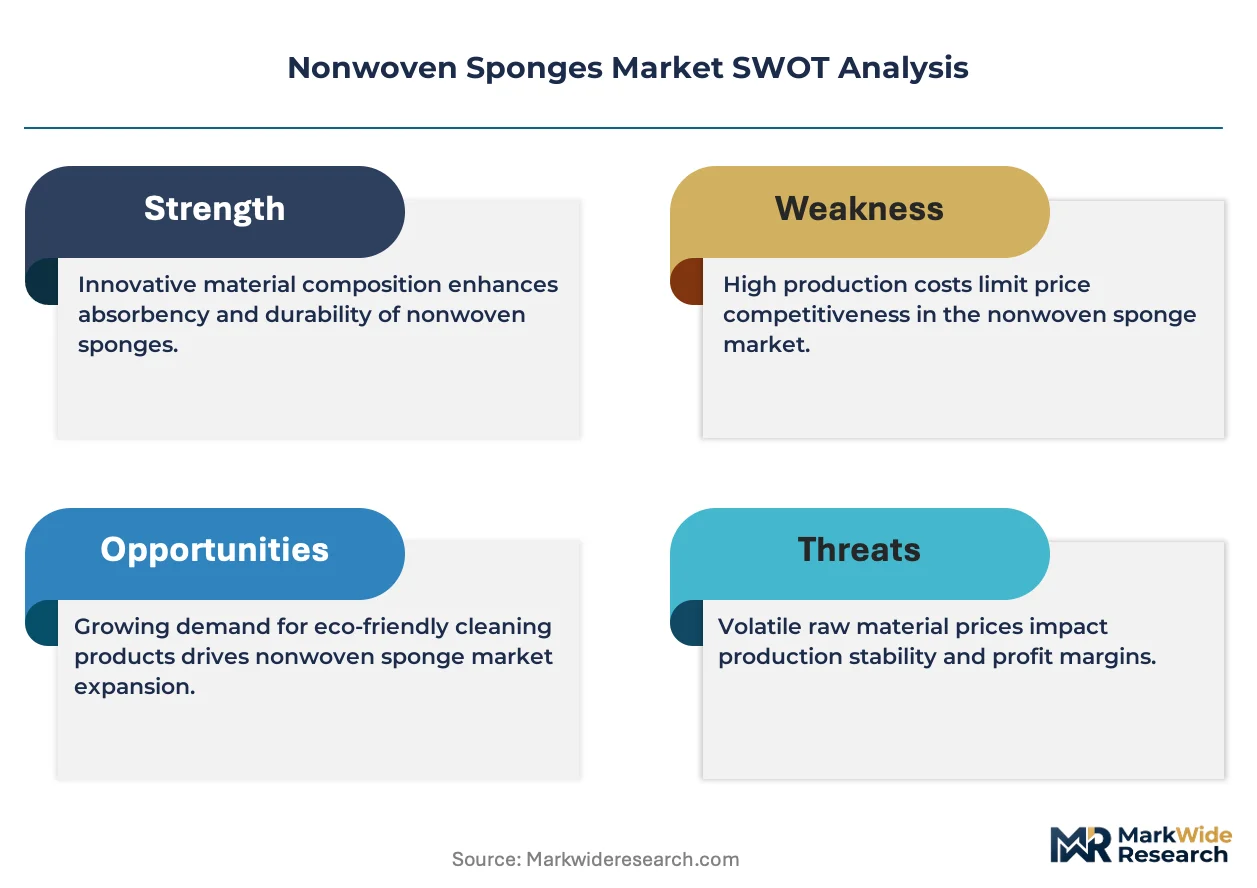
Hospital procurement consolidation and ambulatory surgical center expansion are compressing distribution margins while demanding validated sterilization documentation. Automated meltblown capacity investments by major distributors are decommoditizing conventional carded web supply.
Growth Catalysts
- Ambulatory surgical center throughput:United States outpatient procedural volume expansion drives single-use consumable consumption. These facilities prioritize disposables over reusable instruments for infection control.
- FDA Quality System Regulation enforcement:Updated medical device quality standards pressure manufacturers toward validated sterilization processes. This elevates compliance barriers against unvalidated imports.
- Chlorhexidine-impregnated formulations:Antimicrobial sponge variants gain hospital formulary acceptance as surgical site infection prevention protocols tighten. Fiber impregnation technology advances enable sustained antimicrobial release.
Market Restraints
- Polypropylene resin price volatility:Feedstock cost fluctuations squeeze meltblown nonwoven margins. Petrochemical input exposure concentrates risk among synthetic fiber producers.
- Gamma sterilization capacity concentration:Third-party sterilization services cluster in limited geographic zones, creating bottlenecks. Manufacturers face extended lead times for terminal sterilization validation.
- Reusable surgical textile substitution:Advanced laundering systems and barrier fabric technologies compete in select procedural categories. Cost-conscious facilities evaluate lifecycle economics against single-use disposables.
Strategic Opportunities
- India surgical infrastructure expansion:Government hospital modernization programs and private chain investments expand addressable procedural volume. Local manufacturing incentives reduce import dependency.
- Home wound care channel development:Direct-to-patient distribution bypasses traditional hospital procurement. E-commerce platforms enable chronic wound management product access.
- EU Medical Device Regulation (MDR) transition:Stricter biocompatibility documentation requirements favor established suppliers with ISO 10993 testing capabilities. Compliance-heavy market entry filters low-cost competitors.
Industry Challenges
- Sterilization validation engineering talent scarcity:Specialized expertise in gamma, ethylene oxide, and electron beam process validation commands premium compensation. Workforce gaps extend product launch timelines.
- Legacy ERP integration with track-and-trace systems:Unique device identification (UDI) compliance demands data architecture overhauls. Mid-tier manufacturers face disproportionate IT capital burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Sponges Market |
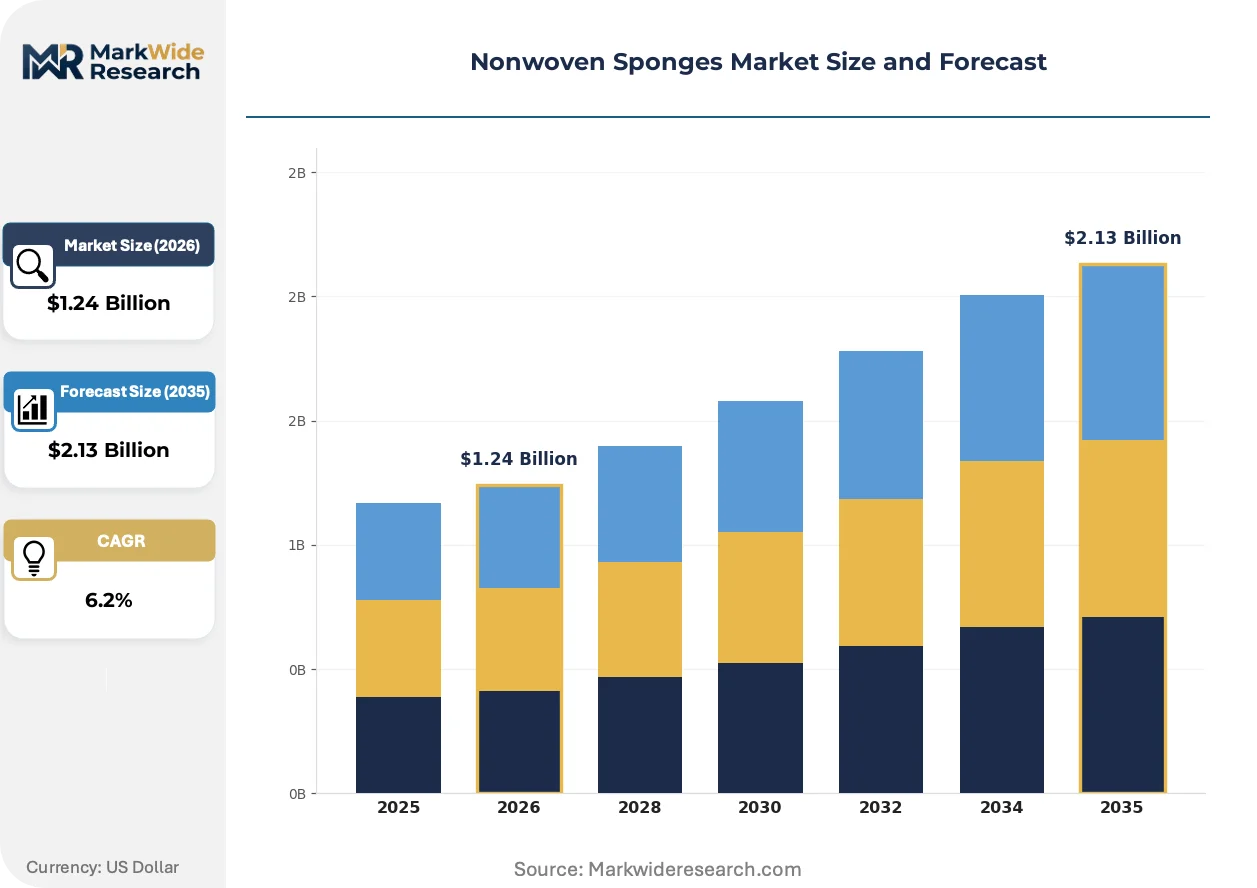
| Market Size in 2026 | $1.24 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Sponges, Reusable Sponges, Antimicrobial Sponges, Surgical Sponges Material: Polyester, Polypropylene, Rayon, Blends End User: Hospitals, Clinics, Home Care, Laboratories Application: Wound Care, Personal Care, Cleaning, Industrial Use |
| Companies Covered | Cardinal Health, Medline Industries, McKesson Corporation, Dukal Corporation, Dynarex Corporation, B. Braun Melsungen AG, 3M Company, Mölnlycke Health Care, Ahlstrom-Munksjö Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Sponges Market Strategic Shifts & Innovations
Sterilization modality diversification and fiber engineering advances are reconfiguring product development priorities. Procurement digitization is compressing traditional distributor roles while elevating technical specification transparency.
Meltblown microfiber webs with sub-micron fiber diameters are decomposing conventional spunbond-laminate structures in barrier applications. Surgical kit assemblers specify these materials for fluid strike-through resistance. The technology is decomposing established supply relationships as converters develop direct polymer sourcing capabilities.
EPA antimicrobial additive claims oversight under FIFRA is tightening substantiation requirements for chlorhexidine and silver-ion formulations. Manufacturers must demonstrate efficacy against specified organism panels. Surgical sponge producers with existing EPA registrations gain timeline advantages over new market entrants.
Hospital value analysis committees now mandate total cost-of-ownership documentation beyond unit price. Integrated delivery networks consolidate purchasing across member facilities. United States health system consolidation concentrates buying power among fewer decision-makers, compressing supplier margins while demanding enhanced clinical evidence packages.
Nonwoven Sponges Market Segmentation
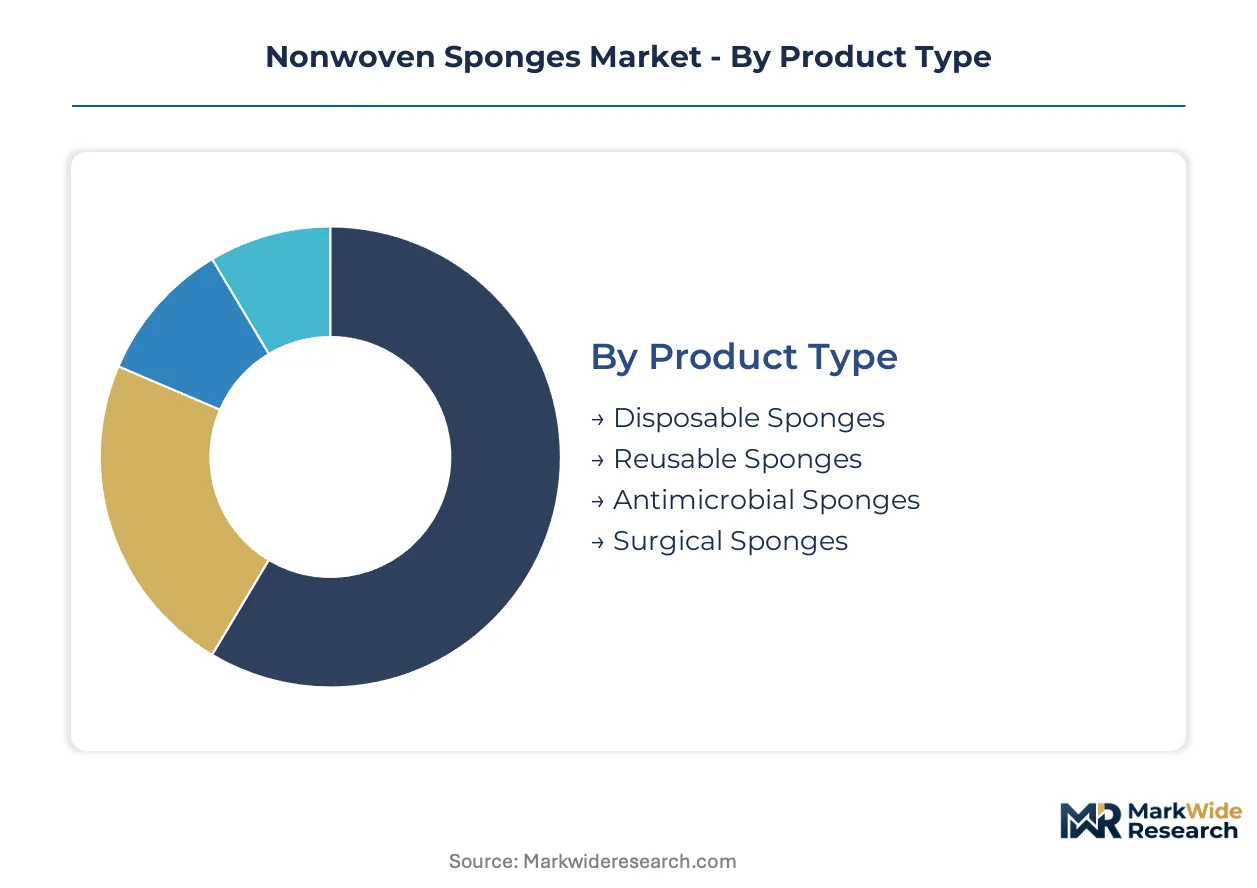
Segmentation in nonwoven sponges reveals where substitution pressures and regulatory requirements diverge most sharply. Hospital procurement teams evaluate segments through infection control protocols, sterilization validation costs, and total cost-of-ownership frameworks that favor disposables in high-throughput settings.
Product Type:
Reusable sponge formats face the strongest substitution threat from single-use alternatives as surgical site infection protocols tighten across acute care facilities.
- Disposable Sponges:Single-use fibrous webs bonded through thermal or mechanical processes achieve 30–100 gsm basis weights for clinical grades. United States ambulatory surgical centers prioritize these for throughput efficiency and terminal sterilization elimination. FDA Quality System Regulation compliance elevates barriers against unvalidated imports.
- Antimicrobial Sponges:Chlorhexidine-impregnated variants deliver sustained antimicrobial release through engineered fiber matrices. EPA FIFRA oversight tightens efficacy substantiation requirements against specified organism panels. Surgical site infection prevention protocols accelerate formulary acceptance in integrated delivery networks.
- Surgical Sponges:Specialized configurations with X-ray detectable elements address retained foreign object prevention in operating theaters.
- Reusable Sponges:Advanced laundering systems and barrier fabric technologies compete in select procedural categories where lifecycle economics favor multi-use formats.
Disposable sponges anchor the volume base while antimicrobial sponges gain share at the steepest rate.
Material:
Cost tier differentiation separates premium fiber grades from commodity synthetics in surgical versus general care applications.
- Polyester:Synthetic polymer fibers deliver consistent absorbency and low linting characteristics for wound management. Hospital value analysis committees specify these for fluid handling reliability in critical care settings.
- Blends:Polyester-rayon combinations command premium positioning where fiber purity and absorbency consistency determine clinical outcomes. United States health system consolidation concentrates purchasing power among fewer decision-makers demanding enhanced technical documentation.
- Rayon:Regenerated cellulose fibers provide high absorbency for general wound care and personal hygiene applications.
- Polypropylene:Thermoplastic polymer webs serve industrial cleaning and lower-acuity medical applications where cost sensitivity dominates.
Blended materials capture margin concentration in surgical grades while polypropylene serves high-volume, price-sensitive segments.
End User:
Customer type segmentation tracks procurement centralization and sterilization infrastructure ownership across care delivery settings.
- Hospitals:Acute care facilities with in-house sterilization infrastructure or third-party service contracts drive validated process documentation requirements. Gamma sterilization capacity concentration in limited geographic zones creates supply bottlenecks for high-volume consumers.
- Home Care:Direct-to-patient distribution channels bypass traditional hospital procurement through e-commerce platforms enabling chronic wound management access. This segment climbs fastest as aging populations and reimbursement shifts favor outpatient care models.
- Clinics:Outpatient facilities with lower sterilization capital investment rely on pre-sterilized single-use formats.
- Laboratories:Research and diagnostic settings demand low-linting specifications for contamination-sensitive procedures.
Hospitals anchor the volume base while home care gains share at the steepest rate.
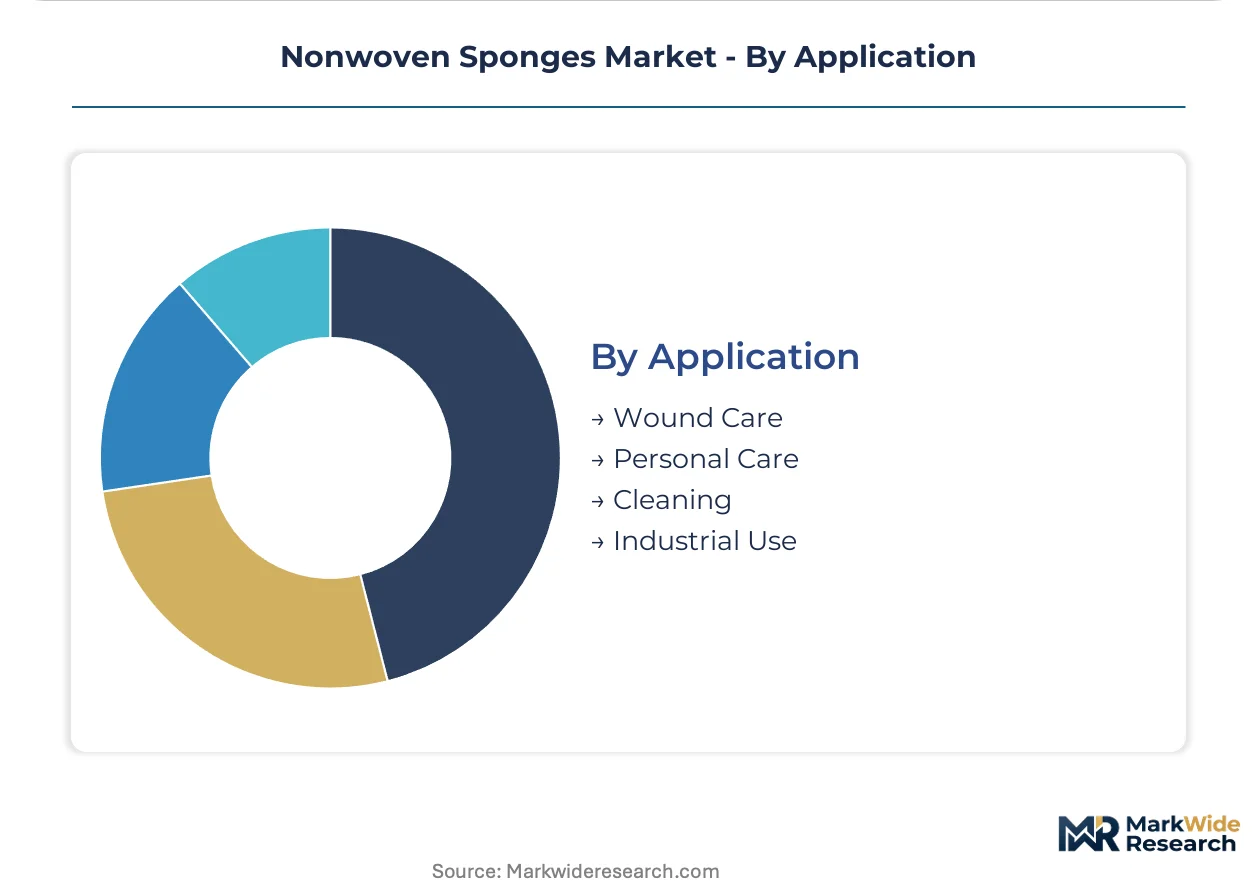
Application:
Application segmentation maps regulatory intensity and reimbursement pathways across clinical and non-clinical use cases.
- Wound Care:Medical-grade applications require ISO 10993 biocompatibility testing and FDA quality system compliance. United States wound care centers specify validated sterilization documentation for chronic and acute dressing protocols.
- Personal Care:Consumer hygiene applications face lower regulatory barriers but compete on absorbency and skin compatibility claims.
- Cleaning:Industrial and institutional surface preparation demands durability and solvent resistance over biocompatibility.
- Industrial Use:Manufacturing and maintenance applications prioritize cost efficiency and bulk availability.
Wound care anchors the volume base while personal care expands most quickly through retail channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: United States facilities prioritize validated sterilization documentation and single-use throughput, while emerging markets emphasize cost-efficient local manufacturing and import substitution programs.
United States
Ambulatory surgical center expansion and health system consolidation drive concentrated purchasing power among integrated delivery networks. The FDA enforces updated Quality System Regulation requirements that elevate compliance barriers against unvalidated imports. North Carolina and Ohio host major sterilization infrastructure clusters where gamma and ethylene oxide capacity constraints create supply bottlenecks for high-volume consumers.
Germany
EU Medical Device Regulation transition accelerates demand for ISO 10993 biocompatibility documentation among surgical sponge purchasers. The country's national pharmaceutical regulator enforces stricter post-market surveillance protocols that favor established suppliers with testing capabilities. Baden-Württemberg and Bavaria concentrate precision nonwoven manufacturing where converters develop direct polymer sourcing relationships.
China
Government hospital modernization programs and domestic manufacturing incentives expand procedural volume while reducing import dependency. The National Medical Products Administration tightens quality system oversight for medical-grade nonwoven devices. Yangtze River Delta industrial zones host meltblown capacity investments that decommoditize conventional carded web supply.
India
Private hospital chain investments and government health infrastructure programs expand addressable surgical volume. The Central Drugs Standard Control Organization implements phased medical device quality regulations that elevate entry barriers. Maharashtra and Gujarat concentrate contract manufacturing operations where local production incentives attract multinational sourcing decisions.
Japan
Aging demographics and chronic wound management reimbursement shifts favor home care channel development. The Pharmaceuticals and Medical Devices Agency maintains stringent biocompatibility validation requirements for medical-grade fibrous webs. Kanto and Kansai regions anchor domestic nonwoven production where specialized surgical sponge formats with detectable elements gain formulary acceptance.
Nonwoven Sponges Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with distribution scale and sterilization infrastructure ownership determining contract access. The market structure concentrates among health system suppliers with captive logistics networks and manufacturers with in-house terminal sterilization capabilities. Three archetypes dominate: diversified medical distributors leveraging procurement relationships, specialty surgical consumables producers with differentiated product formats, and integrated nonwoven converters with polymer-to-finished-goods control. Competitive moves center on sterilization capacity expansion and vertical integration into meltblown microfiber production to escape commodity pricing pressure.
Among diversified health system suppliers, Cardinal Health and McKesson Corporation occupy positions defined by distribution scale and hospital procurement consolidation capture. Medline Industries exemplifies the infrastructure-heavy archetype through sterilization asset ownership that reduces third-party dependency. Mölnlycke Health Care represents specialty differentiation focused on surgical applications with technical specifications that command formulary preference. 3M Company and B. Braun Melsungen AG sit within multi-segment medical portfolios where nonwoven sponges integrate with broader procedure kit and infection control offerings.
| Leading Market Players |
|---|
| Cardinal Health |
| Medline Industries |
| McKesson Corporation |
| Dukal Corporation |
| Dynarex Corporation |
| B. Braun Melsungen AG |
| 3M Company |
| Mölnlycke Health Care |
| Ahlstrom-Munksjö Oyj |
| Others |
Cost & Logistics Intelligence
FDA Quality System Regulation compliance gates both supplier qualification and price differentiation in nonwoven sponges, creating tiered access where validated sterilization documentation commands premium positioning over unvalidated imports.
Pricing Analysis
Long-term offtake contracts dominate hospital system procurement, with spot purchasing limited to emergency replenishment. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-validated surgical grades from general wound care and industrial cleaning variants. Cost compression in standard-tier polyester-rayon blends is intensifying because health system consolidation concentrates purchasing power among fewer decision-makers. Ambulatory surgical centers exhibit highest price sensitivity due to thin operating margins, while integrated delivery networks prioritize total cost-of-ownership over unit price.
Supply Chain Analysis
Gamma sterilization capacity concentration in Ohio and North Carolina creates a chokepoint that constrains terminal processing for high-volume manufacturers. Raw material supply draws from Saudi Arabian and Qatari petrochemical feedstocks for polypropylene resin, while rayon pulp sources from Brazilian and Indonesian forestry operations. Single-source vulnerability runs through concentrated third-party sterilization services clustered in limited geographic zones. Distribution runs through diversified health system suppliers with captive logistics networks and direct hospital procurement portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sterilization validation engineering and track-and-trace system integration represent expanding service-attach layers growing faster than base sponge manufacturing, as hospitals outsource compliance documentation and UDI implementation.
For Market Incumbents: Secure gamma and ethylene oxide sterilization capacity in underserved geographies to reduce third-party dependency and defend against emerging regional converters. Expand backward integration into meltblown microfiber production to escape commodity pricing pressure from carded web competitors. Hospital value analysis committee consolidation threatens margin compression without differentiated technical documentation. For New Entrants and Emerging Players: EPA FIFRA antimicrobial additive registration fast-tracks market access for chlorhexidine-impregnated variants ahead of unregistered competitors. Target India's government hospital modernization programs and private chain investments where local manufacturing incentives reduce import dependency. Pursue direct-to-patient home wound care channels through e-commerce platforms bypassing traditional GPO procurement. For Investors and Strategic Acquirers: EU Medical Device Regulation transition reshapes the acquisition landscape toward established suppliers with ISO 10993 testing capabilities and biocompatibility documentation infrastructure. Over the projection horizon, vertically integrated converters with polymer-to-finished-goods control and in-house sterilization assets represent the most defensible acquisition archetype. Monitor sterilization validation engineering talent scarcity as an inflection indicator for extended product launch timelines and capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Infrastructure Expansion | Captive gamma and ethylene oxide capacity reduces third-party dependency and supply bottlenecks for high-volume manufacturers. |
| Backward Integration into Meltblown Production | In-house microfiber web manufacturing escapes commodity pricing pressure from conventional carded web suppliers. |
| EPA Antimicrobial Registration | FIFRA-compliant chlorhexidine formulations gain timeline advantages over unregistered competitors in surgical site infection prevention. |
| Hospital System Partnership | Integrated delivery network contracts concentrate purchasing power and secure long-term offtake commitments. |
| Track-and-Trace System Development | UDI-compliant data architecture addresses legacy ERP integration challenges and compliance burdens for mid-tier manufacturers. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and sterilization validation specialists; and secondary validation against FDA 510(k) filings, EPA FIFRA registrations, hospital procurement databases, and customs trade records. Bottom-up demand modeling triangulated against top-down supply capacity assessments across meltblown and carded web production lines.
Across the analysis window, forecasts segmented by product type, material composition, end-user facility type, and application area with geographic regulatory clustering. CAGRs derived from surgical volume recovery trajectories, ambulatory surgical center expansion rates, and antimicrobial sponge formulary adoption curves. Modeled inputs included polypropylene resin price volatility indices and gamma sterilization capacity utilization rates.
Decision-makers should treat outputs as directional under assumptions of continued FDA Quality System Regulation enforcement and health system consolidation; material deviation in regulatory intensity or reimbursement policy would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR transition timelines and India CDSCO phased implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Nonwoven Cotton Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Non Woven Converting Machine Market
Nonwoven Materials
Nonwoven Dust Cover Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Global Melt-Blown Nonwovens Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Global Spunbond Nonwovens Market
Nonwoven Materials
India Non-Woven Geotextiles Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market