
 PET Spunbond Nonwoven Market | 2026-2036
PET Spunbond Nonwoven Market Size, Share, and Industry Trends Forecast 2026-2036
PET Spunbond Nonwoven Market Analysis
Buyer concentration among hygiene and medical OEMs is rebalancing as tier-two automotive suppliers and regional construction material distributors enter procurement channels. Freudenberg Performance Materials Holding SE & Co. KG leverages its European manufacturing footprint to sustain filament consistency for medical-grade output. Toray Industries, Inc. anchors Asian supply through integrated polymer-to-fabric operations. Kolon Industries, Inc. differentiates via specialized PET resin formulations for high-temperature filtration end uses.
PET spunbond nonwoven denotes a continuous-filament fabric manufactured from polyethylene terephthalate chips melted and extruded through spinnerets, then drawn, laid into a web, and thermally bonded at basis weights typically ranging from 8 to 150 grams per square meter. The material delivers dimensional stability, chemical resistance, and permeability control for filtration media, geotextiles, and disposable hygiene products. Polyester product type dominates current volume owing to established resin supply chains and recyclability infrastructure, while biodegradable variants represent the fastest-expanding category as brand owners face packaging waste directives. Medical application commands premium positioning due to sterilization compatibility and regulatory certification burdens, whereas agricultural usage remains price-sensitive and volume-driven.
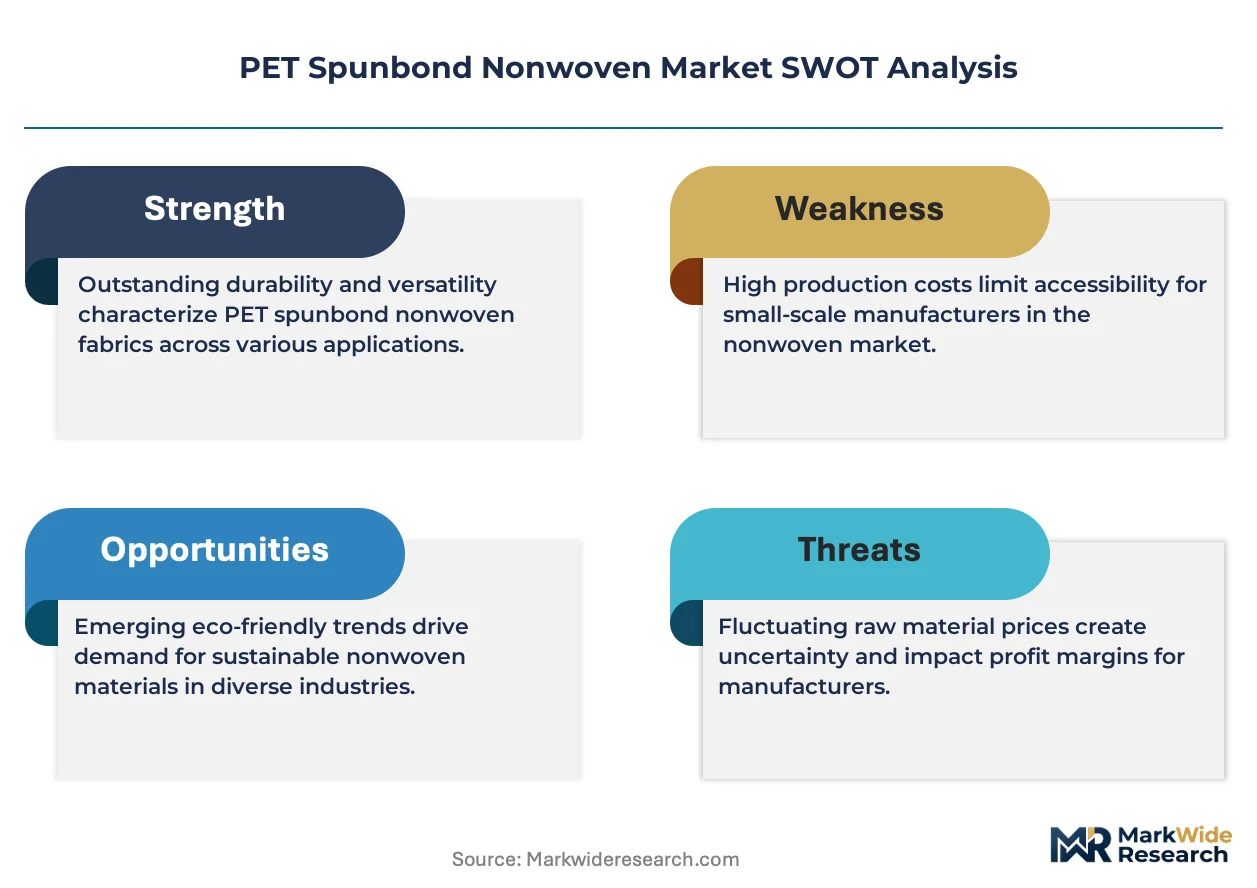
REACH compliance through ECHA governs monomer and additive disclosure for PET spunbond sold across European Union member states, directly elevating testing costs for imported rolls. FDA oversight of medical device components and EPA guidelines on industrial filament extrusion emissions shape product specifications and facility siting decisions in the United States. Stakeholders must weigh capital allocation between biodegradable polymer R&D and legacy polyester capacity as regulatory thresholds for recyclability and carbon intensity tighten without uniform international alignment.
Market Dynamics
Medical-grade hygiene procurement is consolidating around sterilization-certified suppliers as EU Green Deal traceability mandates force filament-level documentation, compressing the viable supplier base for European OEMs.
Growth Catalysts
- EU Green Deal compliance protocols:Material traceability requirements are filtering procurement toward certified European mills capable of monomer disclosure, accelerating consolidation among REACH-compliant suppliers.
- Medical device sterilization demand:Gamma and steam sterilization compatibility is pulling premium-grade PET spunbond into surgical drapes and wound care applications at expanding volumes.
- Germany's industrial belt concentration:Düsseldorf-Cologne corridor demand for filtration media is anchoring regional capacity expansion and specialized resin formulation R&D.
Market Restraints
- Purified terephthalic acid volatility:Crude-linked PTA feedstock costs swing filament economics unpredictably, compressing margin visibility for non-integrated extruders.
- Single-region supply concentration:Asian polymer-to-fabric integration controls upstream resin pricing leverage, limiting European converter bargaining power.
- Biodegradable polymer performance gap:PLA and PHA alternatives lack dimensional stability under thermal bonding, blocking substitution in high-temperature filtration end uses.
Strategic Opportunities
- Construction geotextile underpenetration:India's infrastructure build-out lacks qualified domestic PET spunbond capacity, creating import substitution openings for REACH-certified exporters.
- Dual carbon alignment in China:MEE emission intensity targets are incentivizing recycled-content filament lines, rewarding early movers with provincial green financing.
- Direct-to-brand distributor bypass:Hygiene OEMs are contracting directly with extrusion houses, disintermediating traditional textile traders and capturing 8-12 point margin compression.
Industry Challenges
- MDR certification timelines:European medical device regulation technical documentation requirements extend product qualification cycles to 18-24 months, freezing formulation iterations.
- Multi-site ERP integration:Traceability mandates require real-time lot tracking across polymer receipt, extrusion, and thermal bonding, straining legacy MES architectures.
- Specialized melt-spinning talent scarcity:Experienced spinneret design engineers and rheology specialists command premium compensation in Germany's industrial belt, constraining greenfield project staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Spunbond Nonwoven Market |
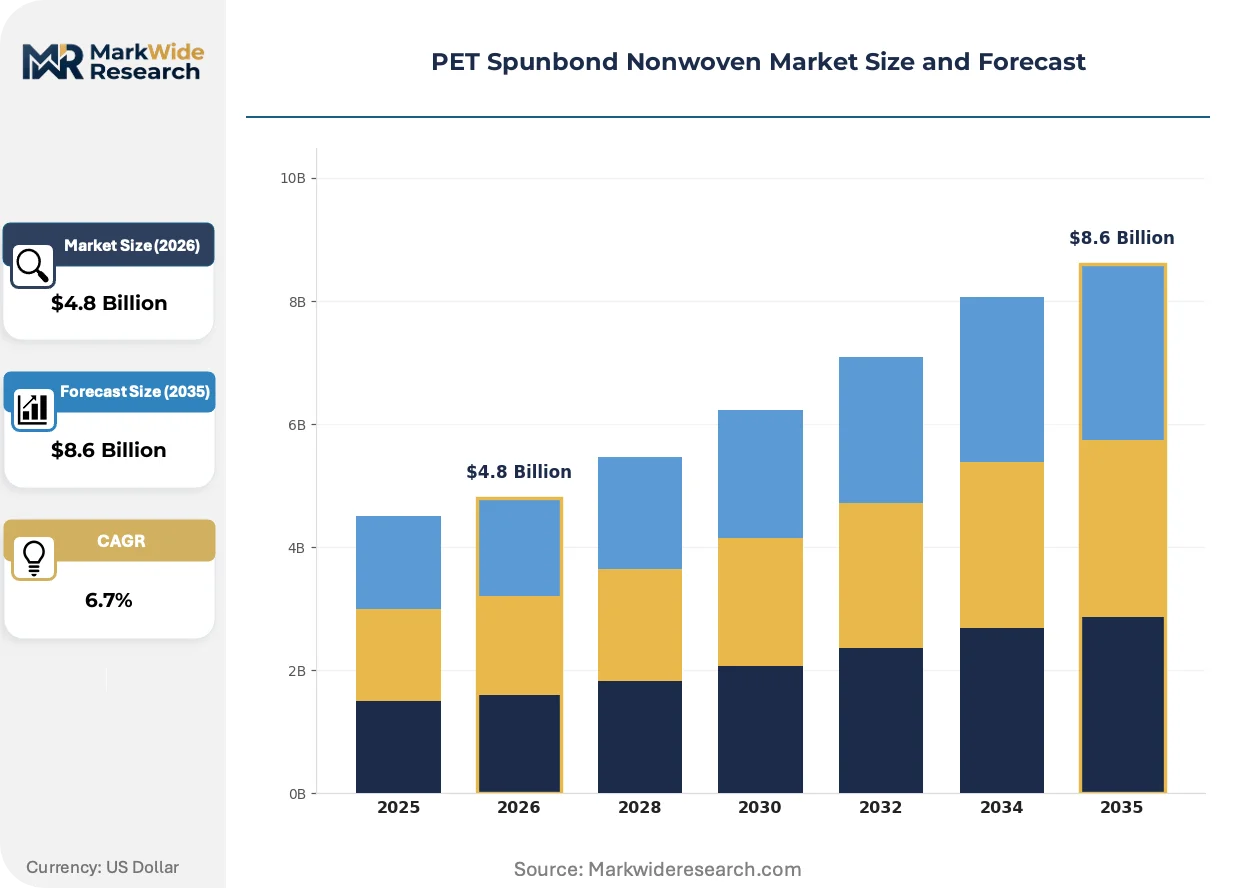
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Biodegradable, Chemical Spunbond, Meltblown Application: Filters, Agriculture, Medical, Hygiene End User: Textile, Packaging, Automotive, Construction Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Toray Industries, Inc., Freudenberg Performance Materials Holding SE & Co. KG, Kolon Industries, Inc., Toyobo Co., Ltd., Asahi Kasei Corporation, Unitika Ltd., Johns Manville Corporation, Fitesa SA, Avintiv, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Spunbond Nonwoven Market Emerging Trajectories
Filament production and bonding processes are converging with digital quality systems and circular feedstock verification, compressing the gap between polymer receipt and certified roll shipment.
Inline spectroscopic polymer verification is automating contaminant detection at melt-extrusion inlets. Medical-grade converters in Germany are deploying these systems to pre-empt REACH audit failures. The technology is automating manual lab sampling workflows and compressing batch release cycles from hours to minutes.
REACH through ECHA now mandates full additive disclosure for PET spunbond sold across EU member states, elevating testing costs for imported rolls. FDA parallel oversight of medical device components shapes sterilization validation protocols. Filtration media producers are responding by consolidating supplier qualification lists to dual-certified extruders.
Brand owners are unbundling after-sales technical service from material supply contracts, purchasing filament specification consulting separately from roll procurement. Hygiene OEMs in the Düsseldorf-Cologne corridor are leading this disintermediation, driving margin pressure on traditional full-service distributors. The shift is most visible among tier-two automotive suppliers entering medical-grade channels without legacy textile trading relationships.
PET Spunbond Nonwoven Market Segmentation
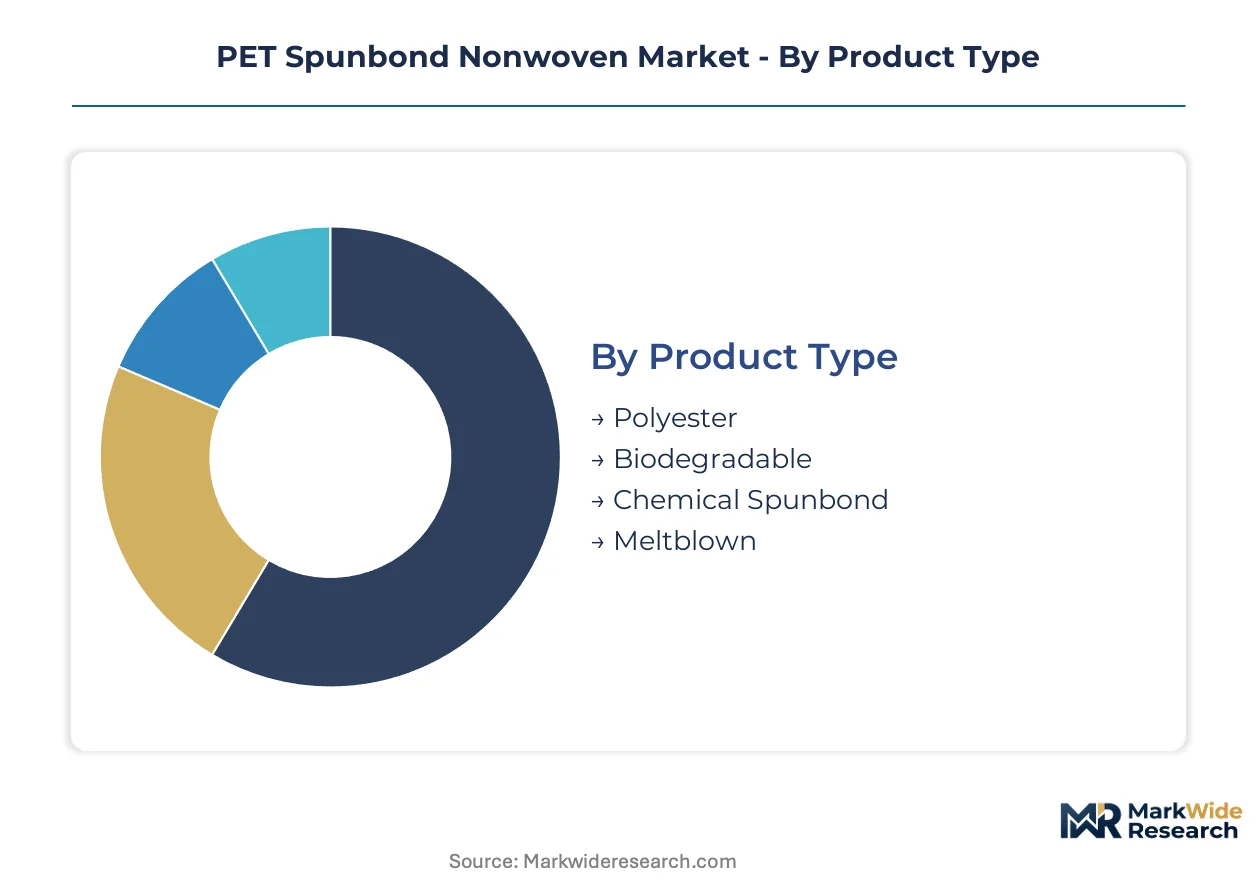
PET spunbond nonwoven markets fragment across material chemistry, sterilization requirements, and supply chain proximity. Procurement teams navigate trade-offs between REACH-certified European supply and Asian polymer-to-fabric integration. Each segmentation axis reveals distinct margin structures and qualification barriers.
Product Type:
Filament chemistry and bonding architecture determine thermal stability, recyclability pathways, and regulatory burden. Material scientists at Düsseldorf-Cologne extruders prioritize dimensional consistency under gamma sterilization.
- Polyester:Virgin PET resin delivers established dimensional stability across 8-150 gsm basis weights. REACH-compliant German mills concentrate procurement for medical-grade output requiring monomer traceability documentation. Automotive interior laminates and surgical drapes anchor volume demand.
- Biodegradable:PLA and PHA formulations face thermal bonding limitations above 140°C. Agricultural mulch film trials in France and Italy are climbing the fastest as packaging waste directives harden, though high-temperature filtration end uses remain blocked.
- Chemical Spunbond:Solvent-based bonding achieves softer hand feel for premium hygiene applications. Japanese converters deploy this technology for cosmetic sheet mask substrates.
- Meltblown:Microfiber webs below 10 gsm enable high-efficiency filtration media. EPA emission guidelines on ultrafine filament extrusion constrain US greenfield capacity.
Polyester leads on scale; biodegradable gains share fastest.
Application:
End-use sterilization protocols and barrier performance specifications split procurement into premium-certified and commodity-volume channels. OEM qualification timelines stretch from months to years.
- Filters:HVAC and liquid filtration media demand controlled permeability across 10-50 micron ratings. Germany's industrial belt around Düsseldorf anchors regional capacity expansion for industrial air handling systems.
- Agriculture:Crop protection fleeces and greenhouse shading prioritize UV stability over certification burden. Indian infrastructure build-out lacks qualified domestic capacity, creating import substitution openings.
- Medical:Gamma and steam sterilization compatibility pulls premium-grade output into surgical drapes and wound care. MDR technical documentation extends product qualification cycles to 18-24 months.
- Hygiene:Diaper acquisition layers and feminine care topsheets drive high-volume, price-sensitive procurement. Tier-two automotive suppliers are entering this channel without legacy textile trading relationships.
Hygiene dominates volume throughput; medical commands premium positioning.
End User:
Customer technical capabilities and specification authority determine whether supply flows through distributors or direct mill contracts. Brand owners are unbundling after-sales consulting from material procurement.
- Textile:Lamination houses and apparel interlining converters source certified rolls for bonding to woven substrates. Freudenberg Performance Materials anchors European supply through integrated manufacturing footprint.
- Packaging:Flexible food and industrial packaging demands heat-seal compatibility and print surface quality. FDA oversight shapes sterilization validation protocols for medical device pouches.
- Automotive:Interior trim and underbody shields require flame-retardant additives meeting OEM material data sheet standards. Tier-two suppliers are bypassing traditional textile traders, capturing 8-12 point margin compression.
- Construction:Geotextile separation and filtration layers specify tensile strength and puncture resistance. India's infrastructure build-out lacks qualified domestic PET spunbond capacity.
Textile channels the most fragmented demand; automotive is concentrating procurement fastest.
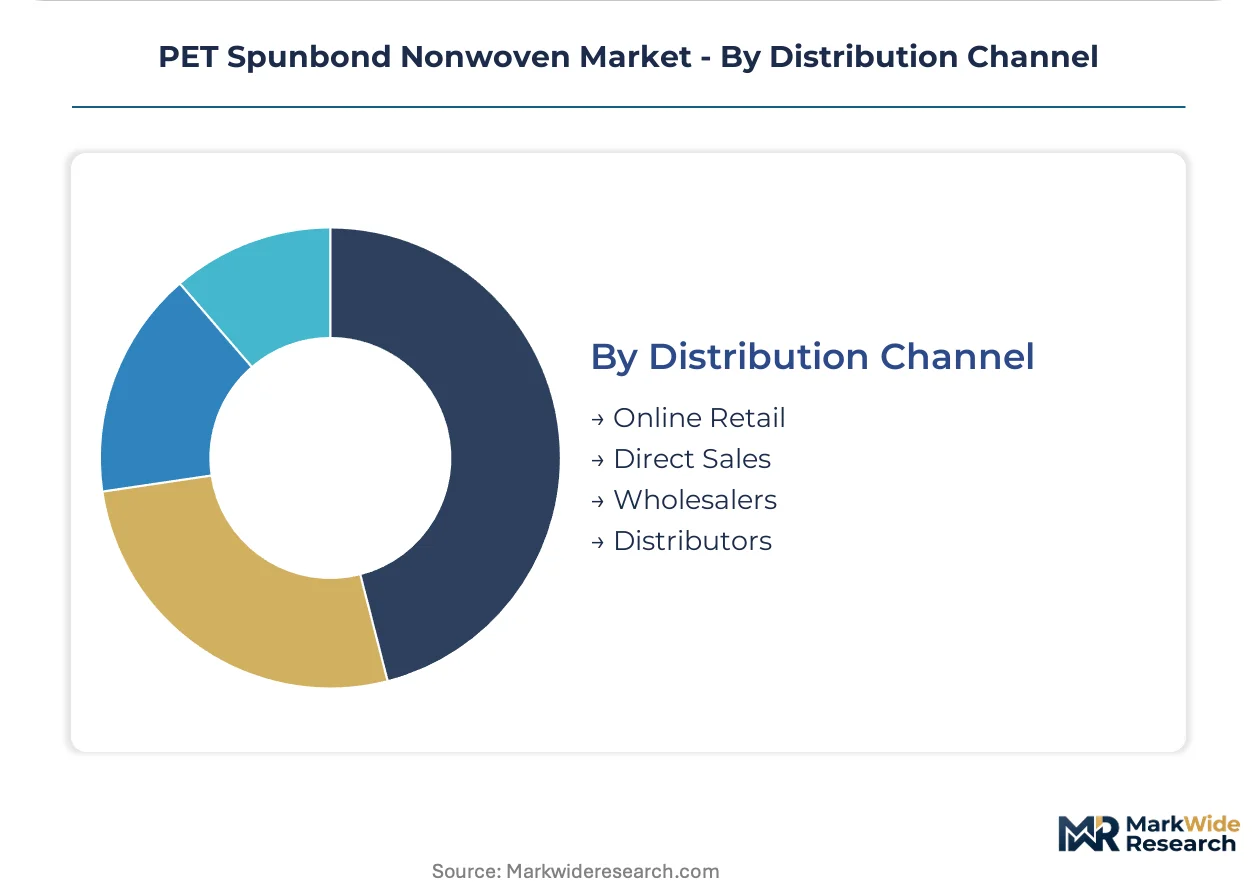
Distribution Channel:
Channel selection reflects lot size, technical service requirements, and traceability documentation burden. REACH mandates are compressing the viable supplier base for European OEMs.
- Online Retail:Small-lot sampling and rapid prototyping orders flow through digital platforms. R&D labs at hygiene OEMs use this channel for formulation iteration before mill-direct volume contracts.
- Direct Sales:Hygiene OEMs in the Düsseldorf-Cologne corridor are contracting directly with extrusion houses, disintermediating traditional traders. This shift is most visible among tier-two automotive suppliers entering medical-grade channels.
- Wholesalers:Regional construction material distributors aggregate demand from fragmented site contractors. Price-sensitive agricultural fleeces move through this channel in Southern Europe.
- Distributors:Full-service textile traders face margin pressure as brand owners unbundle technical consulting from roll procurement. REACH-compliant European mills are consolidating qualification lists to dual-certified extruders.
Direct sales leads on margin capture; online retail expands fastest for sampling workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized melt-spinning engineers cluster in Germany's industrial belt, anchoring European medical-grade capacity. PTA feedstock volatility and REACH compliance costs are redrawing procurement maps across major manufacturing zones.
Germany
Surgical drape and filtration media demand pulls premium-grade output toward the Düsseldorf-Cologne corridor. ECHA REACH mandates full additive disclosure, elevating testing costs for non-integrated converters. Spinneret design specialists command premium wages in North Rhine-Westphalia, constraining greenfield staffing.
United States
Gamma sterilization compatibility requirements from FDA shape medical device component sourcing. EPA emission guidelines on ultrafine filament extrusion constrain capacity expansion in southeastern states. Johns Manville anchors industrial filtration supply from its Colorado-based operations.
China
Provincial dual carbon targets from MEE incentivize recycled-content filament lines. Yangtze River Delta converters capture green financing for emission intensity reductions. Integrated polymer-to-fabric operations control upstream resin pricing leverage for Asian supply.
India
Infrastructure build-out in Maharashtra and Gujarat lacks qualified domestic PET spunbond capacity for geotextile applications. BIS certification requirements create import substitution openings for REACH-certified European exporters. Construction material distributors aggregate fragmented site contractor demand.
Japan
Cosmetic sheet mask substrates and premium hygiene applications drive specialized chemical spunbond demand. METI standards on material traceability align with EU Green Deal protocols for export-oriented mills. Toyobo and Toray anchor integrated operations serving Asian brand owners.
PET Spunbond Nonwoven Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across filament chemistry and bonding architecture tiers. Market structure concentrates around polymer-to-fabric integrators and regional conversion houses serving certified medical channels. Three archetypes dominate: Asian resin-integrated conglomerates, European REACH-certified medical specialists, and regional construction-focused distributors. Capacity expansion and direct-to-brand distributor bypass represent the dominant competitive moves compressing traditional trading margins.
Among Asian resin-integrated conglomerates, Toray Industries, Inc. and Kolon Industries, Inc. exemplify upstream control strategies. Freudenberg Performance Materials Holding SE & Co. KG represents the European REACH-certified specialist archetype. These three anchors illustrate the geographic and regulatory fault lines splitting procurement between traceability-mandated European supply and cost-optimized Asian polymer integration.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Freudenberg Performance Materials Holding SE & Co. KG |
| Kolon Industries, Inc. |
| Toyobo Co., Ltd. |
| Asahi Kasei Corporation |
| Unitika Ltd. |
| Johns Manville Corporation |
| Fitesa SA |
| Avintiv, Inc. |
| Others |
Supply Flow & Price Mechanics
Inline spectroscopic polymer verification is automating contaminant detection at melt-extrusion inlets, simultaneously compressing batch release cycles from hours to minutes and compressing the viable supplier base toward capital-intensive European mills. This technology shift elevates fixed-cost burdens for non-integrated converters while rewarding REACH-certified extruders with pricing power in medical-grade channels.
Pricing Analysis
The bundled-vs-unbundled service split is reshaping contract structures across the Düsseldorf-Cologne corridor. Three-tier pricing structure across premium, standard, and economy levels separates gamma-sterilization-certified medical rolls from industrial filtration grades and agricultural fleeces. Price differentiation hinges on REACH documentation depth and after-sales technical consulting inclusion. Hygiene OEMs disintermediating traditional textile traders are capturing 8-12 point margin compression, forcing distributors to unbundle consulting from roll procurement. Agricultural applications remain most price-sensitive; medical device components show least sensitivity due to MDR qualification barriers.
Supply Chain Analysis
Workforce-availability constraints in Germany's industrial belt around Düsseldorf and Cologne are elevating spinneret design engineer compensation premiums, constraining greenfield project staffing. Supply concentrates in China, Germany, and India for distinct tier applications. Raw material flows draw from purified terephthalic acid feedstocks, virgin PET resin supply chains, and emerging recycled-content filament lines. Single-source vulnerability runs through Asian polymer-to-fabric integrators controlling upstream resin pricing leverage. Distribution runs through direct mill contracts for hygiene OEMs, regional construction material distributors for geotextiles, and digital platforms for R&D sampling workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PET spunbond nonwoven markets present margin-expansion potential as REACH compliance costs filter procurement toward certified European mills capable of capturing premium positioning. Cost compression in standard-grade channels is accelerating consolidation among dual-certified extruders.
For Market Incumbents: Deploy backward integration into specialized PET resin formulations to defend against Asian polymer-to-fabric pricing leverage. Freudenberg Performance Materials anchors European supply through integrated manufacturing footprint; competitors should replicate this model in North Rhine-Westphalia. Consolidate supplier qualification lists to dual-certified extruders ahead of MDR documentation extensions. Channel control through direct mill contracts captures margin compression from disintermediated textile traders.
For New Entrants and Emerging Players: Begin with India's geotextile infrastructure build-out in Maharashtra and Gujarat, where qualified domestic PET spunbond capacity remains scarce. Agricultural mulch film trials in France and Italy offer fastest-expanding biodegradable formulation demand. Construction material distributors aggregate fragmented site contractor demand, providing go-to-market access without legacy textile trading relationships. BIS certification requirements create import substitution openings for REACH-certified European exporters.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional construction-focused distributors facing margin pressure from unbundled technical service contracts. Long-term viability over the next decade rests on dual carbon alignment capabilities and recycled-content filament line deployment. Target acquisition archetype: European REACH-certified medical specialists with spinneret design engineering talent in Germany's industrial belt. Monitor MEE emission intensity targets in China as inflection indicator for green financing flows into recycled-content capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | ECHA additive disclosure mandates elevate testing costs for non-compliant imported rolls. |
| Recycled-Content Filament Expansion | MEE dual carbon targets in China reward early movers with provincial green financing access. |
| Direct-to-Brand Distribution Bypass | Hygiene OEMs in Düsseldorf-Cologne corridor capture margin compression from disintermediated traders. |
| Specialized Resin Formulation R&D | Kolon Industries differentiates via high-temperature PET variants for filtration end uses. |
| Inline Spectroscopic Quality Systems | German medical-grade converters automate contaminant detection to pre-empt audit failures. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extrusion plant managers, procurement leads at hygiene OEMs, spinneret design engineers, and distribution channel partners with secondary validation. Secondary sources included ECHA REACH registration databases, FDA medical device component filings, customs and trade flow data, and SEC disclosures from listed materials conglomerates. Bottom-up filament capacity estimates and top-down end-use demand modeling were triangulated for convergence.
Historical reference periods anchored volume and value trajectories across the projection horizon, with segmentation dimensions spanning filament chemistry, sterilization certification tier, end-use application, and regional production hub. CAGRs were derived from fitted growth curves calibrated to disclosed capacity expansion timelines and procurement contract visibility. Industry-specific forecast inputs incorporated PTA feedstock cost volatility indices and MDR technical documentation cycle lengths.
Several conditions sit outside the modeled scope, including abrupt REACH regulatory amendments, breakthrough biodegradable polymer thermal stability advances, and geopolitical disruptions to Asian resin supply chains. Forecasts reflect documented assumptions about certification timeline continuity and feedstock cost correlation patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Non-Wood Fiber Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Global Polypropylene (PP) Nonwoven Fabrics Market
Nonwoven Materials
Nonwoven Floor Covers Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
HDPE Nonwoven Market
Nonwoven Materials
Meltblown Fabrics Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Nonwoven Sponges Market
Nonwoven Materials
Global Non Woven Fabric Market
Nonwoven Materials
United States Non-Woven Fabric Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Nonwoven Industrial Membrane Market