
 Nonwoven Floor Covers Market | 2026-2036
Nonwoven Floor Covers Market Size, Share, and Industry Trends Forecast 2026-2036
Nonwoven Floor Covers Market Intelligence
The substitution of virgin polymers with recycled polyester (rPET) is expanding the cost-competitiveness and sustainability profile of nonwoven floor coverings. Mohawk Industries leverages its manufacturing scale and broad distribution network across residential and commercial channels. Shaw Industries specializes in modular carpet tiles designed for corporate environments, emphasizing durability and design. The Freudenberg Group differentiates through its advanced nonwoven material technologies for automotive and industrial underlayment applications, focusing on acoustic and thermal performance.
Nonwoven floor covers are textile surfaces produced by bonding fibers together chemically, thermally, or mechanically, rather than through weaving or knitting. These products, often specified by basis weight and fiber composition like polypropylene or polyester, serve as primary flooring or functional underlayment. Carpet tiles for commercial applications represent a high-value segment due to design flexibility and ease of replacement. Underlayment products command significant volume in both residential and automotive sectors, competing on performance metrics and cost-efficiency.
Regulatory frameworks significantly influence material selection and market access for nonwoven floor covers. The US EPA's rules on volatile organic compound (VOC) emissions and the EU's REACH regulation on chemical substances govern product composition. In China, compliance with national GB standards for flammability and durability is mandatory for all flooring products. Stakeholder success will depend on navigating these disparate regional standards while managing raw material price volatility.
Market Dynamics
The integration of circular economy principles, particularly the use of recycled polyester, is the central force reshaping the nonwoven floor covers market. This shift influences everything from raw material sourcing and cost structure to final product specification and regulatory compliance.
Growth Catalysts
- Sustainability Mandates:Policies like the EU Green Deal and corporate ESG initiatives are accelerating the specification of products with high recycled polyester (rPET) content, particularly in commercial building projects across Europe and North America.
- Commercial Sector Expansion:Growth in the hospitality and corporate office sectors drives demand for durable, design-flexible solutions like modular carpet tiles, which offer ease of replacement and maintenance in high-traffic environments.
- Construction Activity:High-growth construction markets, especially in the United States and China, generate significant volume demand for both primary floor coverings and functional underlayment products in new residential and commercial buildings.
Market Restraints
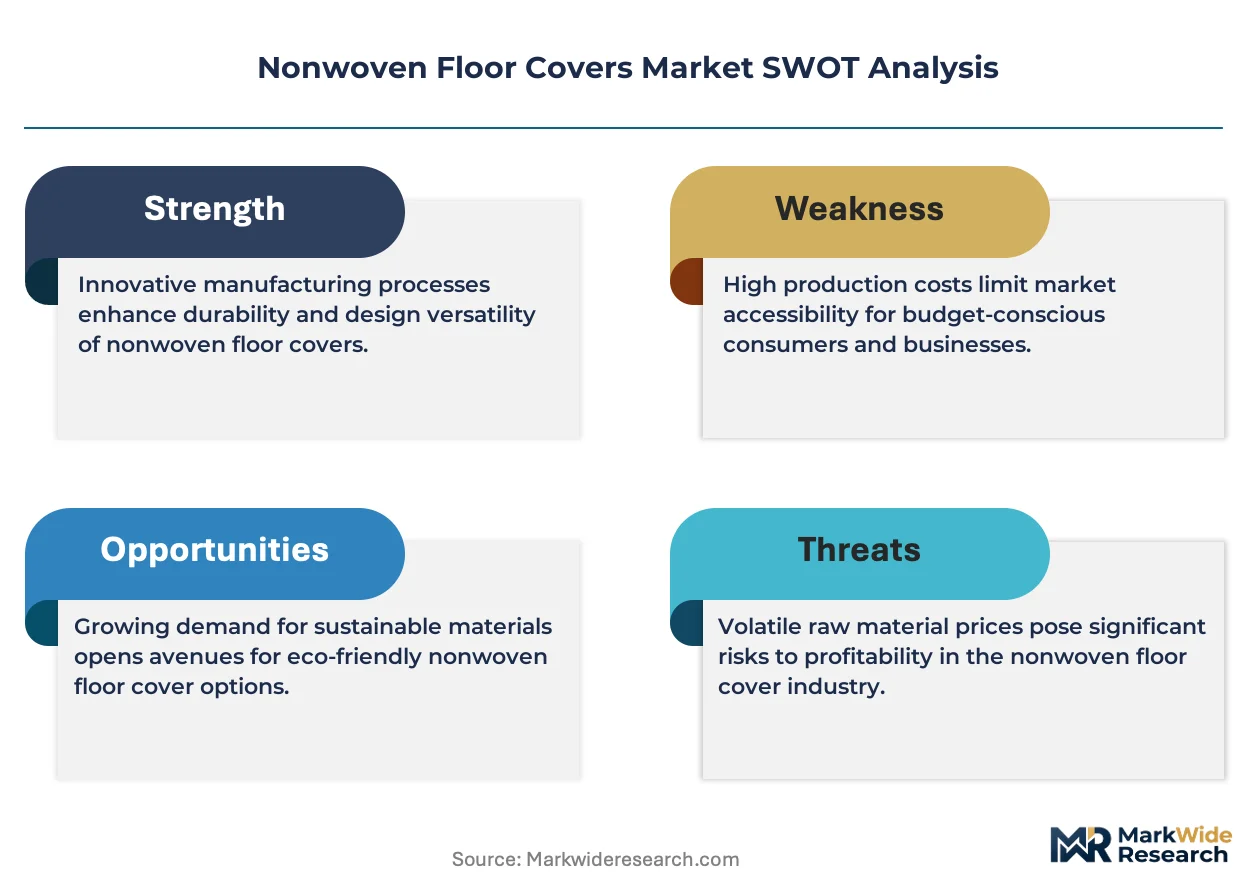
- Raw Material Volatility:Price fluctuations in virgin polymers, such as polypropylene and polyester, directly impact manufacturing costs and create margin pressure, especially for producers competing in cost-sensitive segments.
- Regulatory Fragmentation:Navigating disparate regional standards, including the US EPA's rules on VOC emissions and China’s mandatory GB standards for flammability, increases compliance costs and complexity for producers operating across multiple markets.
- Substitution Threat:Competition from alternative flooring materials, particularly high-performance luxury vinyl tile (LVT) in commercial applications, challenges the market share of nonwoven floor covers by offering different aesthetic and maintenance profiles.
Strategic Opportunities
- Automotive Sector Applications:The transition to electric vehicles creates an opportunity for specialized nonwoven underlayments designed for superior acoustic and thermal insulation to manage new noise profiles and improve battery efficiency.
- Bio-Based Materials:Developing and commercializing nonwoven floor covers using bio-based polymers and binders presents an opportunity to move beyond recycled content and capture demand for next-generation sustainable materials.
- Emerging Market Infrastructure:Targeting large-scale infrastructure and commercial real estate projects in high-growth economies in Southeast Asia and the Middle East can open new channels for volume sales.
Industry Challenges
- Certification Complexity:The time and expense required to secure and maintain multiple environmental and performance certifications, such as the EU's CE marking or various green building labels, can be a barrier for smaller manufacturers.
- Feedstock Quality Control:Reconfiguring supply chains to secure a consistent and high-quality supply of post-consumer rPET feedstock remains a significant operational challenge, impacting final product consistency and performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nonwoven Floor Covers Market |
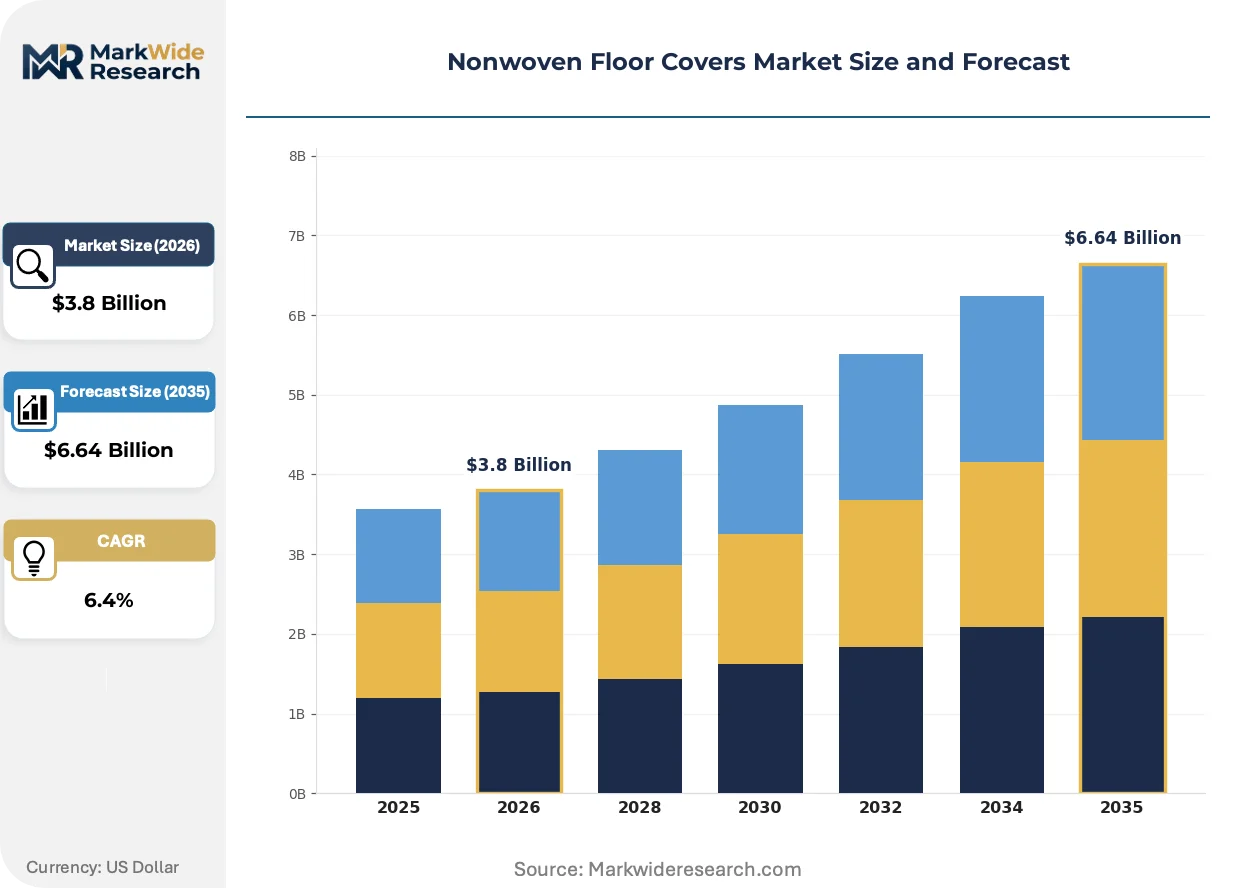
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet Tiles, Area Rugs, Mats, Underlayment Application: Residential, Commercial, Industrial, Automotive Material: Polypropylene, Polyester, Polyethylene, Viscount End User: Homeowners, Contractors, Retailers, Hospitality |
| Companies Covered | Lentex S.A., Mohawk Industries, Inc., Shaw Industries, DuPont, Berry Global, Flexituff Ventures International Ltd, Johns Manville, Freudenberg Group, Fibertex Nonwovens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nonwoven Floor Covers Market Strategic Shifts & Innovations
A convergence of material science and sustainability mandates is defining the next generation of nonwoven floor coverings. Manufacturers are balancing demands for enhanced performance characteristics like acoustics and durability with the commercial imperative for circularity and lower environmental impact across the product lifecycle.
Advanced needlepunch and hydroentanglement technologies create denser, more durable nonwoven structures. These are being adopted rapidly in high-traffic commercial applications, including corporate offices and retail. This technological improvement is unifying the performance gap between traditional woven carpets and nonwoven alternatives in premium segments, expanding addressable applications.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant policy shift. It compels large companies to disclose detailed environmental impacts from their supply chains and building materials. This affects flooring specifiers in the corporate sector, who now prioritize products with transparent lifecycle assessments to meet their own reporting obligations.
Modularity and ease of replacement are altering specification habits in commercial interiors. Instead of broadloom carpets, facility managers and designers are specifying carpet tiles, which disrupts traditional installation channels that are based on larger roll-goods. This trend is most prominent in the North American and European corporate office sectors, where design flexibility is paramount.
Nonwoven Floor Covers Market Segmentation
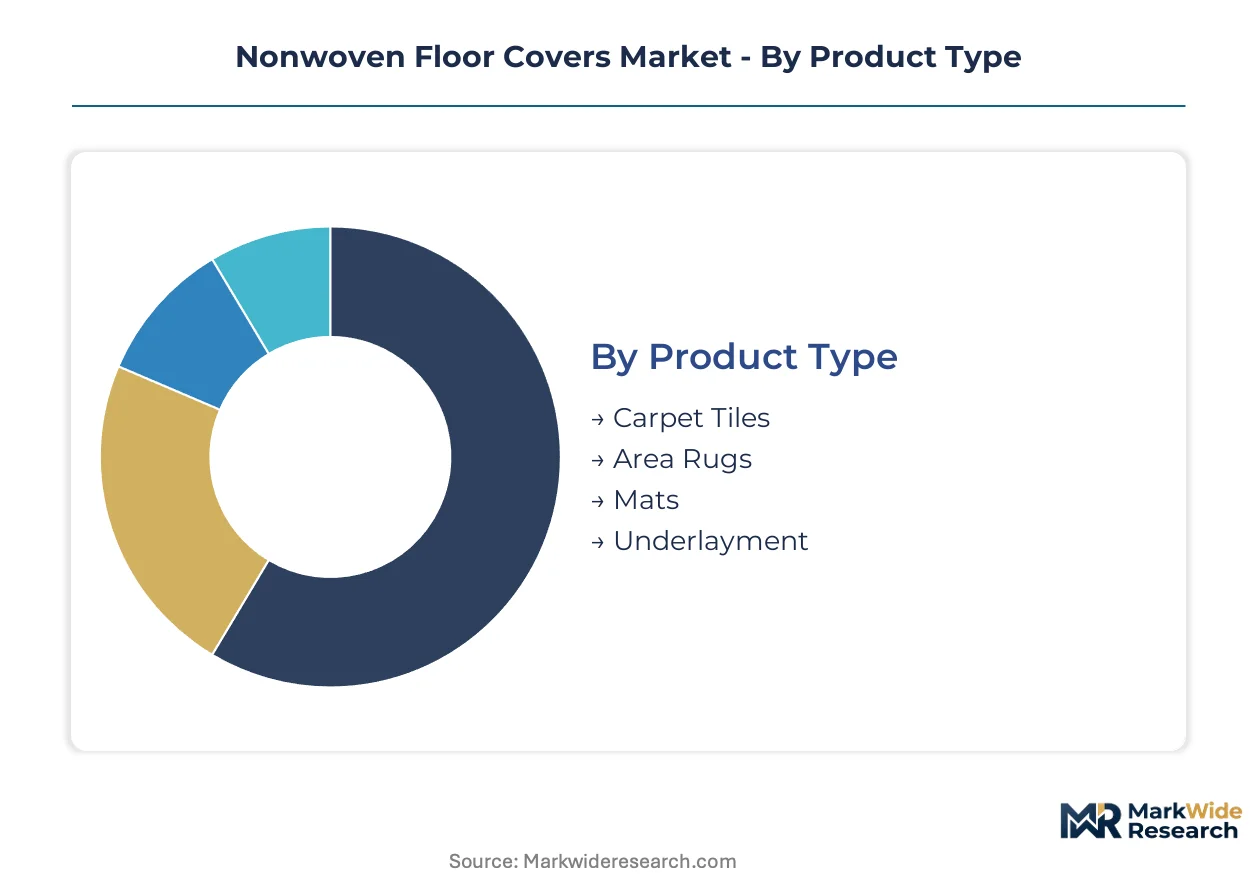
The nonwoven floor covers market categorizes products based on their functional attributes, material composition, and intended applications, allowing for a granular understanding of demand drivers. This segmentation highlights the diverse end-user requirements and the varied performance characteristics of nonwoven solutions across different sectors. Analyzing these segments reveals specific opportunities for product development and market penetration.
Product Type:
The market for nonwoven floor covers spans a spectrum from highly customized design elements to standardized functional layers.
- Carpet Tiles:These modular nonwoven floor coverings offer design flexibility and ease of replacement, often featuring advanced backing systems for stability. Demand concentrates in corporate offices and hospitality venues across the United States and Europe, driven by aesthetic versatility and maintenance benefits.
- Underlayment:Functional nonwoven layers installed beneath primary flooring, providing acoustic insulation, thermal regulation, and moisture barrier properties. This segment commands significant volume in new residential construction in China and automotive manufacturing globally, competing on cost-efficiency and performance metrics.
- Area Rugs:Pre-sized nonwoven floor coverings used for decorative purposes or to define spaces within residential and light commercial settings.
- Mats:Smaller, often portable nonwoven floor covers designed for specific functional needs like entrance protection or anti-fatigue applications.
Leading the category by volume: Underlayment. Growing fastest: Carpet Tiles.
Application:
The volume profile of nonwoven floor covers varies significantly across different application areas.
- Commercial:Nonwoven floor covers in this segment serve high-traffic environments like offices, retail stores, and educational institutions, prioritizing durability and aesthetic appeal. Growth in the hospitality and corporate office sectors drives demand for robust, easily maintainable nonwoven solutions.
- Automotive:Specialized nonwoven materials are used for interior carpeting, trunk liners, and under-hood insulation in vehicles, requiring specific acoustic and thermal performance. The transition to electric vehicles creates new demand for lightweight nonwoven underlayments that enhance battery efficiency.
- Residential:This application includes nonwoven carpets, rugs, and underlayments used in homes, focusing on comfort, aesthetics, and cost-effectiveness for homeowners.
- Industrial:Nonwoven floor coverings in industrial settings must withstand heavy wear, chemical exposure, and provide safety features like slip resistance.
Each application presents distinct performance requirements, influencing material selection and product design.
Material:
The cost structure of nonwoven floor covers is heavily influenced by the underlying material composition.
- Polyester:A versatile synthetic fiber, often used in nonwoven floor covers for its durability, stain resistance, and ability to be recycled. The shift towards recycled polyester (rPET) content is a central force, driven by sustainability mandates and the EU Green Deal.
- Polypropylene:A cost-effective polymer widely used in nonwoven floor covers due to its moisture resistance and light weight. Price fluctuations in virgin polypropylene directly impact manufacturing costs for producers in cost-sensitive segments.
- Polyethylene:Utilized in some nonwoven applications for its flexibility, chemical resistance, and barrier properties, particularly in underlayment products.
- Viscount:A fiber type sometimes incorporated into nonwoven blends for specific textural qualities or enhanced absorbency.
Material innovation, particularly in recycled and bio-based alternatives, is reshaping long-term market dynamics.
End User:
Procurement patterns for nonwoven floor covers differ based on the end-user's scale and operational needs.
- Hospitality:Hotels, resorts, and convention centers specify nonwoven floor covers that offer design flexibility, durability, and ease of maintenance in high-traffic areas. This sector drives demand for modular carpet tiles in North America and Europe.
- Contractors:Construction and flooring installation contractors purchase nonwoven floor covers for both residential and commercial projects, focusing on bulk pricing and installation efficiency. Their purchasing decisions are influenced by project specifications and material availability.
- Homeowners:Individual consumers purchasing nonwoven floor covers for personal residences prioritize aesthetics, comfort, and direct retail availability.
- Retailers:Companies selling nonwoven floor covers directly to consumers or businesses, managing inventory and distribution channels for various product types.
Understanding these diverse end-user needs is critical for effective product development and distribution strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for nonwoven floor covers concentrates in regions experiencing significant construction activity and regulatory shifts toward sustainable materials. Commercial applications, particularly in hospitality and corporate offices, drive substantial volume in established markets. Emerging economies also contribute to overall market expansion through large-scale infrastructure projects.
United States
New residential and commercial construction projects generate demand for primary floor covers and underlayment. The US EPA's rules on VOC emissions influence material selection for indoor air quality. Major metropolitan areas like New York and Los Angeles see high specification for modular carpet tiles in corporate settings.
China
Extensive infrastructure development and new building construction create significant volume demand for underlayment products. Compliance with national GB standards for flammability and durability is mandatory for all flooring products. Industrial clusters in the Yangtze River Delta region are key manufacturing and consumption hubs for nonwoven materials.
Germany
The EU Green Deal and corporate ESG initiatives accelerate the specification of rPET content in commercial building projects. REACH regulation on chemical substances governs product composition, ensuring environmental safety. The Rhine-Ruhr metropolitan region, a center for automotive and manufacturing, utilizes advanced nonwoven underlayments.
India
Rapid urbanization and commercial real estate development fuel demand for cost-effective nonwoven floor covers. The country's infrastructure development programs encourage the use of durable and efficient building materials. Major cities like Mumbai and Delhi are experiencing a boom in commercial and residential construction.
United Arab Emirates
Large-scale infrastructure and commercial real estate projects drive significant volume sales for nonwoven floor covers. Regulatory bodies enforce building codes that prioritize durability and safety in high-rise constructions. Dubai's hospitality sector and new commercial developments demand aesthetic and functional flooring solutions.
Nonwoven Floor Covers Market Key Industry Players
Capacity expansion dominates the current landscape for nonwoven floor covers, driven by sustainability mandates and regional construction booms. The market exhibits a tiered structure, with large integrated manufacturers alongside specialized material technology providers. Strategic archetypes include global diversified material suppliers, specialized carpet tile producers, and functional underlayment experts. Geographic expansion and technology licensing represent dominant competitive moves for market participants.
Large integrated manufacturers, leveraging extensive scale and broad distribution networks, include Mohawk Industries, Inc., which serves both residential and commercial channels. Specialized producers like Shaw Industries focus on modular carpet tiles designed for corporate environments, emphasizing durability and design flexibility. The Freudenberg Group exemplifies advanced nonwoven material technologies, differentiating through solutions for automotive and industrial underlayment applications, with a focus on acoustic and thermal performance. These companies navigate complex regulatory frameworks and raw material volatility, securing consistent and high-quality rPET feedstock. Their strategies often involve balancing cost-competitiveness with product innovation to meet evolving market demands.
| Leading Market Players |
|---|
| Lentex S.A. |
| Mohawk Industries, Inc. |
| Shaw Industries |
| DuPont |
| Berry Global |
| Flexituff Ventures International Ltd |
| Johns Manville |
| Freudenberg Group |
| Fibertex Nonwovens |
| Others |
Cost & Logistics Intelligence
Vertical integration into fiber production and backing material manufacturing anchors both the supply position and the pricing power for large nonwoven floor cover producers. This strategic control mitigates raw material volatility and ensures consistent quality for diverse product lines.
Pricing Analysis
Volume-driven segments like underlayment operate on tight margins, while design-flexible carpet tiles command higher value. Contract-based long-term offtake agreements characterize commercial flooring procurement, stabilizing prices for large projects. Price differentiation stems from material composition, particularly recycled content certification, and customization for specific commercial applications. Pricing softness reflects intense competition from alternative flooring materials like LVT, particularly in cost-sensitive segments. Commercial contractors exhibit high price sensitivity, balancing project budgets with performance requirements.
Supply Chain Analysis
National GB standards in China and the EU Green Deal mandates in Europe are reshaping sourcing for nonwoven floor covers, favoring local production and recycled content. China, the United States, and Germany represent significant manufacturing and consumption hubs. Raw material dependencies center on polypropylene, polyester, and increasingly, recycled polyester (rPET) feedstock. Commodity price volatility for virgin polymers poses a structural risk for manufacturers. Distribution runs through a fragmented network of flooring distributors, commercial contractors, and direct-to-retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nonwoven floor covers market is undergoing a technology-transition phase, with advanced needlepunch and hydroentanglement technologies displacing traditional weaving processes for performance-oriented applications.
For Market Incumbents:
Anchor existing market share through continuous investment in advanced manufacturing technologies that enhance durability and acoustic performance. Diversify raw material sourcing to mitigate price volatility in virgin polymers, potentially through long-term rPET supply agreements. Address the threat from luxury vinyl tile by emphasizing the superior acoustic and thermal properties of nonwoven solutions. Invest in R&D for bio-based materials to align with evolving sustainability mandates.
For New Entrants and Emerging Players:
Digital specification platforms and online marketplaces offer a direct-to-designer route for specialized nonwoven floor covers. Target the modular carpet tile segment in emerging commercial construction markets in Southeast Asia, where design flexibility and ease of replacement are valued. Focus on niche applications requiring superior acoustic insulation, particularly in the growing electric vehicle sector. Emphasize transparent lifecycle assessments and certifications as a go-to-market angle.
For Investors and Strategic Acquirers:
Exit pathways concentrate in specialized material technology providers offering unique performance characteristics or advanced recycling capabilities. Long-term viability rests on companies demonstrating robust circular economy integration and strong intellectual property in sustainable materials. Identify acquisition targets that possess established supply chains for high-quality rPET feedstock. The signal to watch is the increasing stringency of corporate sustainability reporting directives, which will drive demand for certified eco-friendly products.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced rPET Feedstock Integration | Securing consistent, high-quality recycled polyester supply stabilizes costs and meets sustainability mandates. |
| Bio-Based Material Commercialization | Developing nonwoven products from renewable sources captures demand for next-generation sustainable solutions. |
| Acoustic Performance Enhancement | Improving sound absorption properties differentiates nonwoven underlayments in automotive and commercial buildings. |
| Modular Product Line Expansion | Offering versatile carpet tiles addresses design flexibility and maintenance needs in corporate office environments. |
| Emerging Market Infrastructure Partnerships | Collaborating on large-scale projects in high-growth economies opens new channels for volume sales. |
Research Approach
Multi-period observation of construction activity, material science advancements, and regulatory shifts anchored the trend analysis, supplemented by interviews with facility managers, material scientists, architects, and procurement leads. Secondary validation drew from government construction reports, corporate sustainability disclosures, and material science journals. The approach utilized both bottom-up market sizing and top-down industry trend triangulation.
Segment-weighting across product type, application, material, and end user formed the core of the quantitative analytical framework. The model further incorporated specific dimensions like basis weight, fiber composition, and backing system technology. Compound annual growth rates over the projection horizon were derived using a combination of historical market data and projected demand drivers. Forecast inputs included construction starts data and rPET availability projections.
The model holds under current economic conditions and regulatory frameworks; deviation in global construction activity or raw material pricing would shift forecast trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nonwoven Materials
Nonwoven Cleanroom Apparel Market
Nonwoven Materials
Asia-Pacific Non-Woven Fabric Market
Nonwoven Materials
Global Nonwoven Disposable Gloves Market
Nonwoven Materials
Global Automotive Nonwoven Fabrics Market
Nonwoven Materials
PET Spunbond Nonwoven Market
Nonwoven Materials
Nonwoven Protective Clothing Market
Nonwoven Materials
Global Wet Laid Nonwovens Market
Nonwoven Materials
Non Woven Printing Machine Market
Nonwoven Materials
Non-Woven Glass Fiber Prepreg Market
Nonwoven Materials
Global Nonwoven Materials and Products Market
Nonwoven Materials
PP Nonwovens Market
Nonwoven Materials
Polywoven Bags Market
Nonwoven Materials
Staples PP Nonwovens Market
Nonwoven Materials
Nonwoven Geotextiles Market
Nonwoven Materials
Nonwoven Industrial Membrane Market
Nonwoven Materials
Hygienic Non-Woven Fabrics Market