
 Global Penicillin Drug Market | 2026-2036
Global Penicillin Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Global Penicillin Drug Market Foresight
Chinese bulk antibiotic producers is pivoting toward fermentation capacity upgrades to secure penicillin G intermediate supply chains. Pfizer Inc. leverages vertical integration across fermentation and finished dose manufacturing to sustain cost advantages in hospital-grade injectables. Aurobindo Pharma Ltd. anchors its position through backward integration into 6-APA production, while GlaxoSmithKline plc competes on brand strength in respiratory infection therapy segments across regulated markets.
Penicillin drugs comprise beta-lactam antibiotics derived from Penicillium fungi fermentation, characterized by a bicyclic beta-lactam ring fused to a thiazolidine ring that inhibits bacterial cell wall synthesis through transpeptidase binding. These compounds serve as first-line or adjunct therapies against gram-positive pathogens in respiratory, skin, and soft tissue infections across inpatient and outpatient settings. Amoxicillin dominates oral prescription volumes as the most widely prescribed aminopenicillin for community-acquired infections, while injectable benzylpenicillin retains critical utility in hospital sepsis protocols where rapid bactericidal action determines patient outcomes. Therapy area segmentation reveals respiratory infections as the mature revenue base, with urinary tract infection applications representing faster growth due to rising ambulatory care utilization and resistance-driven combination therapies.
FDA enforces current Good Manufacturing Practice standards for penicillin cross-contamination prevention in multi-product facilities, while EMA REACH regulations govern solvent discharge from fermentation processes and EMA pharmacovigilance frameworks mandate post-market allergy surveillance. These compliance requirements elevate capital intensity for new market entrants and favor producers with established quality management systems. Stakeholders must monitor antimicrobial stewardship program expansions in hospital systems and corresponding shifts in formulary preference toward narrow-spectrum penicillin derivatives over broad-spectrum alternatives.
Market Dynamics
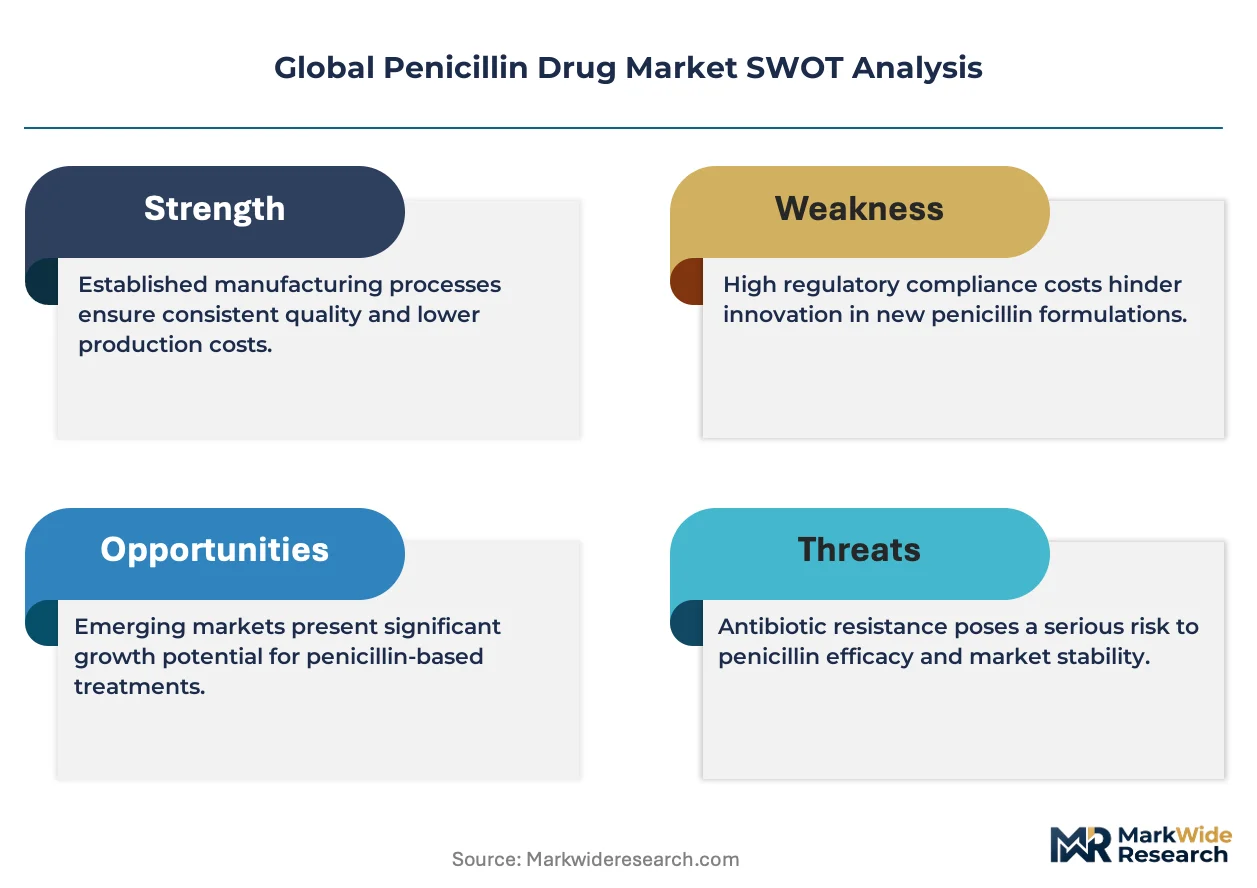
Fermentation capacity concentration across Indian and Chinese bulk manufacturing hubs is reshaping API economics, as FDA and EMA quality mandates force multi-product facilities into costly cross-contamination prevention retrofits that favor incumbent scale players.
Growth Catalysts
- Hospital Sepsis Protocols:Injectable benzylpenicillin retains irreplaceable status in ICU bactericidal regimens, with formulary committees in tertiary care systems mandating rapid-acting gram-positive coverage.
- EMA Pharmacovigilance Frameworks:Post-market allergy surveillance requirements create compliance barriers that filter out substandard producers, tightening supply rationalization around certified manufacturers.
- Fermentation Yield Improvements:Chinese producers deploying automated bioreactor controls are compressing unit costs for penicillin G intermediates, reinforcing cost advantages in generic API export markets.
Market Restraints
- Input Cost Volatility:Corn steep liquor and soybean meal prices fluctuate with agricultural commodity cycles, directly squeezing fermentation margins for bulk penicillin producers.
- Supply Concentration Risk:Overreliance on Shandong and Hebei province clusters for 6-APA intermediates exposes finished dose manufacturers to single-region disruption vulnerabilities.
- Antimicrobial Resistance Substitution:Extended-spectrum cephalosporins and carbapenems displace penicillin in hospital-acquired infection protocols where resistant pathogen prevalence exceeds susceptibility thresholds.
Strategic Opportunities
- Brazilian Ambulatory Care Expansion:ANVISA streamlined generic registration pathways are opening community pharmacy channels for oral aminopenicillin formulations in underserved interior states.
- Combination Therapy Positioning:Beta-lactamase inhibitor pairings with amoxicillin capture urinary tract infection segments where resistance patterns favor synergistic mechanisms.
- Continuous Manufacturing Adoption:FDA quality metrics guidance incentivizes pharmaceutical firms to replace batch fermentation with integrated continuous processing, reducing cross-contamination audit risks.
Industry Challenges
- Specialized Fermentation Expertise Scarcity:Industrial microbiologists capable of optimizing Penicillium chrysogenum strain productivity command premium compensation, constraining capacity expansion timelines.
- Multi-Product Facility Validation:FDA current Good Manufacturing Practice standards for penicillin beta-lactam segregation require dedicated air handling and equipment trains, extending facility qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Penicillin Drug Market |
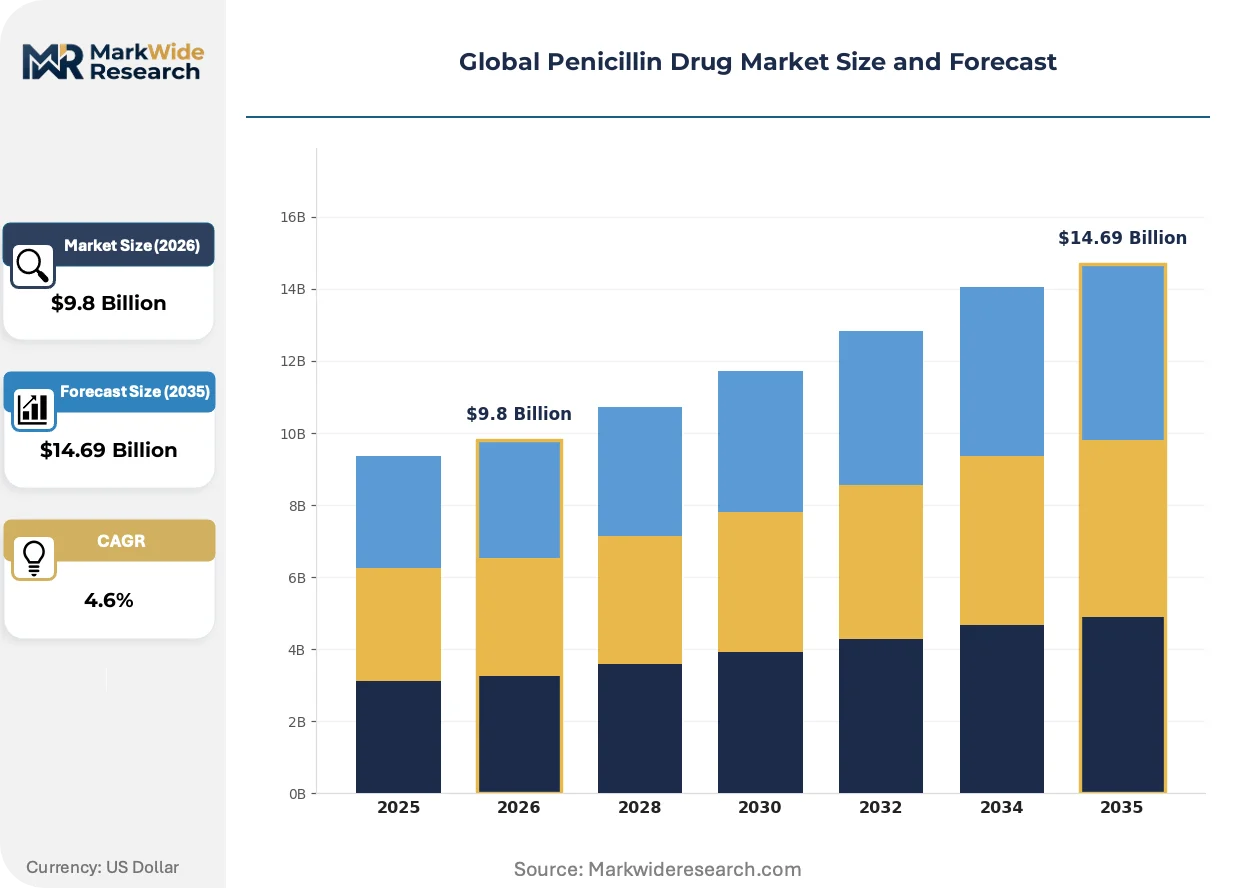
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzylpenicillin, Phenoxymethylpenicillin, Amoxicillin, Ampicillin, Cloxacillin, Flucloxacillin Therapy Area: Respiratory Infections, Skin Infections, Urinary Tract Infections, Sexually Transmitted Diseases, Ear Infections, Dental Infections Dosage Form: Oral Tablets, Injectable Solutions, Capsules, Suspensions, Powders, Creams End User: Hospitals, Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Long-Term Care Facilities |
| Companies Covered | Pfizer Inc., Aurobindo Pharma Ltd., GlaxoSmithKline plc, Sandoz, Teva Pharmaceutical Industries Ltd., Cipla Ltd., Sun Pharmaceutical Industries Ltd., Lupin Ltd., Centrient Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Penicillin Drug Market Shifts & Advancements
Process intensification and regulatory digitization are compressing development-to-commercialization timelines, while procurement rationalization in hospital systems favors narrow-spectrum agents with established resistance stewardship profiles.
Continuous fermentation technology with real-time metabolite monitoring is electrifying bulk API manufacturing economics. Indian producers at Hyderabad and Visakhapatnam clusters are retrofitting stirred-tank bioreactors with automated dissolved oxygen control systems. This convergence is enabling 24-hour production cycles that compress capital intensity per kilogram of active pharmaceutical ingredient output.
EMA REACH regulations governing solvent discharge from antibiotic fermentation processes are tightening environmental compliance thresholds. Fermentation facilities must now deploy closed-loop solvent recovery systems or face operating permit restrictions. Bulk producers in Zhejiang province are responding with membrane separation investments to meet dichloromethane emission limits.
Hospital formulary committees are consolidating antibiotic purchasing around narrow-spectrum penicillin derivatives with documented resistance stewardship benefits. IDSA antimicrobial stewardship program mandates in US health systems are displacing empiric broad-spectrum prescribing. This behavioral pivot concentrates procurement volumes with manufacturers holding FDA-approved susceptibility testing breakpoints for specific gram-positive indications.
Global Penicillin Drug Market Segmentation
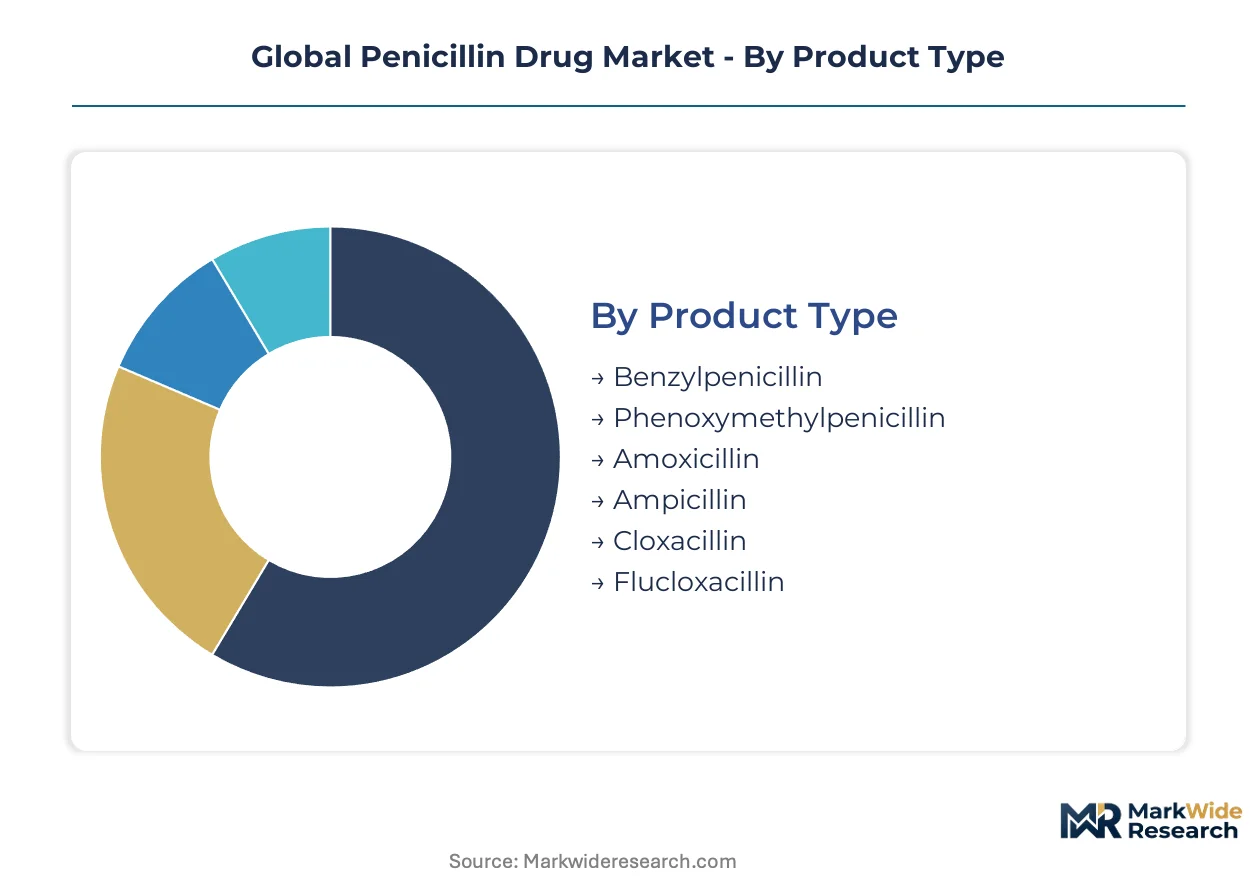
Penicillin drug procurement decisions hinge on infection severity, route of administration urgency, and formulary resistance profiles. Manufacturers align production capacity across fermentation-derived intermediates to match these divergent clinical specifications.
Product Type:
Hospital formulary committees prioritize spectrum specificity and resistance stewardship when selecting among penicillin derivatives for procurement contracts.
- Amoxicillin:This aminopenicillin features enhanced oral bioavailability and broader gram-negative coverage than natural penicillins. Community pharmacies in India and Brazil drive prescription volumes for outpatient respiratory and urinary tract infections, with generic substitution rates compressing brand premiums.
- Benzylpenicillin:The parent compound maintains parenteral administration for rapid bactericidal action in sepsis protocols. ICU departments across tertiary hospitals in the US, Germany, and Japan mandate stockpiles for meningococcal and streptococcal emergencies where time-to-sterilization determines mortality.
- Phenoxymethylpenicillin:Acid-stable oral formulation serving prophylactic streptococcal indications in European primary care networks.
- Ampicillin:Aminopenicillin with extended Enterococcus coverage dominating hospital-acquired pneumonia combination regimens.
- Cloxacillin:Beta-lactamase-resistant penicillin targeting methicillin-susceptible Staphylococcus aureus in Australian and South African skin infection protocols.
- Flucloxacillin:Isoxazolyl penicillin with superior oral absorption prescribed for cellulitis and osteomyelitis in UK NHS community settings.
Amoxicillin leads on scale; benzylpenicillin leads on momentum through sepsis protocol standardization.
Therapy Area:
Resistance surveillance data from ECDC and CDC directly shape prescribing patterns across therapeutic indications.
- Respiratory Infections:Community-acquired pneumonia and pharyngitis constitute the mature revenue base for oral penicillin derivatives. Primary care networks in Germany, France, and Italy maintain high prescription densities despite antimicrobial stewardship pressure to reduce empiric prescribing.
- Urinary Tract Infections:Rising ambulatory care utilization and resistance-driven combination therapies with beta-lactamase inhibitors are expanding this segment fastest. US urgent care chains and Brazilian community pharmacy networks are driving volume shifts toward amoxicillin-clavulanate fixed-dose combinations.
- Skin Infections:Impetigo and cellulitis indications favor anti-staphylococcal penicillins in Australian and UK outpatient settings.
- Sexually Transmitted Diseases:Syphilis treatment protocols reserve benzathine penicillin G for primary and secondary stages per WHO guidelines.
- Ear Infections:Pediatric otitis media applications concentrate in US and Japanese ambulatory clinics with narrow-spectrum preference.
- Dental Infections:Periapical abscess prophylaxis generates consistent demand through European and North American dental practice formularies.
Respiratory infections anchor volume; urinary tract infections are climbing the fastest on ambulatory expansion.
Dosage Form:
Route of administration determines manufacturing complexity, cold chain requirements, and margin structure across the value chain.
- Injectable Solutions:Sterile parenteral formulations require aseptic filling lines and dedicated beta-lactam manufacturing suites. Hospital procurement in the US, Japan, and Germany concentrates volumes with manufacturers holding FDA and EMA-approved sterile facility certifications.
- Oral Tablets:Solid dose manufacturing scales efficiently for high-volume generic markets. Indian producers at Hyderabad and Ahmedabad supply compressed amoxicillin tablets to African and Latin American tender markets.
- Capsules:Gelatin shell formulations dominate US retail pharmacy dispensing for adult outpatient prescriptions.
- Suspensions:Reconstitutable powders for pediatric dosing concentrate in European and North American community pharmacy channels.
- Powders:Bulk antibiotic powders serve veterinary and compounding pharmacy applications with specialized sourcing requirements.
- Creams:Topical fusidic acid-penicillin combinations target localized skin infections in UK and Australian dermatology practices.
Oral tablets dominate production scale; injectable solutions command premium positioning through facility certification barriers.
End User:
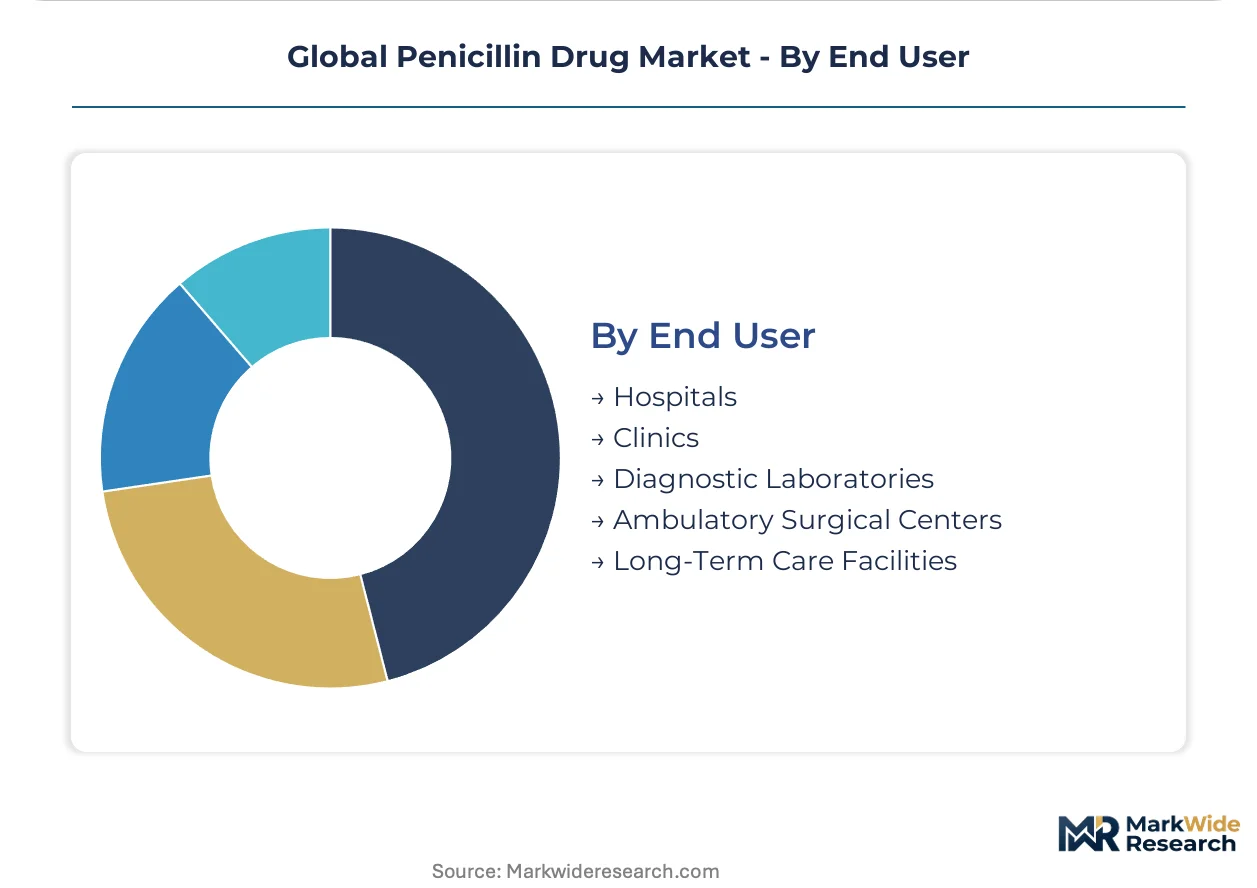
Institutional purchasing power and reimbursement frameworks segment demand across healthcare delivery settings.
- Hospitals:Tertiary care systems aggregate antibiotic procurement through centralized pharmacy and therapeutics committees. US health systems and NHS Trusts in England leverage formulary restrictions to steer prescribing toward narrow-spectrum agents with documented resistance stewardship benefits.
- Clinics:Outpatient diagnostic and treatment centers in Brazil, Mexico, and Indonesia generate rising prescription volumes for oral formulations.
- Diagnostic Laboratories:Reference labs in Germany, Japan, and the US stock penicillin derivatives for susceptibility testing panels and research applications.
- Ambulatory Surgical Centers:Prophylactic dosing for clean surgical procedures drives perioperative antibiotic consumption in US and European day-surgery networks.
- Long-Term Care Facilities:Nursing homes and skilled nursing facilities in the US and Canada face heightened regulatory scrutiny for antibiotic stewardship compliance.
Hospitals concentrate procurement scale; clinics are gaining share fastest on ambulatory care migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands fermentation capacity for penicillin G intermediates while India dominates finished dose exports, yet both face divergent regulatory pressures from FDA and EMA quality mandates.
United States
Hospital sepsis protocols sustain demand for injectable benzylpenicillin in ICU departments across tertiary care systems. FDA current Good Manufacturing Practice standards enforce dedicated beta-lactam manufacturing suites and cross-contamination prevention systems. New Jersey and North Carolina clusters host sterile parenteral filling operations serving domestic health system procurement.
China
Shandong and Hebei province fermentation facilities supply the majority of global 6-APA intermediates for downstream generic production. NMPA alignment with FDA quality metrics is accelerating facility retrofit investments for export certification. Zhejiang province producers are deploying membrane separation systems to meet REACH solvent discharge regulations for dichloromethane emissions.
India
Hyderabad and Visakhapatnam manufacturing hubs export compressed amoxicillin tablets to African and Latin American tender markets. CDSCO streamlined generic registration pathways support backward integration into 6-APA production for cost-competitive API supply. Ahmedabad solid dose facilities scale oral tablet manufacturing for high-volume community pharmacy channels.
Germany
EMA pharmacovigilance frameworks mandate post-market allergy surveillance that filters substandard producers from certified supply chains. Hospital formulary committees in Bavaria and North Rhine-Westphalia steer procurement toward narrow-spectrum agents with documented resistance stewardship benefits. Frankfurt and Munich clusters concentrate sterile injectable manufacturing for regulated European markets.
Brazil
ANVISA streamlined generic registration pathways are opening community pharmacy channels for oral aminopenicillin formulations in underserved interior states. Rising ambulatory care utilization in São Paulo and Minas Gerais drives prescription volumes for outpatient urinary tract infection therapies. Rio de Janeiro diagnostic laboratories stock penicillin derivatives for susceptibility testing panels.
Global Penicillin Drug Market Competitive Landscape
Chinese producers anchor the bulk API tier; Indian specialists hold finished dose manufacturing advantages. The vendor base concentrates around fermentation-derived intermediate supply and sterile parenteral certification. Three archetypes dominate: vertically integrated pharmaceutical conglomerates, generic API exporters with backward integration, and brand-dependent respiratory therapy specialists. Competitive moves center on fermentation yield improvements and facility quality upgrades for regulatory compliance.
Among US-based pharmaceutical conglomerates, Pfizer Inc. exemplifies scale advantages across fermentation and finished dose manufacturing. Indian generic specialists Aurobindo Pharma Ltd. and Lupin Ltd. occupy positions anchored by backward integration into 6-APA production and high-volume oral tablet exports to emerging markets. UK-headquartered GlaxoSmithKline plc represents brand-dependent positioning in respiratory infection segments across regulated markets.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Aurobindo Pharma Ltd. |
| GlaxoSmithKline plc |
| Sandoz |
| Teva Pharmaceutical Industries Ltd. |
| Cipla Ltd. |
| Sun Pharmaceutical Industries Ltd. |
| Lupin Ltd. |
| Centrient Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Hospital formulary consolidation around narrow-spectrum agents is compressing procurement budgets for finished dose manufacturers, forcing API suppliers to absorb fermentation input volatility while maintaining FDA and EMA certification tiers. This demand-side austerity stratifies pricing across facility-grade tiers, with sterile parenteral suites commanding substantial premiums over oral solid dose channels.
Pricing Analysis
Distributor margins for sterile injectable penicillin range from 15-25% in regulated markets, while generic oral tablet channels operate on compressed 5-12% markups. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified sterile facilities from EMA-aligned operations and non-certified bulk exporters. Pricing pressure stems from Indian and Chinese generic substitution in tender markets, with African and Latin American procurement showing highest price sensitivity and Japanese hospital systems demonstrating lowest.
Supply Chain Analysis
Refurbishment and revalidation of fermentation equipment flows from decommissioned European facilities to Indian and Chinese producers seeking rapid capacity scaling. Active pharmaceutical ingredient supply concentrates in China, India, and Hungary, with 6-APA intermediates drawing from corn steep liquor and soybean meal agricultural feedstocks. Single-region vulnerability in Shandong and Hebei province clusters exposes finished dose manufacturers to disruption. Distribution runs through hospital procurement consortia in regulated markets and government tender systems in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA pharmacovigilance framework expansion functions as a regulatory compounder, tightening certification barriers that filter substandard producers and consolidate procurement around quality-validated supply chains.
For Market Incumbents: Deploy fermentation yield optimization as the primary defensive lever. Incumbent manufacturers should accelerate automated bioreactor control investments in Hyderabad and Visakhapatnam clusters to match Chinese unit cost compression, while extending sterile facility certifications to capture hospital formulary consolidation. Cross-contamination prevention retrofits in multi-product facilities defend against emerging pure-play API specialists threatening margin structures. For New Entrants and Emerging Players: The 40-60% price-point gap between premium sterile injectables and economy oral tablets opens white-space targeting in Brazilian ambulatory care networks and Indonesian community pharmacy channels. New entrants should prioritize ANVISA streamlined registration pathways for oral aminopenicillin formulations in underserved interior states, leveraging contract manufacturing partnerships with established CDSCO-certified facilities to bypass capital-intensive fermentation buildouts. For Investors and Strategic Acquirers: Asymmetric upside sits with backward-integrated generic specialists possessing captive 6-APA production and FDA sterile facility dual-certification. Long-term viability over a multi-year horizon favors acquisition targets with demonstrated fermentation expertise and established hospital procurement relationships. Monitor antimicrobial stewardship program expansion rates in US health systems as the critical inflection signal for narrow-spectrum penicillin demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Automated bioreactor deployments in Zhejiang province compress penicillin G intermediate unit costs for export markets. |
| Sterile Facility Certification | FDA and EMA dual-certification unlocks hospital procurement contracts in US, German, and Japanese tertiary care systems. |
| Backward Integration into 6-APA | Captive intermediate production insulates margins from Shandong supply concentration and agricultural input volatility. |
| Combination Therapy Development | Beta-lactamase inhibitor pairings capture urinary tract infection segments where resistance patterns favor synergistic mechanisms. |
| Continuous Manufacturing Adoption | Integrated processing reduces FDA cross-contamination audit risks and accelerates batch release timelines for hospital sepsis protocols. |
Research Methodology
Multiple input streams — primary interviews with fermentation operations directors, regulatory affairs leads at Indian and Chinese API exporters, hospital formulary committee members, and EMA pharmacovigilance officers, alongside secondary validation through FDA inspection databases, EMA submission records, CDSCO registration filings, and customs trade data — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across supply-side capacity assessments and demand-side procurement patterns informed analytical frameworks spanning product type, therapy area, dosage form, end user, and regional regulatory cluster segmentation throughout the projection horizon. CAGRs were derived from modeled fermentation capacity expansion trajectories, hospital sepsis protocol adoption curves, and antimicrobial stewardship program penetration rates.
Caveats apply where EMA REACH solvent discharge enforcement, NMPA-FDA quality alignment acceleration, or antimicrobial resistance substitution thresholds could materially shift the outlook. Practitioners should monitor corn steep liquor commodity price indices and hospital formulary narrow-spectrum preference rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Casein and Casein Derivatives Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Calcium Gluconate Market