
 Healthcare HR Software Market | 2026-2036
Healthcare HR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare HR Software Market Foresight
Buyer concentration among hospital networks is shifting as regional health systems merge into multi-state enterprises. Workday sustains R&D intensity in enterprise-grade workforce analytics for the largest integrated delivery networks. BambooHR specializes in mid-market clinic groups that need rapid deployment without dedicated IT staff. Paycor anchors its position through deep payroll-tax compliance automation that reduces administrative burden for multi-location operators.
Healthcare HR software comprises integrated digital platforms that manage workforce lifecycle operations across clinical and non-clinical personnel, typically incorporating credential verification, shift scheduling algorithms, and benefits administration modules. These systems serve primarily to ensure continuous staffing compliance while reducing labor cost leakage in high-turnover clinical environments. Cloud-based deployment leads structural adoption as hospitals migrate away from capital-intensive on-premises infrastructure, while SaaS pricing models capture expanding margin pools among smaller clinic buyers. Recruitment software represents the fastest-growing product segment as acute nursing shortages force proactive talent pipelining, whereas performance management modules remain comparatively mature with slower replacement cycles.
FDA oversight of clinical trial workforce documentation and HIPAA privacy requirements shape product development priorities for vendors serving research hospitals. OSHA injury reporting mandates and state-specific nurse-to-patient ratio laws further drive demand for automated scheduling and incident-tracking functionality. Stakeholders must monitor how evolving CMS conditions of participation for hospitals reshape the mandatory feature sets that software procurement committees require.
Market Dynamics
Hospital system consolidation is compressing vendor ecosystems toward unified talent platforms that span credentialing, scheduling, and compliance across merged entities. This concentration pressure forces mid-market vendors to specialize or exit.
Growth Catalysts
- HIPAA Security Rule enforcement:The Department of Health and Human Services has intensified audit frequency for workforce access controls, compelling hospitals to automate user provisioning and de-provisioning workflows.
- Clinical labor shortages:Acute nursing gaps in tertiary care centers are driving demand for predictive scheduling algorithms that optimize float pools across emergency departments and surgical units.
- Cloud migration:Capital-constrained community hospitals are abandoning on-premises HRIS installations in favor of SaaS deployments that eliminate server maintenance and disaster recovery overhead.
Market Restraints
- Interoperability friction:Legacy payroll systems from the 1990s lack API connectivity, forcing expensive middleware development for data synchronization with modern HR platforms.
- Implementation timeline risk:Multi-hospital rollouts frequently exceed 18 months due to union contract negotiation requirements and state-by-state tax configuration complexity.
- Specialized talent scarcity:Health system IT departments struggle to recruit analysts who understand both clinical staffing workflows and HR technology configuration.
Strategic Opportunities
- Contingent workforce expansion:Travel nurse agencies and per-diem staffing platforms represent an underserved buyer segment requiring vendor management system integration.
- Behavioral health integration:Psychiatric facilities and addiction treatment centers operate under distinct state licensing frameworks that generic HR software fails to address.
- Artificial intelligence convergence:Machine learning models trained on turnover patterns can predict resignation risk six months ahead, enabling proactive retention interventions.
Industry Challenges
- Multi-state compliance complexity:Health systems operating across California, Texas, and New York must reconcile conflicting overtime calculation rules and mandatory break regulations in a single platform instance.
- Credential verification latency:Primary source verification for physician privileges still requires manual outreach to medical schools and licensing boards, creating onboarding bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare HR Software Market |
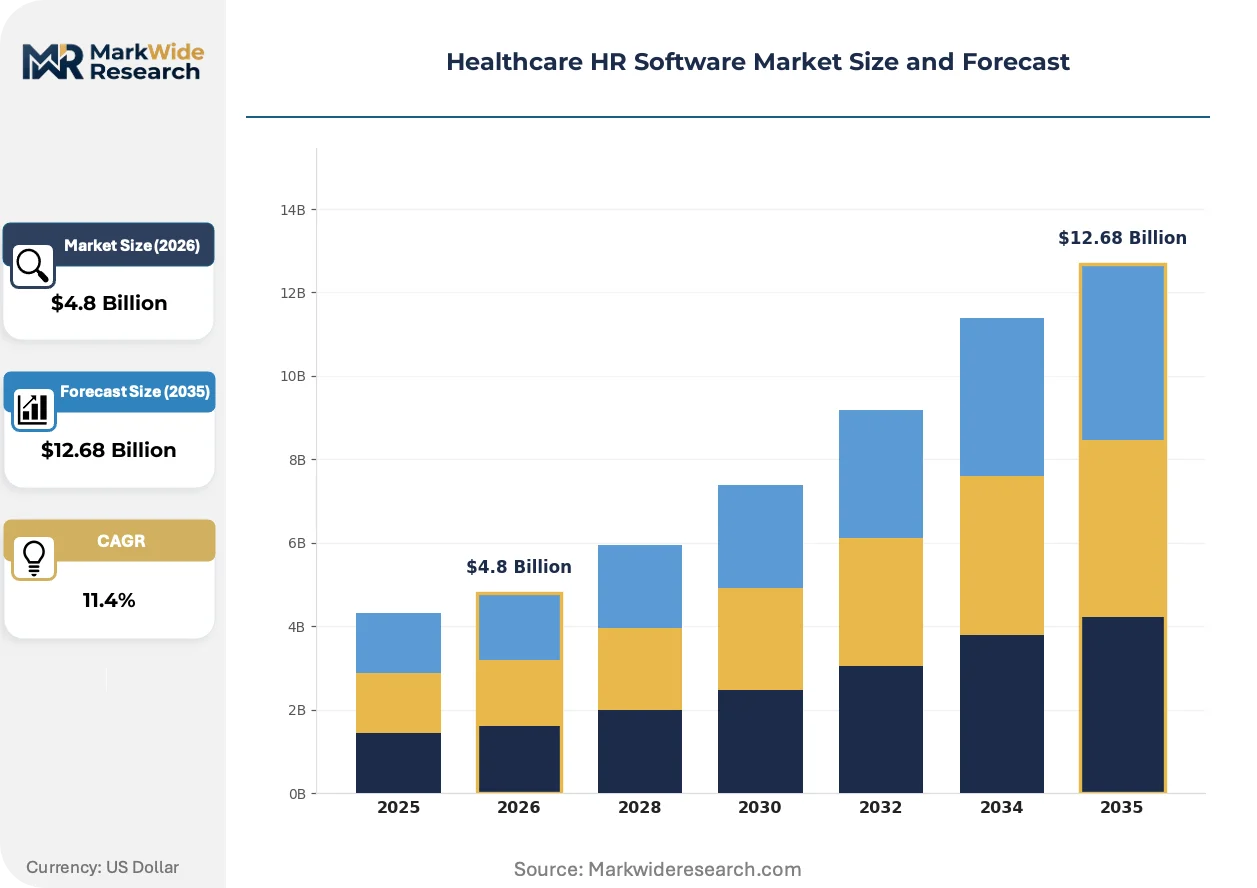
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recruitment Software, Payroll Management, Performance Management, Employee Scheduling Technology: Cloud-Based, On-Premises, Mobile Solutions, SaaS End User: Hospitals, Clinics, Long-Term Care Facilities, Home Healthcare Providers Application: Talent Acquisition, Employee Engagement, Compliance Management, Training & Development |
| Companies Covered | ADP Workforce Now, BambooHR, Paycor, Gusto, Paylocity, Workday, Rippling, UKG Ready, SAP SuccessFactors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare HR Software Market Shifts & Advancements
Workforce management technology is pivoting from administrative record-keeping toward predictive intelligence that anticipates staffing gaps before they impact patient care. This shift reconfigures vendor competitive advantage around data science capabilities rather than feature breadth.
Natural language processing is rewriting how clinical managers interact with scheduling systems. Voice-enabled shift-swapping and absence reporting reduce friction for bedside nurses who lack desktop access. Large health systems in the Upper Midwest are piloting these interfaces in medical-surgical units. The technology is compressing training time for new charge nurses from weeks to days.
OSHA's updated injury reporting requirements for healthcare settings are forcing real-time incident documentation into mobile-first workflows. Hospitals must now capture needlestick exposures and patient violence events within four hours to maintain compliance. Emergency departments and psychiatric units face the steepest operational adjustment as they retrofit paper-based safety protocols with digital capture tools.
Subscription pricing for workforce analytics is displacing perpetual license models among mid-market buyers. Chief nursing officers now demand outcome-based contracts tied to measurable reductions in agency labor spending. This preference shift is most visible in the Southeastern United States, where private equity-backed hospital groups are standardizing procurement across dozens of acquired facilities.
Healthcare HR Software Market Segmentation
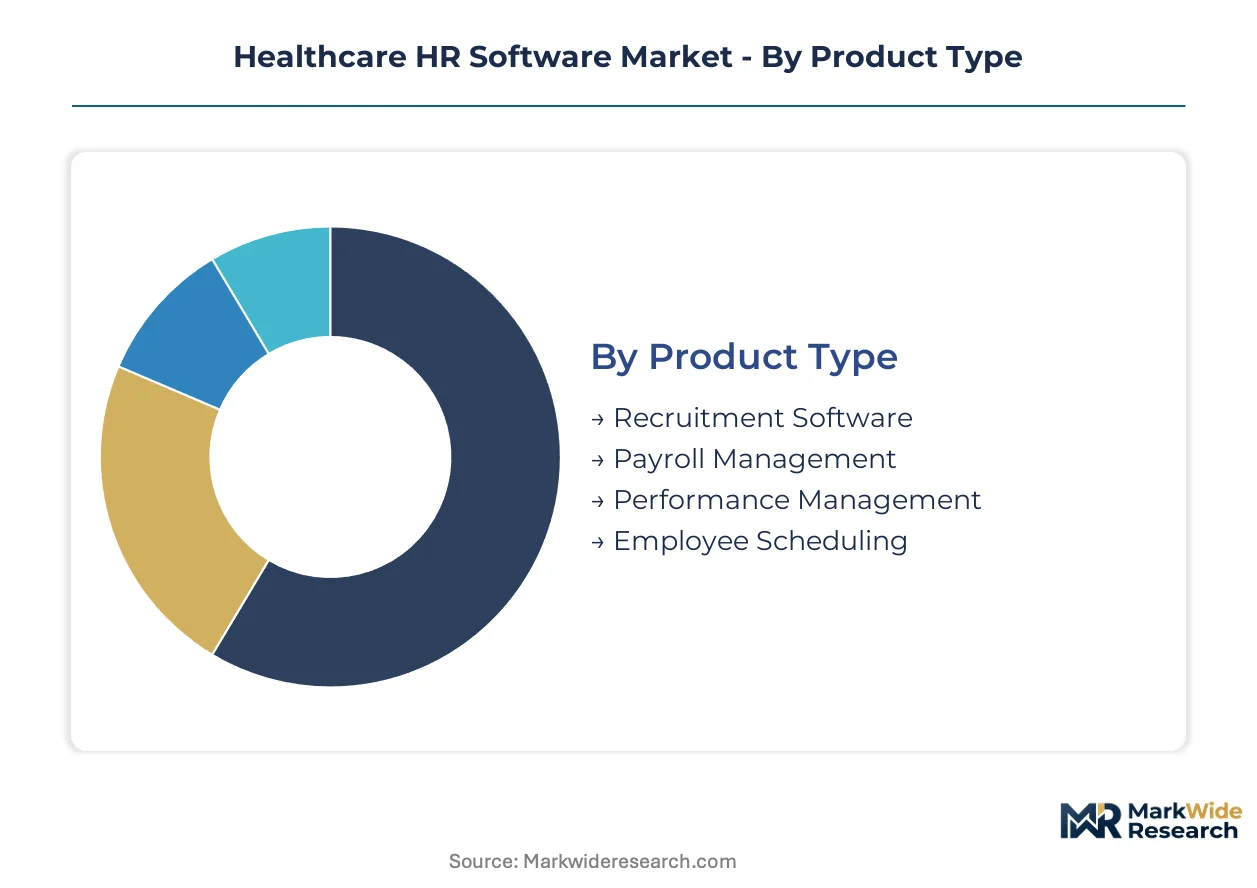
Segmentation in healthcare HR software determines which compliance frameworks vendors must embed and which procurement committees control budget allocation. Hospital networks prioritize segments that automate credential verification and scheduling compliance across merged entities.
Product Type:
HIPAA Security Rule enforcement and state nurse staffing mandates create divergent certification burdens across product categories, with audit-intensive modules requiring SOC 2 Type II attestation and FDA documentation capabilities for research hospital deployments.
- Recruitment Software:Predictive talent pipelining platforms incorporating AI-driven candidate matching and automated license verification. Demand concentrates in tertiary care centers across Texas and California where acute nursing shortages force proactive sourcing. HIPAA-compliant candidate data handling and OFCCP affirmative action tracking represent mandatory feature sets.
- Payroll Management:Multi-jurisdiction tax engines with automated overtime calculation for unionized clinical workforces. Hospital networks in New York and Illinois prioritize this segment to reconcile conflicting state break regulations and prevailing wage requirements in a single platform instance.
- Performance Management:Competency-based evaluation frameworks tracking clinical skill maintenance and continuing education compliance.
- Employee Scheduling:Algorithm-driven shift optimization with float pool management across emergency departments and surgical units.
Leading the category by volume: Payroll Management. Growing fastest: Recruitment Software.
Technology:
Deployment architecture dictates capital expenditure profiles and IT staffing requirements, with cloud migration accelerating among community hospitals that lack dedicated infrastructure teams.
- Cloud-Based:Scalable SaaS infrastructure eliminating on-premises server maintenance and disaster recovery overhead. Regional health systems in the Southeastern United States favor this model for rapid standardization across acquired facilities. SOC 2 compliance and business associate agreements under HIPAA govern vendor selection.
- Mobile Solutions:Voice-enabled interfaces and real-time incident capture for bedside nurses lacking desktop access. Psychiatric units and emergency departments in the Upper Midwest pilot these tools to compress safety documentation timelines under OSHA's four-hour reporting window.
- On-Premises:Legacy installations retained by research hospitals with specialized data sovereignty requirements.
- SaaS:Subscription pricing models with outcome-based contracts tied to measurable agency labor reductions.
Dominating deployment decisions: Cloud-Based. Expanding most quickly: Mobile Solutions.
End User:
Facility type determines workflow complexity and regulatory exposure, with acute care settings demanding the most sophisticated compliance automation.
- Hospitals:Enterprise-grade platforms spanning credentialing, scheduling, and compliance across multi-state integrated delivery networks. Consolidation among health systems in California, Texas, and Florida drives demand for unified talent platforms that eliminate redundant vendor relationships.
- Long-Term Care Facilities:Specialized modules addressing state-specific staffing ratio mandates and Medicaid reimbursement documentation. Facilities across Ohio and Pennsylvania prioritize automated timesheet validation to ensure compliance with CMS conditions of participation.
- Clinics:Rapid-deployment solutions for mid-market physician groups without dedicated IT staff.
- Home Healthcare Providers:Mobile-first workforce management for distributed clinical staff across patient residences.
Commanding largest procurement budgets: Hospitals. Climbing the fastest: Long-Term Care Facilities.
Application:
Functional use case shapes integration requirements with existing clinical systems and determines which stakeholder group controls purchasing decisions.
- Compliance Management:Automated tracking of workforce access controls, license expiration alerts, and incident documentation workflows. Research hospitals serving FDA-regulated clinical trials require this application to maintain workforce documentation integrity. Chief nursing officers in Massachusetts and Washington champion these investments following intensified HHS audit frequency.
- Talent Acquisition:End-to-end recruitment automation from requisition to onboarding with primary source verification integration. Multi-state health systems deploy this application to reduce physician onboarding bottlenecks caused by manual medical school outreach.
- Employee Engagement:Pulse surveys and retention analytics predicting resignation risk six months ahead.
- Training & Development:Competency tracking and continuing education management for clinical certification maintenance.
Highest procurement priority: Compliance Management. Gaining share fastest: Talent Acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud computing infrastructure concentrated in Virginia's data center corridor and Oregon's Columbia River basin underpins SaaS deployment capacity for healthcare HR platforms across North American hospital networks.
United States
Multi-state health system mergers in California, Texas, and Florida drive procurement of unified talent platforms that eliminate redundant vendor relationships. HIPAA Security Rule enforcement by HHS intensifies audit frequency for workforce access controls. The Dallas-Fort Worth metroplex anchors deployment of predictive scheduling algorithms across tertiary care centers managing acute nursing shortages.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia prioritize credential verification automation to reduce physician onboarding bottlenecks. The EU AI Act shapes compliance requirements for machine learning models in workforce analytics. Berlin's Charité hospital system pilots voice-enabled scheduling interfaces for medical-surgical units.
United Kingdom
NHS trust consolidation pressures mid-market vendors toward specialized compliance modules for unionized clinical workforces. GDPR mandates govern cross-border data flows for cloud-based HR platforms serving research hospitals. London's Guy's and St Thomas' NHS Foundation Trust leads adoption of outcome-based contracts tied to agency labor reduction targets.
India
Hospital chains in Maharashtra and Karnataka deploy rapid-deployment SaaS solutions to manage distributed clinical staff across tier-2 and tier-3 cities. The Digital India initiative accelerates cloud migration among capital-constrained community hospitals. Hyderabad's medical technology corridor attracts vendor R&D investment for mobile-first workforce management tools.
Australia
State health departments in New South Wales and Victoria mandate automated scheduling compliance with nurse-to-patient ratio laws. The Therapeutic Goods Administration oversees clinical trial workforce documentation for research hospitals. Melbourne's Alfred Health network standardizes procurement across acquired facilities using subscription-based workforce analytics.
Healthcare HR Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in contingent workforce management and behavioral health specialization. The vendor ecosystem compresses toward integrated platforms spanning credentialing, scheduling, and compliance. Three archetypes dominate: enterprise-grade workforce analytics providers, mid-market rapid-deployment specialists, and payroll-tax compliance automators. Consolidation pressure forces M&A activity among mid-tier players while cloud-native entrants capture margin pools in mobile-first deployment.
Within the enterprise analytics tier, Workday occupies a position exemplifying R&D intensity for integrated delivery networks. BambooHR and Paycor represent mid-market archetypes—BambooHR anchoring rapid-deployment solutions for clinic groups without dedicated IT staff, Paycor sitting within the payroll-tax compliance specialization that reduces administrative burden for multi-location operators.
| Leading Market Players |
|---|
| ADP Workforce Now |
| BambooHR |
| Paycor |
| Gusto |
| Paylocity |
| Workday |
| Rippling |
| UKG Ready |
| SAP SuccessFactors |
| Others |
Supply & Pricing Matrix
Vertical integration into cloud infrastructure anchors both supply security and pricing power for healthcare HR software vendors serving multi-state hospital networks. Captive data center capacity in Virginia's data center corridor and Oregon's Columbia River basin insulates platform providers from third-party hosting volatility while supporting premium SaaS pricing tiers.
Pricing Analysis
Warranty and service bundling separates enterprise-grade implementations from stripped-down mid-market offerings. Three-tier pricing structure across premium, standard, and economy levels reflects SOC 2 Type II certification status and dedicated implementation support. HIPAA Security Rule audit intensity is compressing margins in the economy tier as buyers demand compliance automation previously reserved for premium contracts. Community hospitals without dedicated IT staff exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over license fees.
Supply Chain Analysis
Regional distribution centers in Virginia, Oregon, and Texas anchor hub-and-spoke deployment patterns for cloud-based healthcare HR platforms. Software development talent concentrates in Hyderabad's medical technology corridor, Seattle's enterprise software cluster, and Berlin's health informatics hub. The supply chain draws from specialized clinical workflow analysts, HIPAA compliance auditors, and healthcare data scientists. Single-source vulnerability in primary source verification services for physician credentialing creates onboarding bottlenecks. Distribution runs through direct enterprise sales teams serving hospital networks and channel partners reaching mid-market clinic groups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare HR software sits in a technology-transition phase as predictive analytics and voice-enabled interfaces displace legacy administrative record-keeping systems.
For Market Incumbents: Hedge against cloud-native entrants by acquiring mobile-first workforce management specialists and deepening integration with electronic health record platforms. Consolidation pressure from hospital system mergers demands unified talent platforms spanning credentialing, scheduling, and compliance. Capacity expansion in behavioral health specialization addresses an underserved segment operating under distinct state licensing frameworks. For New Entrants and Emerging Players: AI-driven resignation risk prediction offers a technology-first wedge into retention analytics for health systems battling nursing turnover. Contingent workforce management for travel nurse agencies represents the most penetrable white-space target, lacking vendor management system integration from incumbent platforms. A channel partnership strategy with per-diem staffing platforms accelerates customer acquisition without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by enterprise software consolidators seeking healthcare vertical depth. Long-term viability hinges on data science capabilities rather than feature breadth, favoring targets with machine learning infrastructure and clinical workflow expertise. Watch for intensified HHS audit frequency as an inflection indicator accelerating compliance automation procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies credentialing, scheduling, and compliance across merged hospital networks in California and Texas. |
| Acquisition of Specialist Firm | Captures behavioral health workflow expertise for psychiatric facilities under distinct state licensing. |
| Product Launch | Introduces voice-enabled shift-swapping for bedside nurses lacking desktop access in Upper Midwest pilots. |
| Strategic Partnership | Links predictive scheduling algorithms with travel nurse agency platforms for float pool optimization. |
| Geographic Expansion | Establishes presence in Maharashtra and Karnataka hospital chains through rapid-deployment SaaS models. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contracts, and CMS Medicare data underwrites the qualitative findings. Primary interviews with chief nursing officers, health system IT directors, HR technology procurement committees, and biomedical engineers informed workflow requirements and compliance priorities. Secondary validation drew from hospital procurement databases, GPO contract filings, HHS audit disclosure reports, and state nurse staffing mandate documentation. Bottom-up facility-level deployment estimates triangulate against top-down vendor revenue segmentation across product categories.
Comparable-period anchoring to historical SaaS adoption curves in healthcare settings structured the forecast window. The projection horizon spans cloud deployment models, organization size tiers, vertical specializations, and regional adoption patterns. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs include health system merger velocity, HIPAA audit frequency trajectories, and nursing shortage severity indices by metropolitan statistical area.
Several conditions sit outside the modeled scope, including single-hospital implementations below fifty beds, non-healthcare verticals served by generalist HR platforms, and hardware-dependent workforce management systems. Forecasts reflect documented assumptions about cloud migration pace and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Global Healthcare Revenue Cycle Management Market
Healthcare IT
Clinical Perinatal Software Market
Healthcare IT
Global Cancer Registry Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Pharmaceutical Software Market
Healthcare IT
Healthcare Credentialing Software Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Global Accountable Care Solutions Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
North American Dental Software Market
Healthcare IT
United States Pharmacy Management System Market
Healthcare IT
Europe Outpatient Software Market