
 Veterinary Dental Software Market | 2026-2036
Veterinary Dental Software Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Dental Software Market Insights
North American veterinary technology infrastructure is expanding. IDEXX Laboratories leverages deep diagnostics integration to anchor cloud-based dental workflows across companion animal practices. Henry Schein sustains distribution dominance through captive supply of hardware-software bundles. Covetrus competes on multi-vendor platform openness, allowing third-party imaging devices to connect without proprietary lock-in.
Veterinary dental software encompasses digital platforms that capture, store, and analyze oral health data for non-human patients, typically supporting DICOM-compliant image formats and integrating with anesthesia monitoring hardware to track vital signs during procedures. Its primary commercial purpose is to replace film-based radiography and paper charting, reducing retake rates while creating retrievable longitudinal records for periodontal treatment planning. Patient Management systems currently dominate installed bases as legacy practice management vendors embed dental modules into existing workflows. Cloud-Based deployment represents the fastest-expanding configuration, particularly among veterinary hospital networks seeking centralized data governance across geographically dispersed sites. Dental Imaging commands concentrated margin pools due to perpetual licensing structures for advanced 3D reconstruction and cephalometric analysis tools.
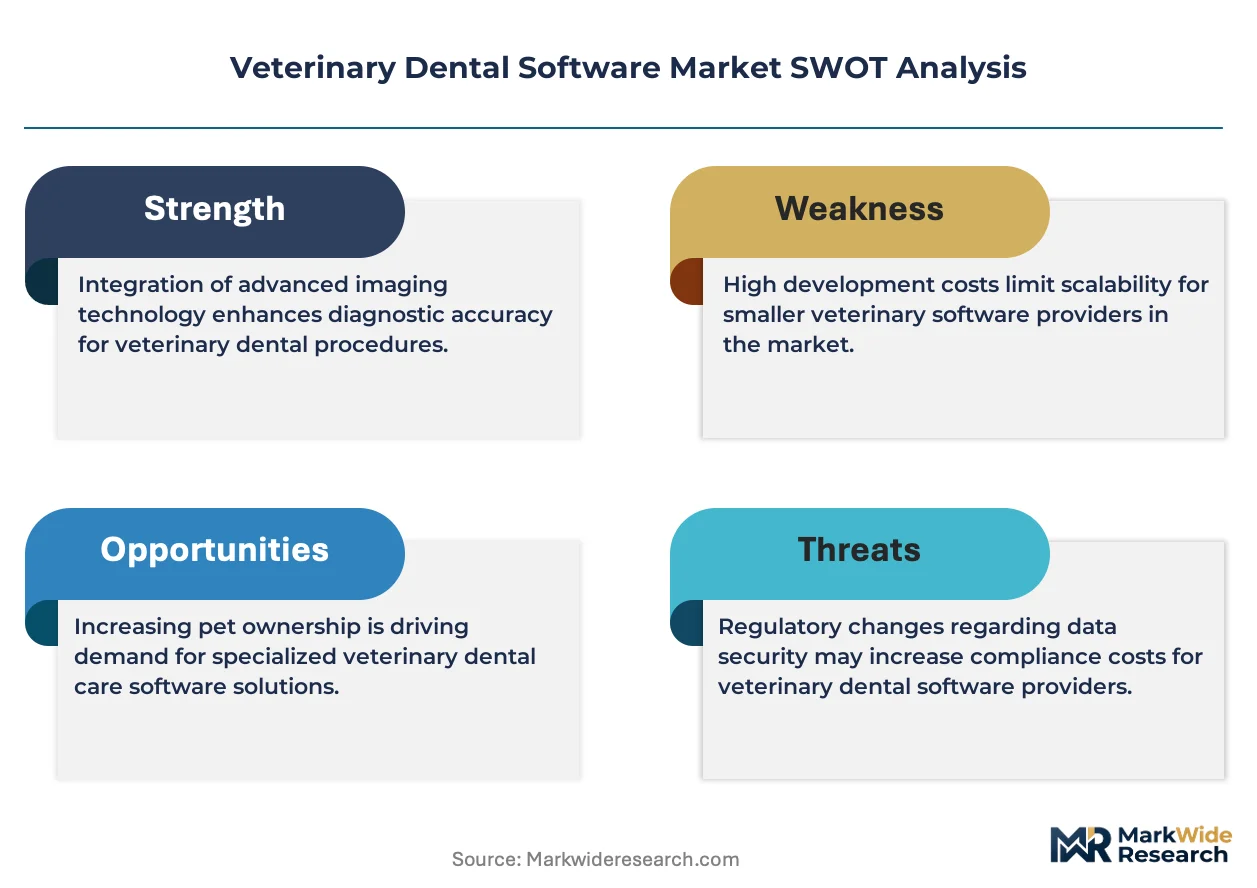
FDA 510(k) clearance requirements for software-as-medical-device modules shape product development timelines and commercial launch sequencing for vendors targeting US veterinary practices. The EU MDR and CE marking obligations extend compliance burdens for European deployments, particularly for cloud-hosted platforms processing patient data across borders. ISO 13485 quality management standards govern development processes for imaging algorithm components, creating certification barriers for smaller entrants. Stakeholders must monitor regulatory divergence between human and veterinary medical device classifications as jurisdictions reassess whether dental software falls under companion animal or human-equipment oversight frameworks.
Market Dynamics
Cloud migration is compressing deployment cycles across veterinary hospital networks, forcing legacy on-premise vendors to rearchitect their platforms for multi-tenant SaaS delivery or cede share to native cloud entrants.
Growth Catalysts
- Consolidation of multi-site practices:Corporate veterinary groups in the United States are mandating standardized dental imaging platforms across acquired locations, creating fleet-scale software procurement.
- FDA 510(k) pathway clarity:The US regulator's guidance on software-as-medical-device classification has reduced approval uncertainty for veterinary dental algorithms, accelerating commercial launches.
- AI-powered pathology detection:Machine learning models trained on DICOM dental radiographs are reducing diagnostic time for periodontal disease screening in high-volume companion animal clinics.
Market Restraints
- Capital intensity of hardware bundles:Digital radiography sensors and intraoral scanners require substantial upfront investment, stretching payback periods for independent practices.
- Veterinary specialist shortage:The limited pipeline of board-certified veterinary dentists constrains procedure volume and software utilization rates in general practice settings.
- Cross-border data friction:EU MDR requirements for cloud-hosted platforms processing patient records across member states create compliance overhead for vendors.
Strategic Opportunities
- Equine dental specialization:Large animal practices represent an underpenetrated vertical where dental software adoption lags companion animal standards by nearly a decade.
- Telemedicine integration:Remote consultation workflows connecting general practitioners with veterinary dental specialists are opening subscription revenue streams for platform vendors.
- US IRA veterinary provisions:Inflation Reduction Act allocations for rural veterinary service expansion include technology infrastructure grants eligible for dental software procurement.
Industry Challenges
- DICOM interoperability gaps:Inconsistent implementation of imaging standards between hardware manufacturers forces costly custom integration work.
- Anesthesia monitoring integration complexity:Synchronizing dental software with multi-parameter vital sign devices requires proprietary protocol development that delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Dental Software Market |
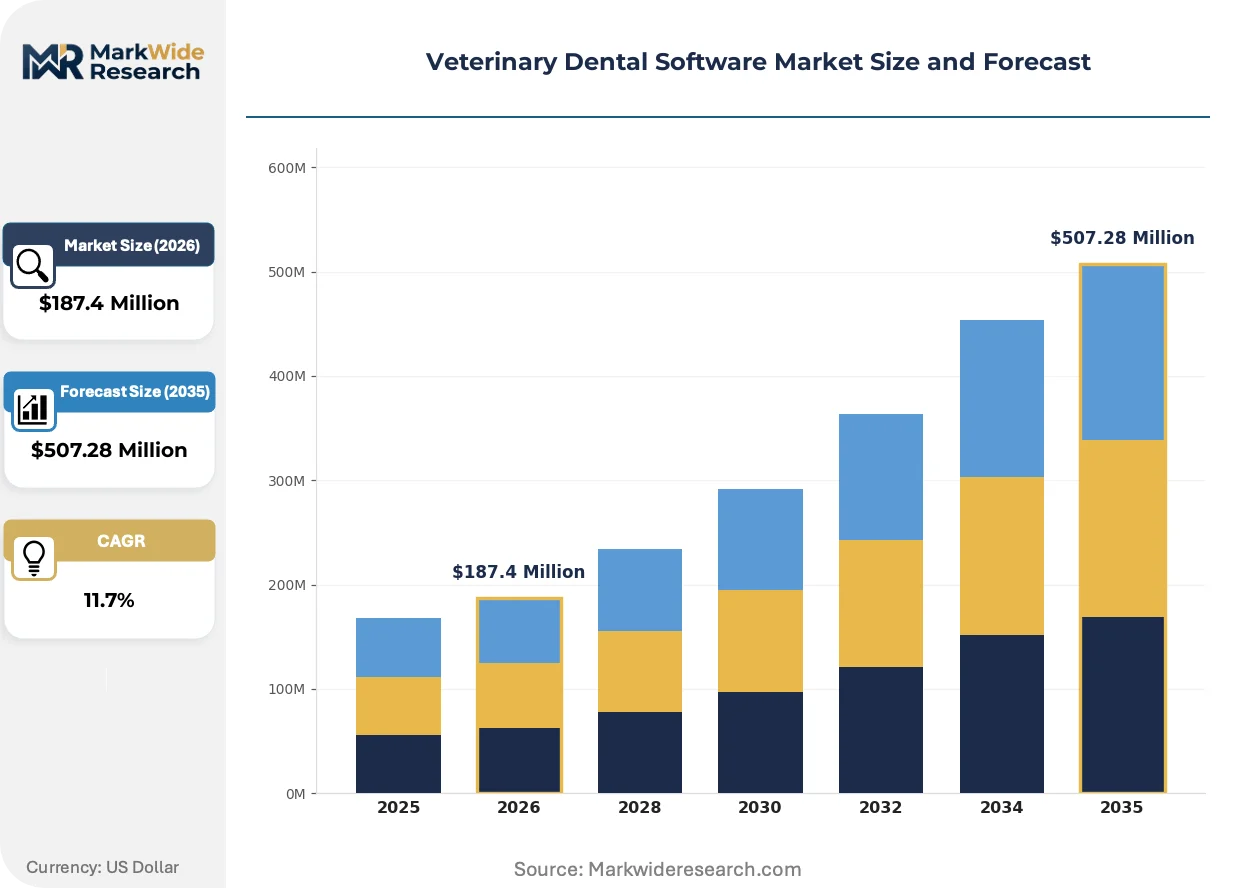
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiology Software, Patient Management, Dental Imaging, Inventory Management End User: Animal Clinics, Veterinary Hospitals, Mobile Veterinarians, Research Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Remote Access Feature: Digital X-Ray, Treatment Planning, Anesthesia Monitoring, Client Communication |
| Companies Covered | IDEXX Laboratories, Covetrus, Henry Schein, Patterson Companies, Carestream Health, Nordhealth, DaySmart Software, Animal Intelligence Software, Antech Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Dental Software Market Trends and Innovations
Artificial intelligence is penetrating diagnostic workflows at the point of care, shifting competitive advantage from image capture quality to algorithmic interpretation accuracy and clinical decision support integration.
Machine learning models for radiographic pathology detection are expanding into real-time chairside assistance, flagging periodontal bone loss and tooth resorption during image review. Specialty referral hospitals in North American metropolitan corridors are adopting these tools fastest, compressing the diagnostic loop from image acquisition to treatment planning. The technology is expanding into general practice workflows as cloud inference costs decline and API integration simplifies.
EU MDR Article 10 quality management mandates are elevating documentation burdens for software vendors seeking CE marking, particularly for cloud platforms hosting patient data across multiple jurisdictions. Vendors are responding by segregating European data infrastructure and appointing authorized representatives within the trading bloc. This regulatory friction is advantaging larger platforms with dedicated compliance functions over smaller entrants.
Subscription pricing for advanced imaging modules is displacing perpetual license models among corporate veterinary groups seeking predictable opex structures. Multi-site hospital chains are negotiating enterprise agreements that bundle dental software with practice management systems and diagnostics platforms. This procurement consolidation is most visible in US metropolitan corridors where private equity-backed practice aggregators dominate acquisition activity.
Veterinary Dental Software Market Segmentation
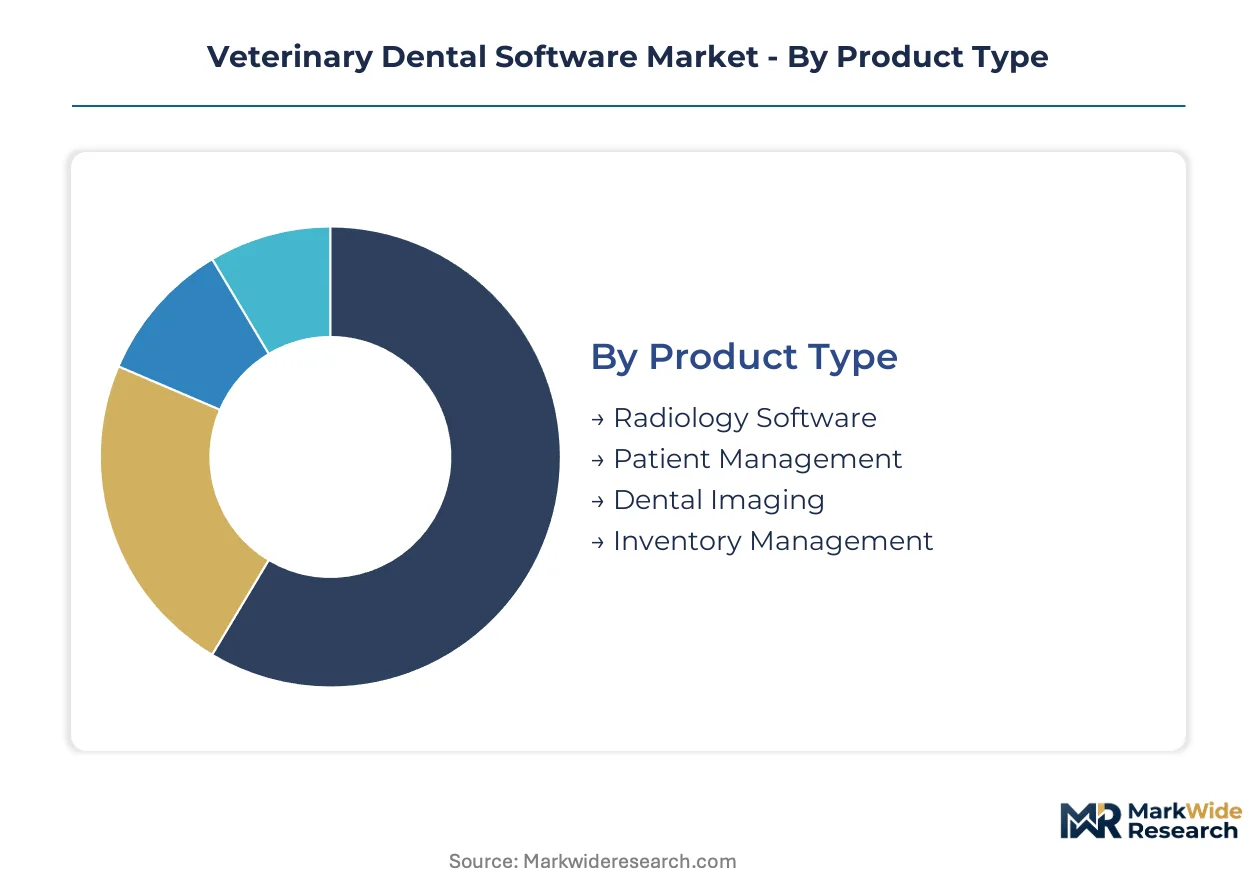
Veterinary dental software segments reflect divergent technology refresh cycles across practice types. Corporate buyers prioritize integrated platforms while independent operators favor modular upgrades. Understanding these segment dynamics reveals where procurement budgets concentrate and which configurations face replacement pressure.
Product Type:
Upgrade cycles vary sharply across product categories, with legacy systems facing displacement as cloud-native alternatives mature.
- Patient Management:Embedded modules within practice management systems handle appointment scheduling, dental charting, and billing integration. Demand concentrates in US metropolitan veterinary corridors where multi-site hospital chains mandate standardized workflows across acquired locations, driven by private equity-backed consolidation requiring fleet-scale software procurement.
- Dental Imaging:Platforms capturing DICOM-compliant radiographs with advanced 3D reconstruction and cephalometric analysis capabilities command concentrated margin pools through perpetual licensing structures. Specialty animal clinics in North American metropolitan areas drive adoption as they replace film-based radiography to reduce retake rates and enable longitudinal periodontal treatment planning.
- Radiology Software:Specialized modules for image interpretation and diagnostic reporting with AI-assisted pathology detection.
- Inventory Management:Dental supply tracking systems integrated with procurement workflows and vendor ordering portals.
Volume placements concentrate in Patient Management; the faster expansion belongs to Dental Imaging.
End User:
Customer type determines pricing tolerance and integration complexity, with institutional buyers negotiating enterprise terms against solo practitioners seeking pay-as-you-scale models.
- Veterinary Hospitals:Multi-site corporate groups and specialty referral centers deploy comprehensive platforms with anesthesia monitoring integration and telemedicine connectivity. These institutions in US metropolitan corridors drive cloud migration fastest, seeking centralized data governance across geographically dispersed sites.
- Animal Clinics:Independent and small-group companion animal practices represent the largest installed base but face capital constraints on hardware-software bundles. Clinics in suburban North American markets show growing interest in subscription models that convert upfront capex to predictable opex.
- Mobile Veterinarians:Equine and large animal practitioners requiring field-deployable imaging with offline synchronization capabilities.
- Research Institutions:Academic veterinary medical centers utilizing dental software for longitudinal studies and teaching case repositories.
Procurement volume clusters with Veterinary Hospitals; Animal clinics show the steepest expansion trajectory as cloud pricing democratizes access.
Deployment:
Infrastructure configuration choices reflect data sovereignty requirements and IT staffing levels across practice scales.
- Cloud-Based:Multi-tenant SaaS platforms with automatic updates, remote accessibility, and vendor-managed security patching. Veterinary hospital networks across the United States adopt this configuration fastest, compelled by centralized governance needs and reduced IT overhead.
- On-Premise:Locally installed servers maintaining physical control over patient records and imaging archives. Independent practices in jurisdictions with strict data localization requirements retain preference for this model despite higher maintenance burdens.
- Hybrid:Mixed architectures keeping sensitive imaging data local while leveraging cloud analytics and backup services.
- Remote Access:Thin-client and VPN-enabled solutions for specialists consulting across multiple practice locations.
Cloud-Based deployments capture the fastest-growing share; Hybrid configurations gain traction among mid-size groups navigating compliance complexity.
Feature:
Functional module prioritization reveals where practices extract operational value and which capabilities drive replacement decisions.
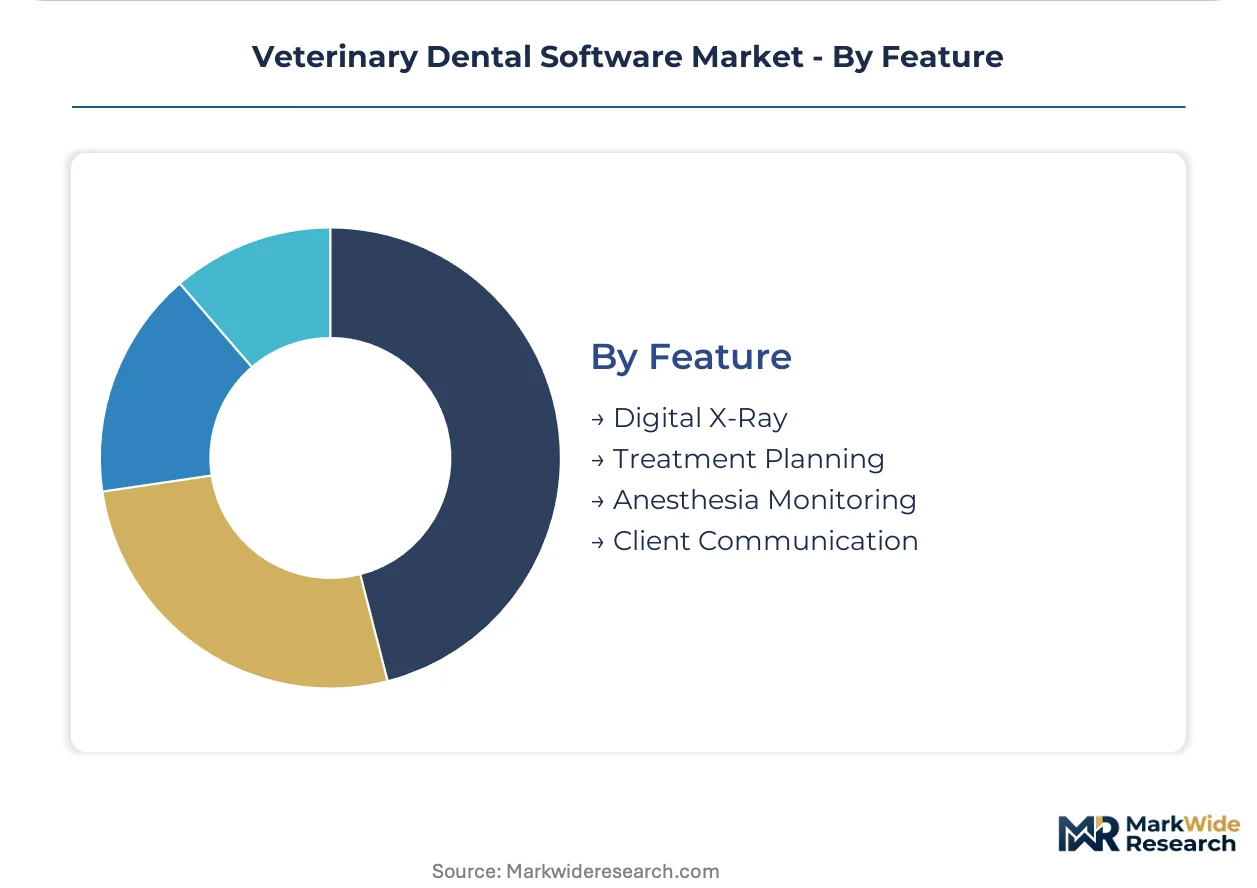
- Digital X-Ray:Sensor-based radiography replacing film with immediate image acquisition, enhancement tools, and DICOM storage. High-volume companion animal clinics prioritize this capability to compress diagnostic loops and reduce anesthesia exposure time.
- Treatment Planning:Visual tools for periodontal staging, extraction sequencing, and client education with 3D modeling. Specialty referral hospitals leverage these features to document clinical reasoning and facilitate owner consent discussions.
- Anesthesia Monitoring:Integration with multi-parameter vital sign devices tracking patient status during dental procedures.
- Client Communication:Automated appointment reminders, home care instructions, and image-sharing portals for owner engagement.
Digital X-Ray modules dominate current procurement; Treatment Planning is climbing the fastest as AI-assisted diagnostics mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's veterinary technology corridor anchors cloud software development for companion animal practices, while metropolitan veterinary clusters in Boston and London drive clinical validation of AI-assisted diagnostics.
United States
Private equity-backed veterinary hospital chains in Texas and Florida mandate standardized dental imaging platforms across acquired locations, consolidating procurement at fleet scale. FDA 510(k) clearance pathways for software-as-medical-device modules reduce regulatory uncertainty for algorithm developers. The Dallas-Fort Worth metroplex hosts dense concentrations of multi-site specialty practices deploying cloud-native platforms with centralized data governance.
Germany
EU MDR Article 10 quality management mandates elevate documentation burdens for vendors seeking CE marking on cloud-hosted platforms. The country's national pharmaceutical regulator enforces strict patient data localization requirements for cross-border imaging archives. Munich's veterinary specialty corridor drives adoption of DICOM-compliant systems with integrated anesthesia monitoring for high-volume referral hospitals.
United Kingdom
Corporate veterinary groups in Greater London negotiate enterprise SaaS agreements bundling dental software with practice management systems. GDPR compliance requirements shape vendor selection for platforms processing pet owner records across dispersed clinic networks. The Southeast England veterinary technology cluster concentrates development of telemedicine modules connecting general practitioners with dental specialists.
Japan
PMDA consultation pathways clarify software-as-medical-device classifications for veterinary dental algorithms, accelerating commercial launches. METI innovation grants support AI-powered pathology detection tools for companion animal clinics. Tokyo's metropolitan veterinary corridor leads adoption of real-time chairside diagnostic assistance in specialty referral hospitals.
Australia
TGA guidance documents distinguish veterinary medical device oversight from human-equipment frameworks, reducing regulatory friction for cloud platform vendors. Rural veterinary service expansion programs include technology infrastructure grants eligible for dental software procurement. Sydney's specialty animal hospitals drive demand for advanced 3D reconstruction and cephalometric analysis capabilities.
Veterinary Dental Software Market Competitive Landscape
Global majors compete with regional champions across cloud deployment architectures, with consolidated procurement power in corporate veterinary groups compressing pricing for multi-tenant SaaS platforms. The vendor base stratifies into three tiers: diagnostics-integrated conglomerates, distribution-heavy supply bundlers, and cloud-native workflow specialists. Dominant competitive moves include M&A-driven practice management consolidation and strategic partnerships anchoring hardware-software bundles.
Within the diagnostics-integrated tier, IDEXX Laboratories and Antech Diagnostics exemplify archetypes leveraging deep laboratory data flows to anchor dental workflows. Covetrus occupies a position representing platform openness strategies, allowing third-party imaging devices to connect without proprietary constraints. Henry Schein sits within the distribution-centric archetype, sustaining market presence through captive supply relationships bundling sensors with software licensing.
| Leading Market Players |
|---|
| IDEXX Laboratories |
| Covetrus |
| Henry Schein |
| Patterson Companies |
| Carestream Health |
| Nordhealth |
| DaySmart Software |
| Animal Intelligence Software |
| Antech Diagnostics |
| Others |
Pricing and Supply Chain Analysis
Corporate veterinary groups in US metropolitan corridors concentrate procurement power, anchoring subscription-based SaaS pricing as the dominant commercial model across dental imaging platforms.
Pricing Analysis
Perpetual licensing for advanced 3D reconstruction modules bundles hardware warranty and software maintenance into multi-year contracts, while cloud-native entrants unbundle professional services to hit lower entry price points. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated diagnostics from basic charting tools. Cost compression in the mid-market tier is intensifying because private equity-backed practice aggregators negotiate fleet-scale enterprise agreements. Independent animal clinics show highest price sensitivity, deferring upgrades during hardware refresh cycles.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Chicago anchor hub-and-spoke fulfillment patterns for digital radiography sensors and intraoral scanning hardware. Manufacturing concentrates in the United States, Germany, and Japan for DICOM-compliant imaging components. Component sourcing draws from specialized semiconductor foundries for sensor arrays and precision optics for intraoral cameras. Single-source vulnerability in CMOS sensor supply creates exposure to foundry allocation constraints. Distribution runs through Henry Schein and Patterson veterinary supply divisions with captive bundling of software licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary dental software supply is constrained by the limited pipeline of ISO 13485-certified development shops capable of supporting FDA 510(k) submissions, propping pricing power for compliant vendors.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by deepening integration with anesthesia monitoring hardware and laboratory diagnostics platforms. Prioritize captive supply relationships with digital radiography sensor manufacturers to defend against disintermediation. Channel control through exclusive distribution agreements with multi-site hospital chains remains the critical defensive lever. For New Entrants and Emerging Players: The price-point gap between premium AI-integrated suites and economy charting modules opens white-space in suburban companion animal clinics seeking modular upgrades. Target equine and large animal practices where dental software penetration lags companion animal standards by nearly a decade. Deploy telemedicine-enabled subscription tiers as the primary go-to-market angle to bypass capital-intensive hardware bundling requirements. For Investors and Strategic Acquirers: The window for entry favors platforms with existing CE marking infrastructure and EU authorized representative appointments. Long-term viability hinges on regulatory compliance scalability across FDA, EU MDR, and PMDA jurisdictions. Cloud-native workflow specialists with proven multi-tenant architectures represent the most defensible acquisition profile. Watch for inflection in corporate practice acquisition velocity as the signal for fleet-scale procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI Pathology Detection Launch | Machine learning models trained on DICOM radiographs compress diagnostic loops in high-volume companion animal clinics. |
| Cloud Platform Integration | Multi-tenant SaaS architectures enable centralized data governance across geographically dispersed veterinary hospital networks. |
| Equine Vertical Expansion | Field-deployable imaging with offline synchronization addresses underpenetrated large animal practice workflows. |
| Telemedicine Module Development | Remote consultation workflows connecting general practitioners with dental specialists unlock subscription revenue streams. |
| Regulatory Certification Investment | ISO 13485 quality management and FDA 510(k) clearance create certification barriers protecting compliant vendors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with veterinary practice owners, software platform engineers, distribution channel managers, and regulatory affairs specialists at diagnostics conglomerates. Secondary sources included FDA 510(k) clearance databases, EU MDR notified body documentation, veterinary hospital procurement records, and corporate veterinary group SEC disclosures. Bottom-up installation base estimates triangulated against top-down market sizing from practice management system penetration data.
Data-stream reconciliation across deployment model adoption rates, end-user procurement patterns, and product feature penetration informed the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, deployment configuration, practice scale, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates, cross-checked against veterinary hospital consolidation velocity and cloud infrastructure capex disclosures from platform vendors.
Inputs from veterinary practice surveys and distributor sell-through reports were available through the study window; gaps in real-time pricing transparency from private enterprise agreements introduce uncertainty bands around revenue estimates. Forecasts reflect documented assumptions regarding corporate practice acquisition rates and regulatory pathway timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Metabolic Rate Analysis System Market
Healthcare IT
Global IT Spending in Healthcare Market
Healthcare IT
Healthcare IT Outsourcing Market
Healthcare IT
IT-Enabled Healthcare Market
Healthcare IT
Patient Registry Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Healthcare Enterprise Software Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Healthcare Workforce Management Systems Market
Healthcare IT
Europe Dental Software Market
Healthcare IT
Italy Dental Practice Management Software Market
Healthcare IT
Europe Smart Hospital Market
Healthcare IT
US Healthcare IT Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
ECG Management Systems Market