
 E-Prescribing Market | 2026-2036
E-Prescribing Market Size, Share, and Industry Trends Forecast 2026-2036
E-Prescribing Market Intelligence
The E-Prescribing Market is pivoting around a widening capability gap between enterprise-grade platforms and basic digital prescription modules. Epic Systems Corporation leverages deep integration with hospital electronic health records to dominate large health system deployments. Cerner Corporation anchors its position through sustained R&D investment in interoperability standards and pharmacy connectivity. Allscripts Healthcare competes by specializing in ambulatory settings where workflow flexibility outweighs raw scale requirements.
E-prescribing constitutes the electronic generation, transmission, and filling of medical prescriptions through certified software systems operating on HL7 FHIR or NCPDP SCRIPT standards, typically requiring two-factor authentication and audit trails for controlled substances. Its primary commercial purpose is eliminating handwritten prescription errors while enabling real-time formulary checking and prior authorization automation. Cloud-based technology leads segment expansion as health systems abandon on-premise infrastructure for subscription models with automatic regulatory updates. Telehealth providers represent the fastest-growing end user category as virtual care platforms embed prescribing into remote consultation workflows. The deployment model landscape tilts toward hybrid configurations that balance data sovereignty requirements with the scalability of public cloud resources.
The US Food and Drug Administration and the Drug Enforcement Administration jointly shape product standards through controlled substance e-prescribing mandates and software certification requirements. HIPAA compliance frameworks dictate encryption, access control, and breach notification protocols that vendors must embed at the architecture level. Stakeholders should monitor evolving state-level prescription drug monitoring program integration requirements as these become the next competitive differentiator for platform selection.
Market Dynamics
Cloud-based EHR integration is compressing deployment timelines for e-prescribing platforms as health systems abandon multi-year on-premise implementations for subscription models with automatic regulatory updates.
Growth Catalysts
- DEA EPCS Mandates:The US Drug Enforcement Administration's electronic prescribing for controlled substances requirements force provider adoption of certified platforms with two-factor authentication and audit trails.
- Telehealth Integration:Virtual care platforms embed prescribing into remote consultation workflows, expanding addressable provider base beyond traditional clinic settings.
- Real-Time Formulary Checking:Pharmacy benefit managers demand instantaneous eligibility verification, pulling providers toward platforms with live payer connectivity.
Market Restraints
- Interoperability Fragmentation:Inconsistent HL7 FHIR implementation across health systems creates data exchange friction and raises integration costs.
- Rural Infrastructure Gaps:Broadband limitations in non-urban US counties delay cloud platform adoption where medication errors remain highest.
- State PDMP Variability:Prescription drug monitoring program integration requirements differ across jurisdictions, complicating multi-state health system deployments.
Strategic Opportunities
- Specialty Pharmacy Convergence:Oncology and rare disease pharmacies seek direct EHR-to-dispensing workflows, opening high-margin verticals beyond primary care.
- Behavioral Health Expansion:Psychiatric practices face controlled substance documentation burdens that automated e-prescribing platforms can capture.
- Medicaid Managed Care:State-level prior authorization automation mandates create procurement windows for platforms with real-time payer connectivity.
Industry Challenges
- Clinical Informatics Talent Scarcity:Health systems struggle to hire specialists who bridge pharmacy operations, EHR configuration, and regulatory compliance.
- Legacy System Integration:Decades-old pharmacy management software requires custom middleware development, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Prescribing Market |
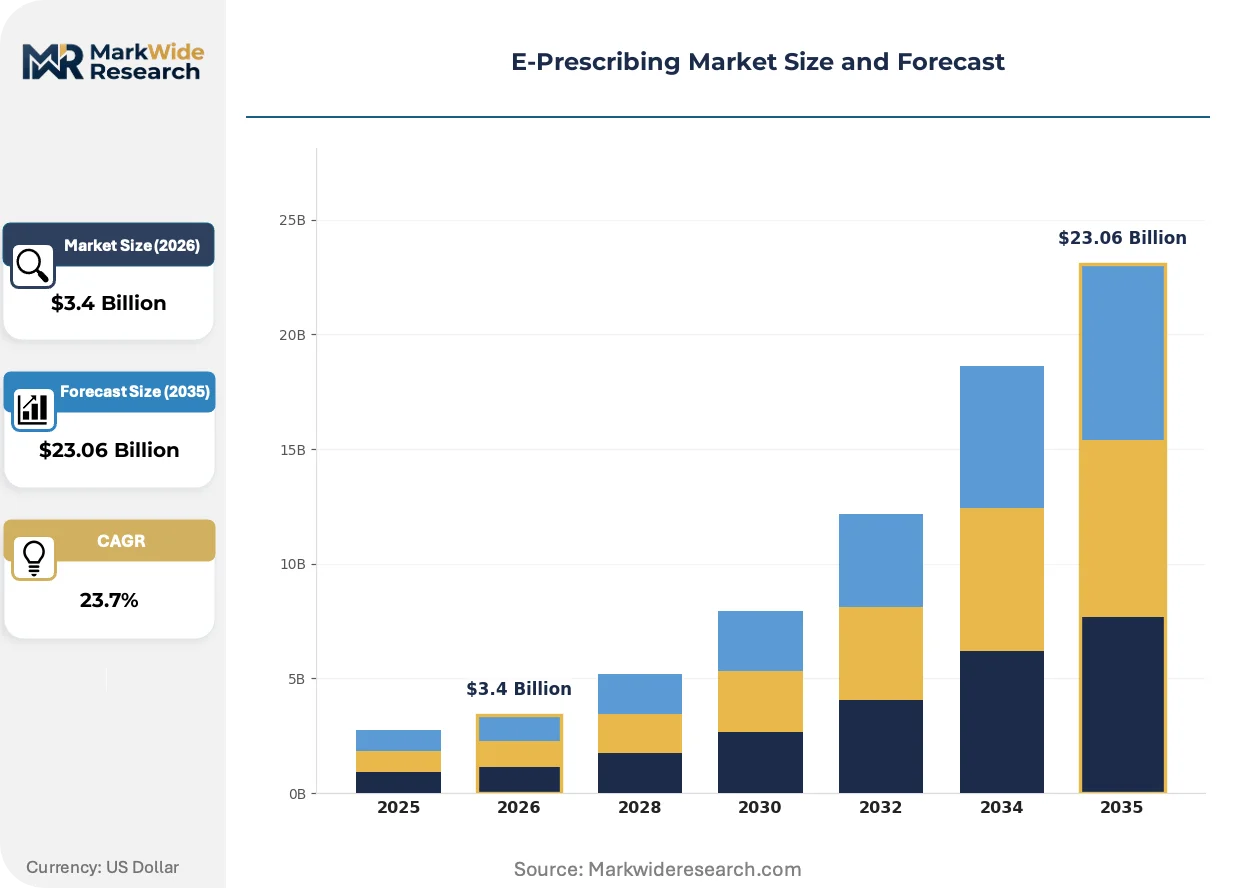
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $23.06 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cloud-Based, Web-Based, Mobile, On-Premise End User: Hospitals, Clinics, Pharmacies, Telehealth Providers Deployment Model: Public Cloud, Private Cloud, Hybrid, Dedicated Server Regulatory Compliance: HIPAA, Meaningful Use, Drug Enforcement Administration, Others |
| Companies Covered | Epic Systems Corporation, Cerner Corporation, Allscripts Healthcare, Medical Information Technology, athenahealth, eClinicalWorks, Surescripts, NextGen Healthcare, DrFirst, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Prescribing Market Strategic Shifts & Innovations
API-first architecture is dissolving the boundary between prescribing platforms and adjacent clinical workflows, enabling embedded functionality that was previously siloed in standalone modules.
Blockchain-enabled prescription integrity verification is decentralizing audit trail management across pharmacy networks. Hospital systems in Texas and Florida pilot distributed ledger systems that eliminate single-point-of-failure risks in controlled substance tracking. This architecture reduces DEA compliance overhead while compressing dispute resolution timelines between prescribers and dispensers.
The US SUPPORT Act mandates electronic prescribing for all controlled substances covered under Medicare Part D, with phased enforcement beginning 2025. Pharmacy chains accelerate EHR vendor certification programs to avoid reimbursement penalties. Independent practices in states without parallel mandates face competitive pressure to upgrade before federal deadlines force compliance.
Subscription-based platform licensing is displacing perpetual software purchases across ambulatory practice groups. Revenue models now bundle regulatory update services, reducing capital expenditure barriers for smaller providers. This shift concentrates vendor relationships with platforms demonstrating sustained R&D investment in interoperability standards.
E-Prescribing Market Segmentation
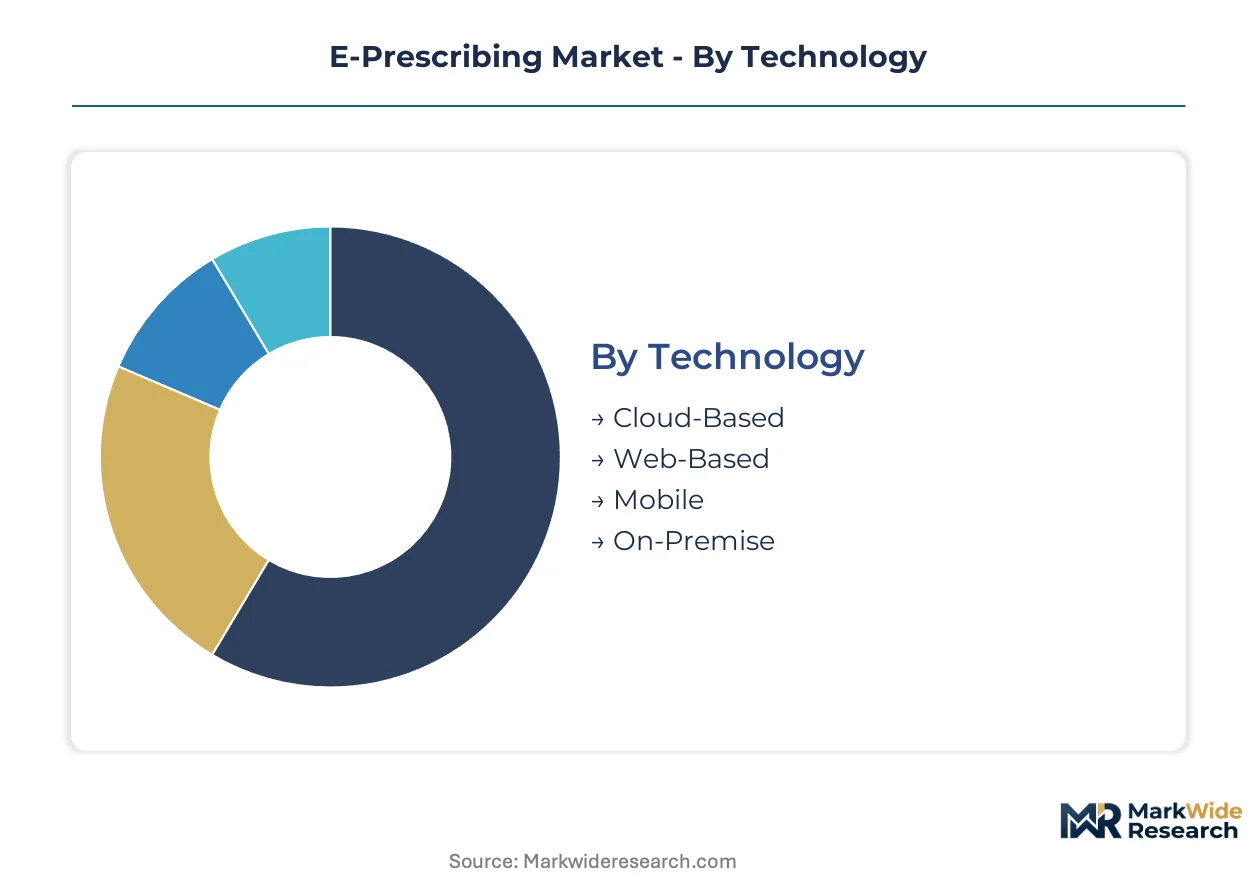
E-prescribing platforms fragment across four structural dimensions that determine integration complexity, compliance burden, and total cost of ownership. Technology architecture and deployment models shape upfront capital requirements, while end-user categories and regulatory scopes define feature prioritization and sales cycle length.
Technology:
Cloud-based systems embed directly into EHR workflows, while standalone web and mobile modules serve providers with fragmented legacy infrastructure.
- Cloud-Based:Multi-tenant architectures with automatic FDA and DEA regulatory updates eliminate on-premise maintenance overhead. Hospital networks in Texas and Florida concentrate procurement here for seamless EHR integration and centralized audit trail management.
- Web-Based:Browser-accessible portals requiring minimal IT support suit small ambulatory practices with limited technical staff. Demand clusters in rural counties where broadband constraints still permit lightweight SaaS connectivity over heavier client-server alternatives.
- Mobile:Native iOS and Android applications enable point-of-care prescribing for house call physicians and nursing home practitioners.
- On-Premise:Locally installed software persists in correctional health systems and certain military medical facilities with data sovereignty mandates.
Volume placements concentrate in Cloud-Based systems; the faster expansion belongs to Mobile as telehealth workflows proliferate.
End User:
Institutional scale dictates workflow customization depth, with acute care facilities demanding full EHR interoperability and retail pharmacies prioritizing real-time eligibility verification.
- Hospitals:Enterprise deployments spanning inpatient, outpatient, and emergency departments require HL7 FHIR connectivity and multi-departmental formulary management. Integrated delivery networks in California and New York anchor procurement volume for these complex implementations.
- Telehealth Providers:Virtual care platforms embed prescribing into video consultation workflows with asynchronous pharmacy communication. This segment climbs fastest as Medicare reimbursement parity for telehealth services locks in post-pandemic.
- Clinics:Federally qualified health centers and independent physician associations seek lightweight implementations with Medicaid prior authorization automation.
- Pharmacies:Chain and independent dispensers require inbound e-prescribing connectivity plus outbound prior authorization status tracking for medication adherence programs.
Procurement volume centers on Hospitals; Telehealth Providers are gaining share fastest as virtual-first care models mature.
Deployment Model:
Data residency requirements and cybersecurity posture drive selection between public elasticity and controlled private infrastructure.
- Hybrid:Configurations splitting controlled substance data in private infrastructure while routing routine prescriptions through public cloud resources balance compliance with scalability. Health systems with multi-state footprints favor this architecture for flexible PDMP integration.
- Private Cloud:Single-tenant environments with dedicated hardware serve academic medical centers and defense health agencies with stringent data localization mandates.
- Public Cloud:Shared infrastructure with automatic scaling suits small practice groups and startup telehealth platforms prioritizing capital efficiency over customization.
- Dedicated Server:Physical hardware deployments persist in critical access hospitals with unreliable internet connectivity and legacy pharmacy system dependencies.
Adoption concentrates in Hybrid configurations; Private Cloud shows the steepest expansion trajectory as ransomware attacks heighten security scrutiny.
Regulatory Compliance:
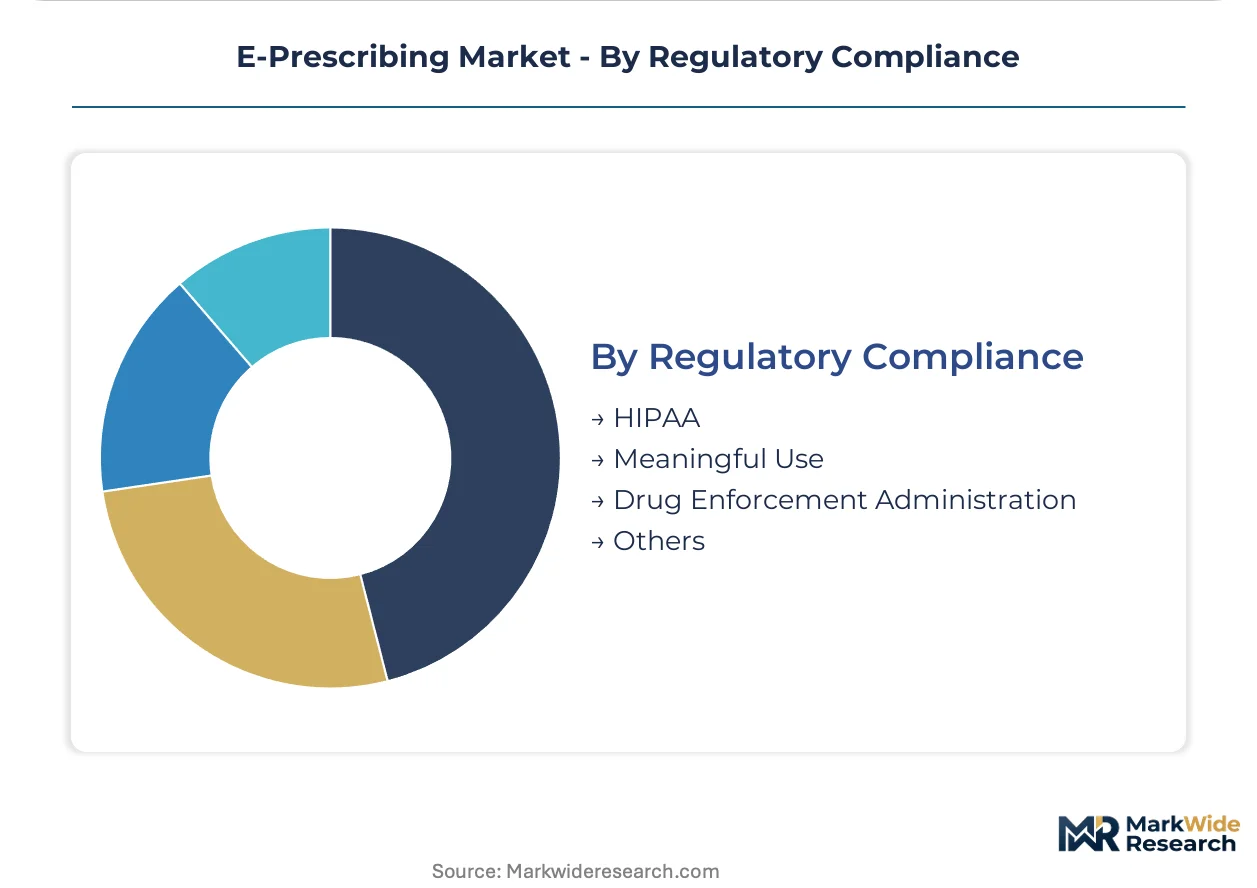
Certification scope determines platform eligibility for specific prescriber categories and reimbursement streams.
- Drug Enforcement Administration:EPCS certification with two-factor authentication and identity proofing enables controlled substance prescribing. The SUPPORT Act mandates this capability for Medicare Part D participation, forcing universal vendor investment.
- HIPAA:Encryption, access control, and breach notification frameworks constitute baseline architecture requirements for all commercial platforms.
- Meaningful Use:E-prescribing quality measures tied to federal incentive programs shape feature roadmaps for ambulatory-focused vendors.
- Others:State-specific PDMP integration, FDA REMS programs for restricted medications, and Medicaid managed care prior authorization protocols round out compliance portfolios.
Certification volume clusters around DEA EPCS; HIPAA baseline requirements are expanding fastest as state privacy laws layer additional obligations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors health technology procurement concentration, with Massachusetts General Brigham and Partners HealthCare driving enterprise EHR-to-pharmacy integration pilots that reshape vendor roadmaps nationwide.
United States
The SUPPORT Act mandates electronic prescribing for controlled substances under Medicare Part D, with DEA EPCS certification becoming non-negotiable for provider reimbursement. Epic Systems Corporation and Cerner Corporation dominate hospital network deployments across integrated delivery networks in California and Texas. Texas Medical Center in Houston pilots blockchain-enabled prescription integrity verification for controlled substance tracking.
Germany
The national e-prescription mandate (E-Rezept) requires universal adoption by statutory health insurance physicians, creating procurement urgency among ambulatory practice groups. EMA interoperability guidelines shape cross-border prescription recognition for mobile EU patients. Berlin-Brandenburg health clusters concentrate vendor certification activity for Telematics Infrastructure compliance.
United Kingdom
NHS England's Electronic Prescription Service (EPS) Phase 4 rollout mandates hospital-to-pharmacy digital connectivity for all acute trusts. The National Institute for Health and Care Excellence embeds e-prescribing quality metrics into reimbursement frameworks. London's Guy's and St Thomas' NHS Foundation Trust anchors interoperability testing for FHIR-based pharmacy exchanges.
India
The National Digital Health Mission (NDHM) Health ID infrastructure enables prescription portability across public and private care settings. CDSCO draft guidance on digital therapeutics creates regulatory clarity for software-as-medical-device prescribing modules. Bengaluru's HealthTech corridor concentrates startup development for cloud-based ambulatory prescribing platforms serving tier-2 cities.
Australia
The Australian Digital Health Agency's Active Script List enables real-time prescription monitoring with pharmacist-controlled dispensing authorization. TGA software as a medical device regulations classify clinical decision support modules embedded in prescribing workflows. Melbourne's Alfred Health anchors pilot programs for specialty pharmacy e-prescribing in oncology and rare disease verticals.
E-Prescribing Market Key Industry Players
Capital-heavy EHR-integrated platform developers compete with asset-light standalone prescribing module vendors for health system procurement contracts. The vendor landscape organizes around three strategic archetypes: enterprise EHR incumbents with native prescribing functionality, interoperability specialists bridging fragmented systems, and telehealth-native platforms embedding prescribing into virtual care workflows. Consolidation pressure intensifies as health systems prioritize single-vendor relationships over best-of-breed integration complexity. Strategic partnerships between EHR vendors and pharmacy benefit managers reshape formulary checking capabilities as a competitive differentiator.
Among US-based health technology developers, Epic Systems Corporation exemplifies the enterprise-integrated archetype through its deep EHR workflow embedding. Cerner Corporation occupies a parallel position through sustained infrastructure investment in hospital network connectivity. Allscripts Healthcare represents the ambulatory-specialist vector with workflow flexibility prioritized over raw deployment scale.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Cerner Corporation |
| Allscripts Healthcare |
| Medical Information Technology |
| athenahealth |
| eClinicalWorks |
| Surescripts |
| NextGen Healthcare |
| DrFirst |
| Others |
Cost & Logistics Intelligence
Cloud infrastructure cost indices from hyperscalers like AWS and Microsoft Azure cascade through e-prescribing vendor pricing tiers, compressing margins for on-premise legacy providers while enabling subscription-based SaaS platforms to capture ambulatory practices through predictable per-provider monthly fees.
Pricing Analysis
Per-provider-per-month subscription tiers anchored to EHR integration depth and DEA EPCS certification status dominate vendor pricing architectures. Price differentiation separates enterprise health system deployments with dedicated implementation teams from lightweight mobile modules for independent practitioners. Pricing pressure stems from telehealth-native platforms undercutting established EHR incumbents with embedded prescribing at no incremental cost. Federally qualified health centers exhibit highest price sensitivity due to constrained Medicaid reimbursement rates, while academic medical centers prioritize interoperability over unit cost.
Supply Chain Analysis
Regional data center distribution across Virginia, California, and Texas anchors cloud platform latency performance for real-time formulary checking workflows. Core technology inputs draw from semiconductor fabrication in Taiwan, enterprise software development in India, and cybersecurity certification services in the United States. Single-source vulnerability concentrates in HL7 FHIR interoperability middleware providers, creating chokepoint risk for multi-vendor health system integrations. Distribution runs through direct sales forces for hospital networks and channel partnerships with practice management consultants for ambulatory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API-first cloud architectures are displacing client-server legacy installations as health systems abandon capital-intensive on-premise infrastructure for subscription models with automatic regulatory compliance updates.
For Market Incumbents: To counter telehealth-native platforms bundling prescribing at zero marginal cost, Epic Systems and Cerner Corporation must accelerate backward integration into pharmacy benefit manager data networks and deepen EHR workflow embedding that raises switching costs for integrated delivery networks. For New Entrants and Emerging Players: Rural health clinics lacking broadband infrastructure for full cloud EHR deployments represent the most penetrable buyer archetype, reachable through lightweight mobile modules with offline prescription drafting and asynchronous pharmacy synchronization capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor interoperability specialists with pre-built PDMP connectors in Medicaid expansion states, where prior authorization automation mandates create procurement urgency and long-term viability rests on sustained R&D investment in FHIR standard evolution.| Strategic Initiative | Industry Significance |
|---|---|
| DEA EPCS Certification Acceleration | Medicare Part D reimbursement eligibility under the SUPPORT Act hinges on compliant platform architecture. |
| Pharmacy Benefit Manager Partnership | Real-time formulary checking capabilities differentiate vendor selection for large health system procurement. |
| Telehealth Workflow Embedding | Medicare reimbursement parity for virtual care services expands addressable provider base beyond traditional clinics. |
| State PDMP Integration Expansion | Prescription drug monitoring program connectivity becomes mandatory competitive table stakes for multi-state deployments. |
| Blockchain Audit Trail Pilot | Texas Medical Center pilots distributed ledger verification for controlled substance tracking compliance efficiency. |
Research Approach
Multi-period observation of DEA EPCS certification timelines, health system EHR procurement cycles, and telehealth platform prescribing integration rates anchored the trend analysis, supplemented by interviews with hospital CIOs, ambulatory practice managers, pharmacy informatics specialists, and EHR implementation consultants. Secondary validation drew from FDA software certification databases, CMS Medicare reimbursement rulemaking, state PDMP integration requirement documents, and hospital GPO contract filings. Bottom-up deployment counts across technology segments triangulated against top-down health IT spending estimates.
Input-output matrices modeled adoption rates across cloud-based, web-based, mobile, and on-premise technology architectures, hospital, telehealth, clinic, and pharmacy end-user categories, and hybrid, private cloud, public cloud, and dedicated server deployment models across the analysis window. CAGRs derived from segment-level growth trajectory analysis incorporating Medicare reimbursement policy shifts, DEA enforcement timelines, and health system consolidation patterns.
Revisions become necessary when DEA regulatory enforcement dates shift, major health system mergers alter vendor selection dynamics, or telehealth reimbursement parity legislation expires. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Global Technology Spending on Core Administration in Healthcare Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Cognitive Assessment and Training in Healthcare Market
Healthcare IT
Healthcare IT Provider Market
Healthcare IT
Clinical Practice Management Software Market
Healthcare IT
Global Patient Flow Management Solutions Market
Healthcare IT
Healthcare Revenue Cycle Management (RCM) Software Market
Healthcare IT
Medical Specimen Tracking System Market
Healthcare IT
North America Internet of Medical Things (Iomt) Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Patient Access Solutions Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Radiation Dose Optimisation Software Market
Healthcare IT
Global Orthopedic Software Market
Healthcare IT
Clinical Communication and Collaboration Market
Healthcare IT
Commercial Pharmaceutical Analytics Market