
 Medical Radiation Protection Aprons Market | 2026-2036
Medical Radiation Protection Aprons Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Radiation Protection Aprons Market Analysis
Chinese textile and polymer composite producers is hardening supply for radiation shielding fabrics, tightening raw material availability for finished apron manufacturers worldwide. INFAB Corporation leverages vertically integrated lamination capabilities to sustain North American production scale. MAVIG anchors European hospital channel relationships through direct sales teams in Düsseldorf and Vienna. Burlington Medical differentiates via custom-fit measurement protocols that reduce orthopedic strain for interventional cardiologists.
Medical radiation protection aprons are personal protective garments constructed from lead rubber, lead-free tungsten-bismuth composites, or barium sulfate-impregnated polymers, engineered to attenuate scattered ionizing radiation in diagnostic and interventional procedures to occupational exposure limits. Manufacturing employs multi-layer calendering or dispersion coating at 0.25–0.50 mm lead-equivalence thicknesses, with seam welding and hook-loop closures ensuring continuous protective coverage. Non-lead aprons now lead material substitution as disposal regulations tighten around hazardous lead waste, while lightweight variants capture preference among operators performing extended fluoroscopy. Pediatric aprons represent a concentrated margin pool due to specialized sizing requirements and lower price elasticity from neonatal intensive care units.
FDA 21 CFR 1020.32 mandates minimum attenuation performance for fluoroscopic equipment accessories, while the EU MDR requires notified body certification for Class I reusable protective garments, elevating compliance costs for non-European exporters. ISO 13485 quality management systems and IEC 60601-1-3 collateral standards further constrain design verification protocols for manufacturers targeting hospital procurement frameworks. Stakeholders must monitor evolving state-level radiological health codes in California and Texas, where Department of Public Health inspections now include apron integrity testing as a condition of facility licensing renewal.
Market Dynamics
Lead-free composite materials are displacing traditional lead rubber across hospital procurement frameworks, driven by tightening hazardous waste disposal mandates and operator ergonomic demands during extended fluoroscopy procedures.
Growth Catalysts
- EU MDR Certification Mandate:Class I reusable protective garments now require notified body oversight, accelerating replacement cycles among European hospital networks seeking compliant inventory.
- Fluoroscopy Volume Expansion:Diagnostic centers in Germany are standardizing apron procurement protocols as interventional cardiology and vascular surgery caseloads rise.
- Lightweight Polymer Substitution:Barium sulfate-impregnated and tungsten-bismuth composites capture preference among operators performing lengthy electrophysiology ablations.
Market Restraints
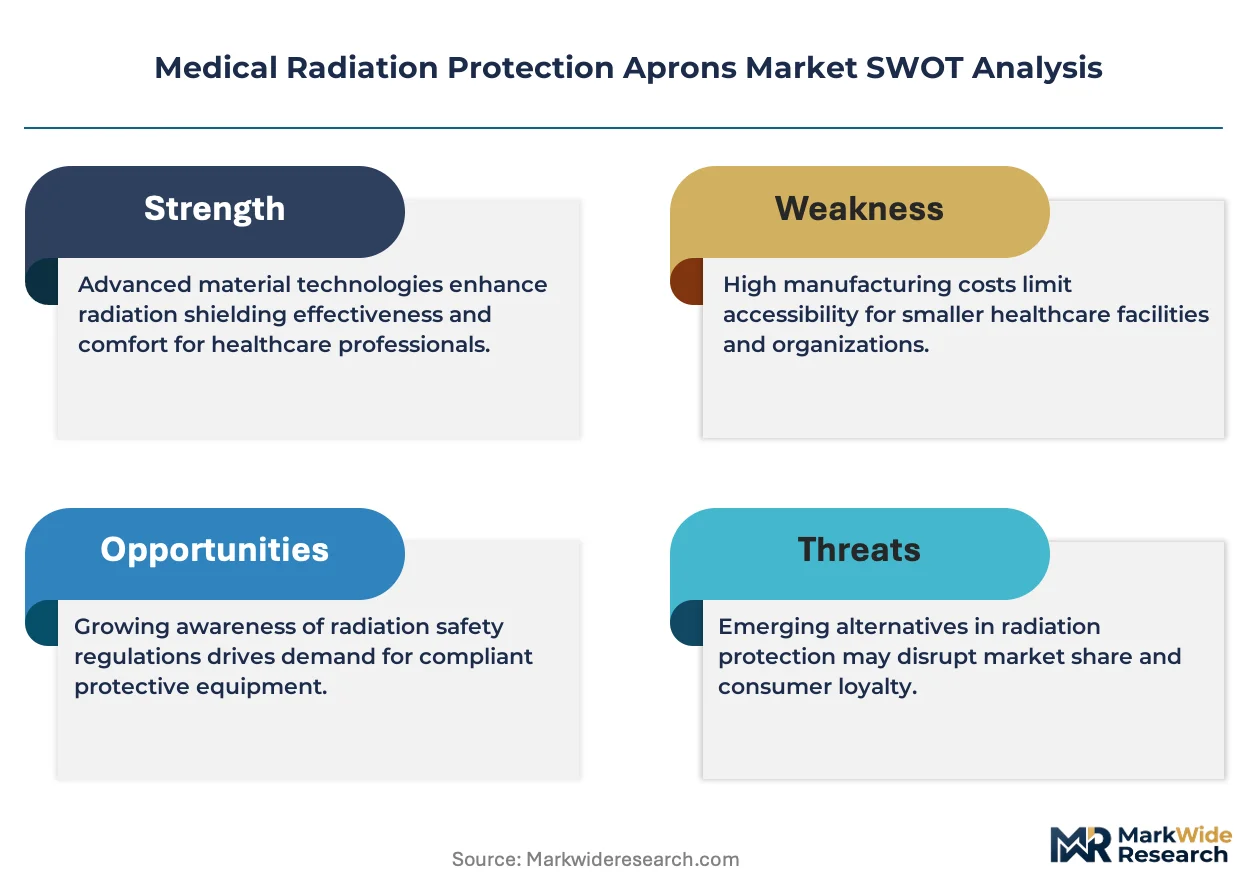
- Raw Material Concentration:Chinese textile and polymer composite producers dominate radiation shielding fabric supply, creating vulnerability for finished apron manufacturers elsewhere.
- Lead-Equivalence Verification Costs:Multi-layer calendering and dispersion coating processes require specialized equipment to achieve 0.25–0.50 mm certification thresholds.
- Disposal Regulatory Burden:Hazardous waste frameworks in multiple jurisdictions impose escalating compliance costs on lead-containing apron end-of-life management.
Strategic Opportunities
- Pediatric Specialization:Neonatal intensive care units demonstrate lower price elasticity for customized sizing, creating concentrated margin pools for tailored apron producers.
- Direct Hospital Channel Expansion:European vendors are building captive sales teams in Düsseldorf and Vienna to bypass distributor markups in high-volume procurement markets.
- Custom-Fit Measurement Protocols:Apron manufacturers incorporating orthopedic strain reduction for interventional cardiologists can command premium positioning against standard catalog offerings.
Industry Challenges
- Seam Welding Certification Delays:Continuous protective coverage validation under ISO 13485 protocols extends design verification timelines for new product introductions.
- State-Level Inspection Variability:California and Texas Department of Public Health authorities now mandate apron integrity testing as a condition of facility licensing renewal, creating fragmented compliance requirements.
- Hook-Loop Closure Standardization:Inconsistent fastener performance specifications across hospital procurement frameworks complicate inventory management for multi-site health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Radiation Protection Aprons Market |
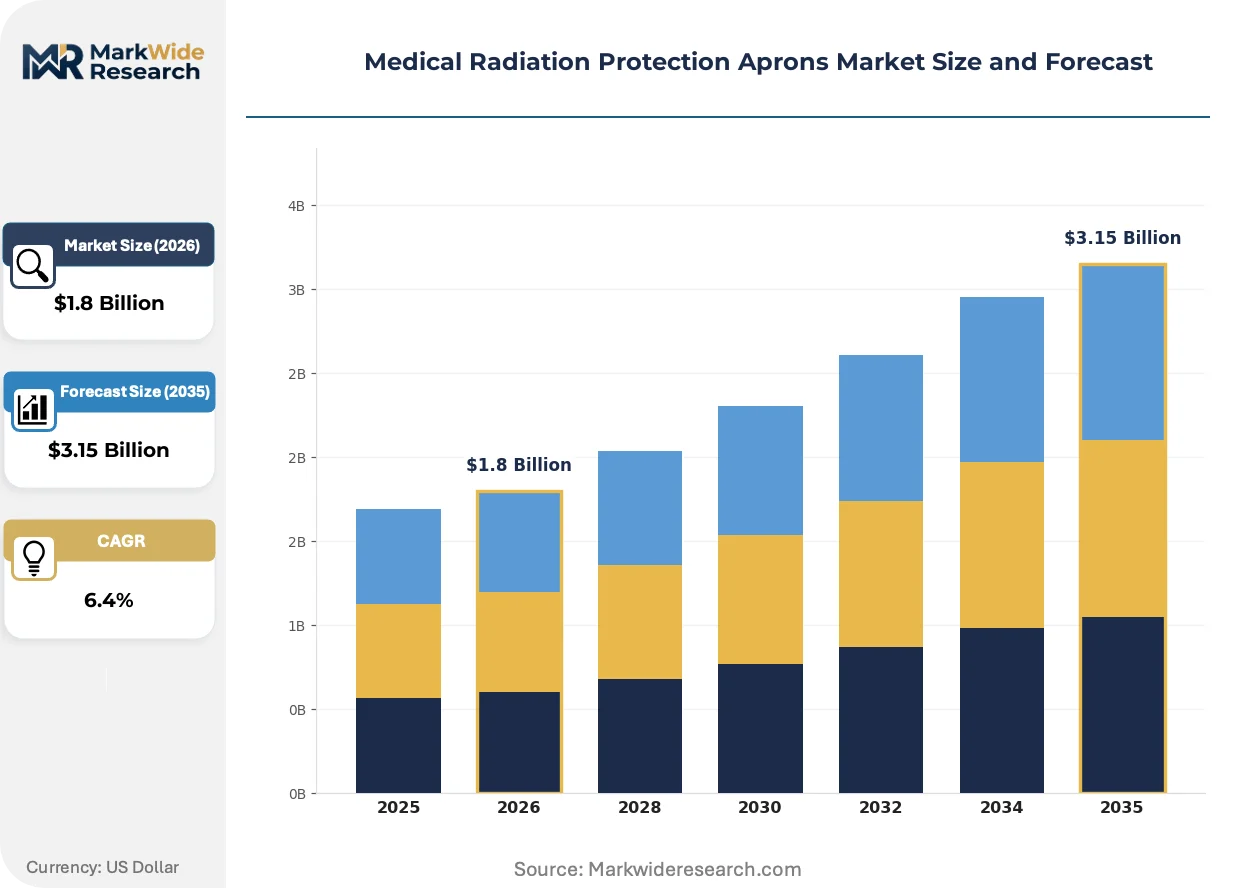
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Aprons, Non-Lead Aprons, Lightweight Aprons, Pediatric Aprons End User: Hospitals, Clinics, Diagnostic Centers, Laboratories Technology: Traditional Technology, Advanced Composite Materials, Custom-Fit Solutions, Detachable Components Distribution Channel: Online Retail, Direct Sales, Distributors, Trade Shows |
| Companies Covered | Amray Radiation Protection, AliMed, BLOXR Solutions, Barrier Technologies, Burlington Medical, Shielding International, INFAB Corporation, Kiran, MAVIG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Radiation Protection Aprons Market Emerging Trajectories
Material science advances and regulatory recalibration are compressing traditional product lifecycles while opening new competitive vectors around weight reduction, customization depth, and circular economy compliance.
Non-lead apron construction is modularizing protective garment architecture. Tungsten-bismuth composite layers replace homogeneous lead rubber cores, enabling zone-specific attenuation tailoring. Interventional radiology departments in high-volume German hospital networks are adopting these configurations fastest. This structural flexibility is modularizing supplier-customer relationships around semi-custom rather than purely catalog offerings.
EU MDR implementation is tightening lead-equivalence certification requirements across member states. Notified body involvement for Class I reusable garments elevates documentation burdens but also creates differentiation for pre-certified suppliers. Non-European exporters face compressed market access timelines as importers demand pre-validated technical files.
Hospital procurement teams are consolidating vendor relationships around full-service apron management. Bundled offerings covering measurement, fitting, cleaning, and disposal replacement are displacing transactional product sales. This pattern concentrates most visibly in German hospital networks standardizing replacement cycles across multi-site radiology departments.
Medical Radiation Protection Aprons Market Segmentation
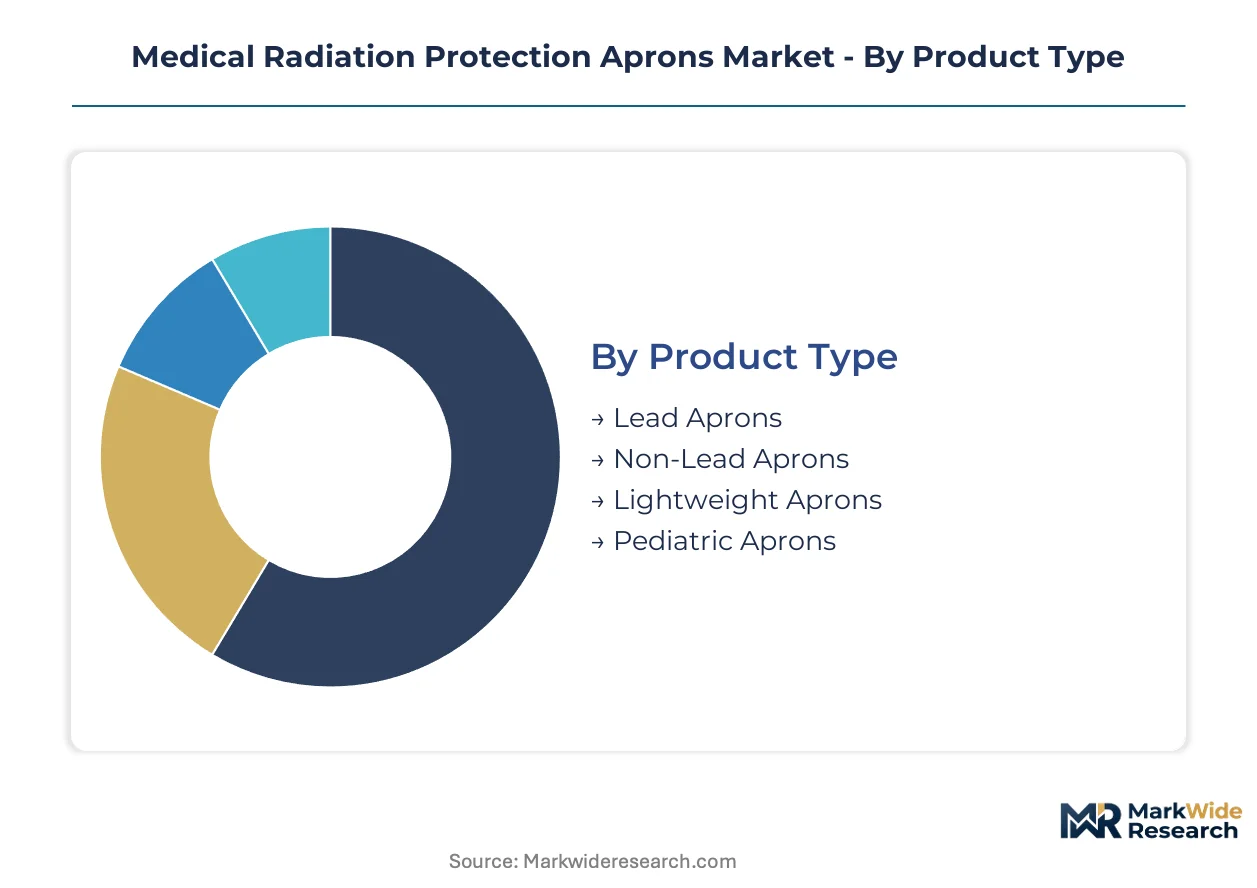
Replacement cycles and material upgrades drive apron procurement decisions across healthcare settings. Segmentation reveals where lightweight composites displace legacy lead rubber and which end-users prioritize custom-fit ergonomic solutions.
Product Type:
Upgrade momentum from heavy lead rubber to composite alternatives reshapes replacement timelines across radiology departments.
- Lead Aprons:Traditional lead rubber construction delivers 0.25–0.50 mm lead-equivalence through homogeneous calendered layers. German hospital networks are phasing out inventories fastest as EU MDR disposal regulations tighten hazardous waste handling costs.
- Non-Lead Aprons:Tungsten-bismuth and barium sulfate-impregnated polymer composites eliminate toxic material disposal liabilities. Diagnostic centers in Düsseldorf and Vienna prioritize these for interventional cardiology suites where extended fluoroscopy creates operator fatigue.
- Lightweight Aprons:Zone-specific attenuation tailoring reduces garment mass by 30–40% versus traditional construction. Electrophysiology labs favor these for lengthy ablation procedures.
- Pediatric Aprons:Specialized sizing protocols address neonatal intensive care requirements with lower price elasticity. Custom measurement services command premium positioning.
Volume placements concentrate in Non-Lead Aprons; the faster expansion belongs to Lightweight Aprons.
End User:
Procurement sophistication varies sharply by facility scale and procedure volume intensity.
- Hospitals:Multi-site radiology departments standardize replacement cycles across interventional cardiology, vascular surgery, and electrophysiology units. German hospital networks now bundle measurement, cleaning, and disposal services into vendor contracts.
- Diagnostic Centers:Rising fluoroscopy caseloads drive apron procurement protocol formalization. These facilities prioritize lightweight composites for operator retention during extended procedures.
- Clinics:Smaller imaging volumes favor catalog-standard sizing over custom-fit protocols. Price sensitivity limits uptake of premium composite materials.
- Laboratories:Research and veterinary applications generate sporadic demand with minimal replacement frequency. Standard lead-equivalence specifications dominate.
Procurement scale peaks at Hospitals; Diagnostic Centers are climbing the fastest as outpatient interventional volumes expand.
Technology:
Material science advances compress product lifecycles while opening differentiation vectors around weight reduction and customization depth.
- Advanced Composite Materials:Multi-layer dispersion coating achieves targeted attenuation with reduced mass. Tungsten-bismuth layering enables zone-specific protection mapping for interventional radiologists.
- Custom-Fit Solutions:Three-dimensional measurement protocols reduce orthopedic strain for operators performing lengthy procedures. Burlington Medical's orthopedic-focused fitting services exemplify premium positioning.
- Traditional Technology:Homogeneous lead rubber construction faces displacement as disposal regulations escalate compliance burdens. Limited to price-constrained procurement environments.
- Detachable Components:Modular thyroid collars and skirt attachments extend garment utility across procedure types. Simplifies inventory management for multi-site health systems.
Deployment breadth spans Advanced Composite Materials; Custom-Fit Solutions gain share fastest as ergonomic awareness penetrates high-volume interventional suites.
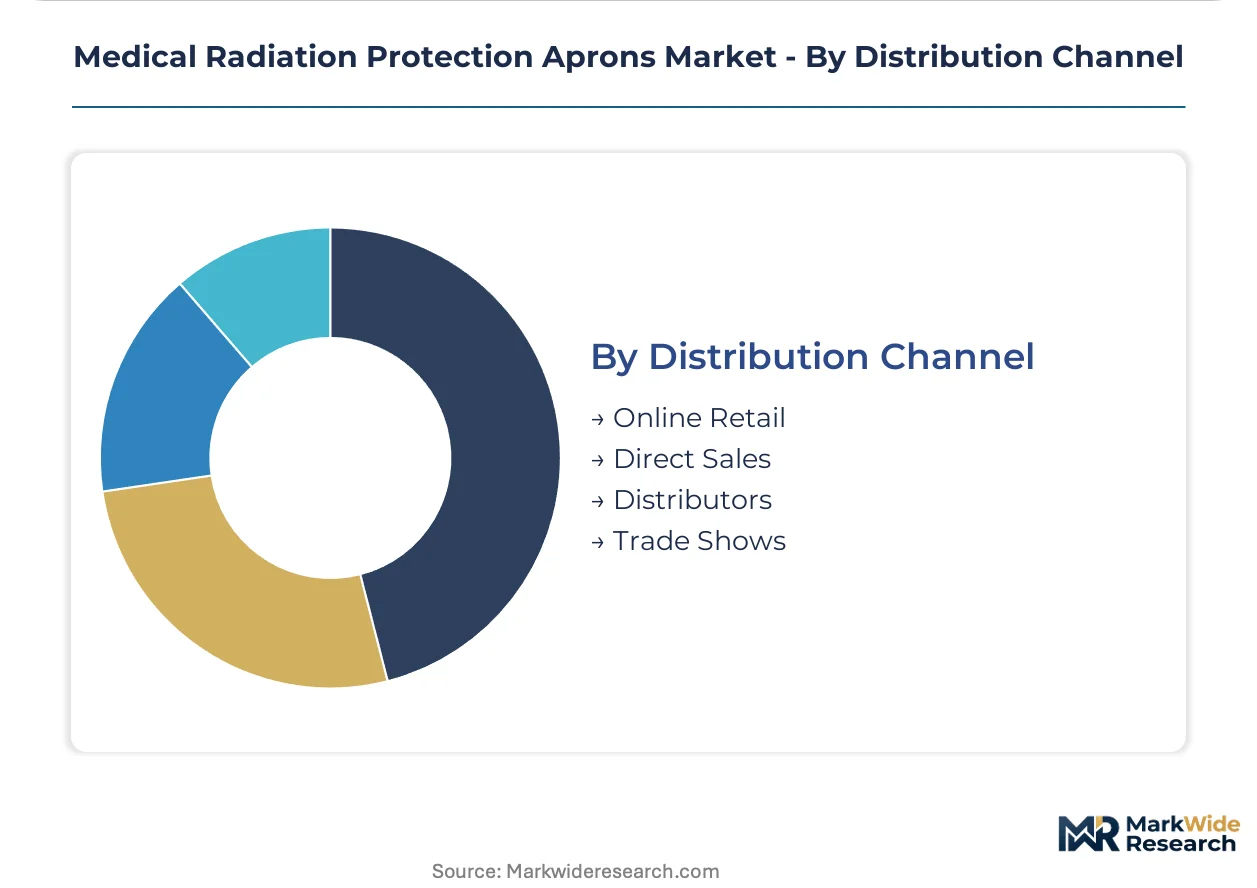
Distribution Channel:
Channel strategy determines margin capture and customer relationship depth in fragmented procurement landscapes.
- Direct Sales:Captive sales teams in Düsseldorf and Vienna bypass distributor markups for high-volume German hospital networks. MAVIG anchors European relationships through this model.
- Distributors:Regional medical supply houses dominate clinic and laboratory segments with catalog-standard offerings. Inventory consolidation pressures margins.
- Online Retail:Limited to replacement accessories and standardized sizing for small facilities. Lead-equivalence certification verification challenges remote procurement.
- Trade Shows:RSNA and ECR exhibitions drive product demonstration and custom-fit protocol adoption. Critical for ergonomic differentiation messaging.
Revenue concentration sits with Direct Sales; Distributors retain volume leadership in fragmented downstream segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese textile and polymer composite producers anchor raw material supply for radiation shielding fabrics, concentrating upstream leverage in East Asia while finished apron manufacturing disperses across North America and Europe.
United States
FDA 21 CFR 1020.32 mandates minimum attenuation performance for fluoroscopic equipment accessories, driving hospital procurement standardization. California and Texas Department of Public Health authorities now require apron integrity testing as a condition of facility licensing renewal. INFAB Corporation sustains North American production scale through vertically integrated lamination capabilities.
Germany
Hospital networks in Düsseldorf and Vienna are standardizing apron replacement cycles across multi-site radiology departments as interventional cardiology caseloads rise. EU MDR implementation tightens lead-equivalence certification requirements for Class I reusable protective garments. MAVIG anchors European channel relationships through direct sales teams positioned in these cities.
China
Domestic textile and polymer composite producers harden supply availability for radiation shielding fabrics worldwide, tightening feedstock access for foreign finished apron manufacturers. NMPA oversight of medical device quality parallels ISO 13485 alignment for export-oriented producers. Yangtze River Delta manufacturing clusters concentrate calendering and dispersion coating capacity.
Japan
PMDA regulatory frameworks enforce IEC 60601-1-3 collateral standards for protective garment design verification. METI industrial policy supports lightweight material substitution in medical device supply chains. Kanto region hospital procurement teams prioritize ergonomic solutions for electrophysiology lab operators.
India
CDSCO medical device regulations are converging toward ISO 13485 quality management requirements for imported protective garments. BIS standards activity in polymer composites supports domestic material substitution initiatives. Maharashtra and Karnataka diagnostic center networks expand fluoroscopy capacity, driving apron procurement formalization.
Medical Radiation Protection Aprons Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue ergonomic specialization and pediatric customization. The vendor base clusters around three archetypes: vertically integrated North American fabricators, European direct-sales specialists, and Asia-Pacific material suppliers. Consolidation pressure operates through bundled service contracts and M&A targeting measurement-protocol capabilities. Geographic expansion and technology licensing represent dominant competitive vectors.
Among North American fabricators, INFAB Corporation and Burlington Medical exemplify contrasting strategic positions. INFAB Corporation occupies a scale-driven anchor role through captive lamination infrastructure. Burlington Medical represents the ergonomic specialization vector, with custom-fit measurement protocols reducing orthopedic strain for interventional cardiologists. European direct-sales architecture finds representation in MAVIG, whose Düsseldorf and Vienna teams bypass distributor markups in high-volume procurement markets.
| Leading Market Players |
|---|
| Amray Radiation Protection |
| AliMed |
| BLOXR Solutions |
| Barrier Technologies |
| Burlington Medical |
| Shielding International |
| INFAB Corporation |
| Kiran |
| MAVIG |
| Others |
Supply Flow & Price Mechanics
Lead-equivalence certification tiers bifurcate apron procurement into premium validated inventory versus commodity catalog offerings, with EU MDR compliance costs concentrating pricing power among pre-certified European suppliers while Chinese material feedstock dominance compresses margins for non-integrated assemblers elsewhere.
Pricing Analysis
Warranty and end-of-life disposal bundling separates premium vendor contracts from transactional apron sales, with full-service agreements covering measurement, cleaning, and hazardous waste retrieval commanding three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ISO 13485 certification status and lead-equivalence verification depth, with German hospital networks least sensitive due to standardized replacement cycles while Indian diagnostic centers face acute cost compression. Pricing pressure stems from raw material concentration in Yangtze River Delta producers, forcing margin tightening among finished goods manufacturers lacking captive lamination.
Supply Chain Analysis
Skilled polymer composite technicians concentrate in China's Yangtze River Delta and Japan's Kanto region, anchoring calendering and dispersion coating capacity for radiation shielding fabrics. Raw material dependencies draw from tungsten-bismuth powder suppliers, barium sulfate compounders, and medical-grade polymer resin producers. Single-source vulnerability runs through Chinese textile producers dominating shielding fabric output. Distribution runs through direct sales teams in Düsseldorf and Vienna for high-volume hospital networks, with regional distributors serving fragmented clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tungsten-bismuth composite substitution for legacy lead rubber defines this market's technology-transition phase, with lightweight zone-specific attenuation architectures displacing homogeneous construction across European and North American procurement frameworks.
For Market Incumbents: Acquire custom-fit measurement protocol capabilities to defend against ergonomic-specialist entrants capturing interventional cardiologist loyalty. Backward integration into polymer composite lamination insulates margin position from Chinese feedstock volatility. Prioritize EU MDR technical file pre-validation to compress replacement cycle capture timelines. For New Entrants and Emerging Players: Capture pediatric apron customization white space where neonatal intensive care units demonstrate lowest price elasticity. Target Indian diagnostic center networks expanding fluoroscopy capacity with catalog-standard lightweight offerings. Lead with trade show demonstration presence at RSNA and ECR to establish ergonomic credibility. For Investors and Strategic Acquirers: Re-rating potential sits with measurement-protocol specialists given hospital procurement consolidation around bundled service contracts. Five-to-ten year viability favors vendors controlling both composite material supply and direct hospital channel relationships. Monitor EU MDR enforcement intensity as inflection signal for compliance-cost barrier sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Pre-Validation | Notified body certification accelerates hospital replacement cycle capture in Germany and Austria. |
| Backward Integration into Composite Lamination | Captive polymer dispersion coating capacity insulates margin from Chinese feedstock volatility. |
| Custom-Fit Measurement Protocol Development | Orthopedic strain reduction services command premium positioning in interventional cardiology suites. |
| Pediatric Sizing Specialization | Neonatal intensive care procurement demonstrates lowest price elasticity for tailored offerings. |
| Direct Sales Team Expansion | Düsseldorf and Vienna presence bypasses distributor markups in high-volume German hospital networks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across biomedical engineers, hospital purchasing committee members, GPO contracts managers, and interventional cardiologists. FDA 21 CFR submissions, EU MDR notified body databases, ISO 13485 certification registries, and hospital procurement contract disclosures supplied validation layers. Bottom-up apron shipment analysis triangulated against top-down healthcare capital expenditure patterns.
Granularity-level modeling operated at product-type, end-user facility scale, technology tier, and distribution channel dimensions, with country-specific regulatory cluster overlays for Germany, United States, China, Japan, and India. CAGRs derived from replacement cycle frequency analysis, fluoroscopy volume projections, and material substitution elasticity coefficients across the projection horizon. Industry-specific inputs incorporated EU MDR implementation timelines and state-level radiological health code evolution in California and Texas.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese export policy shifts and tungsten-bismuth raw material availability. Projections reflect documented assumptions regarding hospital procurement standardization rates and composite material cost curves. Material deviation in EU MDR enforcement intensity or hazardous waste disposal regulation tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Crash Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
Flammable Storage Cabinets Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Germany Personal Protective Equipment (PPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Radiation Protection Apron Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Smart PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Emergency Stop Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market