
 Flammable Storage Cabinets Market | 2026-2036
Flammable Storage Cabinets Market Size, Share, and Industry Trends Forecast 2026-2036
Flammable Storage Cabinets Market Insights
The capital-intensity gap between European precision manufacturers and Asian volume producers is collapsing as steel fabrication automation spreads. Asecos GmbH leverages its German engineering heritage to dominate premium laboratory and chemical processing specifications. Shanghai SYSBEL Industry and Technology Co. Ltd. anchors the Asia-Pacific supply base through integrated cold-rolled steel production and rapid custom fabrication turnaround. DENIOS Inc. competes on modular system architecture, allowing facilities to reconfigure storage arrays without full replacement.
Flammable storage cabinets are engineered steel or stainless steel enclosures with reinforced seams, self-closing doors, and integrated ventilation ports designed to contain ignitable liquids and limit fire propagation in industrial environments. Wall-mounted and freestanding configurations dominate current procurement, with modular cabinets representing the fastest-growing segment as facilities prioritize scalable hazardous material management. Steel construction sustains the largest volume share due to cost efficiency and fire-resistance ratings, while stainless steel commands premium positioning in pharmaceutical cleanrooms and food processing plants where corrosion resistance is mandatory.
OSHA's flammable liquids standard and EPA's Risk Management Plan requirements mandate specific storage capacities and construction standards, directly shaping product certification pathways and procurement specifications in the United States. NFPA 30 and FM Global data sheets provide additional third-party validation frameworks that influence insurance underwriting and facility compliance audits. Buyers must evaluate whether suppliers maintain current UL or FM approvals as regulatory bodies periodically tighten testing protocols for thermal integrity and spill containment performance.
Market Dynamics
OSHA's 2023 enforcement memorandum on flammable liquids storage triggered immediate replacement cycles across US manufacturing, compressing procurement timelines from 18 months to 90 days for non-compliant facilities.
Growth Catalysts
- EPA Risk Management Plan amendments:Chemical processing plants in Texas and Louisiana face mandatory cabinet upgrades to meet revised spill containment thresholds, forcing capital deployment into certified storage infrastructure.
- Pharmaceutical cleanroom expansion:Stainless steel cabinet demand accelerates as FDA sterile manufacturing guidelines tighten material compatibility requirements for solvent storage in aseptic environments.
- Petrochemical corridor densification:New ethylene crackers and derivative units along the US Gulf Coast require fire-rated storage arrays that integrate with distributed control systems for hazardous material tracking.
Market Restraints
- Cold-rolled steel price volatility:Input cost swings of 30-40 percent over 18-month windows compress fabricator margins and destabilize project bidding for large-scale storage deployments.
- Regional supply concentration:Premium cabinet production clusters in Germany and China expose buyers to extended lead times and tariff exposure during trade friction episodes.
- Substitute containment systems:Outdoor bulk tank farms with secondary containment berms capture volume from facilities with sufficient real estate, limiting cabinet penetration in greenfield chemical sites.
Strategic Opportunities
- Modular reconfiguration services:Facilities seek cabinet arrays that expand without full replacement, creating recurring revenue streams for vendors offering field-modifiable shelving and ventilation retrofits.
- India manufacturing incentives:PLI scheme benefits for capital goods production attract fabricators to establish domestic capacity serving South Asian chemical and pharmaceutical growth corridors.
- Smart inventory integration:RFID-enabled cabinets that feed real-time solvent levels into ERP systems command price premiums from multinational manufacturers pursuing digital warehouse transformation.
Industry Challenges
- FM Global thermal testing backlog:Certification queues extending 6-9 months delay product launches and freeze procurement decisions for risk-averse buyers awaiting third-party validation.
- Welding technician scarcity:Precision TIG welding for stainless steel seams requires skilled labor pools that have contracted 15-20 percent in major manufacturing regions, constraining output scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flammable Storage Cabinets Market |
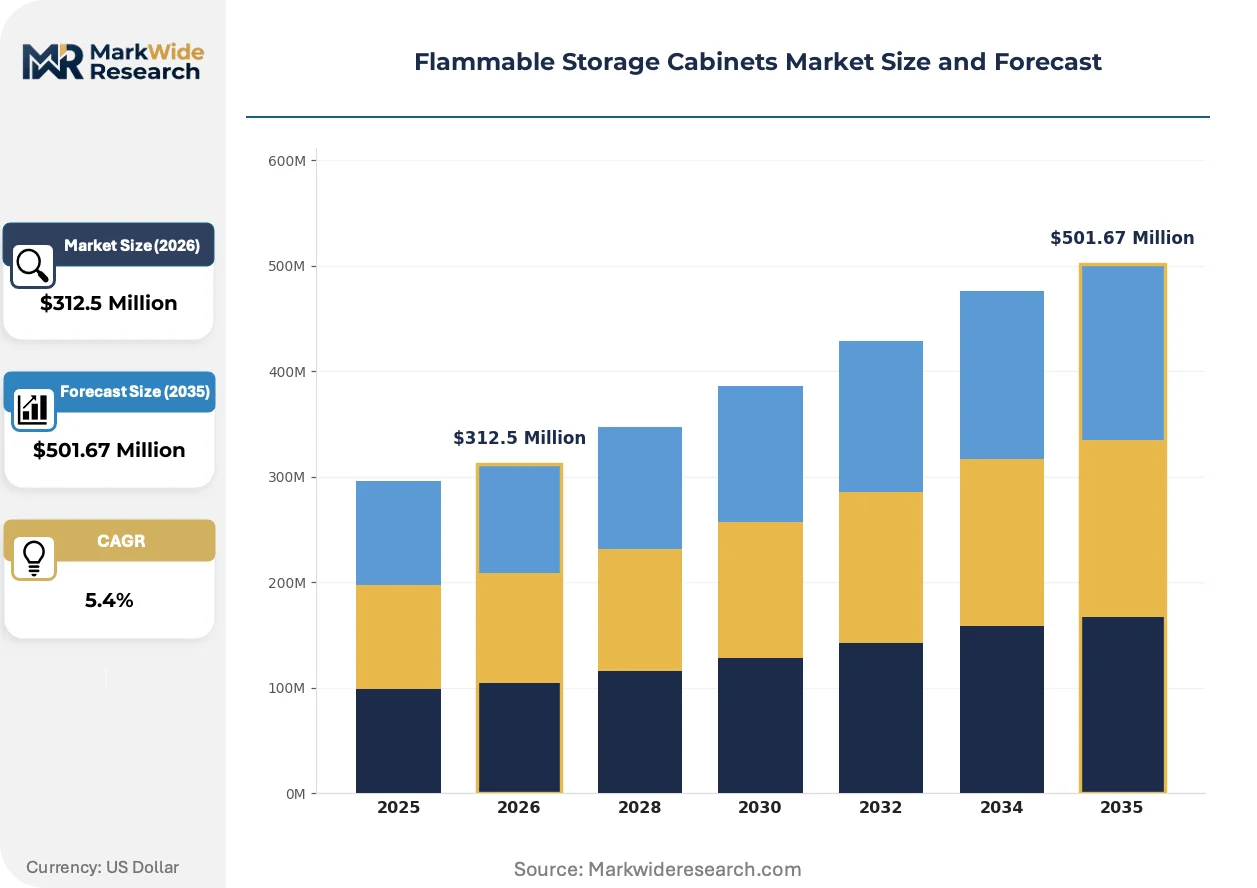
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted Cabinets, Freestanding Cabinets, Portable Cabinets, Modular Cabinets, Mobile Cabinets Material Construction: Steel, Stainless Steel, Polyethylene, Composite, Aluminum Application: Chemical Processing Facilities, Laboratories, Educational Institutions, Automotive Workshops, Aerospace Manufacturing End User Industry: Chemicals & Petrochemicals, Pharmaceuticals, Food & Beverage, Electronics, Oil & Gas |
| Companies Covered | Asecos GmbH, Shanghai SYSBEL Industry and Technology Co. Ltd., Justrite Manufacturing Company, Vestil Manufacturing Corp, Securall A and A Sheet Metal Products, DENIOS Inc., Eagle Manufacturing Company, Wuxi Huanawell Metal Manufacturing Co Ltd., Kewaunee International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flammable Storage Cabinets Market Trends and Innovations
Steel fabrication automation is collapsing the historical performance gap between European precision manufacturers and Asian volume producers, redrawing competitive boundaries across certification tiers.
Electropolished stainless steel interiors with seamless coved corners are supplanting standard brushed finishes in pharmaceutical and semiconductor solvent storage. FDA-registered drug manufacturers specify these surfaces to eliminate microbial harborage points during cleaning validation. The shift is compressing price premiums for electropolished configurations from 40 percent to 15 percent above standard grades as Asian fabricators master the electrochemical process.
OSHA's updated flammable liquids standard interpretation now mandates self-closing doors with fusible link activation at 165°F, overriding previous manual-latch allowances. Chemical processing facilities must retrofit existing cabinets or face willful violation citations during programmed inspections. Texas and Louisiana petrochemical plants are prioritizing FM-approved models to satisfy insurer requirements concurrent with regulatory compliance.
Integrated service contracts bundling cabinet installation, inspection, and recertification are displacing transactional equipment sales in multinational manufacturing accounts. Procurement teams at Dow, DuPont, and BASF operations now specify 5-year total-cost-of-ownership agreements rather than capital purchase orders. This shift concentrates vendor relationships with firms maintaining nationwide technician networks for annual NFPA 30 compliance audits.
Flammable Storage Cabinets Market Segmentation
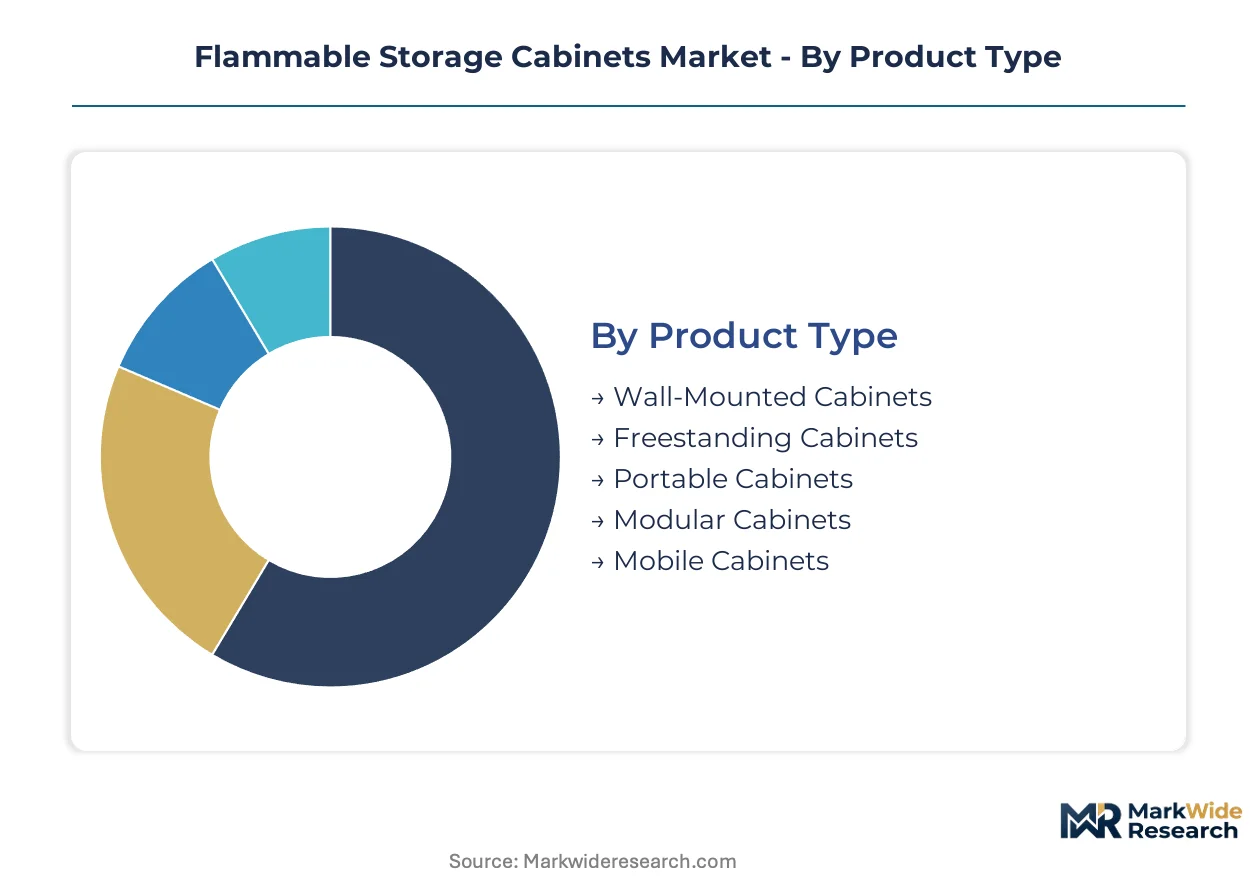
Segmentation in flammable storage cabinets determines procurement specifications, certification pathways, and channel economics. Buyers route wall-mounted units through industrial distributors while modular systems flow direct-to-facility with engineering consultation. Material construction and application requirements shape margin structures and vendor selection criteria across each segment.
Product Type:
Channel economics diverge sharply across product configurations. Wall-mounted and freestanding cabinets move through Grainger and W.W. Grainger-style industrial distributors with standardized lead times. Modular and portable configurations require direct vendor engagement for site assessment and custom engineering.
- Wall-Mounted Cabinets:Vertical enclosures secured to structural walls with reinforced mounting brackets and integrated spill containment sumps. Chemical processing facilities in Texas and Louisiana specify these for solvent dispensing stations where floor space constraints dominate layout decisions. OSHA's 2023 enforcement memorandum triggered immediate retrofit demand for non-compliant legacy installations.
- Freestanding Cabinets:Floor-supported steel enclosures with adjustable shelving and forklift pockets for relocation. Laboratories and educational institutions concentrate procurement here, driven by flexibility requirements and lower structural modification costs compared to wall-mounted alternatives.
- Portable Cabinets:Compact units with casters and reduced capacity ratings for temporary job site deployment. Construction and maintenance contractors represent primary demand channels.
- Modular Cabinets:Interconnecting units with shared ventilation and monitoring systems enabling phased facility expansion. Pharmaceutical manufacturers in sterile manufacturing environments drive specification complexity.
- Mobile Cabinets:Heavy-duty casters and braking systems for intra-facility transport of active process chemicals. Aerospace manufacturing cleanrooms specify corrosion-resistant configurations.
Freestanding cabinets dominate installed base. Modular cabinets are where expansion concentrates.
Material Construction:
Cost tiers stratify procurement decisions across material grades. Steel commands volume share through distributor channels at standard price points. Stainless steel and specialty materials require specification selling with extended sales cycles and engineering validation.
- Steel:Cold-rolled carbon steel with powder-coated exteriors and reinforced seams achieving standard fire-resistance ratings. Chemical processing facilities and automotive workshops drive volume procurement, though cold-rolled steel price volatility of 30-40 percent over 18-month windows compresses fabricator margins and destabilizes project bidding.
- Stainless Steel:304 or 316 grade with electropolished interiors and seamless coved corners for microbial elimination. FDA-registered pharmaceutical manufacturers specify these for solvent storage in aseptic environments as sterile manufacturing guidelines tighten material compatibility requirements.
- Polyethylene:Corrosion-resistant thermoplastic construction for aggressive acid and base storage where metal degradation risks exceed fire containment priorities. Electronics manufacturing cleanrooms utilize these for etchant chemical handling.
- Composite:Fiberglass-reinforced polymer systems combining chemical resistance with reduced weight for rooftop and mezzanine installations.
- Aluminum:Lightweight marine-grade construction for offshore oil and gas platforms where corrosion resistance and weight reduction compete with fire-rating requirements.
Steel sustains volume leadership across distributor channels. Stainless steel is climbing the fastest on pharmaceutical cleanroom expansion.
Application:
Customer type determines specification complexity and service bundling requirements. Chemical processing demands integrated compliance documentation. Educational institutions prioritize transactional procurement with basic certification packages.
- Chemical Processing Facilities:High-capacity arrays with distributed control system integration for hazardous material tracking. Texas and Louisiana petrochemical corridor expansions drive replacement cycles for aging cabinet infrastructure as EPA Risk Management Plan amendments mandate spill containment threshold upgrades.
- Laboratories:Precision specifications with fume hood integration and point-of-use ventilation. Research universities and contract research organizations concentrate demand.
- Educational Institutions:Standardized configurations meeting baseline OSHA compliance for chemistry department instructional labs. State procurement contracts dominate channel structure.
- Automotive Workshops:Solvent and parts washer fluid storage with emphasis on accessibility and rapid inventory turnover.
- Aerospace Manufacturing:Cleanroom-compatible stainless steel with particulate control and electrostatic discharge protection for solvent-based composite processing.
Chemical processing facilities anchor revenue concentration. Laboratories are gaining share fastest on biotech research expansion.
End User Industry:
Margin profiles diverge across end-use verticals. Oil and gas and chemicals prioritize total-cost-of-ownership contracts with service bundling. Food and beverage and electronics segments drive specification standardization.
- Chemicals & Petrochemicals:Large-scale deployments with 5-year total-cost-of-ownership agreements replacing capital purchase orders. Dow, DuPont, and BASF operations specify nationwide technician networks for annual NFPA 30 compliance audits.
- Pharmaceuticals:Electropolished stainless steel with FDA material compatibility validation and cleaning protocol documentation. Sterile manufacturing guidelines are tightening requirements for solvent storage in aseptic environments.
- Food & Beverage:Corrosion-resistant construction for flavoring solvent and cleaning agent storage with emphasis on washdown compatibility.
- Electronics:Precision capacity ratings for photoresist and etchant chemicals in semiconductor fabrication facilities.
- Oil & Gas:Explosion-proof specifications and offshore platform certifications with integrated inventory tracking for remote location supply management.
Chemicals and petrochemicals dominate installed base. Pharmaceuticals are where specification premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command 25-30 percent price premiums over Chinese volume producers for FM-certified cabinets, though automation is compressing this gap. The United States concentrates procurement volume through petrochemical corridor expansions. Asian supply bases anchor cost-competitive production for standard-grade specifications.
United States
Texas and Louisiana petrochemical corridors drive replacement cycles for aging cabinet infrastructure as EPA Risk Management Plan amendments mandate spill containment threshold upgrades. OSHA's 2023 enforcement memorandum compressed procurement timelines from 18 months to 90 days for non-compliant facilities. Houston-area ethylene crackers and derivative units require fire-rated storage arrays integrating with distributed control systems.
Germany
Precision engineering heritage sustains premium positioning in laboratory and chemical processing specifications across Baden-Württemberg and North Rhine-Westphalia industrial clusters. REACH compliance documentation and CE marking requirements shape export-oriented production for EU-wide distribution. BASF operations in Ludwigshafen specify nationwide technician networks for annual NFPA 30 compliance audits.
China
Yangtze River Delta and Pearl River Delta manufacturing bases anchor Asia-Pacific supply through integrated cold-rolled steel production and rapid custom fabrication turnaround. GB standards and SAMR certification pathways govern domestic market access. Shanghai SYSBEL Industry and Technology Co. Ltd. exemplifies the scale-driven fabrication archetype serving export markets.
India
Maharashtra and Gujarat chemical and pharmaceutical growth corridors attract fabricators establishing domestic capacity under PLI scheme benefits for capital goods production. CDSCO sterile manufacturing guidelines tighten material compatibility requirements for solvent storage in aseptic environments. Mumbai-Pune industrial belt procurement prioritizes corrosion-resistant configurations for coastal humidity exposure.
Flammable Storage Cabinets Market Competitive Landscape
Concentration sits with mid-cap specialists maintaining dual UL and FM certification portfolios. The vendor base spans three functional tiers: premium German engineering houses, high-volume Chinese fabricators, and North American full-service providers bundling installation with compliance auditing. Strategic differentiation centers on modular system architecture and integrated service contracts displacing transactional equipment sales. Geographic expansion and certification backlog management represent dominant competitive moves.
Among Germany-based engineering specialists, Asecos GmbH occupies a position exemplifying premium-tier precision manufacturing for laboratory and chemical processing specifications. Shanghai SYSBEL Industry and Technology Co. Ltd. anchors the Asia-Pacific volume production archetype through integrated steel supply chains. DENIOS Inc. represents the modular system architecture approach enabling facilities to reconfigure storage arrays without full replacement.
| Leading Market Players |
|---|
| Asecos GmbH |
| Shanghai SYSBEL Industry and Technology Co. Ltd. |
| Justrite Manufacturing Company |
| Vestil Manufacturing Corp |
| Securall A and A Sheet Metal Products |
| DENIOS Inc. |
| Eagle Manufacturing Company |
| Wuxi Huanawell Metal Manufacturing Co Ltd. |
| Kewaunee International Group |
| Others |
Pricing and Supply Chain Analysis
Scale economies in cold-rolled steel fabrication anchor price floors across certification tiers, with German precision houses commanding 25-30 percent premiums over Chinese volume producers as automation compresses historical capability gaps. Buyers face divergent cost structures depending on whether procurement routes through distributor channels for standardized specifications or engages fabricators directly for configured-to-order arrays with FM Global or UL validation.
Pricing Analysis
Configured-to-order pricing for modular stainless steel systems with electropolished interiors and integrated ventilation runs 15-40 percent above standard cold-rolled steel cabinets moving through industrial distributors. Three-tier pricing structure across premium, standard, and economy levels separates FM-certified pharmaceutical specifications from OSHA-compliant workshop grades and basic educational institutional units. Pricing pressure stems from cold-rolled steel input cost swings of 30-40 percent over 18-month windows, compressing fabricator margins and destabilizing large-scale project bidding. Educational institutions exhibit highest price sensitivity through state procurement contracts, while pharmaceutical manufacturers prioritize total-cost-of-ownership agreements with bundled compliance auditing over unit economics.
Supply Chain Analysis
China and Germany anchor global production capacity, with Yangtze River Delta and Pearl River Delta manufacturing bases supplying cost-competitive cold-rolled steel fabrications and Baden-Württemberg precision engineering houses serving premium laboratory specifications. Raw material dependencies center on cold-rolled steel coil, stainless steel 304/316 sheet, and electropolishing chemical inputs. Tariff exposure during trade friction episodes poses structural risk to buyers reliant on cross-border sourcing from concentrated premium production clusters. Distribution runs through Grainger-style industrial distributors for standardized wall-mounted and freestanding units, while modular systems require direct vendor engagement with site assessment and engineering consultation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA's 2023 enforcement memorandum on flammable liquids storage compressing procurement timelines from 18 months to 90 days creates a high-growth disruption window as non-compliant facilities face immediate replacement mandates. This regulatory inflection concentrates competitive advantage with vendors maintaining current UL and FM approvals alongside nationwide technician networks.
For Market Incumbents: Consolidate certification portfolio depth and technician network density to capture mandatory replacement cycles. Defensive moves center on accelerating FM Global thermal testing queue management to reduce 6-9 month certification backlogs, and expanding backward integration into cold-rolled steel supply to buffer margin compression from input volatility. Threat from substitute outdoor bulk tank farms with secondary containment berms limits cabinet penetration in greenfield chemical sites with sufficient real estate.
For New Entrants and Emerging Players: Lead with modular reconfiguration services and smart inventory integration as white-space entry vectors. India's Maharashtra and Gujarat chemical corridors under PLI scheme incentives represent the most penetrable geography, with domestic fabrication capacity serving CDSCO-sterile pharmaceutical growth and coastal corrosion-resistant specifications. Go-to-market angle targets 5-year total-cost-of-ownership contracts displacing transactional equipment sales at multinational manufacturing accounts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mid-cap specialists with dual UL/FM certification portfolios and field service infrastructure over pure-play fabricators. Long-term viability across the 5-10 year window rests on recurring revenue streams from compliance auditing and recertification services rather than equipment replacement cycles alone. Acquisition target archetype: vendors with modular system architecture and existing relationships with Dow, DuPont, or BASF procurement teams. Signal to watch: EPA Risk Management Plan amendment implementation pace in Texas and Louisiana driving spill containment threshold upgrade mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cold-Rolled Steel Supply | Mitigates 30-40 percent input cost volatility destabilizing project bidding for large-scale deployments. |
| FM Global Thermal Testing Queue Expansion | Reduces 6-9 month certification delays freezing procurement decisions for risk-averse buyers. |
| Smart Inventory Integration Development | RFID-enabled cabinets feeding real-time solvent levels into ERP systems command price premiums from multinationals. |
| India Domestic Capacity Establishment | PLI scheme benefits for capital goods production capture South Asian chemical and pharmaceutical growth corridors. |
| Integrated Service Contract Bundling | 5-year total-cost-of-ownership agreements with nationwide technician networks displace transactional sales at Dow, DuPont, BASF. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant managers, procurement leads at downstream chemical processors, distribution channel partners, and aftermarket service heads; and secondary validation through OSHA enforcement memoranda, EPA Risk Management Plan amendments, FM Global data sheets, NFPA 30 standards, and SEC 10-K filings from listed industrial equipment manufacturers. Bottom-up triangulation across product type, material construction, and application segments converged with top-down demand estimation from petrochemical corridor expansion announcements and pharmaceutical cleanroom buildout tracking.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across product configuration, material grade, end-use industry, and regional production hub. CAGRs derived from regression analysis against regulatory enforcement intensity, capital expenditure cycles in named chemical processing corridors, and replacement demand from aging cabinet infrastructure. Industry-specific forecast inputs incorporated welding technician labor pool contraction rates and electropolishing process technology diffusion curves.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement intensity, stable cold-rolled steel input pricing, or continued petrochemical corridor densification would require recalibration. Forecasts reflect assumptions around certification body testing protocol stability and pharmaceutical sterile manufacturing guideline evolution. Recalibration cycles align with material shifts in EPA Risk Management Plan enforcement schedules and FM Global thermal testing capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Personal Protective Equipment Packaging Market
Safety Equipment and Personal Protective Equipment (PPE)
Bullet Proof Jackets Market
Safety Equipment and Personal Protective Equipment (PPE)
Cargo Security Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Laser Safety Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Wearable Airbag Belt Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
US Negative Pressure Escape Masks Market