
 Protective Mask Market | 2026-2036
Protective Mask Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Mask Market Analytics
A shortage of certified filtration engineers is reorganizing how manufacturers allocate technical talent across production lines. 3M leverages its captive melt-blown polymer capacity to sustain domestic supply continuity. Honeywell International anchors North American industrial distribution through its respiratory safety channel network. Kimberly-Clark competes in healthcare institutional contracts with specialized surgical mask portfolios.
Protective masks are personal respiratory devices engineered with multi-layer nonwoven media, typically incorporating melt-blown polypropylene between spunbond outer layers, designed to filter airborne particulates, droplets, or toxic vapors depending on assigned protection factor. N95 respirators occupy the premium tier due to NIOSH certification complexity and healthcare procurement rigor, while cloth mask demand has matured among general public segments with minimal regulatory oversight. Industrial application growth concentrates in construction and manufacturing settings where OSHA permissible exposure limits mandate respiratory program compliance.
OSHA, NIOSH, and FDA standards collectively determine product classification, testing protocols, and market access pathways for respiratory protective equipment in the United States. The European Union's PPE Regulation and REACH chemical restrictions similarly constrain material formulations and import eligibility for CE-marked devices. Stakeholders must monitor evolving harmonization between national certification regimes to anticipate supply chain reconfiguration costs.
Market Dynamics
Melt-blown polypropylene supply concentration in East Asia is forcing manufacturers to reconfigure polymer sourcing strategies and accelerate captive capacity investments across North American and European production footprints.
Growth Catalysts
- NIOSH Certification Mandates:OSHA respiratory protection standards in the United States require healthcare institutions to maintain N95 inventory minimums, institutionalizing recurring procurement volumes.
- Construction Sector Expansion:Industrial buyers in Germany are scaling FFP-class respirator orders as silica dust exposure limits tighten across European building codes.
- Electrospun Nanofiber Media:Advanced filtration layer technologies are penetrating premium healthcare segments by achieving sub-micron capture efficiency without compromising breathability.
Market Restraints
- Polypropylene Price Volatility:Propylene feedstock fluctuations transmit directly to melt-blown nonwoven input costs, compressing margin stability for mid-tier manufacturers.
- Single-Source Concentration:South Korean and Chinese suppliers dominate high-grade electret charging equipment, creating equipment access bottlenecks for new market entrants.
- Biodegradability Limitations:Polypropylene's chemical stability prevents composting pathways, exposing producers to extended producer responsibility frameworks under EU packaging regulations.
Strategic Opportunities
- Indian Industrial Safety Penetration:BIS certification requirements for respiratory protective equipment are expanding addressable demand among manufacturing SMEs previously served by unstandardized alternatives.
- Wearable Sensor Convergence:Integration of particulate exposure monitoring electronics with respirator hardware creates value-added positioning for industrial safety programs.
- Subscription-Based Inventory Management:Healthcare procurement teams are piloting automated replenishment contracts that guarantee supply continuity against pandemic disruption scenarios.
Industry Challenges
- Filtration Engineer Scarcity:Certified specialists capable of optimizing electret charge retention and pressure drop trade-offs command premium compensation, constraining R&D throughput.
- NIOSH Approval Timelines:New respirator submissions face 12-18 month evaluation queues, delaying product commercialization and freezing capital in pre-revenue inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Mask Market |
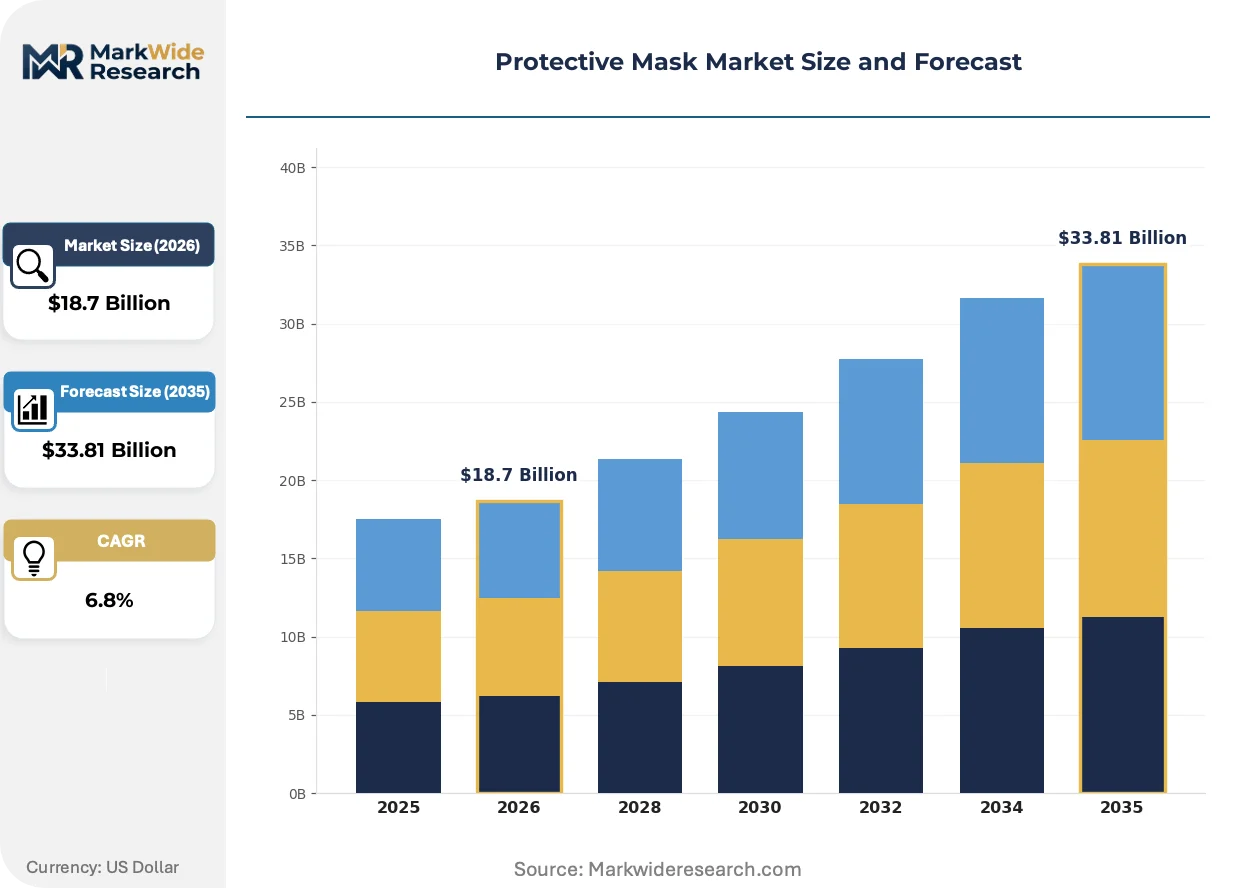
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: N95, Surgical, Cloth, Respirator Application: Healthcare, Industrial, Construction, Public Health End User: Healthcare Professionals, General Public, Workers, Students Material: Polypropylene, Cotton, Polyester, Foam |
| Companies Covered | 3M, Honeywell International, Kimberly-Clark, Cardinal Health, UVEX Group, MSA Safety, Moldex-Metric, DuPont, Shanghai Dasheng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Mask Market Evolving Landscape
Filtration architecture is fragmenting across performance tiers as end-users demand application-specific optimization rather than universal respirator designs.
Electrospun nanofiber membranes are decomposing the traditional melt-blown monopoly in high-efficiency layers. Healthcare procurement teams in the United States are qualifying these materials for surgical N95 alternatives. The technology is compressing the performance gap between industrial and medical-grade respirators while enabling thinner, cooler-wearing designs.
REACH chemical restrictions are forcing reformulation of mask adhesives, nose foams, and elastic components across European supply chains. Manufacturers are substituting phthalate-based plasticizers with bio-derived alternatives to maintain CE marking eligibility. Medical device and industrial PPE segments face divergent compliance timelines, with surgical mask producers absorbing earlier certification burdens.
Hospital purchasing cooperatives are consolidating vendor rosters to secure volume discounts and supply guarantees. Group purchasing organizations are displacing direct manufacturer relationships for mid-sized health systems. This concentration is most visible in the southeastern United States, where regional GPOs have captured substantial acute care procurement volume.
Protective Mask Market Segmentation
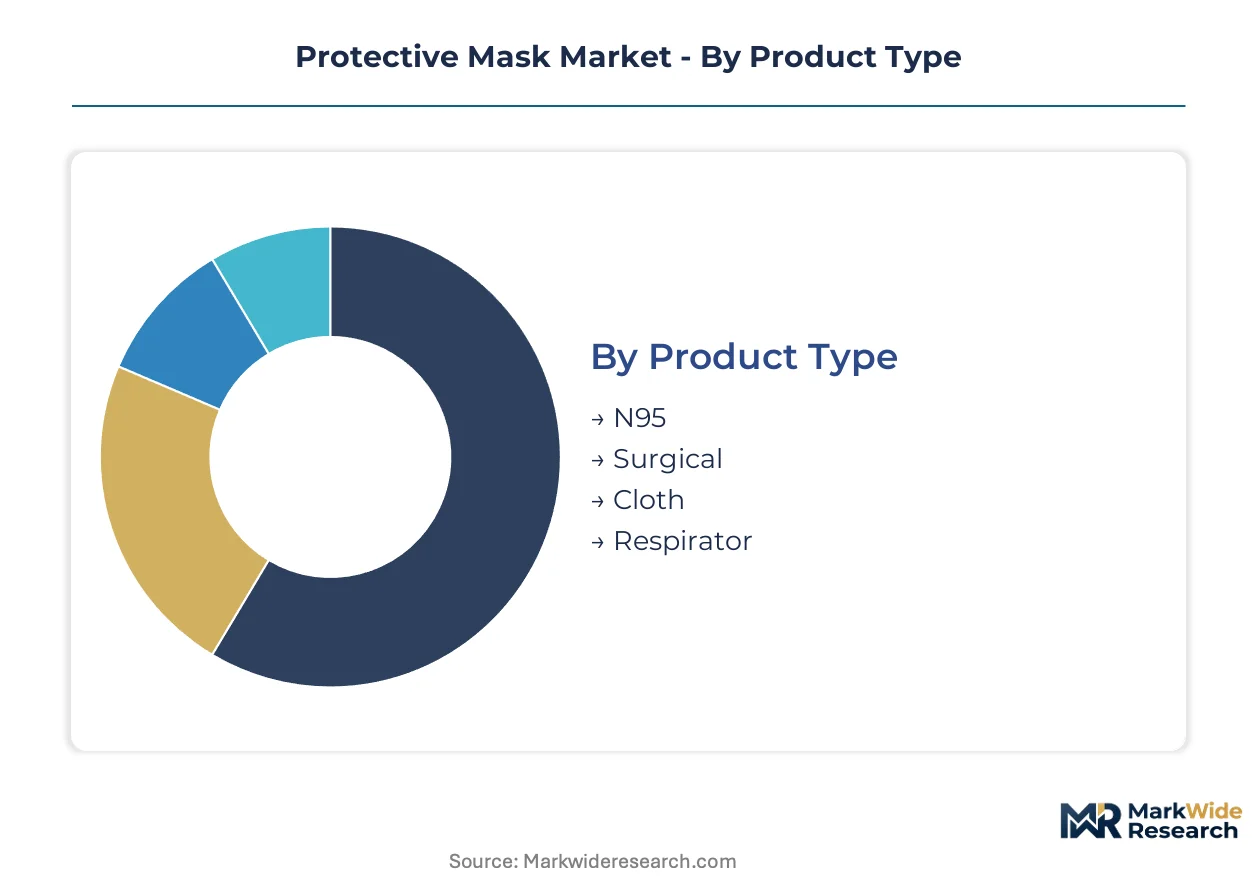
Protective mask purchasing patterns diverge sharply across use contexts, with certification requirements and exposure risk levels creating distinct demand pools that resist cross-substitution. Manufacturers must align production capacity to these discrete segments rather than treating masks as a uniform commodity category.
Product Type:
Substitution pressure concentrates most intensely on cloth masks, which face displacement from both regulated respirators in professional settings and fashion-oriented alternatives in consumer markets.
- N95:Multi-layer polypropylene construction with electrostatically charged melt-blown filtration media meeting NIOSH 42 CFR Part 84 standards. Healthcare procurement teams in the United States maintain these as minimum inventory under OSHA respiratory protection mandates, creating institutionalized recurring demand despite per-unit cost premiums.
- Respirator:Reusable elastomeric facepieces with replaceable filter cartridges designed for industrial chemical and particulate exposure. German industrial buyers concentrate FFP-class orders here as REACH compliance tightens material sourcing requirements for single-use alternatives.
- Surgical:Three-ply nonwoven barriers meeting ASTM F2100 fluid resistance standards for medical procedure protection. Demand concentrates in hospital purchasing cooperatives seeking standardized supply contracts.
- Cloth:Woven or knitted textile face coverings with minimal regulatory oversight and highly variable filtration performance. General public demand has matured with pandemic transition, leaving this segment exposed to fashion accessory substitution.
N95 respirators anchor the volume base in professional procurement while electrospun nanofiber alternatives gain share at the steepest rate in premium healthcare segments.
Application:
Margin structures compress most severely in public health deployment, where bulk purchasing and minimal technical specifications eliminate pricing power.
- Healthcare:Acute care, surgical suites, and long-term facilities requiring FDA-cleared or NIOSH-approved respiratory protection. OSHA permissible exposure limits and Joint Commission accreditation standards institutionalize compliance-driven procurement.
- Industrial:Manufacturing and chemical processing environments where OSHA respiratory program mandates govern fit testing and cartridge replacement protocols. Silica dust and vapor exposure regulations in Germany and the United States sustain replacement filter demand.
- Construction:Building sites and renovation projects subject to crystalline silica exposure limits. European building code tightening accelerates FFP-class adoption among contractors previously relying on basic dust masks.
- Public Health:Community transmission mitigation and institutional bulk distribution with minimal performance verification. Demand volatility here reflects policy shifts rather than enduring exposure control requirements.
Industrial application anchors the volume base through regulatory compliance mandates while construction sector procurement climbs the fastest as silica exposure standards tighten across jurisdictions.
End User:
Volume concentration skews toward institutional buyers with standardized procurement protocols, leaving individual consumer segments fragmented across retail channels.
- Healthcare Professionals:Physicians, nurses, and ancillary staff subject to employer-mandated respiratory protection programs. Fit testing requirements and medical surveillance obligations create switching costs that lock in approved supplier relationships.
- Workers:Industrial and construction employees covered by OSHA or national equivalent respiratory protection standards. German employers bear explicit duty-of-care obligations under national occupational safety frameworks.
- General Public:Individual consumers purchasing through retail and e-commerce channels with minimal technical guidance. Preference formation here follows price and comfort rather than verified protection factors.
- Students:Educational institution populations subject to district or campus-level masking policies. Demand concentration depends on administrative mandate continuity rather than individual choice.
Healthcare professionals anchor the volume base through institutional procurement contracts while worker segments expand most quickly as developing economies formalize occupational safety enforcement.
Material:
Supply concentration in East Asian polypropylene production creates input cost vulnerability that material diversification strategies seek to mitigate.
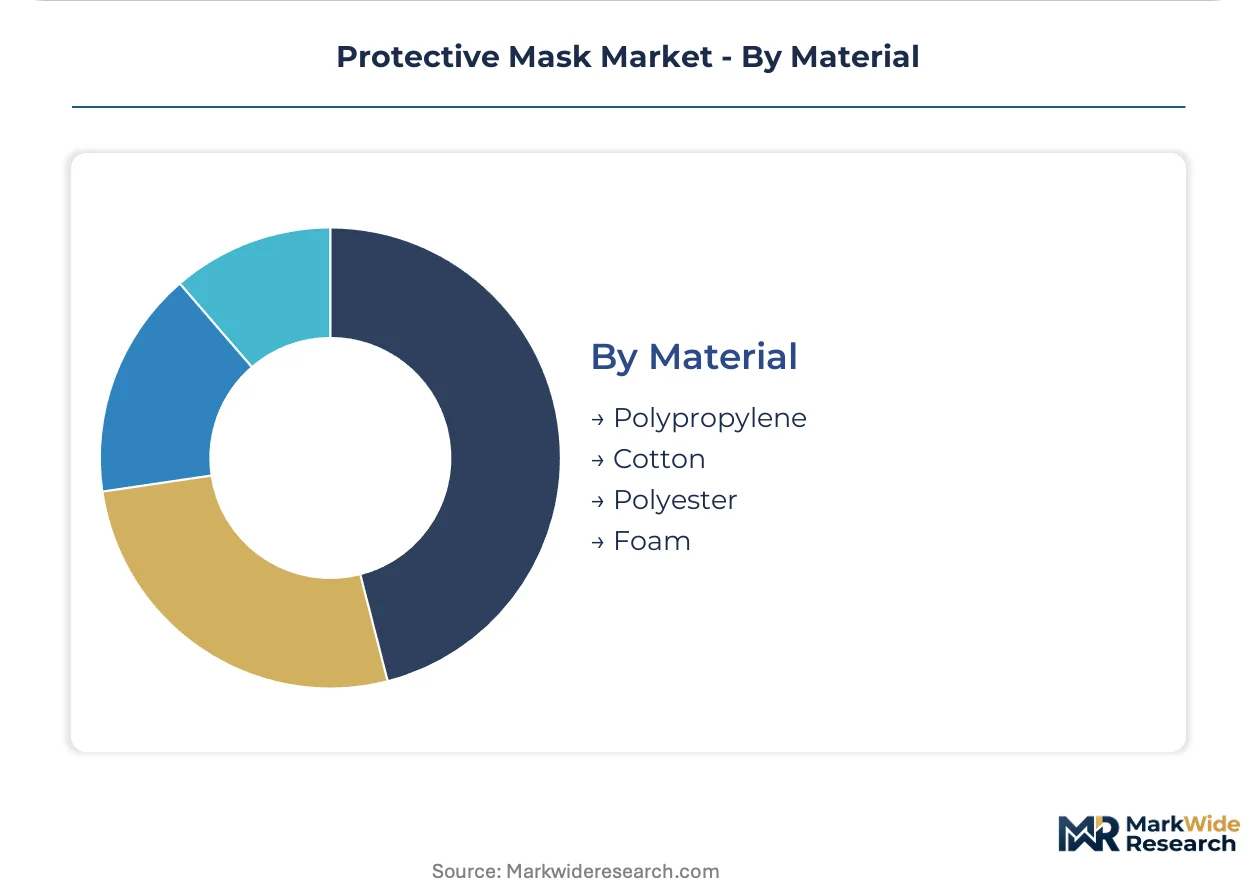
- Polypropylene:Spunbond and melt-blown nonwoven layers forming the technical core of N95 and surgical mask construction. Electret charging dependency leaves this material exposed to equipment access bottlenecks from South Korean and Chinese suppliers.
- Cotton:Natural fiber woven into reusable cloth mask designs with comfort advantages but limited sub-micron filtration efficiency. Biodegradability appeals to EU packaging regulation compliance strategies.
- Polyester:Synthetic fiber employed in blended textile constructions and some nonwoven applications. REACH chemical restrictions constrain phthalate-based additive formulations in European supply chains.
- Foam:Polyurethane or latex materials forming nose cushions and sealing surfaces in elastomeric respirators. Adhesive reformulation pressures under EU chemical regulations accelerate bio-derived substitute qualification.
Polypropylene anchors the volume base through technical performance requirements while cotton gains share fastest in consumer segments prioritizing sustainability signaling over verified protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA anchors the dominant geography through respiratory protection mandates that institutionalize N95 procurement volumes across acute care networks. Supply chain reconfiguration accelerates as manufacturers diversify melt-blown polymer sourcing beyond East Asian concentration. Regional demand patterns diverge sharply across certification regimes and exposure control standards.
United States
Healthcare procurement teams maintain N95 inventory minimums under Joint Commission accreditation pressure. FDA 510(k) clearance pathways govern surgical mask market access while NIOSH certification timelines constrain new respirator commercialization. The southeastern hospital purchasing cooperative cluster concentrates acute care contract consolidation.
Germany
Industrial buyers scale FFP-class respirator orders as silica dust exposure limits tighten across building codes. REACH compliance restricts phthalate-based additives in mask adhesives and elastic components. The Ruhr industrial corridor anchors respiratory safety program adoption among manufacturing employers.
China
Domestic electret charging equipment suppliers dominate high-grade filtration machinery access. GB standards and NMPA medical device registration govern product classification for export eligibility. The Yangtze River Delta melt-blown nonwoven production cluster supplies raw material to regional fabricators.
India
BIS certification requirements expand addressable demand among manufacturing SMEs previously served by unstandardized alternatives. The central government's occupational safety enforcement formalization drives institutional procurement. Maharashtra's Pune-Aurangabad industrial belt concentrates respiratory protection program adoption.
Japan
METI industrial safety guidelines sustain replacement filter demand in chemical processing and electronics manufacturing. JIS standards alignment with international certification regimes reduces export friction for domestic manufacturers. The Kansai manufacturing corridor anchors elastomeric respirator utilization in heavy industry.
Protective Mask Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in protective mask supply. Consolidated polymer-to-product manufacturers command input cost advantages while mid-tier fabricators compete on regional certification speed. Three archetypes dominate: captive melt-blown producers, respiratory safety channel specialists, and healthcare institutional contract holders. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure electret charging equipment access.
Within the integrated leader tier, 3M and Honeywell International exemplify polymer-backward positioning that insulates margin stability from propylene feedstock swings. Shanghai Dasheng occupies a position among Asia-Pacific fabricators navigating GB standard export compliance. UVEX Group represents the European specialist archetype concentrated on REACH-aligned material formulations. These anchors illustrate how geographic certification specialization fragments competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| 3M |
| Honeywell International |
| Kimberly-Clark |
| Cardinal Health |
| UVEX Group |
| MSA Safety |
| Moldex-Metric |
| DuPont |
| Shanghai Dasheng |
| Others |
Value Network & Pricing Analysis
Captive melt-blown polymer capacity in North America and Europe anchors margin stability for integrated manufacturers while forcing mid-tier fabricators toward price-competitive positioning. N95 respirators command sustained premiums through NIOSH certification scarcity, whereas surgical mask procurement consolidates under hospital purchasing cooperative pressure. Polypropylene feedstock volatility transmits directly to nonwoven input costs, compressing flexibility for manufacturers without backward integration.
Pricing Analysis
Trans-Pacific price spreads between East Asian-sourced melt-blown media and domestically produced alternatives exceed 30% for comparable electret grades. Three-tier pricing structure across N95 premium, surgical standard, and cloth economy levels stratifies by certification burden and volume commitment. Pricing pressure stems from propylene feedstock volatility and REACH-compliant adhesive reformulation costs. Healthcare procurement teams demonstrate lowest price sensitivity due to Joint Commission compliance mandates, while general public segments prioritize unit cost over verified protection factors.
Supply Chain Analysis
Container availability constraints on the Shanghai-Long Beach trade lane elevate inbound logistics costs for electret charging equipment and high-grade filtration machinery. Melt-blown polypropylene supply concentrates in China, South Korea, and Taiwan, with the Yangtze River Delta anchoring raw material output. Production draws from propylene feedstock, spunbond nonwoven substrates, and South Korean electret charging systems. Single-source vulnerability in electret equipment access creates qualification bottlenecks for new market entrants. Distribution runs through respiratory safety channel networks for industrial segments and group purchasing organizations for healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Filtration architecture fragmentation across application-specific tiers creates specialist niches as end-users abandon universal respirator designs. Electrospun nanofiber penetration and REACH-driven material reformulation reward agile manufacturers with certification speed.
For Market Incumbents: Fortify captive melt-blown capacity positions through North American and European footprint expansion to offset East Asian supply concentration. Deepen hospital purchasing cooperative relationships through automated replenishment contract pilots that guarantee N95 inventory continuity. Electret charging equipment access represents the critical lever for sustaining technical differentiation against nanofiber substitutes. For New Entrants and Emerging Players: Differentiate on REACH-aligned bio-derived adhesive formulations for European CE marking eligibility as incumbents absorb reformulation costs. Target Indian manufacturing SMEs transitioning from unstandardized alternatives under formalizing BIS enforcement. Pursue wearable sensor convergence for industrial safety programs as the most penetrable value-added positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors filtration media specialists with electrospun nanofiber qualification progress and electret equipment access agreements. Long-term viability hinges on material diversification beyond polypropylene and regulatory harmonization capture. Watch NIOSH approval timeline compression as the signal for capital efficiency inflection in new respirator commercialization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Melt-Blown Capacity Expansion | Insulates margin stability from propylene feedstock volatility and East Asian supply disruption. |
| Electrospun Nanofiber Qualification | Enables thinner, cooler-wearing designs that compress the industrial-medical performance gap. |
| REACH-Compliant Material Reformulation | Maintains CE marking eligibility as ECHA restrictions tighten phthalate-based additive prohibitions. |
| Automated Replenishment Contract Pilot | Secures hospital purchasing cooperative volume against pandemic disruption scenarios. |
| Wearable Sensor Integration | Creates particulate exposure monitoring value-add for OSHA-mandated industrial safety programs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with filtration engineers, hospital procurement managers, industrial safety officers, and respiratory protection program administrators. Secondary validation drew from FDA 510(k) filings, NIOSH certification databases, OSHA regulatory dockets, and ECHA REACH restriction proposals. Bottom-up capacity and shipment estimates triangulated against top-down healthcare expenditure and industrial PPE procurement data.
Across the analysis window, volume and value outputs reflect segmentation by product type, application context, end-user archetype, and material composition. CAGRs were derived from trend extrapolation of N95 inventory mandates, silica exposure limit tightening, and nanofiber penetration curves. Forecast inputs incorporated BIS certification expansion timelines and electret equipment access bottlenecks.
The analysis sits within stated boundaries; outcomes outside sustained OSHA enforcement, REACH implementation continuity, or electret charging equipment supply stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization progress and polymer feedstock volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Global Respiratory Protection Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Protective Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Light Curtains Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Particulate Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Digital Camlock Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Personal Protective Equipment Kit Market
Safety Equipment and Personal Protective Equipment (PPE)
Booster Seat Type Child Safety Seats Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market