
 Smart Seat Belt Technology Market | 2026-2036
Smart Seat Belt Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Seat Belt Technology Market Analysis
Project finance tied to automotive safety platform rollouts is narrowing the field of viable competitors in smart seat belt development. Autoliv Inc. leverages its vertically integrated sensor manufacturing to sustain cost advantages across OEM contracts. ZF Friedrichshafen AG anchors European supply through its integrated mechatronics division, while Joyson Safety Systems competes aggressively on volume scale in Asia-Pacific assembly partnerships.
Smart seat belt technology encompasses electromechanical restraint systems integrating force-limited retractors, webbing pretensioners, and multi-axis occupant sensors to enable real-time crash response adaptation. These systems employ woven polyester webbing with embedded conductive threads and piezoelectric strain gauges to measure torso position and belt tension with millisecond latency, primarily serving collision mitigation and post-crash emergency response functions. Sensor-based technology leads current revenue contribution due to its established regulatory compliance pathway, while AI-powered systems represent the fastest-growing segment as neural-network-driven occupant classification enables predictive pretensioning before impact detection. The OEM end-user channel captures the dominant margin pool through long-term platform contracts, though aftermarket providers are gaining share in fleet retrofit applications.
NHTSA's Federal Motor Vehicle Safety Standard 208 and 209 requirements shape baseline product specifications for the US market, while ECE R16 regulations administered by European type-approval authorities govern webbing strength and retractor performance across EU member states. Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces compatible standards through its Motor Vehicle Type Approval system, creating a triad of compliance frameworks that manufacturers must navigate simultaneously. Stakeholders should monitor how divergent crash-test protocols between these jurisdictions influence R&D allocation and platform standardization decisions.
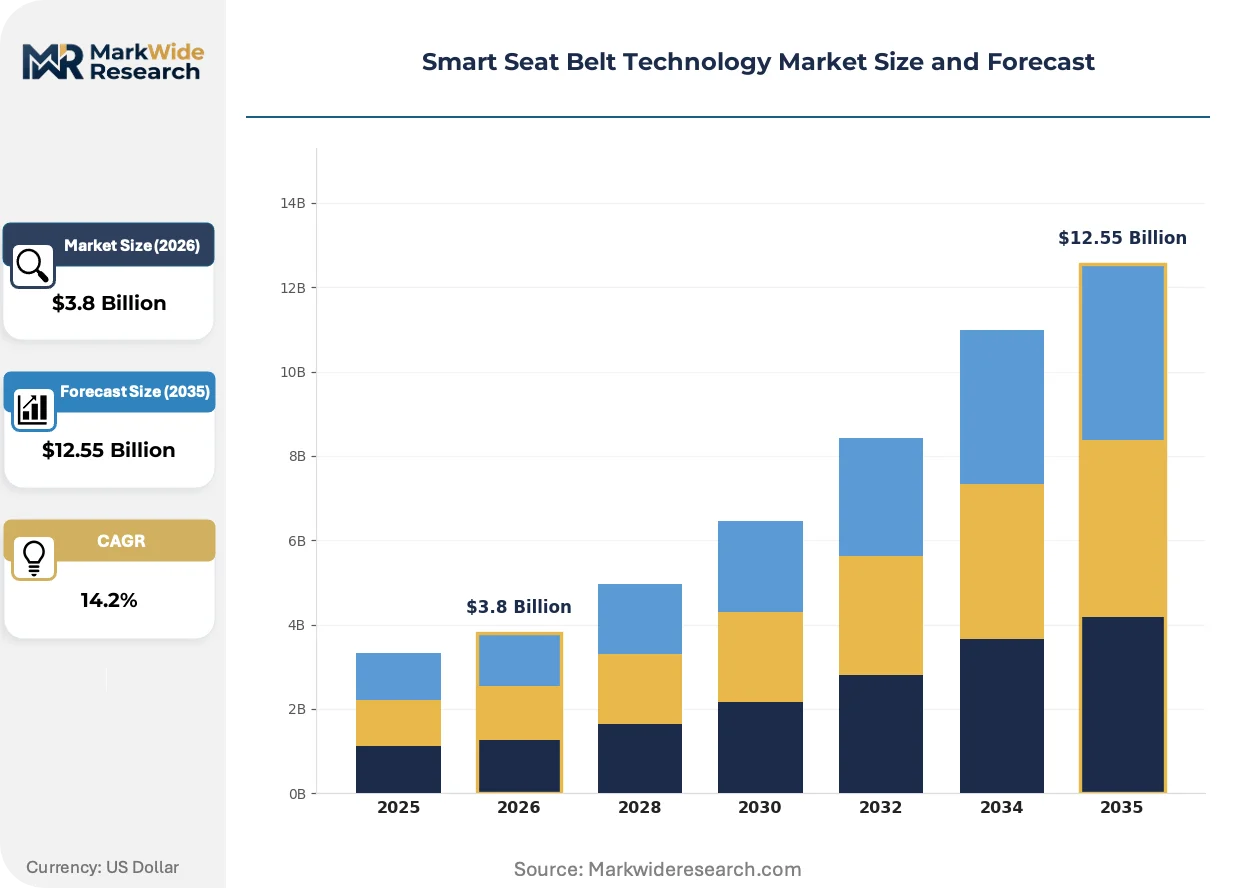
Market Dynamics
OEM platform consolidation around advanced driver-assistance systems is compressing supplier qualification timelines while elevating sensor integration requirements for seat belt architectures.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 208:Mandates for automatic emergency locking retractors are compelling Tier 1 suppliers to accelerate electromechanical system development for North American vehicle platforms.
- Piezoelectric strain gauge integration:Embedded conductive thread technology enables millisecond-latency occupant position sensing, unlocking predictive pretensioning capabilities previously confined to luxury segments.
- German production clustering:Stuttgart and Wolfsburg anchor concentrated R&D investment for force-limited retractor systems serving premium European OEMs with integrated mechatronics supply chains.
Market Restraints
- Woven polyester webbing supply concentration:Specialized conductive textile production remains captive to a narrow base of European and Japanese material suppliers, creating input bottlenecks during platform ramp cycles.
- ECE R16 type-approval divergence:European webbing strength testing protocols differ materially from NHTSA FMVSS 209 requirements, forcing dual-certification investments that extend development timelines.
- Legacy mechanical retractor substitution:Cost-optimized vehicle programs in emerging markets continue specifying conventional emergency locking retractors, capping smart system penetration in volume segments.
Strategic Opportunities
- Fleet retrofit channel development:Commercial vehicle operators in the United States are deploying aftermarket sensor-based restraint systems to reduce liability exposure and insurance premiums.
- AI-powered occupant classification:Neural network algorithms trained on multi-axis sensor fusion are enabling predictive crash response before impact detection, creating premium pricing headroom.
- Japan's Motor Vehicle Type Approval alignment:METI's convergence toward UN ECE regulatory frameworks is reducing certification friction for suppliers targeting both European and Japanese OEM platforms.
Industry Challenges
- Mechatronics systems integration talent scarcity:The convergence of mechanical retractor engineering with embedded sensor firmware development is outpacing available cross-functional engineering capacity.
- Dual-jurisdiction certification timelines:Simultaneous NHTSA and ECE R16 homologation processes extend platform qualification cycles by 8-14 months, compressing program margin windows.
- Legacy vehicle electrical architecture compatibility:Retrofitting smart belt systems into existing CAN bus configurations requires proprietary gateway modules that fragment supplier interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Seat Belt Technology Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Seat Belts, Adjustable Seat Belts, Smart Seat Belts, Automatic Seat Belts End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Manufacturers Technology: Sensor-Based, IoT-Enabled, AI-Powered, Wearable Integration Application: Passenger Vehicles, Commercial Vehicles, Military Vehicles, Autonomous Vehicles |
| Companies Covered | Autoliv Inc., Continental AG, ZF Friedrichshafen AG, DENSO Corporation, Ashimori Industry Co., Ltd, Joyson Safety Systems, Hyundai Mobis, ITW Safety, GWR Safety Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Seat Belt Technology Market Emerging Trajectories
Electromechanical restraint architectures are converging with occupant sensing platforms, compressing the boundary between passive safety and active collision mitigation systems.
Webbing-integrated piezoelectric sensor arrays are hybridizing traditional polyester restraint materials with real-time biomechanical monitoring capabilities. Tier 1 suppliers serving German and Japanese OEMs are embedding conductive thread matrices at commercial scale. This material evolution is hybridizing the cost structure of premium and standard restraint tiers, eroding historical segmentation.
Japan's Ministry of Land, Infrastructure, Transport and Tourism is accelerating Motor Vehicle Type Approval harmonization with UN ECE technical prescriptions. This regulatory convergence reduces redundant testing burdens for suppliers qualified under European frameworks. Japanese OEMs with integrated European platform strategies are consolidating supplier pools to capture certification efficiency gains.
Commercial fleet operators are unbundling safety system procurement from vehicle acquisition cycles, creating dedicated retrofit channel demand. Third-party installers in the United States are capturing margin previously retained by OEM captive service networks. This channel fragmentation is most pronounced in long-haul trucking segments where liability-driven safety investment exceeds OEM standard specification.
Smart Seat Belt Technology Market Segmentation
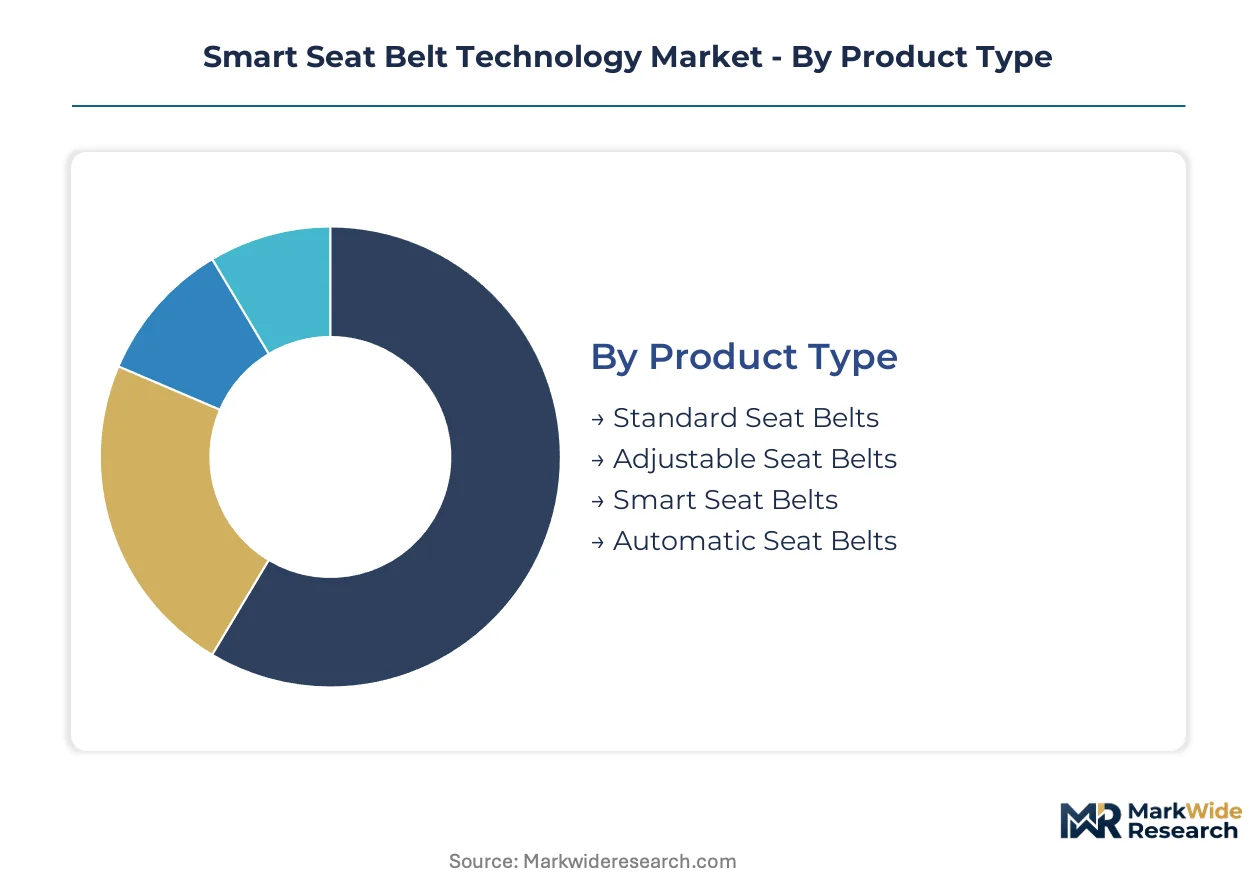
Smart seat belt architectures fragment across four distinct dimensions that determine procurement patterns and margin structures. Product type reflects the maturity spectrum from mechanical to electromechanical systems. Technology segmentation tracks the shift from reactive restraint to predictive occupant protection platforms.
Product Type:
Mature mechanical configurations anchor volume production while electromechanical variants command premium positioning through integrated sensing capabilities.
- Standard Seat Belts:Three-point lap-and-shoulder configurations using woven polyester webbing and emergency locking retractors. Demand concentrates in emerging market vehicle programs where cost optimization overrides advanced safety specification, though NHTSA FMVSS 208 baseline compliance still mandates automatic locking functionality.
- Smart Seat Belts:Electromechanical systems embedding piezoelectric strain gauges and conductive thread matrices for real-time occupant position monitoring. German and Japanese OEM procurement is accelerating for premium platform integration, driven by predictive pretensioning requirements in advanced driver-assistance system architectures.
- Adjustable Seat Belts:Height-adjustable D-ring configurations with manual or motorized positioning.
- Automatic Seat Belts:Motorized shoulder belt systems with passive lap belt integration.
Standard Seat Belts handle the majority of throughput; Smart Seat Belts are expanding most quickly on share.
End User:
Procurement authority determines specification depth, with long-term platform contracts creating divergent margin pools across the value chain.
- OEMs:Vehicle manufacturers integrating restraint systems at platform design phase. Stuttgart and Wolfsburg production clusters anchor European demand, where multi-year supply agreements lock in sensor-based system specifications across premium brand portfolios.
- Aftermarket Providers:Third-party distributors and installers serving fleet retrofit applications. United States commercial trucking operators are driving channel growth through liability-driven safety upgrades independent of OEM acquisition cycles.
- Tier-1 Suppliers:Integrated mechatronics specialists managing subsystem development for OEM qualification.
- Vehicle Manufacturers:Captive production facilities with in-house restraint system integration.
OEMs capture the dominant margin pool; Aftermarket Providers are climbing the fastest on volume contribution.
Technology:
Functional sophistication tiers separate regulatory-compliant baseline systems from predictive platforms enabling pre-crash response.
- Sensor-Based:Multi-axis accelerometers and strain gauges measuring belt tension and occupant position with millisecond latency. Established ECE R16 and NHTSA certification pathways make this the default specification for current platform rollouts across European and North American supply chains.
- AI-Powered:Neural network algorithms processing sensor fusion inputs to enable predictive pretensioning before impact detection. Japanese OEMs with integrated European platform strategies are consolidating supplier pools around these systems to capture harmonized type-approval efficiency gains.
- IoT-Enabled:Connected restraint systems transmitting occupant status data to vehicle telematics platforms.
- Wearable Integration:Biometric monitoring interfaces linking seat belt sensors to personal health devices.
Sensor-Based technology dominates current procurement; AI-Powered systems show the steepest expansion trajectory.
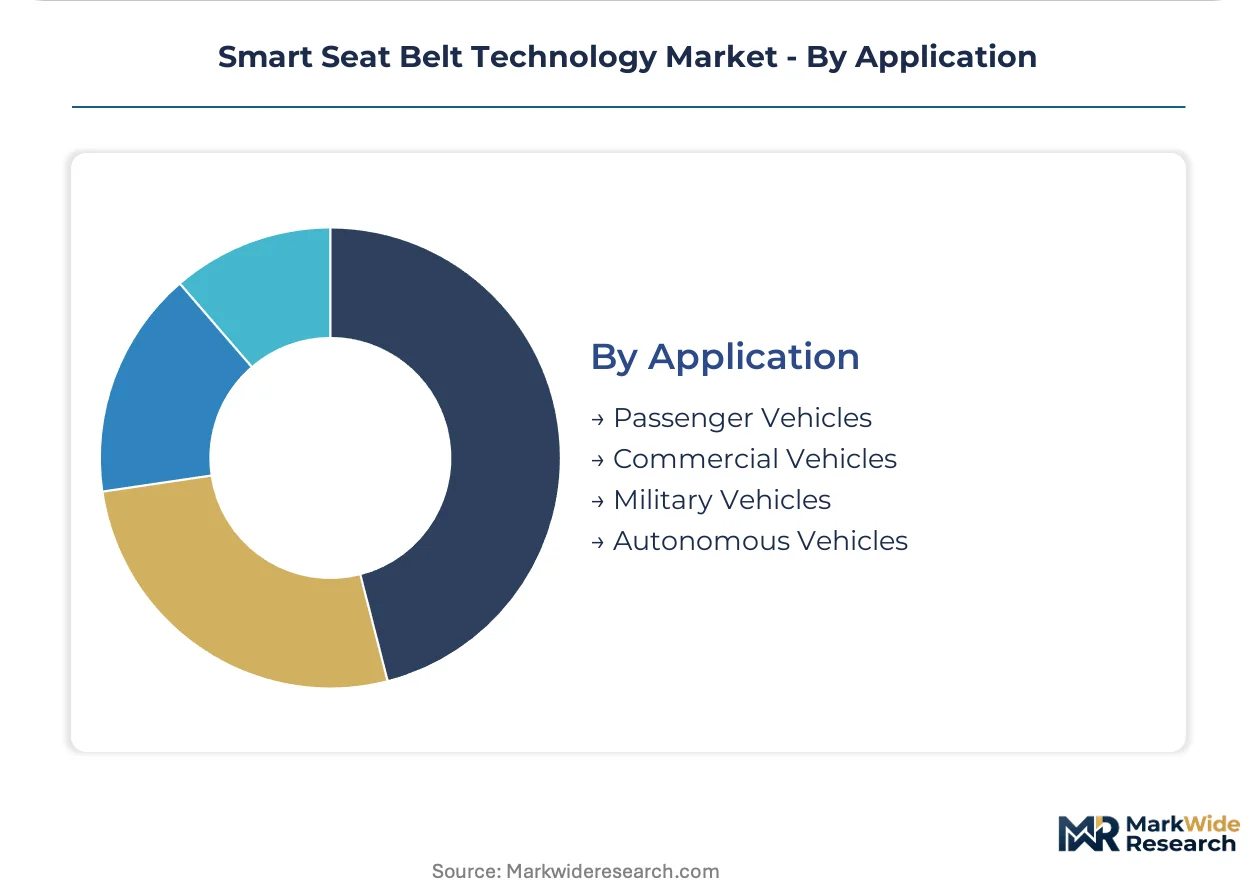
Application:
Vehicle use case determines occupant sensing complexity and regulatory scrutiny intensity across deployment scenarios.
- Passenger Vehicles:Light-duty automotive applications with front and rear occupant protection requirements. German premium brand platforms are driving specification escalation through integrated advanced driver-assistance system architectures that demand predictive restraint response.
- Commercial Vehicles:Long-haul trucking and fleet applications with elevated liability exposure. United States fleet operators are unbundling safety procurement from vehicle acquisition, creating dedicated retrofit channel demand for sensor-based restraint upgrades.
- Military Vehicles:Tactical platforms with blast-resistant occupant protection specifications.
- Autonomous Vehicles:Self-driving platforms with non-traditional seating configurations and occupant monitoring requirements.
Passenger Vehicles absorb the majority of unit volume; Commercial Vehicles are gaining share fastest through fleet retrofit conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of smart seat belt components concentrate in German and Japanese manufacturing clusters, while import demand accelerates in North American and Chinese assembly markets. The United States maintains a structural deficit in electromechanical retractor systems, sourcing advanced sensor-integrated units from European Tier-1 suppliers. Regulatory divergence between NHTSA and ECE frameworks fragments certification pathways, elevating the strategic value of dual-qualified production facilities.
United States
NHTSA's updated FMVSS 208 mandates for automatic emergency locking retractors are compelling domestic automakers to accelerate electromechanical system procurement. The regulator's crash-test protocols differ materially from European standards, forcing dual-certification investments that extend supplier qualification timelines. Detroit-area assembly plants anchor North American demand, with Tier-1 distributors managing inbound supply from Stuttgart and Wolfsburg production clusters.
Germany
Autoliv and ZF Friedrichshafen anchor concentrated R&D investment for force-limited retractor systems serving premium European OEM portfolios. ECE R16 type-approval administered by KBA governs webbing strength and retractor performance, creating a compliance framework that Japanese regulators are gradually harmonizing toward. Stuttgart and Wolfsburg production clusters serve as the primary export base for sensor-based restraint systems bound for North American and Asian assembly plants.
Japan
METI's convergence toward UN ECE regulatory frameworks is reducing certification friction for suppliers targeting both European and Japanese OEM platforms. DENSO Corporation and Ashimori Industry occupy positions within the integrated mechatronics supply chain serving domestic automakers with global platform strategies. The Kanto region around Tokyo anchors sensor manufacturing and type-approval testing infrastructure for occupant detection systems.
China
Domestic vehicle manufacturers are accelerating specification of smart restraint systems as MIIT strengthens occupant protection requirements under evolving GB standards. Joyson Safety Systems has established production scale within Asia-Pacific assembly partnerships, competing on volume against European and Japanese incumbents. The Yangtze River Delta region concentrates webbing textile production and electromechanical component assembly for both domestic consumption and regional export.
South Korea
Hyundai Mobis represents the domestic anchor for smart belt system integration within Hyundai-Kia global platform architectures. MFDS alignment with international type-approval frameworks facilitates component export to European and North American markets. The Seoul Capital Area concentrates R&D investment for predictive pretensioning algorithms and multi-axis sensor fusion technologies.
Smart Seat Belt Technology Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated mechatronics specialists capable of managing sensor firmware development alongside mechanical retractor engineering. Three archetypes dominate competitive positioning: European heritage suppliers with captive textile production, Asian scale manufacturers competing on assembly volume, and integrated safety platform specialists leveraging advanced driver-assistance system convergence. M&A activity concentrates on sensor technology acquisition, while strategic partnerships with semiconductor foundries secure piezoelectric component supply.
Within the European heritage tier, Autoliv Inc., ZF Friedrichshafen AG, and Continental AG exemplify the vertically integrated model combining in-house webbing production with electromechanical system integration. These entities occupy positions where regulatory compliance depth and platform contract longevity create defensive moats against Asian volume competitors. Joyson Safety Systems and DENSO Corporation represent the Asia-Pacific scale archetype, with geographic positioning enabling cost-optimized supply to regional assembly partnerships. Hyundai Mobis anchors Korean competitive presence through captive relationships with domestic OEM global platforms.
| Leading Market Players |
|---|
| Autoliv Inc. |
| Continental AG |
| ZF Friedrichshafen AG |
| DENSO Corporation |
| Ashimori Industry Co., Ltd |
| Joyson Safety Systems |
| Hyundai Mobis |
| ITW Safety |
| GWR Safety Systems |
| Others |
Supply Flow & Price Mechanics
Woven polyester webbing production concentrates in European and Japanese textile clusters, anchoring margin capture for conductive thread suppliers while OEM procurement teams absorb volatility through long-term offtake agreements. This upstream concentration funnels pricing power toward material specialists, compressing assembler margins during platform ramp cycles.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. ECE R16 and NHTSA dual-certification investments command 15-20% premiums over single-jurisdiction systems. Cost compression in standard mechanical retractor tiers is intensifying because emerging market OEMs specify baseline emergency locking configurations. Fleet retrofit operators exhibit highest price sensitivity, while German premium OEMs prioritize predictive pretensioning performance over unit cost.
Supply Chain Analysis
Export controls on piezoelectric sensor technology limit component flows from Japanese and German specialists to Chinese assemblers, fragmenting supplier interoperability. Geographic supply concentrates in Germany, Japan, and China, with Stuttgart and Wolfsburg anchoring force-limited retractor production. The chain draws from conductive textile mills, semiconductor foundries, and mechatronics integrators. Single-source vulnerability runs through European conductive thread suppliers. Distribution runs through Tier-1 subsystem specialists into OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart seat belt technology sits in early-cycle expansion as AI-powered occupant classification penetrates from luxury into mid-tier vehicle platforms. NHTSA's updated emergency locking retractor mandates accelerate replacement demand across North American fleet operators.
For Market Incumbents: Build certification-depth moats by securing simultaneous ECE R16 and NHTSA homologation capabilities before dual-jurisdiction timelines extend further. Deepen backward integration into piezoelectric sensor firmware development to defend against semiconductor foundry allocation constraints. Lock in multi-year platform contracts with German OEMs consolidating supplier pools around harmonized type-approval efficiency.
For New Entrants and Emerging Players: Build out aftermarket fleet retrofit channels in the United States, where commercial trucking operators unbundle safety procurement from OEM acquisition cycles. Target sensor-based restraint upgrades for long-haul segments with elevated liability exposure. Pursue partnerships with third-party installers capturing margin previously retained by captive service networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European heritage suppliers possessing captive textile production and established regulatory compliance pathways. Five-to-ten year viability hinges on convergence toward AI-powered predictive systems displacing reactive architectures. Monitor Japanese METI alignment with UN ECE frameworks as signal for certification friction reduction enabling cross-regional platform consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | German OEMs consolidate supplier pools around unified sensor-integrated architectures serving multiple vehicle classes. |
| Sensor Technology Acquisition | Piezoelectric strain gauge specialists command premium valuations as neural-network pretensioning requirements escalate. |
| Geographic Manufacturing Footprint | Dual-qualified production facilities in Stuttgart and Wolfsburg reduce NHTSA-ECE certification timeline compression. |
| Software-Defined Vehicle Investment | CAN bus gateway modules enable retrofit compatibility with legacy electrical architectures in commercial fleets. |
| Long-term Supply Agreement | Conductive textile offtake contracts with European and Japanese mills secure input availability during platform ramps. |
Methodological Framework
The analysis maps electromechanical restraint architectures, sensor-based occupant detection platforms, and AI-powered predictive systems, each validated through Tier-1 supplier procurement leads, OEM platform engineers, aftermarket fleet operators, and regulatory affairs specialists at NHTSA and KBA. Primary interview findings triangulate against vehicle production databases, IHS Markit registration data, SEC filings from listed safety system suppliers, and customs records of conductive textile trade flows. Bottom-up unit economics and top-down market sizing converge through iterative stakeholder feedback.
Assumption sets hold NHTSA FMVSS 208 enforcement timelines and ECE R16 harmonization progress within observed regulatory patterns across the analysis window. Segmentation dimensions span product type maturity, technology sophistication tier, OEM versus aftermarket procurement channel, and vehicle application class. CAGRs derive from platform contract visibility, content-per-vehicle trajectories, and replacement cycle analysis. Forecast inputs incorporate sensor fusion algorithm development curves and piezoelectric component yield rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian scale manufacturers or accelerated AI pretensioning adoption by Japanese OEMs would shift outcomes. Material shifts in NHTSA-ECE regulatory divergence or conductive textile supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Body Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Premium Motorcycle Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
UAE Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
China Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Gowns Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Grade Medical Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market