
 Protective Snowmobile Gear Market | 2026-2036
Protective Snowmobile Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Protective Snowmobile Gear Market Insights
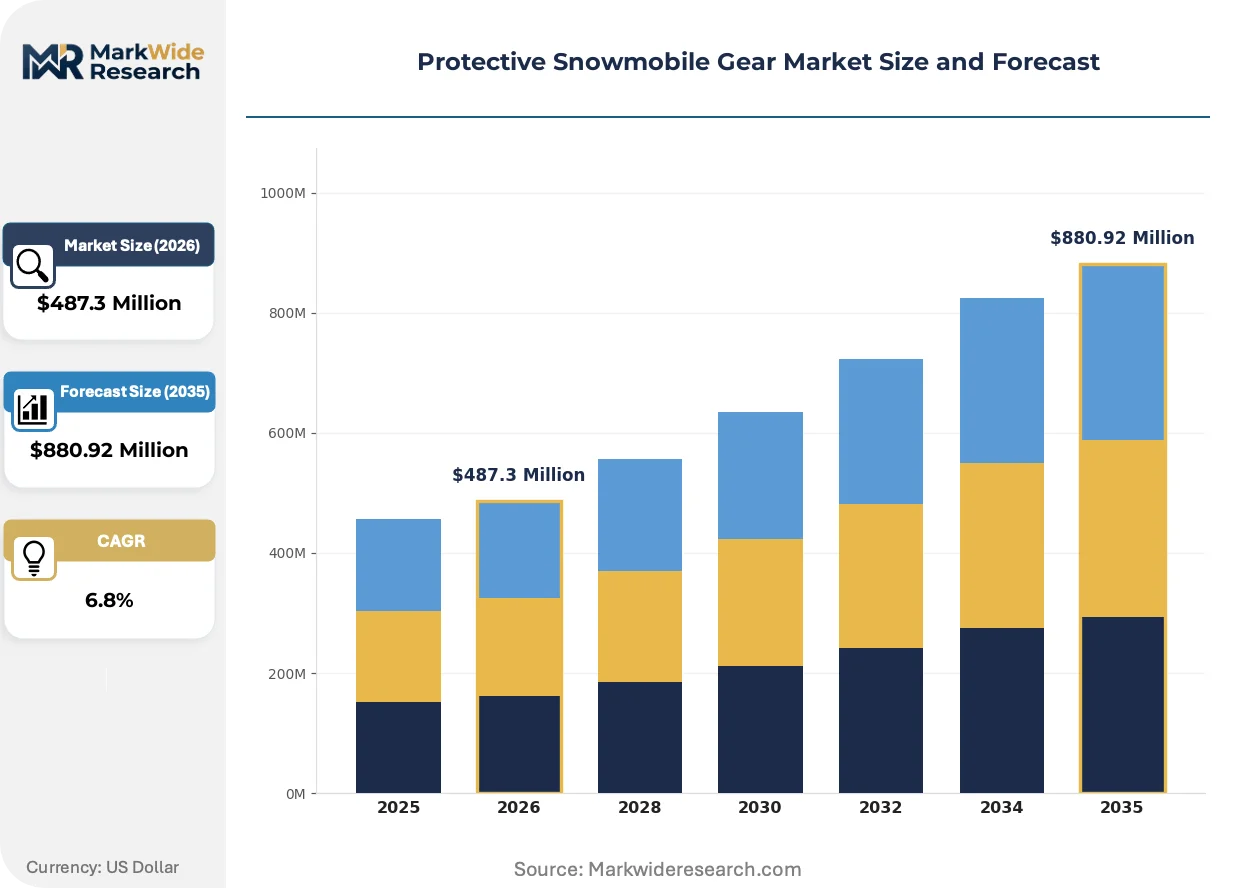
CE Level 2 protective certification is collapsing the gap between premium and mid-tier snowmobile gear as riders demand hospital-grade impact absorption at accessible price points. KLIM leverages proprietary D3O armor integration to sustain its dominance in backcountry suits. FXR Racing anchors its position through proprietary F.A.S.T. insulation technology that competes directly with traditional down systems. Castle X differentiates via aggressive channel control across Canadian and upper Midwest dealerships.
Protective snowmobile gear encompasses engineered apparel and equipment designed to shield operators from cold-induced injury, high-speed impact, and environmental exposure during motorized oversnow travel. Helmets incorporate multi-density EPS liners bonded to polycarbonate or carbon fiber shells, with chin bars rated to ASTM F2040 or Snell standards. Suits and gloves integrate waterproof-breathable membranes with synthetic insulation to maintain thermal equilibrium across temperature differentials exceeding 60°C. The helmets segment leads absolute revenue due to mandatory-use laws across most jurisdictions, while waterproof-breathable feature sets command the fastest expansion as riders extend seasons into marginal snow conditions. EVA-based boot liners are displacing traditional felt constructions where moisture management determines comfort duration.
FDA oversight of Class I medical devices intersects with snowmobile gear where cold-weather protective equipment interfaces with trauma care protocols in remote rescue scenarios. ASTM International publishes F2040 for snow sports helmets while CE marking governs European market access through EN 1077 alpine standards adapted for motorized use. The Consumer Product Safety Commission monitors recall patterns for drawstring and fastening hazards in children's snowmobile apparel. Stakeholders must monitor evolving state-level mandatory helmet legislation and insurance-premium tie-ins that directly influence replacement-cycle frequency and specification tier selection.
Market Dynamics
CE Level 2 certification is compressing the premium-mid tier gap as riders demand hospital-grade impact absorption without paying flagship prices, forcing armor suppliers to recalibrate cost structures across all product lines.
Growth Catalysts
- ASTM F2040 helmet mandates:State-level mandatory-use legislation in Minnesota, Wisconsin, and Michigan accelerates replacement cycles as riders upgrade to certified units to avoid insurance premium penalties.
- D3O smart material integration:Non-Newtonian polymer armor enables thinner, lighter protection layers that maintain flexibility at rest while hardening on impact, expanding adoption beyond racing into recreational segments.
- Trail-access program expansion:Provincial and state-funded groomed trail networks across Ontario, Quebec, and the upper Midwest convert casual landowners into registered riders requiring full protective kits.
Market Restraints
- Petrochemical input volatility:Polycarbonate shell production and synthetic insulation manufacturing face feedstock cost swings that compress margin stability for mid-tier suppliers.
- Canadian manufacturing concentration:Premium suit assembly clusters in Quebec and Manitoba create geographic vulnerability to winter labor disruptions and cross-border tariff friction.
- CE certification timeline friction:EN 1077 adaptation for motorized use adds 8-14 months to product launch schedules, freezing development capital in testing phases.
Strategic Opportunities
- Marginal snow condition riding:Waterproof-breathable membrane technology opens season extension in Scandinavia and the Baltic states where freeze-thaw cycles previously limited equipment utility.
- Direct-to-rider digital channels:Subscription-based gear refresh programs bypass traditional dealership networks, capturing younger riders in Alberta and British Columbia who prioritize convenience over in-person fitting.
- US Forest Service trail modernization grants:Federal infrastructure investment in interconnected trail systems expands addressable rider populations in Montana, Idaho, and Wyoming.
Industry Challenges
- Multi-density EPS molding expertise scarcity:Helmet liner fabrication requires specialized thermoforming technicians concentrated in legacy automotive supply regions, creating recruitment bottlenecks for expanding manufacturers.
- ASTM-to-CE dual certification complexity:Products targeting both North American and European distribution must satisfy divergent impact testing protocols, doubling validation costs and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protective Snowmobile Gear Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Boots, Suits, Gloves Material: Nylon, Neoprene, Leather, EVA End User: Recreational Riders, Professionals, Rentals, Competitors Feature: Waterproof, Insulated, Lightweight, Breathable |
| Companies Covered | Polaris Industries Inc., BRP Inc., FXR Racing, KLIM, Castle X, Arctic Cat Inc., Alpinestars, 509 Inc., Fox Racing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protective Snowmobile Gear Market Trends and Innovations
Material science convergence with connected safety systems is redefining what protective gear monitors and mitigates, shifting competitive advantage from passive cushioning to active hazard response.
Non-Newtonian polymer armor is decomposing the traditional trade-off between flexibility and protection density. Recreational riders in Minnesota and Wisconsin are adopting CE Level 2 vests at three times the rate of legacy foam-based alternatives. This material shift is compressing the premium tier's historical insulation from mid-market competition.
REACH chemical restrictions on per- and polyfluoroalkyl substances are forcing membrane manufacturers to reformulate durable water repellent coatings. European suppliers face 2025 compliance deadlines that require full chemistry redesigns. The waterproof-breathable segment is responding with bio-based alternatives that sacrifice some hydrostatic head performance for regulatory clearance.
Season-extension behavior is fragmenting the traditional fall purchase window. Riders in Michigan and Ontario now acquire gear across four quarterly intervals rather than the historical pre-winter surge. Specialty retailers are unbundling helmet-glove-suit bundles to capture these distributed transactions, while direct brands deploy climate-triggered digital campaigns timed to regional freeze-thaw patterns.
Protective Snowmobile Gear Market Segmentation
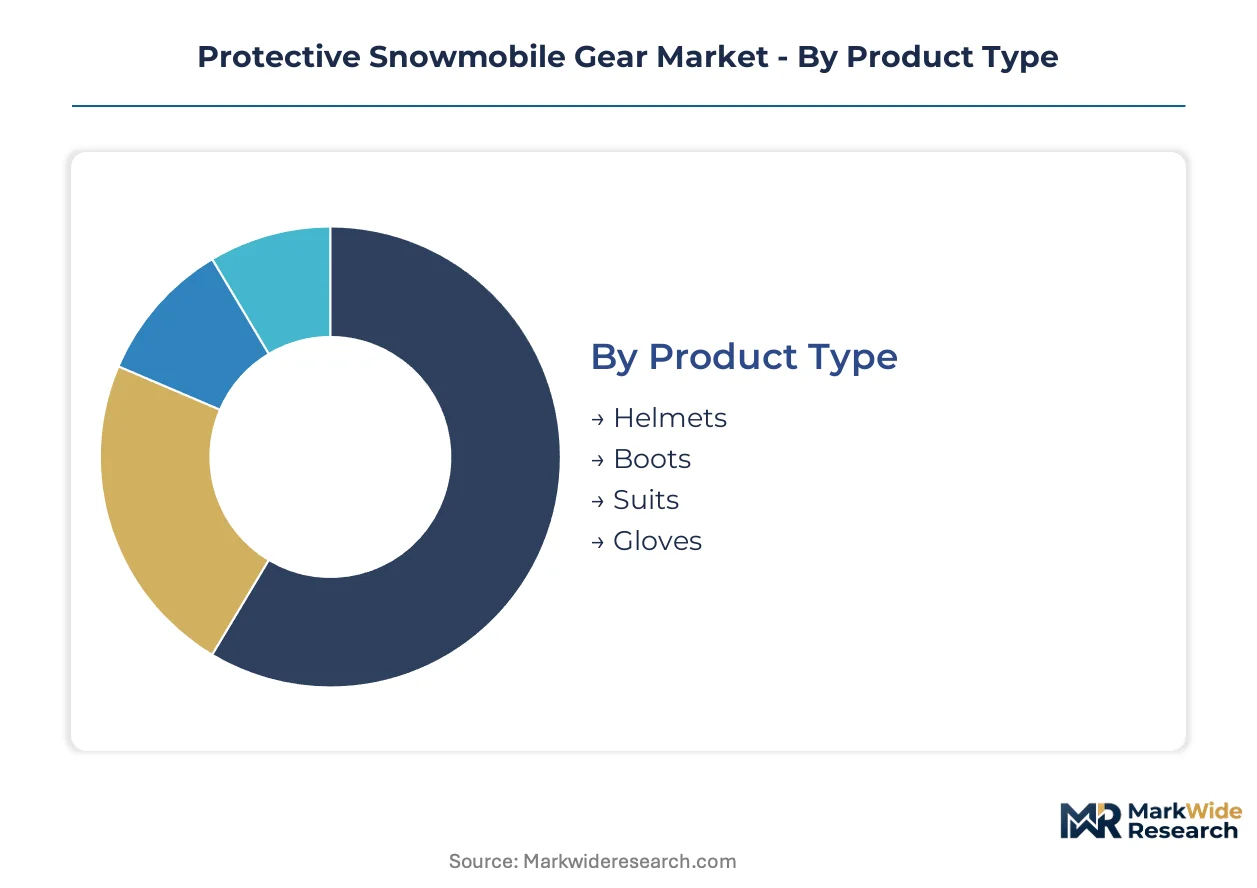
Protective snowmobile gear segments fracture along regulatory compliance tiers and riding intensity levels. ASTM F2040 and CE marking requirements create divergent specification paths that reshape procurement patterns across product categories.
Product Type:
ASTM F2040 mandates in Minnesota, Wisconsin, and Michigan concentrate replacement demand in certified helmet architectures while other categories follow voluntary upgrade cycles.
- Helmets:Multi-density EPS liners bonded to polycarbonate or carbon fiber shells must satisfy ASTM F2040 or Snell chin-bar standards for trail access in high-registration states. Mandatory-use legislation accelerates replacement frequency as insurers penalize non-compliant riders.
- Suits:Waterproof-breathable membranes with synthetic insulation maintain thermal equilibrium across temperature differentials exceeding 60°C. Backcountry riders in Alberta and British Columbia prioritize CE Level 2 armor integration for hospital-grade impact absorption.
- Boots:EVA-based liners displace traditional felt where moisture management determines comfort duration in marginal snow conditions.
- Gloves:Waterproof-breathable constructions with synthetic insulation address season-extension demand in Scandinavia and the Baltic states.
Helmets handle the majority of throughput; suits are the fastest mover on share as armor technology compresses premium-mid tier gaps.
Material:
REACH chemical restrictions on per- and polyfluoroalkyl substances force reformulation of durable water repellent coatings across membrane-dependent materials.
- Nylon:Dominates suit and glove shells with waterproof-breathable laminates. European suppliers face compliance deadlines requiring full chemistry redesigns for 2025 regulatory clearance.
- EVA:Boot liner material displacing felt constructions through superior moisture management and thermal retention in freeze-thaw cycling conditions.
- Neoprene:Seals and gasket applications in glove wrist closures and boot ankle cuffs for splash protection.
- Leather:Reinforced palm and knuckle overlays in competition gloves where abrasion resistance supersedes thermal priorities.
Nylon commands the largest volume position; EVA is expanding most quickly as boot manufacturers abandon legacy felt supply chains.
End User:
Trail-access program expansion across Ontario, Quebec, and the upper Midwest converts casual participants into registered riders requiring full protective kits.
- Recreational Riders:Fastest-expanding buyer segment as provincial and state-funded groomed trail networks extend season length. Quarterly purchase intervals replace historical pre-winter surges.
- Professionals:Guide services and patrol operations in Montana, Idaho, and Wyoming require fleet-standardized gear meeting US Forest Service trail modernization grant specifications.
- Rentals:Tourism operators in Michigan and Wisconsin prioritize durability and simplified sizing over performance optimization.
- Competitors:Racing circuits demand Snell-certified helmets and CE Level 2 armor exceeding baseline ASTM requirements.
Recreational riders generate the steepest volume climb; professionals maintain the most predictable replacement cadence.
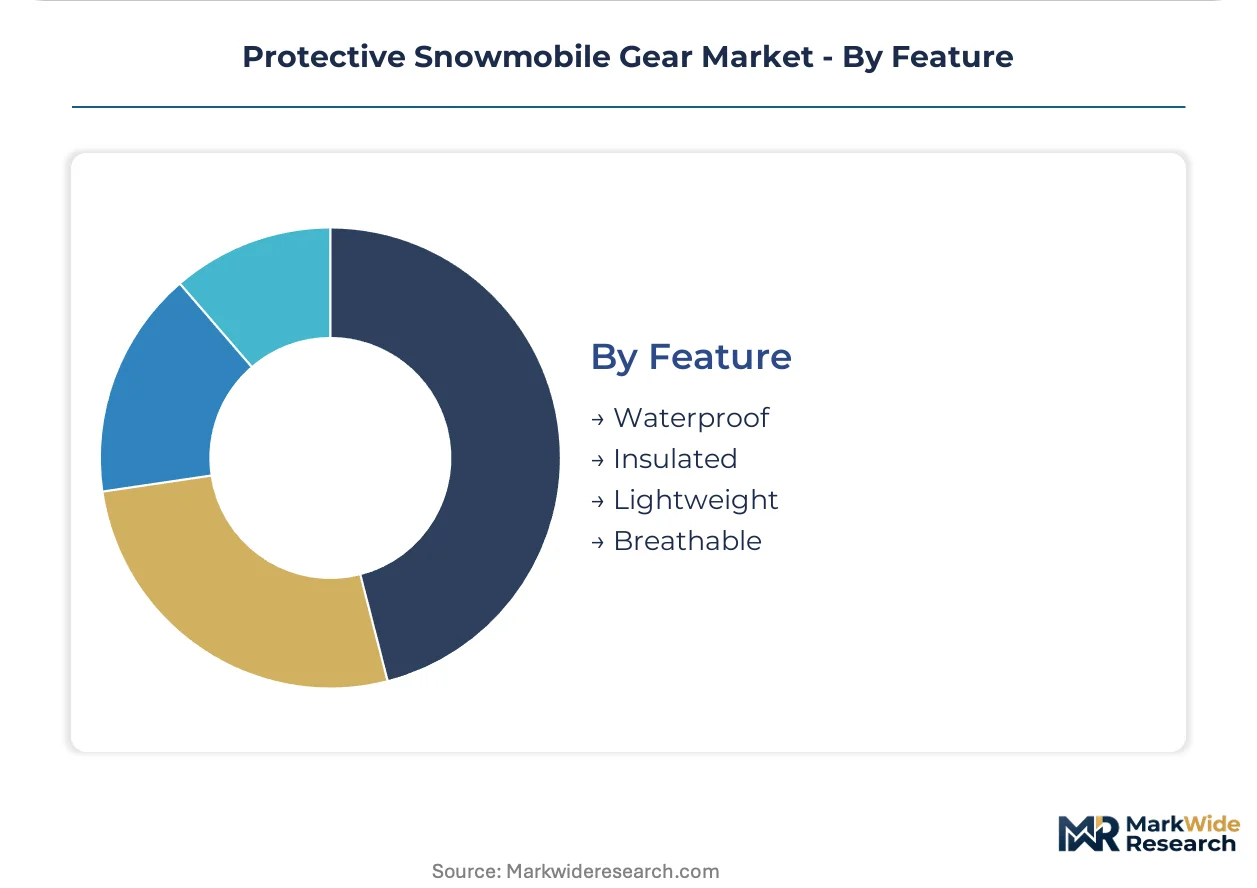
Feature:
Climate-triggered purchase behavior fragments traditional fall buying windows as riders respond to regional freeze-thaw patterns.
- Waterproof:Hydrostatic head performance thresholds determine utility in marginal snow conditions. Bio-based alternatives sacrifice some performance for REACH compliance.
- Breathable:Moisture vapor transmission rates govern comfort duration during high-exertion riding. Season-extension behavior concentrates demand in this specification tier.
- Insulated:Synthetic fill power and loft retention compete with traditional down systems in sub-zero temperature differentials.
- Lightweight:D3O smart material integration enables thinner protection layers without sacrificing impact absorption density.
Waterproof specifications anchor baseline procurement; breathable feature sets are gaining share fastest as season extension becomes standard behavior.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Minnesota and Wisconsin show the highest price elasticity for mid-tier gear, while Alberta and British Columbia riders absorb premium pricing for backcountry-rated equipment without volume decline.
United States
Minnesota, Wisconsin, and Michigan account for the densest concentration of registered snowmobiles and trail-access program participation. ASTM F2040 helmet mandates in these states accelerate replacement cycles as insurers penalize non-compliant riders. Manufacturing clusters in the upper Midwest supply domestic demand while facing petrochemical input volatility.
Canada
Ontario and Quebec trail networks convert casual landowners into registered riders requiring full protective kits. Health Canada oversees product safety standards that align with provincial insurance frameworks. Premium suit assembly concentrates in Quebec and Manitoba, creating geographic vulnerability to winter labor disruptions.
Sweden
Freeze-thaw cycling in Scandinavia drives waterproof-breathable membrane demand for season-extension riding. REACH chemical restrictions on per- and polyfluoroalkyl substances force 2025 compliance deadlines requiring full chemistry redesigns. Stockholm-based distributors are unbundling traditional helmet-glove-suit bundles to capture quarterly purchase intervals.
Norway
Backcountry riding culture supports premium CE Level 2 armor adoption at rates exceeding North American recreational segments. ECHA enforcement of durable water repellent coating reformulations pressures membrane manufacturers. Bergen and Trondheim retail clusters serve as Nordic distribution hubs for marginal-snow-condition equipment.
Finland
Cross-border trail connectivity with Sweden and Norway expands addressable rider populations requiring standardized protective specifications. CE marking governs market access through EN 1077 alpine standards adapted for motorized use. Helsinki-area logistics nodes manage Baltic state re-export of compliant gear.
Protective Snowmobile Gear Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with armor integration specialists commanding premium positioning while volume fabricators compete on channel density. The market structures around three tiers: integrated powersports OEMs with captive gear divisions, independent technical apparel houses with proprietary material science, and regional distributors with aggressive dealership control. Consolidation pressure runs through ASTM-to-CE dual certification complexity, which favors players with capital to absorb doubled validation timelines. Geographic expansion and portfolio diversification represent the dominant competitive vectors as players chase trail-access program growth across provincial and state boundaries.
Among North American powersports OEMs, Polaris Industries Inc. and BRP Inc. occupy positions that leverage captive vehicle sales channels to bundle protective gear at point of purchase. FXR Racing and KLIM exemplify the independent technical apparel archetype, with the former representing Canadian manufacturing concentration and the latter anchoring backcountry-rated specification tiers. Castle X sits within the regional distribution specialist tier, with channel control strategies focused on upper Midwest and Canadian dealership networks.
| Leading Market Players |
|---|
| Polaris Industries Inc. |
| BRP Inc. |
| FXR Racing |
| KLIM |
| Castle X |
| Arctic Cat Inc. |
| Alpinestars |
| 509 Inc. |
| Fox Racing |
| Others |
Pricing and Supply Chain Analysis
Quebec and Manitoba manufacturing clusters concentrate premium suit assembly capacity, creating scale economies that compress unit costs for CE Level 2 certified gear while simultaneously elevating price floors for mid-tier competitors lacking comparable throughput. This geographic concentration of specialized labor and thermoforming equipment lets integrated players defend margin structures that fragmented assemblers cannot replicate.
Pricing Analysis
ASTM F2040 and CE marking dictate the pricing tier structure across helmet and armor categories, separating premium certified units from uncertified economy alternatives. Three-tier pricing stratifies across hospital-grade impact absorption, recreational-grade compliance, and entry-level discretionary purchase tiers. Cost compression in mid-tier suits is intensifying because REACH chemical restrictions force membrane reformulation investments that smaller fabricators cannot absorb. Recreational riders in Minnesota and Wisconsin exhibit the highest price elasticity, while Alberta backcountry operators absorb premium positioning without volume decline.
Supply Chain Analysis
Great Lakes port congestion and cross-border customs clearance at Detroit-Windsor chokepoints constrain just-in-time delivery schedules for Quebec-manufactured goods entering US distribution networks. Manufacturing concentrates in Quebec, Manitoba, and upper Midwest states where winter labor availability fluctuates with seasonal migration patterns. Polycarbonate shell production draws from petrochemical feedstocks concentrated in Texas and Alberta refining corridors, creating exposure to commodity price swings. Tariff exposure on finished goods crossing the US-Canada border elevates landed cost unpredictability. Distribution runs through captive OEM dealership networks, independent powersports retailers, and emerging direct-to-rider digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern anchored to trail-access program funding cycles and state-level infrastructure investment waves that convert latent landowner interest into registered rider demand.
For Market Incumbents: Consolidate manufacturing footprint around Quebec and Manitoba clusters to capture labor scale efficiencies and deflect margin pressure from petrochemical input volatility. Deepen backward integration into D3O smart material supply or equivalent non-Newtonian polymer sources to armor integration specialists threatening technical differentiation. Channel control investments across upper Midwest dealership networks remain essential as direct-to-rider digital alternatives erode traditional distribution economics.
For New Entrants and Emerging Players: Lead with subscription-based gear refresh programs targeting Alberta and British Columbia riders who prioritize convenience over in-person fitting protocols. Marginal snow condition equipment represents the most penetrable white space, as waterproof-breathable membrane technology opens season extension demand across Scandinavia and Baltic states where freeze-thaw cycling previously limited utility. Direct climate-triggered digital campaigns timed to regional weather patterns bypass incumbent dealership gatekeeping.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors armor integration specialists with proprietary material science IP and established CE certification pathways over volume fabricators competing on channel density alone. Long-term viability hinges on regulatory compliance agility across ASTM-to-CE dual certification complexity that freezes development capital for undercapitalized competitors. Acquisition targets should demonstrate established EN 1077 adaptation timelines and existing Health Canada alignment. The signal to monitor is state-level mandatory helmet legislation expansion beyond current Minnesota-Wisconsin-Michigan concentration, which would accelerate replacement cycle frequency and concentrate demand among certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Level 2 Certification Investment | Hospital-grade impact absorption specifications collapse premium-mid tier gaps, recalibrating competitive positioning. |
| Direct-to-Rider Digital Channel Launch | Subscription refresh programs capture younger Alberta and British Columbia riders prioritizing convenience. |
| Membrane Chemistry Redesign | REACH per- and polyfluoroalkyl substance compliance secures European market access through bio-based alternatives. |
| Trail-Access Program Partnership | Provincial and state-funded groomed network expansion converts casual landowners into registered full-kit purchasers. |
| D3O Armor Integration Scale-Up | Non-Newtonian polymer supply security differentiates technical performance from foam-based legacy competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of snowmobile registration databases, state trail-funding appropriations records, and ASTM certification filings to establish demand quantification and regulatory trajectory baselines. Primary interviews engaged product development directors at technical apparel houses, procurement managers at powersports OEMs, dealership operations heads across Minnesota and Wisconsin, and trail program administrators at state natural resource departments. Secondary validation drew from Consumer Product Safety Commission recall patterns, Health Canada product safety advisories, and ECHA chemical restriction enforcement timelines. Bottom-up unit shipment estimates triangulate against top-down consumer expenditure models derived from regional registration density and equipment replacement cycle assumptions.
Segmentation dimensions modeled include product type, material composition, end-user category, protective feature specification, and geographic regulatory cluster across the projection horizon. CAGRs derive from regression analysis of historical shipment volumes against explanatory variables including trail-access program enrollment, mandatory helmet legislation adoption, and petrochemical input price indices. Industry-specific forecast inputs incorporate CE certification timeline friction effects and REACH compliance deadline impacts on membrane manufacturer launch schedules.
Underlying assumptions cover stable state-level trail funding appropriations and continued ASTM F2040 enforcement intensity, with deviation risk concentrated in petrochemical feedstock price volatility and cross-border tariff regime shifts. Practitioners should keep alternative scenarios live as provincial trail-access program expansion rates and ECHA chemical restriction enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Respirator Filter Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Flu Protection Kits Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
APAC Safety Instrumented Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Ship Life-Saving Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Law Enforcement Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Strobe Beacon Market