
 Cystinuria Treatment Market | 2026-2036
Cystinuria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cystinuria Treatment Market Outlook
Aftermarket service revenue from patient monitoring and stone-event prevention programs is tilting toward integrated care networks. Travere Therapeutics leverages its rare-disease infrastructure to sustain high-touch patient support models. Teva Pharmaceutical Industries competes through broad generic penetration across oral alkalinization agents. Viatris anchors hospital formulary access with established distribution contracts in nephrology.
Cystinuria treatment encompasses pharmacological, nutritional, and surgical interventions designed to reduce urinary cystine concentration and prevent recurrent kidney stone formation, typically involving urinary alkalinization to pH 7.5-8.0 and chelation therapy with tiopronin or penicillamine. The primary purpose is preventing cystine crystallization that leads to obstructive uropathy, chronic kidney disease, and repeated surgical interventions. Medication dominates current value pools, particularly alkalinizing agents and thiol-binding drugs, while dietary supplements represent the fastest-expanding segment as patients seek non-pharmacological stone prevention. The therapy area dimension shows nephrology capturing premium pricing for complex cases, with urology handling acute stone management and general medicine expanding into screening protocols.
The US FDA orphan drug program shapes development economics by granting market exclusivity and tax incentives for novel cystinuria therapeutics, while the EMA's parallel designation accelerates European access pathways. FDA Good Manufacturing Practice standards for chelation agents enforce purity specifications that limit supplier entry and protect incumbent manufacturers. Stakeholders must monitor evolving reimbursement policies for preventive pharmacotherapy versus episodic stone removal procedures.
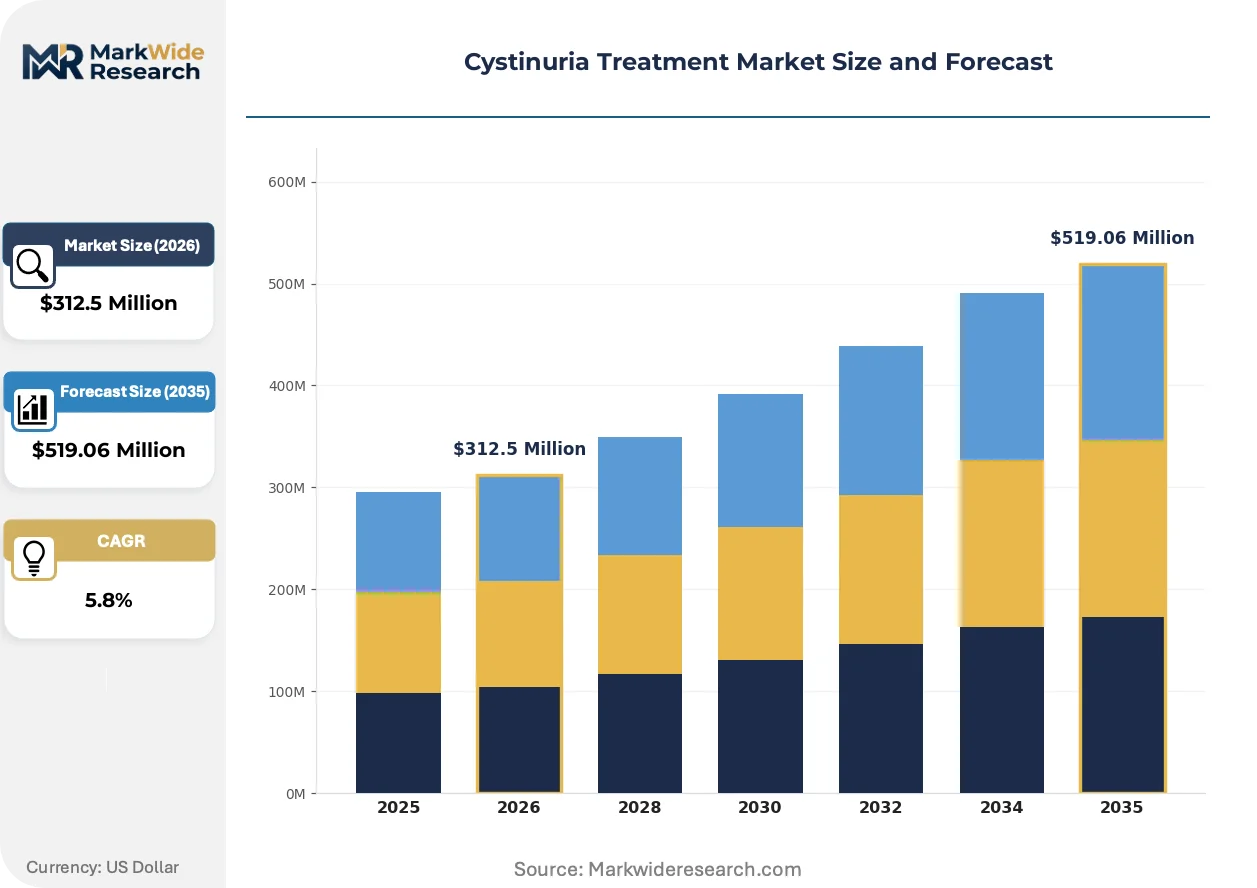
Market Dynamics
Hospital formulary consolidation is concentrating purchasing power for cystinuria therapeutics into integrated delivery networks, compressing margins for alkalinizing agents while amplifying volume commitments for orphan-designated chelation therapies.
Growth Catalysts
- Orphan Drug Incentives:The US FDA's tax credits and extended exclusivity provisions accelerate novel thiol-binding compound development. Biopharmaceutical sponsors channel these benefits into high-touch patient support infrastructure.
- Metabolic Stone Clinic Expansion:Tertiary care centers in the United States are formalizing dedicated cystinuria management protocols. These units bundle alkalinization monitoring with surgical prevention programs.
- Chelation Therapy Advances:Next-generation tiopronin formulations with improved tolerability profiles are displacing first-generation penicillamine regimens. Nephrology practices prioritize these agents for treatment-naive patients.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Penicillamine and tiopronin raw material synthesis concentrates among a limited supplier base in Southern China. Disruption to this geography propagates downstream formulation shortages.
- Reimbursement Compression:Medicare's bundled payment models for kidney stone episodes de-emphasize preventive pharmacotherapy. Payers classify chronic alkalinization as maintenance rather than disease-modifying therapy.
- Thiol Compound Toxicity Profile:Penicillamine's association with hypersensitivity syndrome and hematologic adverse events limits first-line utilization. Prescribers reserve this agent for tiopronin-intolerant patients.
Strategic Opportunities
- Underpenetrated European Markets:France and Italy maintain lower cystinuria diagnosis rates relative to diagnostic yield in Germany. EMA parallel orphan designation accelerates access pathway development for novel entrants.
- Digital Therapeutics Integration:Urinary pH monitoring wearables paired with mobile adherence platforms create remote care revenue streams. Technology convergence between consumer electronics and clinical-grade sensors enables home-based alkalinization titration.
- Dietary Supplement Positioning:Potassium citrate and fluid intake protocols packaged as condition-specific nutrition products bypass prescription regulatory burdens. Direct-to-consumer channels capture patient self-management expenditure.
Industry Challenges
- Specialized Metabolic Nursing Shortage:Cystinuria case management requires expertise in 24-hour urine interpretation and stone-event triage. Academic medical centers compete for scarce nephrology nurse practitioners trained in inherited metabolic disorders.
- Multi-Stakeholder Coordination Complexity:Optimal outcomes demand synchronization between urology, nephrology, and nutrition services. Electronic health record fragmentation across these departments impedes care pathway standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystinuria Treatment Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Dietary Supplements, Intravenous Therapy, Surgery Therapy Area: Urology, Nephrology, General Medicine, Pain Management Delivery Mode: Oral, Injectable, Infusion, Topical End User: Hospitals, Clinics, Homecare, Research Institutions |
| Companies Covered | Travere Therapeutics, Inc., Dr. Reddy's Laboratories Ltd., Advicenne, Teva Pharmaceutical Industries Ltd., ANI Pharmaceuticals, Inc., Viatris Inc., Bausch Health Companies Inc., Camber Pharmaceuticals, Inc., Par Pharmaceutical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystinuria Treatment Market Strategic Shifts
Digital biomarker platforms are restructuring how cystinuria patients monitor stone risk, shifting reliance from episodic laboratory testing toward continuous physiological surveillance and algorithmic intervention triggering.
Cloud-connected urinary dipstick readers is virtualizing the traditional 24-hour urine collection workflow. Home-based patients transmit real-time cystine supersaturation estimates to metabolic stone clinics. This distributed monitoring model compresses emergency department utilization for acute stone events while expanding remote patient monitoring revenue pools.
EMA's Medical Device Regulation (MDR) reclassification of software-as-medical-device is tightening validation requirements for cystinuria management applications. Developers must demonstrate clinical benefit equivalence to predicate diagnostic methods. European nephrology practices delay platform adoption pending notified body certification completion.
Stone-event prevention programs are unbundling from traditional hospital-based urology contracts. Independent metabolic stone clinics in the United States negotiate direct capitation arrangements with regional payers. This channel disintermediation concentrates patient volume into specialized centers while eroding general urology practice stone-related procedure revenue.
Cystinuria Treatment Market Segmentation
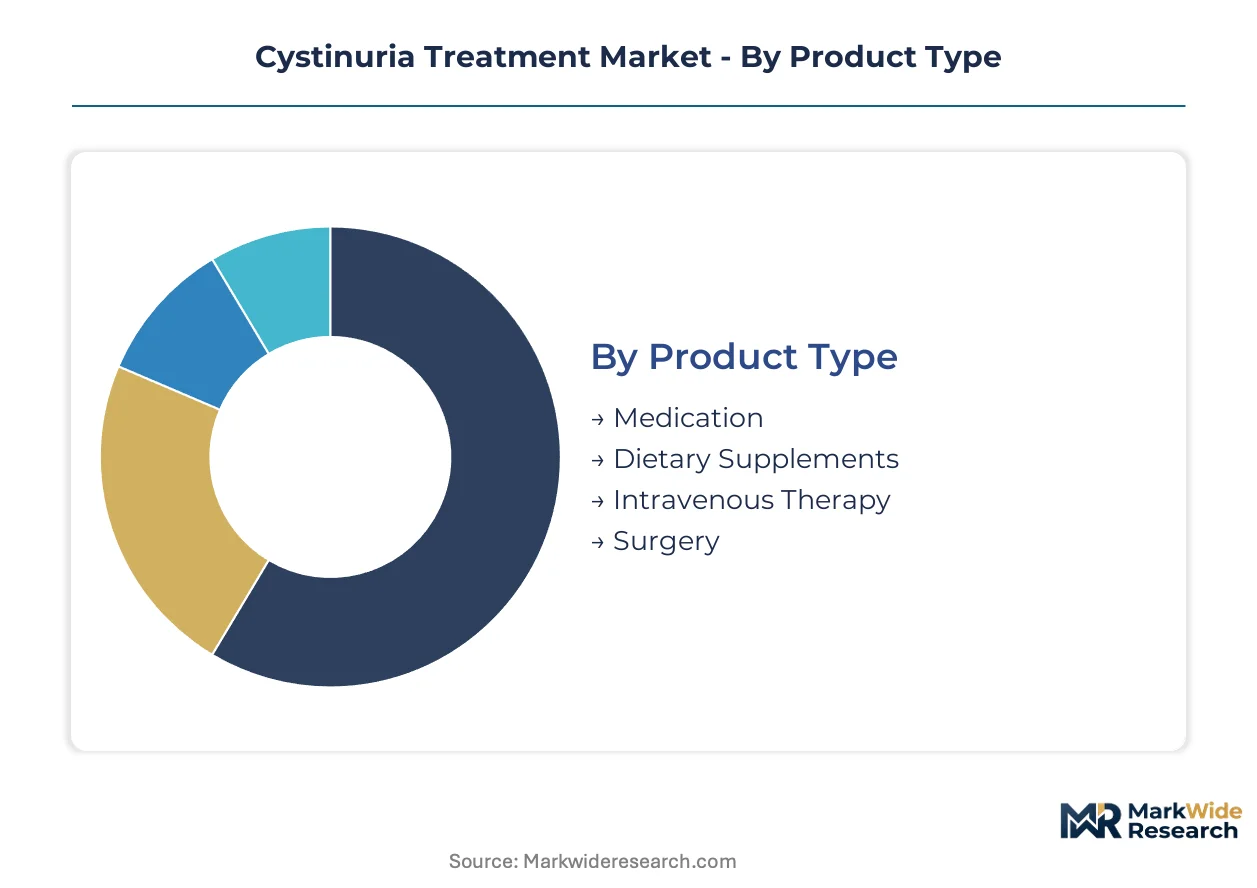
Cystinuria management spans acute intervention and chronic prevention, requiring distinct product configurations across care settings. Segmentation reveals how hospital purchasing power concentrates in high-cost chelation therapies while home-based alkalinization drives volume expansion.
Product Type:
Cost tier stratification separates chronic maintenance therapies from acute surgical interventions and premium orphan-designated pharmaceuticals.
- Medication:Urinary alkalinizing agents (potassium citrate, sodium bicarbonate) and thiol-binding chelators (tiopronin, penicillamine) constitute the revenue core. Tertiary nephrology clinics in the United States prioritize tiopronin for treatment-naive patients given penicillamine's toxicity constraints.
- Dietary Supplements:Potassium citrate formulations, fluid management protocols, and cystine-binding nutritional adjuncts bypass prescription regulatory pathways. Direct-to-consumer channels in Germany and France capture patient self-management expenditure as patients seek non-pharmacological stone prevention.
- Intravenous Therapy:Hospital-administered fluids and electrolyte correction for acute stone events or perioperative management.
- Surgery:Ureteroscopic stone removal, percutaneous nephrolithotomy, and open procedures for obstructive uropathy refractory to medical management.
Medication commands the established base. The steepest expansion runs through Dietary Supplements.
Therapy Area:
Clinical specialization determines pricing power, with nephrology capturing premium reimbursement for complex metabolic management against urology's procedure-based economics.
- Urology:Acute stone management, surgical intervention, and ureteral stenting dominate this segment. German university hospitals bundle surgical prevention programs with metabolic workups to reduce recurrence rates.
- Nephrology:Inherited metabolic disorder expertise commands premium pricing for 24-hour urine monitoring and chelation titration. United States academic medical centers compete for scarce nephrology nurse practitioners trained in cystinuria case management.
- General Medicine:Screening protocols and initial diagnosis in primary care settings before specialist referral.
- Pain Management:Opioid-sparing protocols for recurrent stone episodes and chronic renal colic.
Nephrology retains pricing leadership. General Medicine shows the steepest patient volume climb as screening protocols expand.
Delivery Mode:
Patient convenience and adherence economics favor oral formulations, while injectable and infusion routes concentrate in acute hospital settings.
- Oral:Potassium citrate tablets, tiopronin capsules, and penicillamine tablets dominate chronic therapy. French and Italian patients demonstrate higher persistence with divided-dose regimens than single-daily dosing.
- Injectable:Subcutaneous or intramuscular chelation alternatives for patients with severe gastrointestinal intolerance.
- Infusion:Intravenous fluids, parenteral alkalinization, and perioperative electrolyte management in hospital settings.
- Topical:Limited current utility; experimental formulations for cutaneous manifestations of cystinosis (distinct from cystinuria).
Oral formulations anchor chronic disease management. Infusion routes gain share fastest through bundled kidney stone episode payments.
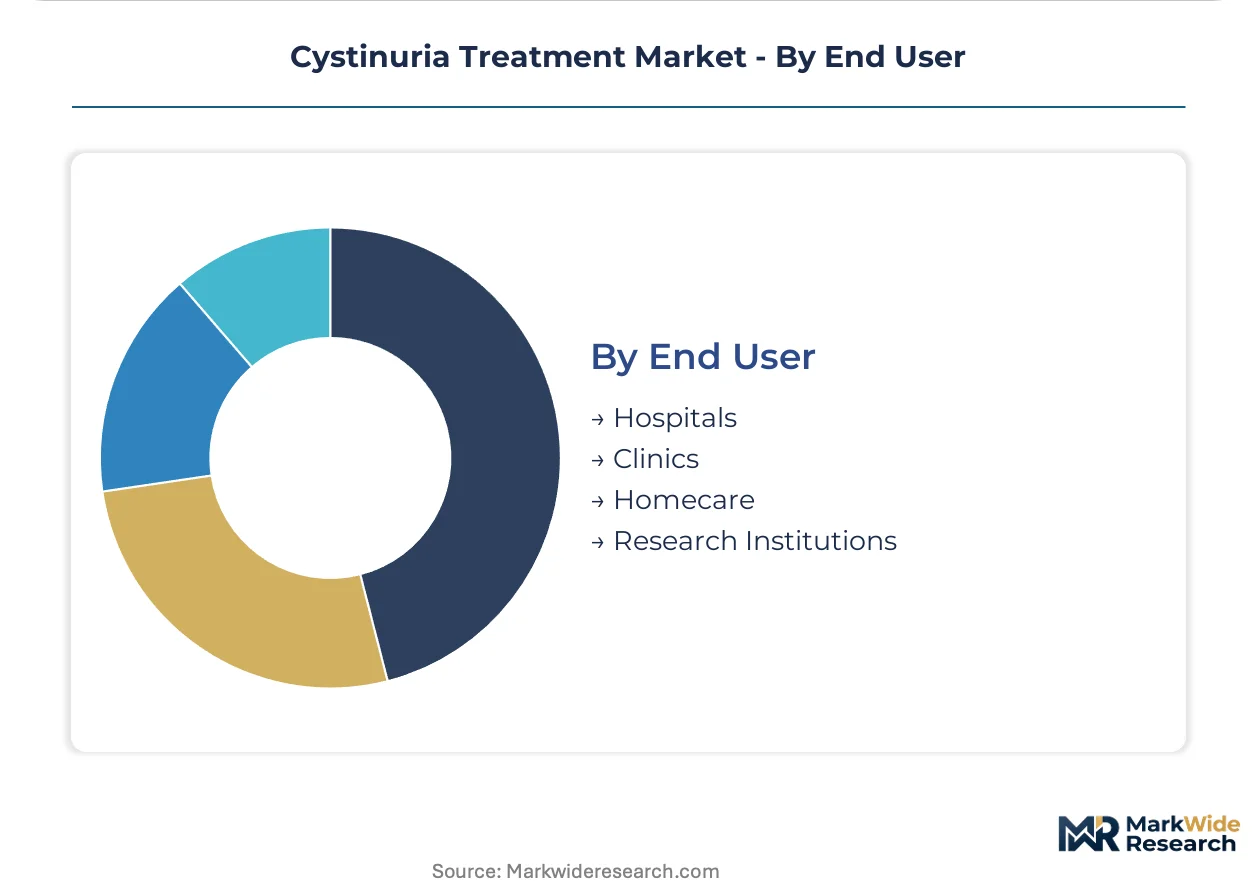
End User:
Site-of-care economics concentrate high-touch chelation therapy in hospital networks while homecare captures alkalinization monitoring revenue.
- Hospitals:Integrated delivery networks concentrate purchasing power for orphan-designated chelation therapies. United States hospital formulary consolidation compresses margins for generic alkalinizing agents.
- Clinics:Independent metabolic stone clinics negotiate direct capitation arrangements with regional payers. These specialized centers erode general urology practice stone-related procedure revenue.
- Homecare:Remote patient monitoring platforms and home health nursing for complex chelation regimens.
- Research Institutions:Clinical trial sites for novel thiol-binding compounds and digital therapeutic validation.
Hospitals control the established therapeutic base. Homecare demonstrates the steepest expansion trajectory through remote monitoring platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material synthesis for penicillamine and tiopronin concentrates among limited suppliers in Southern China, creating geographic vulnerability that propagates downstream into formulation shortages across North American and European markets.
United States
Hospital formulary consolidation concentrates purchasing power for orphan-designated chelation therapies into integrated delivery networks. The FDA's orphan drug tax credits accelerate novel thiol-binding compound development. Tertiary care centers in Boston and New York formalize dedicated metabolic stone clinics bundling alkalinization monitoring with surgical prevention.
Germany
University hospitals in Bavaria and Baden-Württemberg bundle surgical prevention programs with metabolic workups to reduce cystine stone recurrence rates. The EMA's parallel orphan designation accelerates access pathway development for novel entrants. Academic medical centers in Heidelberg and Munich compete for nephrology nurse practitioners trained in inherited metabolic disorders.
France
Lower cystinuria diagnosis rates relative to German diagnostic yield create underpenetrated market conditions for novel therapeutics. ANSM oversight of chelation agent manufacturing enforces purity specifications that limit supplier entry. Independent metabolic stone clinics in Paris negotiate direct capitation arrangements with regional payers, eroding general urology practice revenue.
United Kingdom
NHS bundled payment models for kidney stone episodes de-emphasize preventive pharmacotherapy in favor of acute intervention. The MHRA aligns with EMA orphan pathways for accelerated cystinuria therapeutic access. London-based tertiary centers expand remote patient monitoring platforms for home-based alkalinization titration.
Italy
Patients demonstrate higher persistence with divided-dose alkalinization regimens than single-daily dosing, influencing formulation preferences. The AIFA reimbursement framework classifies chronic alkalinization as maintenance rather than disease-modifying therapy. Northern Italian metabolic clinics in Lombardy and Emilia-Romagna pioneer digital therapeutics integration with urinary pH monitoring wearables.
Cystinuria Treatment Market Competitive Environment
Orphan-disease specialists and broad generic manufacturers split the market along therapy complexity lines. The competitive structure concentrates premium pricing power with FDA-designated orphan drug sponsors while commoditizing oral alkalinization agents. Three archetypes dominate: rare-disease infrastructure deployers, formulary access anchors, and high-volume generic penetrators. Consolidation through hospital network purchasing agreements and strategic patient support infrastructure investments defines current competitive moves.
Within the orphan-disease infrastructure tier, Travere Therapeutics occupies a position leveraging rare-disease capabilities for high-touch patient support models. Teva Pharmaceutical Industries exemplifies broad generic penetration strategies across oral alkalinization agents. Viatris anchors hospital formulary access through established distribution contracts in nephrology, representing the formulary-anchoring archetype.
| Leading Market Players |
|---|
| Travere Therapeutics, Inc. |
| Dr. Reddy's Laboratories Ltd. |
| Advicenne |
| Teva Pharmaceutical Industries Ltd. |
| ANI Pharmaceuticals, Inc. |
| Viatris Inc. |
| Bausch Health Companies Inc. |
| Camber Pharmaceuticals, Inc. |
| Par Pharmaceutical, Inc. |
| Others |
Value Chain & Pricing Dynamics
Southern China's API synthesis clusters for penicillamine and tiopronin intermediate chemicals constrain downstream formulation pricing power across North American and European markets. Hospital formulary consolidation into integrated delivery networks compresses margins for generic alkalinizing agents while amplifying volume commitments for orphan-designated chelation therapies.
Pricing Analysis
The FDA's orphan drug exclusivity provisions dictate the pricing tier structure for cystinuria therapeutics. Three-tier pricing structure across premium orphan-designated chelators, standard branded alkalinizing agents, and economy generic potassium citrate separates reimbursement categories. Cost compression in the generic alkalinization tier intensifies as integrated delivery networks centralize purchasing. Academic medical centers demonstrate lowest price sensitivity given bundled metabolic stone clinic economics, while independent urology practices face acute margin pressure.
Supply Chain Analysis
Upstream thiol compound precursors draw from concentrated chemical manufacturing bases in China, India, and select European specialty chemical producers. Penicillamine and tiopronin active pharmaceutical ingredients hinge on mercaptan derivative feedstocks and specialized fermentation capacities. Single-source vulnerability propagates from limited qualified suppliers of pharmaceutical-grade chelation raw materials. Distribution runs through hospital GPO contracts, specialty pharmacy networks, and direct-to-patient channels for dietary supplement adjacents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
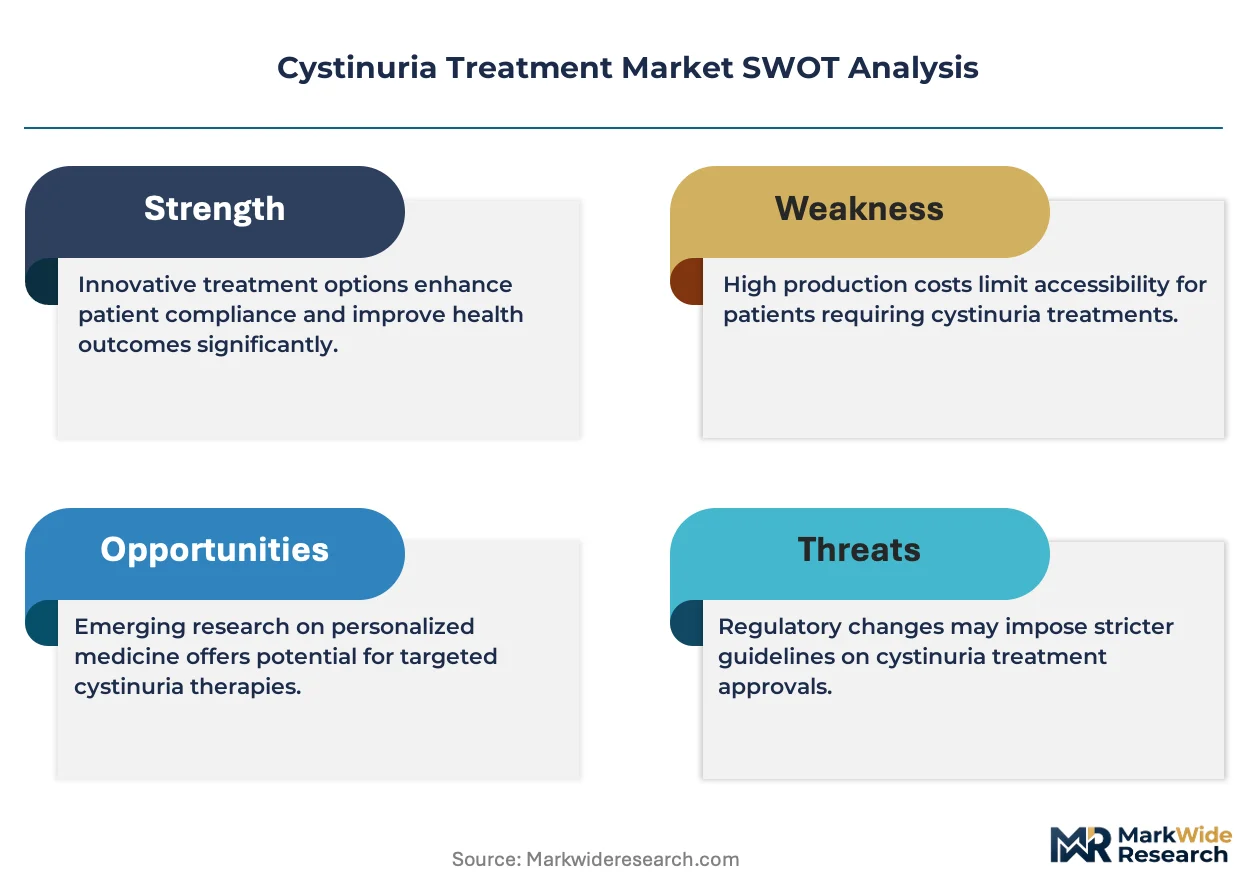
The cystinuria treatment market functions as a regulatory entrenchment story where FDA orphan drug exclusivity creates durable competitive moats through extended market protection and tax incentive economics.
For Market Incumbents: Pre-empt generic erosion in oral alkalinization by securing backward integration into potassium citrate active ingredient supply. Lock hospital formulary access through metabolic stone clinic partnership infrastructure before independent clinics disintermediate stone-event revenue. Channel orphan drug tax credits into high-touch patient adherence platforms that raise switching costs for treatment-naive patients. For New Entrants and Emerging Players: Build out digital therapeutics capabilities in urinary pH monitoring and remote alkalinization titration to capture homecare expansion. France and Italy present underpenetrated diagnosis rate environments relative to German diagnostic yield. Partner with nephrology nurse practitioner training programs to secure scarce metabolic case management expertise as a distribution wedge. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors rare-disease infrastructure deployers with established FDA orphan pathway navigation capabilities. Long-term viability rests on patient support platform scalability and chelation therapy tolerability improvement pipelines. Watch EMA parallel orphan designation velocity as the inflection signal for European market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and exclusivity provisions accelerate novel thiol-binding compound development economics. |
| Metabolic Stone Clinic Partnership | Direct capitation arrangements with regional payers concentrate high-value patient volume away from general urology. |
| Digital Therapeutics Integration | Urinary pH monitoring wearables paired with mobile adherence platforms create remote care revenue streams. |
| API Supply Security Investment | Backward integration into penicillamine and tiopronin raw material synthesis mitigates Southern China concentration risk. |
| Nurse Practitioner Training Program | Academic medical center partnerships secure scarce nephrology expertise for inherited metabolic disorder case management. |
Study Parameters
Cross-validation between nephrology practice interviews and formulary database analysis anchors the qualitative findings. Primary fieldwork encompassed drug development executives at orphan-disease specialists, regulatory affairs leads navigating FDA and EMA parallel pathways, hospital formulary directors at integrated delivery networks, and payer access specialists at regional health plans. Secondary validation drew from FDA orphan drug designations, EMA submissions, ClinicalTrials.gov cystinuria protocol registries, and hospital procurement databases. Bottom-up patient volume modeling and top-down therapeutic class expenditure analysis provided triangulation checks.
Calibration against historical orphan drug launch trajectories and metabolic stone clinic expansion patterns informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed product type stratification, therapy area specialization, delivery mode preferences, and end-user site-of-care economics. CAGRs derived from therapeutic class growth rate benchmarks adjusted for orphan drug incentive impacts and digital therapeutic adoption curves. Forecast inputs incorporated 24-hour urine monitoring protocol penetration and chelation therapy persistence rates by formulation type.
Sensitivities concentrate around FDA orphan exclusivity policy continuity, API supply disruption scenarios, and Medicare bundled payment model evolution for kidney stone episodes. Cross-checking against CMS Medicare Part D expenditure trends for rare disease therapeutics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Sporothrix Schenckii Infection Treatment Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Pemphigus Vulgaris (PV) Treatment Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Acromegaly Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Tinea Corporis Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Desmoid Tumor Market