
 Global Medical Affairs Outsourcing Market | 2026-2036
Global Medical Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Affairs Outsourcing Market Foresight
The EU Green Deal and CSRD disclosure mandates is broadening the scope of environmental reporting that pharma sponsors require from outsourcing partners. IQVIA Holdings Inc. leverages its integrated data backbone to anchor multi-country medical affairs programs. ICON plc dominates in oncology therapy area support through specialized investigator networks. Syneos Health Inc. differentiates by embedding virtual engagement platforms into standard service delivery.
Medical affairs outsourcing encompasses the delegation of scientific communication, pharmacovigilance, regulatory support, and healthcare professional engagement activities to third-party specialists, typically governed by ISO 14155 standards for clinical investigation and ICH E2B guidelines for adverse event reporting. Its primary purpose is to accelerate therapeutic commercialization while maintaining rigorous evidence standards across diverse geographies. Pharmacovigilance services capture the largest share of contract value due to mandatory post-market surveillance requirements. Hybrid delivery models are gaining share fastest as sponsors seek cost arbitrage without sacrificing regulatory proximity. Medical communications generates concentrated margins where agencies combine scientific expertise with digital channel proficiency.
FDA oversight of real-world evidence submissions and EMA's evolving guidance on decentralized trials are tightening competency requirements for outsourced medical affairs providers. The EU AI Act introduces additional compliance layers for automated safety signal detection systems used in pharmacovigilance workflows. India's CDSCO alignment with ICH standards is expanding the country's role in global regulatory document preparation. Stakeholders must evaluate partner capabilities against emerging digital health regulatory frameworks before committing to long-term outsourcing structures.
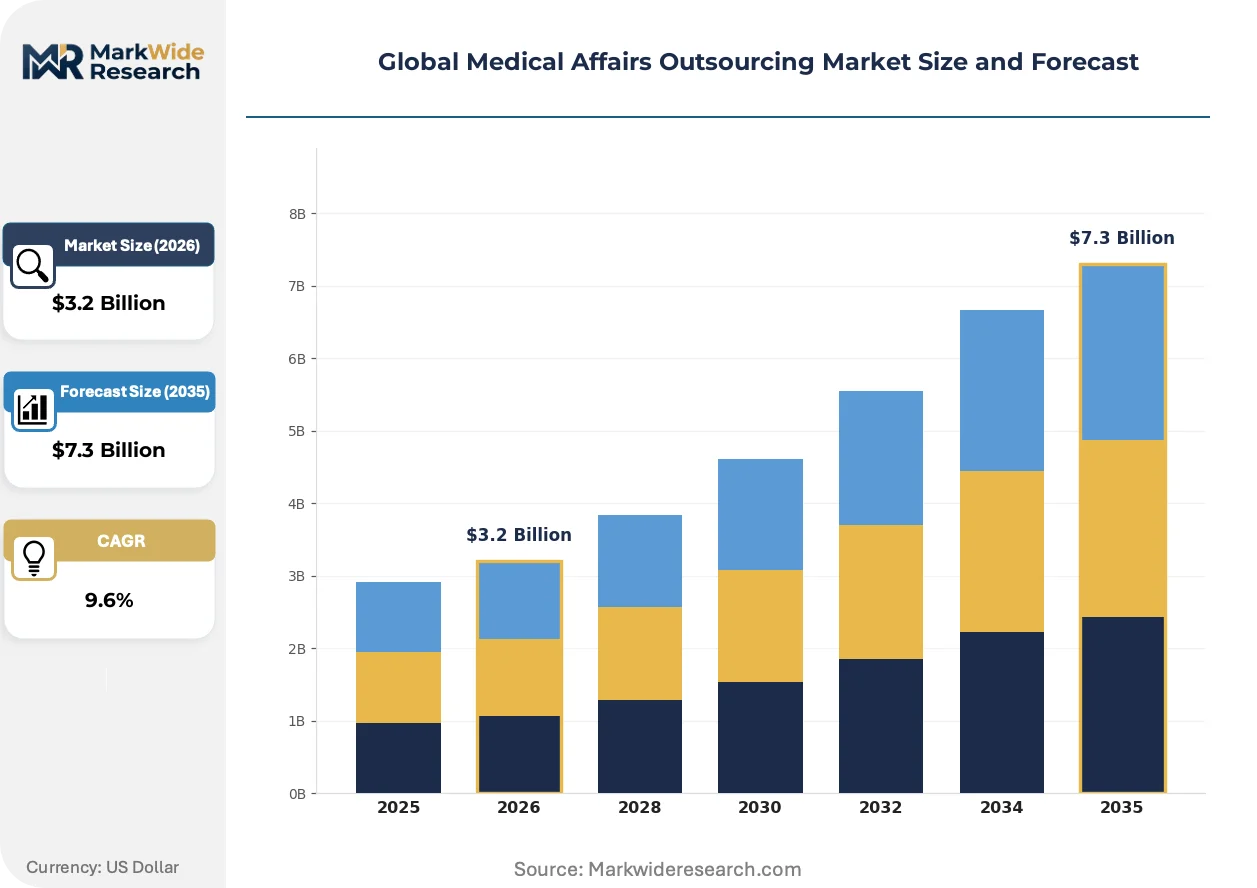
Market Dynamics
EU MDR implementation timelines and FDA digital health guidance are compressing sponsor timelines while fragmenting compliance workloads across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
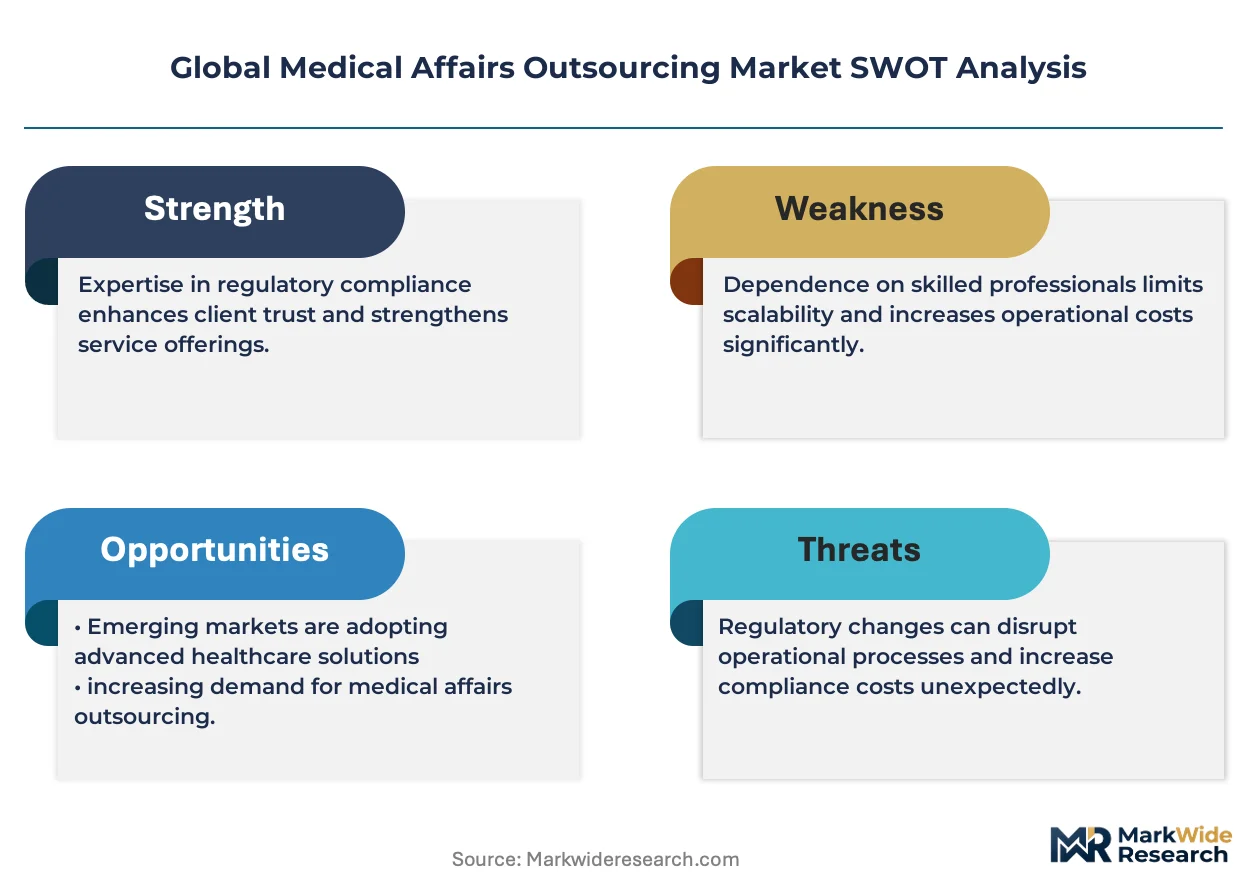
- Post-market surveillance mandates:EMA pharmacovigilance requirements and FDA adverse event reporting obligations expand contract scope for safety database management and signal detection services.
- Decentralized trial infrastructure:Remote patient monitoring platforms and virtual site capabilities reduce geographic constraints on investigator engagement and medical science liaison deployment.
- Biotechnology pipeline expansion:Cell and gene therapy developers in the United States and Germany lack internal medical affairs scale, driving externalization of publication planning and KOL relationship management.
Market Restraints
- Regulatory documentation complexity:EU MDR technical file requirements and FDA 510(k) submission reforms lengthen contract initiation cycles and inflate compliance verification costs.
- Talent concentration in established clusters:Qualified medical affairs professionals cluster in Basel, Boston, and Mumbai, creating wage arbitrage pressures and retention challenges for providers operating outside these hubs.
- Data sovereignty restrictions:GDPR patient data localization requirements and China's data security law fragment pharmacovigilance database architectures, preventing single-instance global deployments.
Strategic Opportunities
- Real-world evidence generation:FDA's expanding acceptance of RWE for label expansion creates demand for observational study design and healthcare claims database analysis capabilities.
- EU AI Act compliance services:Automated signal detection algorithms used in pharmacovigilance require conformity assessment and risk management documentation support.
- Hybrid engagement models:Virtual medical science liaison platforms combined with in-person specialist access address access restrictions in Japan and rural United States markets simultaneously.
Industry Challenges
- ISO 14155 investigator training gaps:Clinical research associates with combined therapeutic expertise and regulatory documentation skills command premium compensation and extended recruitment timelines.
- Legacy safety database migration:Pharmacovigilance providers maintain heterogeneous Oracle, ARISg, and custom platform environments that complicate multi-sponsor workforce deployment.
- ICH E2B(R3) implementation variance:Individual case safety report formatting inconsistencies between FDA, EMA, and PMDA systems require redundant quality control checkpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Affairs Outsourcing Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $7.3 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Medical Writing, Pharmacovigilance, Regulatory Support, Medical Communications, Data Management Delivery Model: Onshore, Offshore, Hybrid, Virtual Teams Therapy Area: Oncology, Neurology, Cardiovascular, Immunology, Endocrinology Client Type: Biotechnology Firms, Pharmaceutical Companies, Medical Device Manufacturers, Contract Research Organizations |
| Companies Covered | IQVIA Holdings Inc., ICON plc, Syneos Health Inc., The Medical Affairs Company, Pharmaceutical Product Development LLC, Ashfield Healthcare Communications, Indegene Inc., Parexel International Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Affairs Outsourcing Market Shifts & Advancements
Artificial intelligence and machine learning applications are restructuring pharmacovigilance workflows while regulatory digitization mandates force capability reinvestment across service tiers.
Natural language processing engines are extracting adverse event narratives from unstructured sources including social media, medical literature, and call center transcripts. Large pharmaceutical sponsors in oncology and immunology are deploying these tools for signal detection prioritization. NLP integration is compressing manual case processing timelines while elevating data quality verification requirements for outsourcing partners.
EMA's decentralized clinical trial guidance and FDA's digital health software pre-certification program are rewriting competency specifications for medical affairs providers. Remote source data verification and electronic informed consent platforms now require validation documentation aligned with ICH E6(R2) annexes. Oncology trials in Germany and cardiology studies in the United States exhibit the most rapid adoption of fully virtual site management models.
Biotechnology sponsors are unbundling medical affairs contracts into discrete workstreams with distinct performance metrics. Publication planning, medical information call centers, and field medical engagement now source from separate providers rather than consolidated full-service arrangements. This fragmentation is most pronounced among Series C-funded cell therapy developers in Boston and gene editing companies in the San Francisco Bay Area, where capital efficiency pressures override vendor relationship continuity.
Global Medical Affairs Outsourcing Market Segmentation
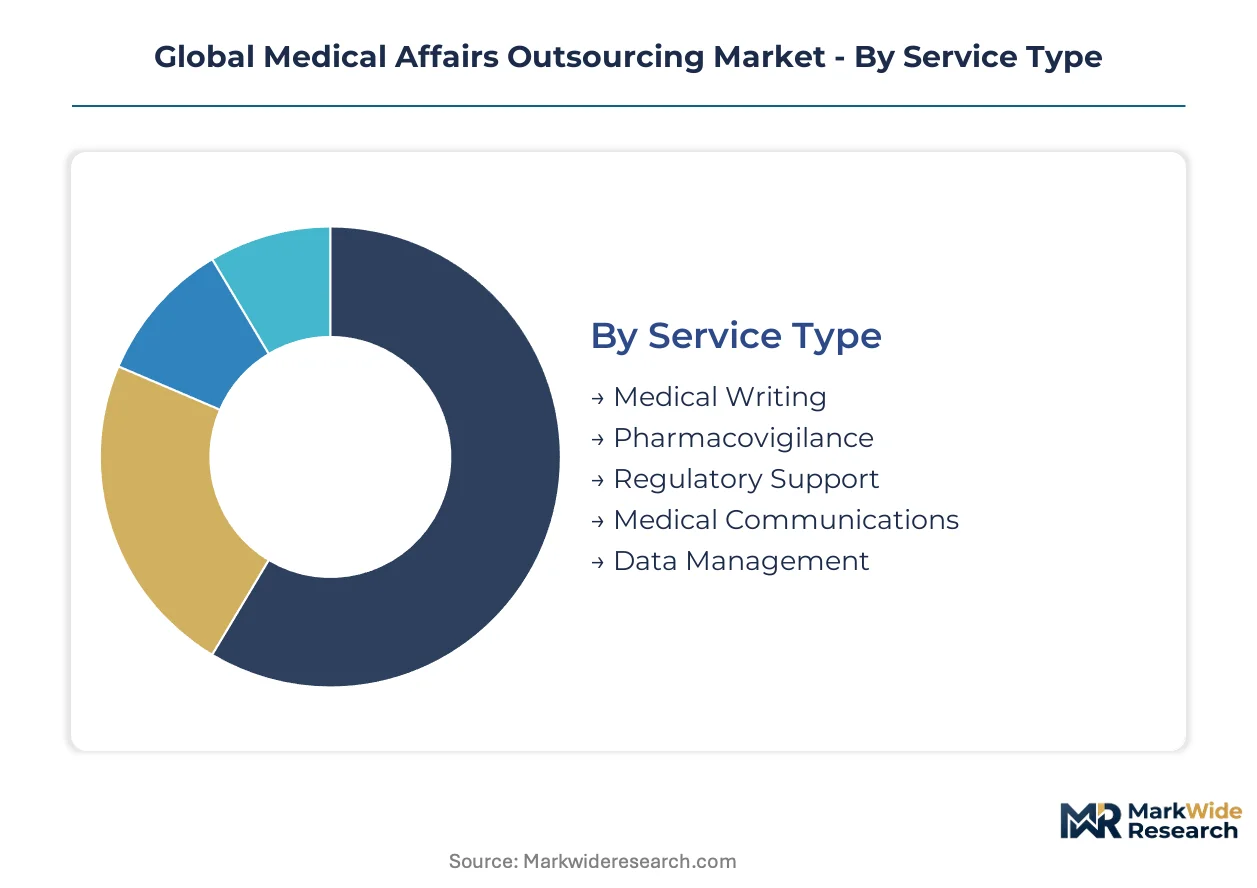
Service specialization and delivery geography determine compliance burden and margin structure across medical affairs outsourcing. Segmentation reveals where ISO 14155 certification, ICH E2B(R3) readiness, and GDPR data localization requirements concentrate contract value and talent premiums.
Service Type:
Pharmacovigilance and regulatory support segments carry the heaviest certification burdens, with FDA adverse event reporting and EMA signal detection mandates requiring validated safety database infrastructure. Medical writing and communications face lighter formal approval requirements but demand therapeutic domain expertise.
- Pharmacovigilance:Case processing, signal detection, and periodic safety update report preparation governed by ICH E2B(R3) and FDA 21 CFR 312.32. Demand concentrates among Boston and Basel biotechnology sponsors lacking internal safety database scale, driven by mandatory post-market surveillance obligations for oncology and cell therapy products.
- Regulatory Support:Submission preparation, health authority correspondence, and labeling compliance spanning FDA 510(k), EMA centralized procedures, and PMDA consultations. German and United States sponsors externalize EU MDR technical documentation and FDA breakthrough therapy designation requests amid compressed approval timelines.
- Medical Writing:Clinical study reports, investigator brochures, and peer-reviewed manuscript development requiring ISO 14155 familiarity. Sponsors in India and the United States commission protocol and CSR drafting for decentralized trials.
- Medical Communications:Scientific platform development, congress presentations, and healthcare professional engagement materials. Digital channel proficiency distinguishes high-margin providers serving immunology and endocrinology brands.
- Data Management:Electronic data capture configuration, database lock procedures, and CDISC SDTM mapping for regulatory submission readiness. Remote monitoring adoption in United States cardiology trials expands demand for virtual data verification workflows.
Pharmacovigilance sits at the top of the volume ranking, with medical communications climbing the fastest as virtual engagement platforms reshape scientific exchange economics.
Delivery Model:
Cost tier and regulatory proximity tradeoffs define delivery model selection, with hybrid structures capturing share as sponsors seek wage arbitrage without sacrificing FDA and EMA access.
- Hybrid:Blended onshore account management with offshore execution for case processing and document preparation. United States biotechnology sponsors deploy Mumbai-based teams for pharmacovigilance case intake while retaining Boston-based medical directors for health authority interactions, optimizing cost-quality balance.
- Onshore:Full-service delivery within sponsor geography ensuring real-time regulatory access and investigator relationship continuity. Premium pricing applies for FDA pre-approval inspection support and EMA oral explanation preparation.
- Offshore:Centralized delivery from India or Eastern Europe for high-volume, rules-based workstreams. CDSCO-aligned Indian providers capture global regulatory document preparation as ICH harmonization accelerates.
- Virtual Teams:Distributed specialist networks enabled by cloud-based collaboration platforms and electronic trial master files. Japan and rural United States access constraints drive medical science liaison virtualization.
Hybrid deployment shows the steepest expansion trajectory, with pure offshore delivery losing share to proximity-sensitive compliance requirements.
Therapy Area:
Clinical complexity and regulatory scrutiny intensity vary sharply across therapeutic domains, with oncology and cell therapy commanding specialist expertise premiums.
- Oncology:Immuno-oncology combination protocols, biomarker-driven patient selection, and expedited approval pathways demand integrated medical affairs capabilities. United States and German sponsors externalize publication planning and KOL engagement for checkpoint inhibitor and CAR-T programs.
- Neurology:Rare disease trial design, patient registry management, and long-term safety follow-up for gene therapies. Biogen and Roche competitive dynamics in Alzheimer's disease reshape medical communication strategies.
- Cardiovascular:Large outcome trials, real-world evidence generation, and digital health integration for remote monitoring. Decentralized trial adoption runs highest in United States cardiology studies.
- Immunology:Biosimilar differentiation, patient support program design, and subcutaneous formulation messaging. AbbVie and Johnson & Johnson legacy franchise defense drives medical information call center investment.
- Endocrinology:Diabetes device-software combination products and obesity peptide launch support. Novo Nordisk and Eli Lilly market expansion creates demand for field medical scaling.
Oncology maintains the largest contract value position, with neurology gaining share fastest on gene therapy pipeline expansion.
Client Type:
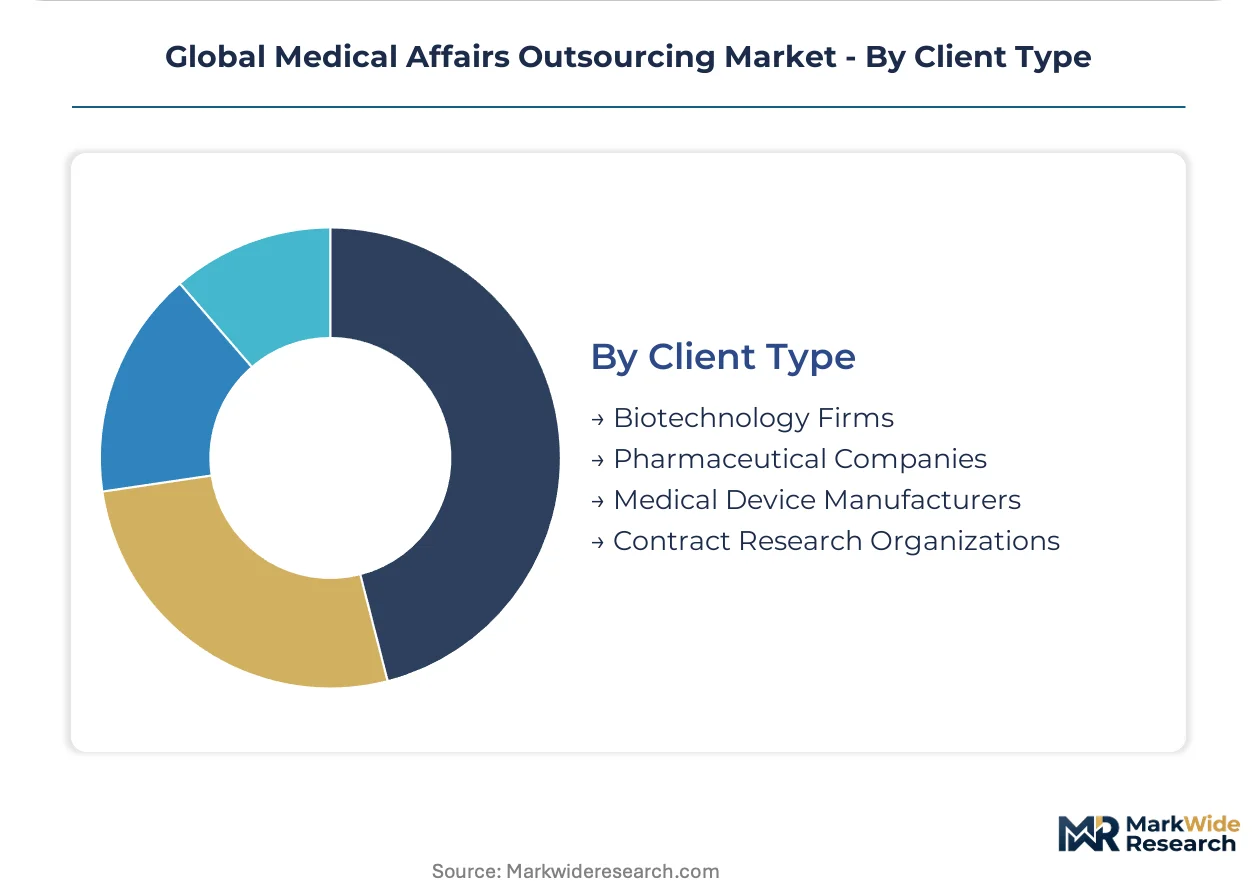
Internal capability maturity and capital efficiency pressures determine outsourcing depth, with biotechnology firms showing the highest externalization rates.
- Biotechnology Firms:Venture-funded developers lacking commercial infrastructure externalize end-to-end medical affairs from phase II through launch. Series C cell therapy companies in Boston and gene editing ventures in San Francisco unbundle contracts into discrete workstreams.
- Pharmaceutical Companies:Established players supplement internal teams for geographic expansion, therapeutic area entry, or digital capability gaps. Mid-cap specialty pharma in Germany and Switzerland outsource EU MDR transition support.
- Medical Device Manufacturers:Software-as-medical-device and AI-enabled diagnostics developers navigate FDA pre-certification and EU AI Act conformity assessment. Digital health guidance complexity drives regulatory consulting demand.
- Contract Research Organizations:Full-service CROs subcontract specialized medical affairs capabilities including medical writing and pharmacovigilance to niche providers, creating tiered outsourcing structures.
Biotechnology firms anchor volume demand, with medical device manufacturers expanding most quickly on digital health regulatory complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical affairs outsourcing originated in the United States during the 1990s as biotechnology firms sought external scientific expertise without building internal infrastructure. European expansion followed through Basel and Frankfurt clinical research clusters. Asian capability matured last, with Indian regulatory documentation centers achieving global scale by 2015.
United States
FDA breakthrough therapy designations and real-world evidence submission requirements compress sponsor timelines. The 21st Century Cures Act accelerates externalization of medical writing and regulatory correspondence. Boston and San Francisco biotechnology corridors host the densest concentration of Series C-funded cell therapy developers outsourcing publication planning.
Germany
EMA centralized procedure expertise and EU MDR technical documentation demands drive contract value. The Medical Device Regulation implementation deadlines force mid-cap manufacturers toward external regulatory support. Munich and Frankfurt clinical research hubs concentrate pharmacovigilance case processing for oncology and immunology portfolios.
India
CDSCO alignment with ICH E2B(R3) standards positions Mumbai and Bangalore as global regulatory document preparation centers. Cost arbitrage for high-volume case processing attracts United States and European sponsors. The country's data localization requirements under digital health frameworks fragment pharmacovigilance database architectures.
United Kingdom
Post-Brexit MHRA standalone procedures create parallel regulatory submission workloads. London and Cambridge biotechnology clusters externalize medical information call center operations and healthcare professional engagement. NHS real-world data access agreements generate observational study design demand.
Switzerland
Swissmedic consultation procedures and Basel pharmaceutical headquarters proximity sustain premium onshore delivery pricing. Geneva and Zurich medical science liaison networks serve rare disease and gene therapy developers. The country's bilateral EU agreements maintain regulatory pathway access for outsourced submission preparation.
Global Medical Affairs Outsourcing Market Competitive Landscape
Capital-heavy integrated data platform providers compete with asset-light specialized agencies for medical affairs outsourcing contracts. The market structure concentrates around three strategic tiers: full-service conglomerates with validated safety databases, therapeutic-area specialists with investigator networks, and virtual-first platforms with digital engagement capabilities. Consolidation accelerates through vertical capability acquisition, while geographic expansion targets CDSCO-aligned Indian delivery centers and EU MDR-ready German regulatory hubs.
Among integrated platform providers, IQVIA Holdings Inc. and ICON plc exemplify the data backbone archetype, anchoring multi-country medical affairs programs through validated infrastructure. Syneos Health Inc. occupies a distinct position within the virtual engagement tier, embedding cloud-based collaboration tools into standard pharmacovigilance and medical communications delivery. These three entities represent the dominant competitive vectors: scale-driven consolidation, therapeutic specialization, and digital-native service restructuring.
| Leading Market Players |
|---|
| IQVIA Holdings Inc. |
| ICON plc |
| Syneos Health Inc. |
| The Medical Affairs Company |
| Pharmaceutical Product Development LLC |
| Ashfield Healthcare Communications |
| Indegene Inc. |
| Parexel International Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
AI-enabled pharmacovigilance automation is compressing case processing timelines while redistributing talent premiums toward signal detection specialists and regulatory proximity hubs. This technological shift simultaneously elevates fixed platform investment requirements and concentrates pricing power among providers with validated FDA and EMA database infrastructure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates contract structures, with ISO 14155 certification tier and therapeutic domain expertise as primary differentiation drivers. Cost compression in economy-tier case processing is intensifying because Indian CDSCO-aligned providers are scaling document preparation capacity. Biotechnology sponsors in Boston and Basel exhibit the highest price sensitivity, while pharmaceutical companies prioritize regulatory access over unit economics.
Supply Chain Analysis
Workforce availability constraints in Mumbai, Boston, and Basel are elevating recruitment premiums for clinical research associates with combined therapeutic and regulatory documentation skills. Service delivery draws from India for high-volume case processing, Germany for EU MDR technical documentation, and the United States for FDA health authority interactions. Single-source vulnerability runs through Oracle and ARISg safety database platforms that fragment multi-sponsor workforce deployment. Distribution runs through hybrid account management models blending onshore regulatory access with offshore execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in medical affairs outsourcing rests on automation-driven cost compression in pharmacovigilance case processing and premium-tier pricing for EU AI Act compliance services. The shift toward unbundled contracts with discrete performance metrics creates additional margin capture opportunities for specialized providers.
For Market Incumbents: Extend validated safety database infrastructure into automated signal detection capabilities to defend against AI-native entrants. Acquire CDSCO-aligned Indian regulatory documentation centers to secure cost arbitrage without sacrificing ICH E2B(R3) compliance proximity. Prioritize EU AI Act conformity assessment capabilities as emerging biotechnology sponsors externalize risk management documentation. For New Entrants and Emerging Players: The price-point gap between premium onshore regulatory consulting and economy-tier offshore case processing creates white-space opportunity for mid-tier hybrid providers. Target Series C-funded cell therapy developers in San Francisco and gene editing ventures in Boston with virtual medical science liaison platforms bundled into pharmacovigilance contracts. Differentiate through therapeutic-area specialization in neurology gene therapy rather than competing on oncology scale. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light medical communications agencies lacking integrated data platforms but possessing digital channel proficiency. Long-term viability favors providers with validated FDA 21 CFR 312.32 infrastructure and EMA signal detection mandates across the analysis window. Watch FDA real-world evidence submission volume as the inflection indicator for observational study design capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Capability Buildout | Automated pharmacovigilance signal detection algorithms require conformity assessment documentation support under EMA guidance. |
| Hybrid Delivery Model Expansion | Blended Mumbai-Boston teams optimize cost-quality balance for United States biotechnology sponsors seeking ICH E2B(R3) readiness. |
| Therapeutic Area Specialist Acquisition | Oncology and neurology domain expertise commands premium pricing as cell therapy pipelines expand in Germany and United States. |
| Virtual MSL Platform Deployment | Cloud-based medical science liaison networks address access restrictions in Japan and rural United States markets simultaneously. |
| CDSCO-Aligned Regulatory Documentation Center | Indian ICH harmonization accelerates global regulatory document preparation capture from European and North American sponsors. |
Research Methodology
Bottom-up biotechnology sponsor modeling reconciled against top-down pharmacovigilance provider capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads, medical affairs executives, pharmacovigilance database administrators, and hospital formulary directors combined with secondary validation from FDA filings, EMA centralized procedure submissions, ClinicalTrials.gov records, and CDSCO regulatory alignment documentation. Triangulation between demand-side outsourcing depth surveys and supply-side validated safety database infrastructure assessments ensures segmentation integrity.
Historical trendline analysis of medical affairs outsourcing contract values and service mix evolution informed projection framework construction across the modeling period. Segmentation dimensions include service type, delivery model, therapy area, and client type, with CAGRs derived from sponsor pipeline analysis and regulatory mandate expansion trajectories. Forecast inputs incorporate EU MDR implementation timeline compression, FDA digital health guidance evolution, and decentralized trial infrastructure adoption rates.
Caveats apply where FDA real-world evidence submission acceptance thresholds, EMA pharmacovigilance mandate expansion, or EU AI Act enforcement intensity could materially shift the outlook. Forecasts reflect assumptions regarding ICH E2B(R3) harmonization pace and biotechnology capital availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Healthcare Provider Network Management Market
Healthcare Services
Medical Peer & External Physician Review Services Market
Healthcare Services
US Long Term Care Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
Pharmaceutical Contract Sales Organizations Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
US Post-Acute Care (PAC) Market
Healthcare Services
US Sterilization Services Market
Healthcare Services
US Registered Nurses Market
Healthcare Services
Global Umbilical Cord Blood Banking Market
Healthcare Services
US Retail Clinics Market
Healthcare Services
Michigan Urgent Care Center Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Healthcare Staffing Market